
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Horizontal Milling Machine Market Size 2024 | USD 68,314.5 million |
| Horizontal Milling Machine Market , CAGR | 6.1% |
| Horizontal Milling Machine Market Size 2032 | USD 109,707.41 million |
Market Overview:
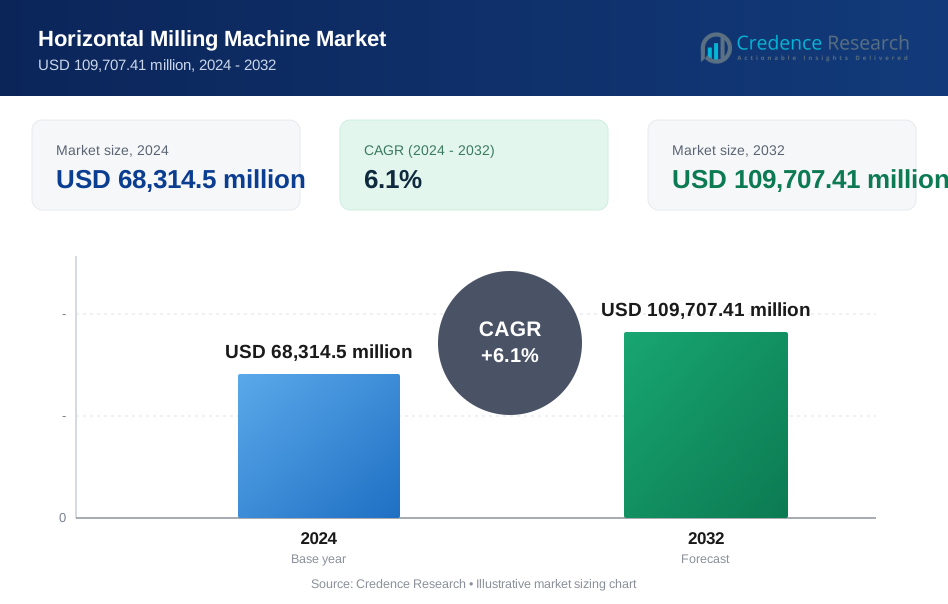
The Horizontal Milling Machine Market size was valued at USD 68,314.5 million in 2024 and is anticipated to reach USD 109,707.41 million by 2032, at a CAGR of 6.1% during the forecast period (2024-2032).
The Horizontal Milling Machine Market is driven by the rising demand for high-performance machining tools, increasing automation in manufacturing, and growing investments in industrial infrastructure. As industries seek to enhance productivity, precision, and efficiency, the adoption of computer-aided manufacturing (CAM) solutions is accelerating, improving metalworking, component fabrication, and machining accuracy. The automotive and aerospace industries are among the primary users of horizontal milling machines, as these systems enable precision machining of complex geometries, lightweight materials, and high-strength components. Furthermore, the integration of AI-driven predictive maintenance, real-time analytics, and automated tool-changing systems is revolutionizing the market, enabling manufacturers to optimize machine uptime, reduce operational costs, and extend equipment lifespan.
Regionally, Asia-Pacific leads the market, accounting for the largest share due to strong industrial growth, rapid urbanization, and increasing adoption of CNC machining technologies. China, Japan, and India are driving demand, investing heavily in advanced automation and precision machining technologies. Meanwhile, India’s “Make in India” initiative is promoting domestic industrial development, further boosting CNC milling machine adoption. North America and Europe remain key players, fueled by high investments in aerospace, defense, and smart manufacturing technologies. Germany continues to lead in precision engineering, integrating AI-driven and Industry 4.0 solutions into machining systems. Latin America and the Middle East & Africa are also experiencing steady growth, with Brazil’s industrial sector contributing over 20% to its GDP and Saudi Arabia’s Vision 2030 initiative accelerating investments in infrastructure and metalworking technologies.
Market Insights:
- The Horizontal Milling Machine Market is projected to grow from USD 68,314.5 million in 2024 to USD 109,707.41 million by 2032, driven by advancements in precision machining and automation.
- The adoption of computer-aided manufacturing (CAM) and CNC-controlled horizontal milling machines is increasing due to higher accuracy, efficiency, and automation in industrial applications.
- Industries such as automotive, aerospace, and defense are driving demand for high-precision, multi-axis milling solutions to produce complex and lightweight components.
- The market faces challenges due to high initial investment, maintenance costs, and skilled labor requirements for operating advanced milling systems.
- China, Japan, and India dominate the market, supported by strong manufacturing activity and increasing investments in industrial automation.
- The U.S. and Germany lead in high-precision, AI-powered milling technologies for aerospace, defense, and industrial applications.
- Brazil and Saudi Arabia are expanding investments in infrastructure, construction, and metal fabrication, driving demand for automated horizontal milling machines.
Market Drivers:
Rising Demand for Precision Machining:
The increasing demand for precision machining across various industries is a significant driver for the horizontal milling machine market. Industries such as automotive, aerospace, energy, and heavy equipment manufacturing require machining of large and complex parts with high precision. For instance, the automotive industry requires precise manufacturing for critical components such as engine parts, transmission components, and chassis assemblies. A report by the National Association of Manufacturers indicates that precision machining is crucial for producing high-quality automotive components, ensuring optimal performance and safety. Horizontal milling machines are pivotal in achieving the precise tolerances necessary for these components, thus driving their demand.
Growth in Manufacturing and Machining Industries:
The growth in manufacturing and machining industries globally is a key driver for the horizontal milling machine market. As the "Make in China" campaign continues to expand, the country is emerging as a high-potential market for horizontal milling machines. For instance, the Indian government's focus on promoting the manufacturing sector through initiatives like "Make in India" is creating a conducive environment for industries like metal, plastic, and automotive, thereby boosting demand for horizontal milling machines. The India Brand Equity Foundation (IBEF) reports that the "Make in India" initiative has significantly boosted manufacturing output, creating a favorable landscape for machine tool adoption.
Automation in Manufacturing:
The increasing adoption of automation in manufacturing industries is driving the demand for advanced milling machines, including horizontal milling machines. The push towards automation aims to enhance production efficiency and reduce operational costs. For instance, the integration of Computer Numerical Control (CNC) technology in horizontal milling machines enables improved precision, productivity, and versatility in machining operations. A study by Deloitte indicates that companies investing in automation technologies experience a 10-15% increase in productivity, highlighting the benefits of CNC integration in milling machines.
Versatility and Efficiency:
Horizontal milling machines offer versatility and efficiency in performing various machining operations. These machines can be used for drilling, chamfering, turning, and slot cutting, making them suitable for a wide range of applications. For instance, horizontal milling machines facilitate easier chip evacuation, allowing metal swarf to naturally fall away under gravity, which enhances machining efficiency and improves surface finishes. A report by the Advanced Manufacturing Research Centre (AMRC) highlights that efficient chip evacuation contributes to improved surface quality and reduced tool wear in machining operations, further driving the adoption of horizontal milling machines. Their ability to handle multiple cuts simultaneously and produce high-quality products further drives their adoption across diverse industries.
Market Trends:
Integration of AI and IoT for Smart Machining:
A significant trend in the horizontal milling machine market is the integration of Artificial Intelligence (AI) and the Internet of Things (IoT) to create smart machining solutions. AI-assisted programming tools can analyze machining data and suggest optimal cutting parameters, reducing the need for manual adjustments and increasing machining efficiency. For instance, smart sensors integrated into horizontal mills monitor factors such as tool wear, spindle vibration, and temperature, sending real-time alerts to operators. A report estimates that predictive maintenance enabled by IoT sensors can reduce maintenance costs by up to 40%. This enables predictive maintenance, reducing downtime and operational costs. This trend ensures that horizontal milling machines become smarter, more reliable, and more efficient, thereby reducing waste and enhancing productivity.
Automation and Robotics for Enhanced Productivity:
Automation and robotics are increasingly being adopted in conjunction with horizontal milling machines to enhance productivity. Automation systems that load and unload parts into horizontal mills are becoming more common, allowing for 24/7 production cycles without human intervention. For instance, collaborative robots (cobots) are being integrated into the machining process to handle repetitive tasks such as loading raw materials or unloading finished parts, minimizing human error and reducing labor costs. The Robotic Industries Association (RIA) reports that the use of robots in manufacturing has increased by over 10% annually in recent years, driven by the need for greater efficiency and reduced labor costs. Automation not only improves cycle times but also reduces human error, leading to better cash flow and the ability to reinvest in the business. The future of horizontal milling will undoubtedly be shaped by increased automation, enabling manufacturers to take full advantage of the machines' capabilities while reducing labor costs and improving overall productivity.
Focus on Advanced Materials and Coatings:
The development of advanced materials and coatings for cutting tools and workpieces is another notable trend in horizontal milling technology. High-performance coatings, such as diamond-like carbon (DLC) and titanium nitride (TiN), enhance wear resistance, increase cutting speeds, and improve surface finishes. For instance, these advancements allow horizontal milling machines to achieve better performance even when working with hard-to-machine materials. A study by the American Society for Metals (ASM) indicates that advanced coatings can increase tool life by up to 300%, reducing tooling costs and improving machining efficiency. The use of modern materials and new engineering technologies contributes to the development of strong and reliable horizontal machines capable of delivering exceptional results.
Customization and Versatility through Modular Designs:
There is a growing trend toward modular and versatile horizontal milling machines that can be customized to meet specific application requirements. These machines are designed to perform multiple operations, such as milling, turning, and drilling, within a single setup. For instance, horizontal machining centers are offering various models and configurations, such as fixed table, rotary table, and multitasking options, to adapt to different work environments. A report by the National Center for Manufacturing Sciences (NCMS) emphasizes the importance of modular designs in enabling manufacturers to quickly adapt to changing production requirements. This modular design approach offers high reliability, easier service, and flexibility in devising solutions for customers, making horizontal milling machines suitable for a wide array of industries and applications.
Market Challenges Analysis:
High Initial Investment Costs:
One of the most significant restraints on the horizontal milling machine market is the high initial investment required to purchase these machines. The advanced technology and precision engineering involved in manufacturing horizontal milling machines lead to substantial upfront costs. For instance, small and medium-sized enterprises (SMEs) may find it challenging to allocate the necessary capital for acquiring these machines, particularly when compared to lower-cost alternatives. According to a report by the India Ministry of Micro, Small & Medium Enterprises, financial constraints are a primary obstacle for SMEs in adopting advanced manufacturing technologies. A report by the Congressional Research Service notes that access to capital is a persistent challenge for SMEs, hindering their ability to invest in modern equipment. Collaboration, technological advancements, and government support are needed to reduce production costs and make horizontal milling machine more accessible.
Skilled Labor Shortage:
Operating and maintaining horizontal milling machines, especially CNC models, requires skilled labor, which is in short supply in many regions. For instance, CNC machines require trained programmers and operators who understand complex machining processes and can troubleshoot technical issues. A survey found that the skills gap in manufacturing could leave millions of positions unfilled, impacting production efficiency and growth. The National Association of Manufacturers (NAM) emphasizes that addressing the skills gap is critical for U.S. manufacturing competitiveness. Addressing this challenge requires investments in training programs and workforce development initiatives to ensure an adequate supply of skilled personnel.
Complexity of Operations and Maintenance:
Horizontal milling machines, particularly those with advanced CNC capabilities, can be complex to operate and maintain, leading to increased operational costs. For instance, maintaining the precision and accuracy of these machines requires regular calibration and component replacements, adding to the total cost of ownership. A study by the American Society of Mechanical Engineers (ASME) highlights that proper maintenance and calibration are crucial for ensuring the long-term performance and reliability of milling machines. The U.S. Department of Energy emphasizes that proper maintenance of industrial equipment can improve energy efficiency and reduce operational costs. Moreover, the complexity of these machines means that specialized technical expertise is required for repairs and maintenance, increasing service charges.
Market Opportunities:
The Horizontal Milling Machine Market presents significant growth opportunities, driven by technological advancements, increased automation in manufacturing, and the rising demand for precision machining across industries. The integration of computer numerical control (CNC) technology, AI-driven predictive maintenance, and Industry 4.0 innovations is enhancing the efficiency and versatility of horizontal milling machines, allowing manufacturers to improve production accuracy and operational flexibility. With the global automotive industry exceeding USD 3 trillion, the demand for high-precision milling solutions for engine components, transmission systems, and lightweight structural parts is increasing. Similarly, the aerospace sector, which produced over 1,500 commercial aircraft in 2023, is investing in multi-axis CNC horizontal milling machines to manufacture high-strength, lightweight components such as turbine blades, aircraft fuselage parts, and landing gear assemblies.
Expanding industrialization and infrastructure projects in emerging economies also provide strong growth prospects. Asia-Pacific, led by China, India, and Japan, dominates market expansion, supported by rapid manufacturing growth and increasing investments in automated machining technologies. Additionally, North America and Europe are driving innovation, with Germany and the U.S. focusing on smart manufacturing and precision engineering. The construction, defense, and heavy machinery sectors in Latin America and the Middle East & Africa are also fueling demand for cost-effective, durable, and high-efficiency horizontal milling machines. As industries continue to invest in automation, energy-efficient machinery, and high-performance metal fabrication solutions, the market for horizontal milling machines is expected to witness robust expansion and technological evolution in the coming years.
Market Segmentation Analysis:
By Product:
The Horizontal Milling Machine Market is segmented into plain horizontal milling machines, universal horizontal milling machines, and CNC horizontal milling machines. CNC horizontal milling machines dominate the market, driven by increasing automation, precision engineering, and demand for high-speed machining. These machines offer superior accuracy, real-time monitoring, and integration with Industry 4.0 solutions, making them highly preferred in aerospace, automotive, and heavy machinery sectors. Universal horizontal milling machines, which provide greater flexibility for custom machining tasks, are widely adopted in job shops and metal fabrication industries. Plain horizontal milling machines, though less technologically advanced, remain essential in small-scale manufacturing and maintenance operations due to their cost-effectiveness and ease of use.
By Application:
The market is segmented by application into automotive, aerospace, construction, heavy machinery, and general manufacturing. The automotive industry holds the largest market share, as manufacturers increasingly use horizontal milling machines for engine blocks, transmission components, and chassis fabrication. The aerospace sector is rapidly expanding its adoption of multi-axis CNC milling machines for turbine blades, fuselage components, and lightweight aircraft parts. Additionally, the construction and heavy machinery industries rely on horizontal milling machines for machining large metal parts used in cranes, excavators, and industrial equipment.
By Distribution Channel:
Horizontal milling machines are distributed through direct sales, online sales, and third-party distributors. Direct sales channels dominate the market, with manufacturers partnering directly with OEMs and industrial clients to provide customized solutions and after-sales services. Online sales are gaining traction, as companies increasingly invest in digital platforms and e-commerce for industrial machinery procurement. Third-party distributors remain essential for regional sales expansion and servicing in emerging markets, particularly in Latin America and the Middle East & Africa.
Segmentations:
By Product:
- Compact Precision
- Standard
- Grinding
- Free-Mounted
- Other
By Application:
- Commercial
- Industrial
- Plastic Industry
- Wood Industry
- Metal Industry
By Number of Axis:
- 1 Axis
- 2axis
- 3 Axis
- 5 Axis
- 6axis
- 7axis
- Other
By Distribution Channel:
- Online
- Offline
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia-Pacific:
Asia-Pacific holds the largest market share of 42%, driven by rapid industrialization, increasing adoption of CNC machining, and strong growth in the automotive and aerospace industries. China, Japan, and India are major contributors, with China’s manufacturing sector valued at over USD 4 trillion, leading in smart factory automation and high-precision machining investments. For instance, China’s automotive industry, producing over 27 million vehicles annually, heavily relies on advanced horizontal milling machines for engine components, chassis, and transmission parts. Additionally, India’s "Make in India" initiative is fueling investments in domestic manufacturing and CNC machinery, with the metalworking and fabrication sector expected to surpass USD 70 billion by 2025. The rise of aerospace manufacturing in Japan, with companies like Mitsubishi Heavy Industries and Kawasaki Heavy Industries, is also increasing demand for multi-axis horizontal milling machines for turbine blades and aircraft fuselage components.
North America:
North America accounts for 25% of the global market, driven by technological advancements in smart manufacturing, strong aerospace and defense investments, and increasing automation in metal fabrication. The United States, home to major aerospace and defense manufacturers like Boeing and Lockheed Martin, is leading in AI-driven milling technologies and real-time machine monitoring systems. For instance, the U.S. Department of Defense allocated over USD 800 billion in 2023, with a portion directed toward precision machining solutions for military vehicles, aircraft, and defense components. Meanwhile, Canada and Mexico are expanding their automotive and industrial machinery sectors, increasing demand for automated, energy-efficient horizontal milling machines. The rise of EV manufacturing in North America, particularly with Tesla, General Motors, and Ford investing in lightweight vehicle components, is further driving the market for CNC-controlled horizontal milling solutions.
Europe:
Europe holds 22% of the market, led by Germany, France, and the UK, which are global leaders in precision engineering, high-performance machining, and Industry 4.0 adoption. Germany, home to leading manufacturers such as DMG Mori and Heller, is advancing sustainable manufacturing by integrating energy-efficient and AI-powered horizontal milling systems. For instance, the EU’s Green Manufacturing Initiative, aimed at reducing industrial carbon emissions by 55% by 2030, is pushing manufacturers to adopt lightweight, high-precision CNC machines. Meanwhile, France’s aerospace sector, with Airbus producing over 600 aircraft annually, heavily invests in high-speed, multi-axis horizontal milling solutions for complex aircraft parts. The UK’s automotive industry, with Jaguar Land Rover and Rolls-Royce investing in precision machining, is also fueling demand for advanced milling machines with automated tool-changing systems.
Latin America and the Middle East & Africa:
Latin America and the Middle East & Africa (MEA) collectively account for 11% of the market, experiencing gradual yet steady growth in infrastructure development, industrial machinery investments, and construction sector expansion. For instance, Brazil, producing over 2.3 million vehicles annually, is driving demand for cost-effective and durable horizontal milling machines in metal fabrication and automotive component manufacturing. Mexico’s growing industrial sector, fueled by foreign direct investments in machinery and aerospace industries, is also increasing the adoption of precision CNC milling solutions.
In the Middle East, particularly in Saudi Arabia and the UAE, industrial diversification efforts are expanding the market. For instance, Saudi Arabia’s Vision 2030 initiative aims to develop a strong domestic manufacturing base, boosting investments in high-performance machining for construction, defense, and industrial equipment. Additionally, South Africa’s metal fabrication industry, contributing over USD 10 billion annually, is increasing its reliance on automated horizontal milling machines to enhance production efficiency and meet international quality standards. As regional investments in industrial automation and precision engineering continue to grow, Latin America and MEA are expected to play a more significant role in the global horizontal milling machine market expansion.
Key Player Analysis:
- DATRON Dynamics, Inc.
- Haas Automation, Inc.
- YAMAZAKI MAZAK CORPORATION
- Amera-Seiki
- FANUC CORPORATION
- ANDERSON EUROPE GMBH
- Hurco Companies, Inc.
- Okuma Corporation
- KNUTH Werkzeugmaschinen GmbH
- EMCO group
Competitive Analysis:
The Horizontal Milling Machine Market is highly competitive, with key players focusing on technological advancements, automation, and precision engineering to strengthen their market position. Leading companies such as DMG Mori, Makino, Haas Automation, Okuma Corporation, and Yamazaki Mazak dominate the industry, leveraging AI-powered CNC systems, high-speed machining, and Industry 4.0 integration. For instance, DMG Mori controls a significant share of the global CNC milling machine market, continuously investing in digitized machining solutions and automated tool-changing systems. Meanwhile, Makino’s advanced horizontal milling machines are widely used in aerospace and automotive applications, providing multi-axis capabilities for high-precision component manufacturing. The increasing adoption of smart factories and AI-driven predictive maintenance solutions is intensifying competition, prompting manufacturers to develop cost-effective, energy-efficient, and high-performance milling systems. As demand for precision machining rises across industries, leading players continue to invest in innovation, R&D, and strategic collaborations to maintain a competitive edge.
Recent Developments:
- In August 2024 DATRON showcased its mechanical engineering advancements live at AMB in Stuttgart, presenting highlights from its machine, tool, and service solutions. DATRON CNC milling machines feature German engineering with precision, ease-of-use, and speed in mind.
- In February 2025 Haas Automation will showcase its latest advancements in CNC technology at IMTEX 2025, emphasizing automation and precision machining solutions. Haas machines provide full CNC capabilities, including available 4th- and 5th-axis functionality, at affordable prices.
- In December 2024 Yamazaki Mazak announced that it is manufacturing mineral castings in-house to expand the range of adopted machines. In March 2023, Yamazaki Mazak started operations at its new factory in Pune, India, producing vertical machining centers tailored to local needs.
- In December 2024 Okuma developed the MS-320H compact horizontal machining center (HMC) featuring a new design with a vertical A-axis table to minimize chip-related problems and enable extended unmanned operation. In September 2024, Okuma launched the MA-4000H horizontal machining center featuring a large machining area and the OSP-P500 CNC control
Market Concentration & Characteristics:
The Horizontal Milling Machine Market is moderately concentrated, with a mix of established global players and regional manufacturers competing based on technological innovation, automation, and cost-efficiency. Leading companies such as DMG Mori, Makino, Haas Automation, Okuma Corporation, and Yamazaki Mazak dominate the market, leveraging advanced CNC technologies, AI-driven machining, and Industry 4.0 integration to enhance precision and productivity. The industry is characterized by high entry barriers, including significant capital investment, complex technology integration, and the need for skilled labor. Additionally, the rise of smart manufacturing and predictive maintenance solutions is shaping market trends, pushing manufacturers to develop energy-efficient, multi-axis horizontal milling machines. While North America and Europe lead in high-performance and AI-powered milling solutions, Asia-Pacific holds the largest market share due to rapid industrialization and strong demand from the automotive and aerospace sectors. The market’s future growth will be driven by automation, digitalization, and the expansion of precision machining capabilities.
Report Coverage:
The research report offers an in-depth analysis based on Product, Application, Distribution Channel, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing demand for precision machining will drive the adoption of high-speed, multi-axis horizontal milling machines across industries such as automotive, aerospace, and defense.
- Advancements in CNC technology and automation will enhance accuracy, productivity, and operational efficiency, reducing human intervention in manufacturing processes.
- Integration of AI and predictive maintenance solutions will enable manufacturers to optimize machine uptime, reduce downtime, and improve overall equipment efficiency (OEE).
- Growing adoption of Industry 4.0 and smart factories will push manufacturers to implement real-time monitoring, automated tool-changing systems, and digital twin technology in milling operations.
- Expansion of the electric vehicle (EV) market will increase demand for lightweight, high-precision components, boosting the need for advanced horizontal milling machines.
- Asia-Pacific will continue leading market growth, with China, Japan, and India investing in industrial automation and CNC machining innovations.
- North America and Europe will drive high-end innovation, focusing on AI-driven, energy-efficient, and sustainable milling solutions for aerospace, defense, and high-precision engineering.
- Sustainability and energy efficiency concerns will encourage manufacturers to develop eco-friendly, low-energy consumption milling machines with improved performance.
- Mergers, acquisitions, and collaborations among key players will accelerate technological advancements, geographic expansion, and product diversification.
- Emerging markets in Latin America and the Middle East & Africa will witness increasing investment in infrastructure, construction, and industrial machinery, boosting demand for cost-effective horizontal milling machines.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Automation in Manufacturing
The increasing integration of automation and CNC technology in manufacturing is driving demand for horizontal milling machines, as these solutions enhance productivity, reduce operational costs, and enable 24/7 production cycles with minimal human intervention.
Precision Machining Requirements
Industries such as automotive, aerospace, and defense require high-precision machining for complex and lightweight components, making horizontal milling machines essential for achieving tight tolerances and superior surface finishes.
Industrialization and Infrastructure Growth in Asia-Pacific
Rapid industrialization, urbanization, and government initiatives like 'Make in India' and China's manufacturing expansion are fueling investments in advanced machining technologies, significantly boosting the adoption of horizontal milling machines in the region.
Adoption of AI and Predictive Maintenance
The integration of AI-driven predictive maintenance and real-time analytics in horizontal milling machines is enabling manufacturers to optimize machine uptime, reduce unplanned downtime, and extend equipment lifespan, making these machines more attractive for high-volume production environments.
Versatility and Modular Design
The trend toward modular, multi-functional horizontal milling machines allows manufacturers to perform various operations - such as milling, drilling, and turning - in a single setup, increasing operational flexibility and reducing changeover times across diverse industrial applications.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Horizontal Milling Machine Market?
What factors are driving the growth of the Horizontal Milling Machine Market?
What are some challenges faced by the Horizontal Milling Machine Market?
Who are the major players in the Horizontal Milling Machine Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Compact Precision
- 1.2.2 Standard
- 1.2.3 Grinding
- 1.2.4 Free-Mounted
- 1.2.5 Other
- 1.3 By Application
- 1.3.1 Commercial
- 1.3.2 Industrial
- 1.3.3 Plastic Industry
- 1.3.4 Wood Industry
- 1.3.5 Metal Industry
- 1.4 By Number of Axis
- 1.4.1 1 Axis
- 1.4.2 2 Axis
- 1.4.3 3 Axis
- 1.4.4 5 Axis
- 1.4.5 6 Axis
- 1.4.6 7 Axis
- 1.4.7 Other
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 68,314.5 million → 2032: USD 109,707.41 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Horizontal Milling Machine Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Horizontal Milling Machine Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Horizontal Milling Machine Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Horizontal Milling Machine Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Horizontal Milling Machine Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Horizontal Milling Machine Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Horizontal Milling Machine Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Horizontal Milling Machine Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 68,314.5 million → 2032: USD 109,707.41 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Horizontal Milling Machine Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Compact Precision
- 12.3.7.2 Standard
- 12.3.7.3 Grinding
- 12.3.7.4 Free-Mounted
- 12.3.7.5 Other
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Commercial
- 12.4.7.2 Industrial
- 12.4.7.3 Plastic Industry
- 12.4.7.4 Wood Industry
- 12.4.7.5 Metal Industry
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Number of Axis - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 1 Axis
- 12.5.7.2 2 Axis
- 12.5.7.3 3 Axis
- 12.5.7.4 5 Axis
- 12.5.7.5 6 Axis
- 12.5.7.6 7 Axis
- 12.5.7.7 Other
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Horizontal Milling Machine End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Horizontal Milling Machine Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Horizontal Milling Machine Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Horizontal Milling Machine Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 DATRON Dynamics, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Haas Automation, Inc.
- 18.4 YAMAZAKI MAZAK CORPORATION
- 18.5 Amera-Seiki
- 18.6 FANUC CORPORATION
- 18.7 ANDERSON EUROPE GMBH
- 18.8 Hurco Companies, Inc.
- 18.9 Okuma Corporation
- 18.10 KNUTH Werkzeugmaschinen GmbH
- 18.11 EMCO group
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

