
Market Overview:
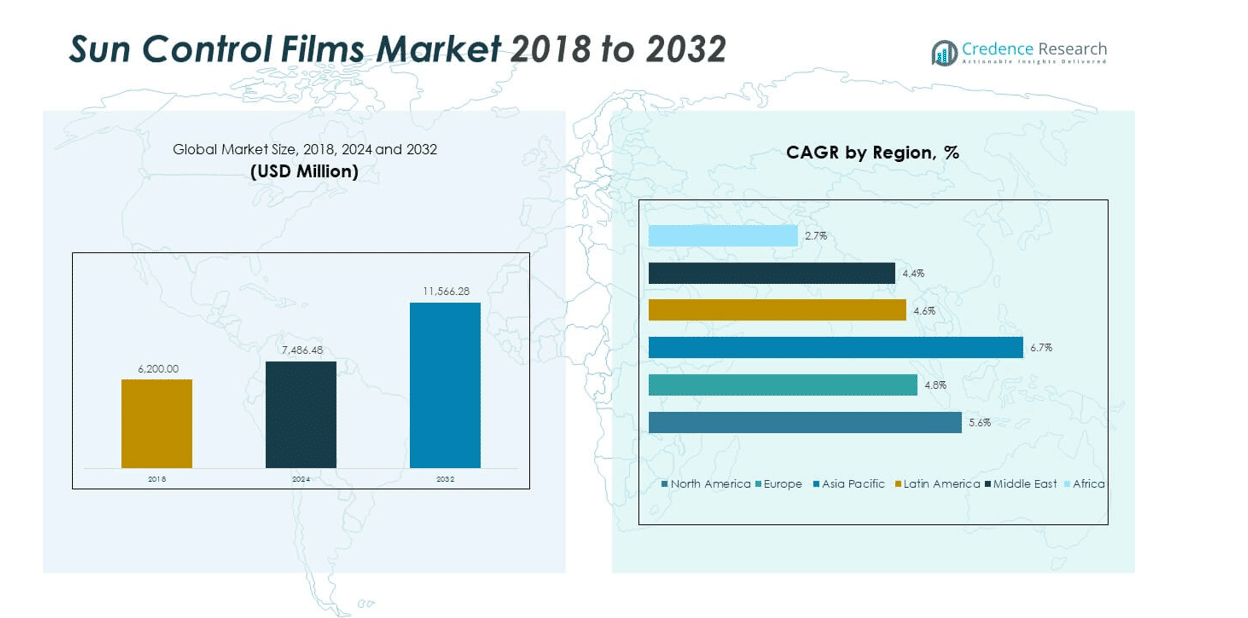
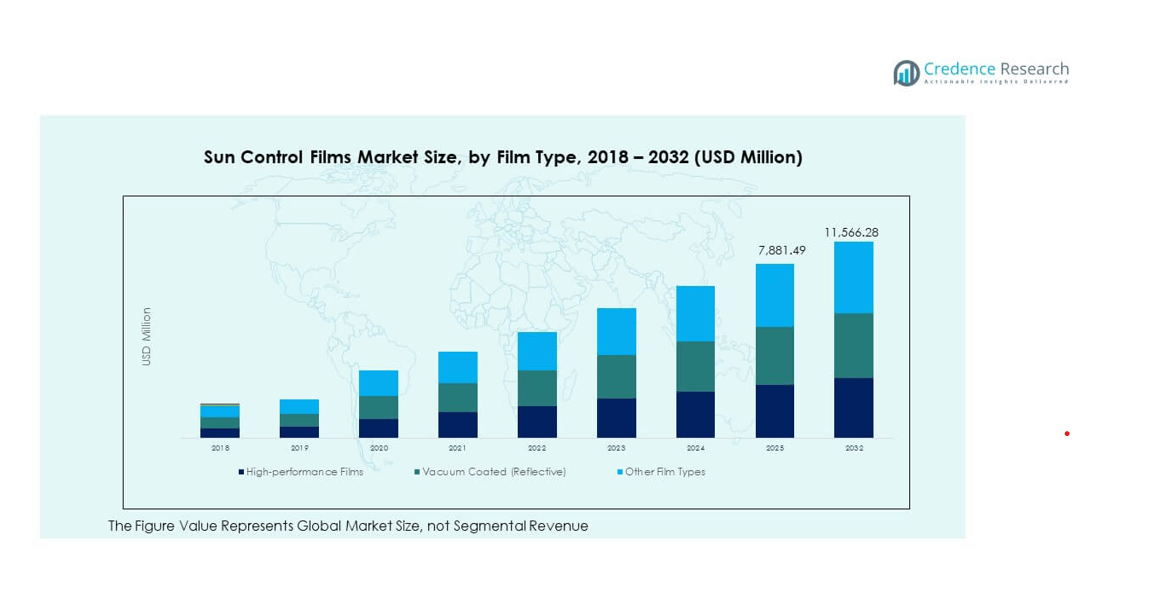
The Global Sun Control Films Market size was valued at USD 6,200.00 million in 2018 to USD 7,486.48 million in 2024 and is anticipated to reach USD 11,566.28 million by 2032, at a CAGR of 5.63% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Sun Control Films Market Size 2024 | USD 7,486.48 million |
| Sun Control Films Market, CAGR | 5.63% |
| Sun Control Films Market Size 2032 | USD 11,566.28 million |
The Global Sun Control Films Market is growing due to rising demand for energy-efficient and sustainable window solutions across commercial and residential buildings. Increasing awareness about UV protection and temperature regulation drives product adoption. Growth in the automotive sector, where sun control films improve cabin comfort and reduce air conditioning use, also supports expansion. Manufacturers are focusing on advanced materials that enhance durability and optical clarity. The growing trend toward green buildings further promotes market adoption across developing economies.
North America and Europe lead the market due to high adoption in construction and automotive sectors, supported by strict energy-saving regulations. Asia Pacific is emerging rapidly, driven by urbanization, rising vehicle ownership, and increased construction of smart buildings. The Middle East shows strong potential owing to high temperatures and demand for solar protection solutions. Latin America and Africa are developing markets where growing environmental awareness and infrastructure modernization are opening new opportunities for sun control film applications.
Market Insights:
- The Global Sun Control Films Market was valued at USD 6,200.00 million in 2018, reached USD 7,486.48 million in 2024, and is projected to attain USD 11,566.28 million by 2032, registering a CAGR of 5.63% during the forecast period.
- North America leads with a 34% market share, followed by Europe at 22% and Asia Pacific at 29%, driven by strong automotive production, construction innovation, and adoption of energy-efficient building solutions.
- Asia Pacific is the fastest-growing region, expanding rapidly due to large-scale infrastructure projects, rising urbanization, and increasing demand for heat-reducing films in residential and commercial buildings.
- High-Performance Films hold about 45% of the market share owing to their superior heat rejection, UV protection, and durability across automotive and architectural applications.
- Vacuum Coated (Reflective) Films account for around 30% of the market, supported by their efficiency in glare control and growing preference in commercial and industrial installations.
Market Drivers:
Growing Demand for Energy-Efficient Building Materials and Thermal Regulation Solutions
The Global Sun Control Films Market is driven by the increasing focus on energy-efficient buildings that reduce heat gain and cooling costs. Sun control films lower energy consumption by minimizing solar radiation penetration in residential and commercial structures. Governments are introducing green building regulations, motivating adoption in both new and retrofit projects. Rising electricity prices are pushing consumers to seek cost-effective energy management options. These films also reduce greenhouse gas emissions by limiting air conditioning usage. Construction of smart and sustainable infrastructure strengthens the demand base. Manufacturers are investing in films that combine heat rejection with high optical clarity. The shift toward sustainable materials continues to support long-term market expansion.
- For instance, CRYLINK attended SPIE Photonics West 2025, an event that highlighted advancements in high-energy laser imaging technologies, and showcased its LBO and Nd:YLF crystals.
Expanding Use in Automotive Applications to Enhance Comfort and Safety
The automotive sector significantly drives the Global Sun Control Films Market through the adoption of heat-resistant and UV-blocking films. It helps improve passenger comfort by regulating cabin temperature and reducing glare. Vehicle manufacturers are incorporating advanced sun control films to enhance fuel efficiency by reducing air conditioning load. Increased consumer awareness of skin protection from harmful UV rays strengthens demand. Automotive tinting also enhances privacy and aesthetics, promoting premium segment growth. Stringent safety and environmental standards have encouraged the use of certified, eco-friendly materials. Rapid expansion of electric vehicles has created demand for lightweight films that enhance battery performance. Rising vehicle production in emerging economies fuels overall consumption of automotive-grade sun control films.
- For instance, Avery Dennison’s NR Nano Ceramic IR Series delivers up to 87% infrared heat rejection (SIRR), over 99% UV blocking, and 93% glare reduction across several VLT levels, according to its official 2025 product data sheet verified on averydennison.com.
Rising Awareness Toward UV Protection and Health Benefits
Growing public awareness about UV-related health risks is influencing the Global Sun Control Films Market. The films prevent interior fading, skin damage, and glare, ensuring improved indoor and driving comfort. Businesses are adopting these solutions to protect furnishings and reduce maintenance costs. Residential consumers are also focusing on protecting home interiors from sun damage. Increasing adoption of smart glass technology has highlighted the importance of UV filtration efficiency. Manufacturers are introducing products with enhanced optical clarity to maintain visibility while ensuring high protection. Retail and commercial buildings are integrating these films to improve occupant well-being. The trend toward health-conscious, energy-saving living environments continues to support demand growth.
Technological Advancements in Film Coatings and Manufacturing Processes
The Global Sun Control Films Market benefits from ongoing innovations in film coating technology and material composition. Development of nano-ceramic and multi-layered coatings has improved thermal insulation and visibility. Automation in manufacturing processes ensures consistent film quality and higher production efficiency. Advanced adhesives and anti-scratch coatings increase product durability and performance. Companies are investing in R&D to create eco-friendly, recyclable films with enhanced energy-saving properties. The introduction of smart, switchable, and self-tinting films has diversified applications across sectors. Increased collaboration between material suppliers and manufacturers promotes continuous improvement. Technology integration and product innovation remain critical in maintaining market competitiveness.
Market Trends:
Integration of Smart and Adaptive Window Film Technologies
A major trend shaping the Global Sun Control Films Market is the integration of smart and adaptive film technologies. These films automatically adjust light transmission based on sunlight intensity, enhancing comfort and energy savings. Smart tinting solutions are becoming popular in luxury vehicles and commercial spaces. Growing demand for IoT-enabled and electronically controlled films supports market transformation. Manufacturers are focusing on user-friendly and customizable solutions. Integration with building management systems ensures better indoor climate control. This advancement aligns with global trends toward automation and energy optimization. The growing preference for intelligent window solutions accelerates innovation in this segment.
- For instance, Saint-Gobain’s electrochromic glazing systems can adjust visible light transmission from 60% to below 2% within minutes, reducing peak cooling loads by up to 20% in commercial structures, as verified in the company’s official sustainable technology reports.
Shift Toward Sustainable and Eco-Friendly Raw Materials
The Global Sun Control Films Market is moving toward sustainability through the use of eco-friendly materials and recyclable polymers. Manufacturers are phasing out toxic adhesives and coatings to comply with environmental standards. Demand for PVC-free and biodegradable alternatives is gaining attention among eco-conscious consumers. Governments and certification bodies are promoting sustainable manufacturing practices. Companies are investing in cleaner production lines to minimize carbon footprints. The shift toward sustainability is improving brand reputation and consumer trust. The use of green materials also supports long-term product durability and efficiency. Environmental compliance has become a competitive advantage in global market operations.
- For instance, Lintec Corporation’s BR-50UH RECYCLE 100 solar control film, made entirely from 100% recycled PET resin, blocks more than 99% of UV rays and reduces CO₂ emissions by approximately 17.5%, according to the company’s official release on lintec-global.comdated July 2025.
Rising Popularity of Decorative and Aesthetic Film Applications
The growing demand for aesthetic appeal in interiors is driving the decorative film trend within the Global Sun Control Films Market. Consumers are favoring tinted and patterned films that combine privacy with style. Architects and designers are using these films to create modern, functional spaces. The ability to achieve elegant looks without major structural changes appeals to both residential and commercial users. Office buildings are adopting frosted and printed films to enhance visual appeal and natural lighting balance. Manufacturers are expanding product portfolios with design-oriented collections. This trend has also influenced hospitality and retail sectors aiming to improve ambience. The combination of aesthetics and functionality continues to attract new customers.
Expansion of Distribution Networks and E-Commerce Platforms
The Global Sun Control Films Market is witnessing rapid expansion in distribution channels and online sales. E-commerce platforms are offering easy access to professional-grade films for retail customers. Manufacturers are building direct-to-consumer strategies to improve brand presence. Partnerships with distributors and installers enhance market reach in developing regions. The shift toward online customization and quick installation services attracts home and auto users. Improved supply chain efficiency supports consistent product availability. Competitive pricing and easy comparison tools encourage digital purchases. The integration of online platforms strengthens global accessibility and customer engagement.
Market Challenges Analysis:
High Installation Costs and Limited Consumer Awareness in Developing Regions
The Global Sun Control Films Market faces challenges related to high installation costs and limited awareness in emerging markets. Many consumers perceive these films as luxury products rather than energy-saving essentials. Lack of technical expertise among installers often leads to improper application and product inefficiency. Limited retail infrastructure in rural areas restricts availability. Price-sensitive buyers in developing nations hesitate to invest without visible short-term benefits. The need for specialized tools and certified professionals increases installation expenses. Educational campaigns about long-term savings are insufficient in many regions. Manufacturers are working to simplify application processes and improve outreach, but adoption gaps remain significant.
Stringent Regulations and Quality Standard Variations Across Markets
The Global Sun Control Films Market faces regulatory challenges related to safety and material compliance. Variations in regional tinting laws, especially for automotive films, create confusion for manufacturers and distributors. Strict transparency and reflectivity limits in some countries restrict product versatility. Different climate conditions also demand region-specific performance testing. Meeting diverse international quality certifications increases production costs. Counterfeit or low-grade products in unregulated markets affect brand credibility. Companies must balance innovation with compliance to maintain trust and profitability. The need for standardized regulations across major regions remains an industry priority.
Market Opportunities:
Rising Construction of Green Buildings and Smart Infrastructure
The Global Sun Control Films Market presents strong opportunities in green construction and sustainable infrastructure. Energy-efficient building initiatives are driving large-scale film adoption in commercial and residential sectors. Architects are specifying high-performance films to meet certification standards. Governments are encouraging eco-friendly construction through incentives and building codes. The increasing integration of advanced window technologies strengthens long-term adoption. Real estate developers are incorporating sun control films into smart city projects to enhance comfort and energy savings. This opportunity aligns with global sustainability goals and growing awareness of indoor energy optimization.
Expanding Penetration Across Emerging Markets and Automotive Sector
The Global Sun Control Films Market is expanding across developing economies driven by rising disposable incomes and urbanization. The growing automotive industry in Asia Pacific, Latin America, and the Middle East provides strong demand potential. Increasing consumer interest in vehicle aesthetics and heat protection drives product usage. Partnerships between film producers and automakers create opportunities for integrated solutions. Rapid industrialization and retail growth enhance product accessibility. Awareness campaigns promoting energy efficiency and UV safety are expected to accelerate adoption. Emerging markets hold significant potential for volume growth and product diversification.
Market Segmentation Analysis:
By Film Type
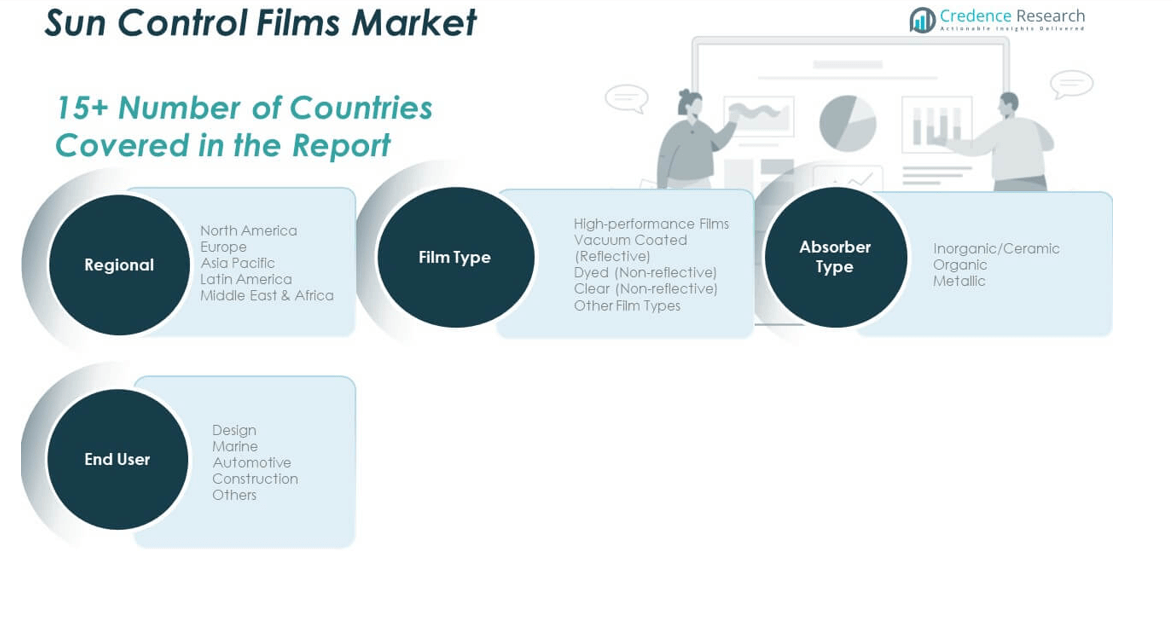
The Global Sun Control Films Market is segmented into high-performance, vacuum coated (reflective), dyed (non-reflective), clear (non-reflective), and other film types. High-performance films dominate due to their superior heat rejection, UV protection, and energy-saving benefits. Vacuum coated reflective films are preferred in commercial buildings and automotive applications for their excellent glare control. Dyed non-reflective films remain popular in residential use for their low cost and aesthetic appeal. Clear non-reflective films are gaining traction in spaces where visibility and natural light are essential. Continuous advancements in coating technologies are improving durability and optical clarity across all types.
- For instance, Avery Dennison’s high-performance reflective film formulations provide solar energy rejection levels up to 70% while maintaining visible light transmittance near 40%, balancing efficiency and clarity as stated in its 2025 technical brochures.
By Absorber Type
The market by absorber type includes inorganic/ceramic, organic, and metallic films. Inorganic or ceramic absorbers lead due to high thermal resistance and long lifespan. These films effectively reduce solar heat gain while maintaining optical transparency. Organic absorbers are expanding in usage because of their flexibility and lower production costs. Metallic films are widely used for reflective applications, offering enhanced light rejection in automotive and commercial sectors. Innovations in nanoceramic materials are strengthening performance consistency.
- For instance, Avery Dennison’s nanoceramic absorbers used in the NR Nano Ceramic IR Series achieve up to 99.9% UV block and 87% infrared rejection without interfering with electronics, demonstrating superior energy control verified from the company’s product documentation.
By End-User
The market by end-user covers design, marine, automotive, construction, and others. Automotive applications hold a significant share due to high demand for comfort, glare reduction, and UV protection. The construction sector follows, driven by smart city initiatives and energy-efficient building regulations. Marine and design applications utilize films for visibility, aesthetics, and surface protection. Increasing awareness of sustainable materials supports broader use across industries. The market continues to evolve with growing emphasis on eco-friendly and performance-optimized film solutions.
Segmentation:
By Film Type
- High-Performance Films
- Vacuum Coated (Reflective)
- Dyed (Non-Reflective)
- Clear (Non-Reflective)
- Other Film Types
By Absorber Type
- Inorganic/Ceramic
- Organic
- Metallic
By End-User
- Design
- Marine
- Automotive
- Construction
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Sun Control Films Market size was valued at USD 2,139.00 million in 2018 to USD 2,549.85 million in 2024 and is anticipated to reach USD 3,933.71 million by 2032, at a CAGR of 5.6% during the forecast period. North America accounts for around 34% of the total Global Sun Control Films Market share. High demand from the construction and automotive sectors drives market growth in the region. It benefits from stringent energy efficiency standards and growing preference for green building certifications. The U.S. dominates the regional market due to high adoption in commercial spaces and residential retrofitting. Canada and Mexico are expanding rapidly with increased automotive production and architectural projects. Rising awareness of UV protection and sustainability continues to strengthen product use. Technological innovation and the presence of key manufacturers ensure a steady supply chain. Continuous investments in smart window technologies support regional market advancement.
Europe
The Europe Sun Control Films Market size was valued at USD 1,537.60 million in 2018 to USD 1,780.08 million in 2024 and is anticipated to reach USD 2,587.99 million by 2032, at a CAGR of 4.8% during the forecast period. Europe contributes about 22% to the Global Sun Control Films Market share. The region’s growth is supported by environmental regulations and the adoption of sustainable building practices. Germany, France, and the UK lead in commercial installations with advanced glass coating technologies. Automotive manufacturers are increasingly integrating high-performance window films to improve energy efficiency. Government incentives promoting energy conservation further boost adoption across construction and transportation. The region’s strong research infrastructure encourages product innovation and material efficiency. Rising demand for tinted films in architectural projects also supports revenue growth. Expansion in retrofitting and industrial applications enhances Europe’s long-term potential.
Asia Pacific
The Asia Pacific Sun Control Films Market size was valued at USD 1,782.50 million in 2018 to USD 2,233.56 million in 2024 and is anticipated to reach USD 3,756.74 million by 2032, at a CAGR of 6.7% during the forecast period. Asia Pacific holds the largest share of approximately 29% in the Global Sun Control Films Market. Strong economic growth, rapid urbanization, and increasing construction activities fuel regional expansion. China, Japan, and India are major contributors due to large-scale building projects and automotive production. Governments are focusing on reducing energy consumption through sustainable architectural solutions. Growing population density in urban centers is pushing the need for efficient cooling systems. The rising demand for residential and commercial retrofits supports long-term adoption. Technological advancements and cost-effective manufacturing strengthen regional competitiveness. Increasing awareness about environmental protection and comfort optimization further stimulates market growth.
Latin America
The Latin America Sun Control Films Market size was valued at USD 378.20 million in 2018 to USD 452.11 million in 2024 and is anticipated to reach USD 646.21 million by 2032, at a CAGR of 4.6% during the forecast period. Latin America represents nearly 7% of the Global Sun Control Films Market share. The region is witnessing growing demand in construction and automotive applications. Brazil leads with strong infrastructure investment and adoption of thermal protection films. Rising middle-class income levels support the use of energy-efficient window solutions. Mexico and Argentina show steady growth supported by vehicle production and urban expansion. Local distributors are improving product reach through retail and e-commerce networks. Government incentives for energy-saving technologies are gradually influencing market development. Continuous product awareness and regional manufacturing investments are expected to enhance long-term growth.
Middle East
The Middle East Sun Control Films Market size was valued at USD 260.40 million in 2018 to USD 296.42 million in 2024 and is anticipated to reach USD 417.61 million by 2032, at a CAGR of 4.4% during the forecast period. The region contributes around 5% to the Global Sun Control Films Market share. Its demand is driven by extreme climatic conditions and increased investment in infrastructure. Countries such as the UAE, Saudi Arabia, and Qatar are leading adopters due to their large commercial and residential construction projects. Sun control films are gaining popularity in high-rise buildings and luxury automobiles for heat and glare reduction. Energy-saving initiatives and green building mandates promote higher film utilization. Technological partnerships between local and international manufacturers are strengthening market presence. Rising awareness about indoor comfort and environmental sustainability supports future adoption. Regional diversification in product offerings enhances competitiveness in the construction and automotive sectors.
Africa
The Africa Sun Control Films Market size was valued at USD 102.30 million in 2018 to USD 174.47 million in 2024 and is anticipated to reach USD 224.03 million by 2032, at a CAGR of 2.7% during the forecast period. Africa accounts for nearly 3% of the Global Sun Control Films Market share. The region is emerging with rising infrastructure development and urban modernization. South Africa leads demand through commercial and residential projects focusing on energy efficiency. Limited product awareness and higher installation costs currently restrict broader market expansion. However, growth in tourism and hospitality sectors increases demand for comfort-enhancing window solutions. Import-driven supply chains influence regional availability and pricing. Governments are initiating programs to promote sustainable construction and energy conservation. With ongoing economic reforms and foreign investment, market penetration is expected to gradually strengthen across Africa.
Key Player Analysis:
- Avery Dennison Corporation
- 3M
- Garware Sun Control
- Saint-Gobain
- LLumar Films (Pty) Ltd.
- LINTEC Corporation
- Nexfil USA
- Solar Control Window Film Inc.
- Dexerials Corporation
- Eastman Performance Films LLC
- HAVERKAMP GmbH
- Recon Blinds E&B Co., Ltd.
- Madico Inc.
Competitive Analysis:
The Global Sun Control Films Market is moderately competitive, characterized by the presence of multinational corporations and regional players offering a diverse range of film solutions. It is dominated by key companies such as 3M, Avery Dennison Corporation, Garware Sun Control, Saint-Gobain, Eastman Performance Films, and Madico Inc. Competition centers on innovation, product quality, and expansion into developing markets. Firms are focusing on sustainable materials, improved UV resistance, and energy-efficient coatings to enhance performance. Strategic mergers, acquisitions, and capacity expansions strengthen market reach and distribution networks. Constant technological development in nanoceramic and reflective films continues to define market leadership.
Recent Developments:
- In September 2025, Saint-Gobain completed its acquisition of RISE Building Products through its CertainTeed Siding division, extending its commitment to sustainable, recycled-material-based construction solutions in North America. The deal aligns closely with Saint-Gobain’s glass and film technology focus, helping it strengthen its position in energy-efficient and eco-friendly building products applications.
- In August 2025, Avery Dennison further expanded its window film portfolio with the launch of the Auravate Decorative Film Series. This retrofit product range supports sustainable building initiatives and features seven design finishes, four of which are PVC-free. The films offer both privacy and daylight enhancement, catering to residential and commercial markets seeking eco-friendly upgrades.
- In July 2025, Lintec Corporation launched a new solar control window film made from 100% recycled PET resin under the WINCOS brand. Marketed as BR-50UH RECYCLE 100, the product aims to cut solar heat transmission and UV rays while simultaneously reducing CO₂ emissions from both manufacturing and building operations. This launch expanded Lintec’s sustainable film portfolio, following the company’s 2024 introduction of recycled shatterproof films.
- In January 2025, Garware Hi-Tech Films Limited announced a series of innovations in India, including the introduction of Coloured Paint Protection Film (PPF) and Head & Taillight Glass Protection Film. The company also formed strategic partnerships with Bajaj Finance for consumer financing of its films and Insurance Dekho to integrate protection film coverage into vehicle insurance policies, enhancing accessibility and customer value across its sun control film portfolio.
Report Coverage:
The research report offers an in-depth analysis based on film type, absorber type, and end-user segments.It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing adoption of energy-efficient building materials will drive global demand.
- Smart and adaptive sun control films will gain popularity in modern architecture.
- Expansion of automotive manufacturing will strengthen consumption worldwide.
- Rising environmental awareness will accelerate development of eco-friendly films.
- Nanoceramic and hybrid film technologies will redefine product performance.
- Urbanization in emerging economies will boost construction-related applications.
- Partnerships with real estate developers will expand commercial usage.
- E-commerce distribution will improve accessibility for residential consumers.
- Government policies promoting green infrastructure will enhance adoption rates.
- Continuous innovation in film durability and transparency will sustain long-term growth.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Demand for Energy-Efficient Building Materials
Sun control films are increasingly adopted in residential and commercial buildings to reduce heat gain, lower cooling costs, and comply with green building regulations, supporting energy conservation and sustainability goals.
Growth in Automotive Applications
Automotive manufacturers and consumers are using sun control films to improve cabin comfort, reduce glare, block UV rays, and enhance fuel efficiency by lowering air conditioning usage, especially as vehicle production rises in emerging markets.
Rising Awareness of UV Protection and Health Benefits
Consumers and businesses are prioritizing sun control films to protect interiors from fading, reduce skin damage, and improve occupant comfort, driving adoption in both the construction and automotive sectors.
Technological Advancements in Film Coatings
Innovations such as nano-ceramic, multi-layered, and smart adaptive films are enhancing thermal insulation, optical clarity, and durability, expanding the range of applications and improving product performance.
Expansion of Green Building and Smart Infrastructure Initiatives
Government incentives, stricter building codes, and the global push for sustainable urban development are accelerating the integration of sun control films in new construction and retrofit projects worldwide.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Sun Control Films Market?
At what Compound Annual Growth Rate is the Global Sun Control Films Market projected to grow between 2025 and 2032?
What drives the demand for sun control films?
Which regions dominate the sun control films market?
What are the challenges facing the sun control films market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Automotive
- 1.2.2 Construction
- 1.2.3 Design
- 1.2.4 Marine
- 1.2.5 Others
- 1.3 By Film Type
- 1.3.1 High-Performance Films
- 1.3.2 Vacuum Coated (Reflective)
- 1.3.3 Dyed (Non-Reflective)
- 1.3.4 Clear (Non-Reflective)
- 1.3.5 Other Film Types
- 1.4 By Absorber Type
- 1.4.1 Inorganic/Ceramic
- 1.4.2 Organic
- 1.4.3 Metallic
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 6,200.00 million → 2032: USD 11,566.28 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Sun Control Films Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Sun Control Films Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Sun Control Films Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Sun Control Films Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Sun Control Films Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Sun Control Films Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Sun Control Films Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Sun Control Films Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 6,200.00 million → 2032: USD 11,566.28 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Sun Control Films Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Automotive
- 12.3.7.2 Construction
- 12.3.7.3 Design
- 12.3.7.4 Marine
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Film Type - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 High-Performance Films
- 12.4.7.2 Vacuum Coated (Reflective)
- 12.4.7.3 Dyed (Non-Reflective)
- 12.4.7.4 Clear (Non-Reflective)
- 12.4.7.5 Other Film Types
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Absorber Type - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Volume Forecast, 2018-2032
- 12.5.5 Base-Year Market Share, 2018
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Inorganic/Ceramic
- 12.5.7.2 Organic
- 12.5.7.3 Metallic
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Sun Control Films End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Sun Control Films Geographic Market Outlook, 2018-2032
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Sun Control Films Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Sun Control Films Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Avery Dennison Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 3M
- 18.4 Garware Sun Control
- 18.5 Saint-Gobain
- 18.6 LLumar Films (Pty) Ltd.
- 18.7 LINTEC Corporation
- 18.8 Eastman Performance Films LLC
- 18.9 Madico Inc.
- 18.10 Dexerials Corporation
- 18.11 HAVERKAMP GmbH
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

