
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Industrial Hand Protection Gloves market Size 2024 | USD 11,880 million |
| Industrial Hand Protection Gloves market, CAGR | 13.40% |
| Industrial Hand Protection Gloves market Size 2032 | USD 32,487.84 million |
Market Overview:
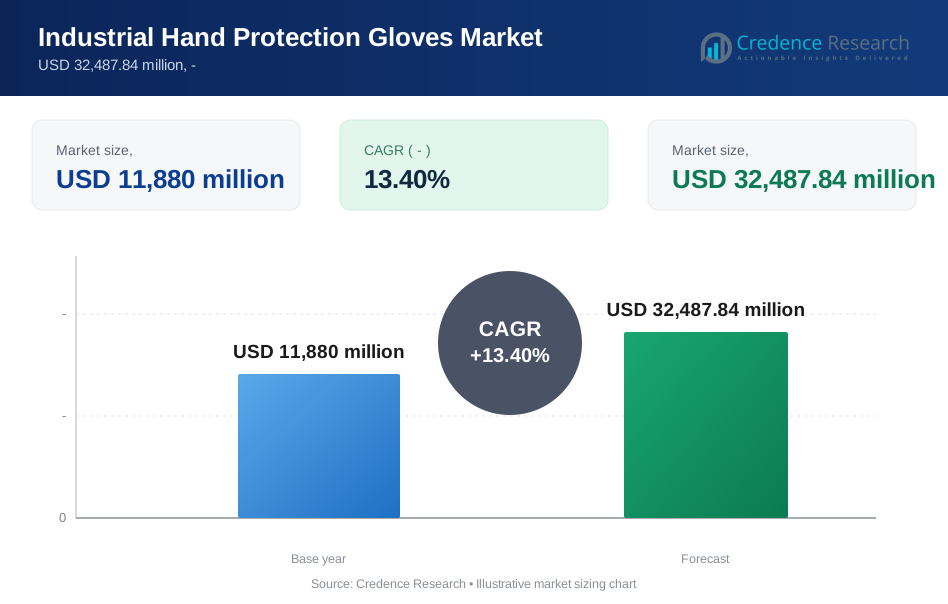
The Industrial Hand Protection Gloves market is projected to grow significantly from USD 11,880 million in 2024 to USD 32,487.84 million by 2032, reflecting a compound annual growth rate (CAGR) of 13.40% during the forecast period. This growth is driven by increasing awareness about workplace safety, rising occupational hazards, and stringent government regulations across various industries such as construction, oil and gas, chemical, and manufacturing. Employers are increasingly adopting protective gear, including hand protection gloves, to comply with safety standards and reduce workplace injuries.
Market drivers include the rise in industrial activities, particularly in developing economies, and the increasing emphasis on worker safety across hazardous work environments. The implementation of stringent regulations by bodies such as the Occupational Safety and Health Administration (OSHA) in the U.S. and the European Union’s PPE Directive, which mandate the use of personal protective equipment (PPE), is fueling the demand for industrial hand protection gloves. Additionally, advancements in glove manufacturing technology, such as enhanced cut resistance and ergonomic designs, are supporting market growth. The surge in demand for disposable gloves in the healthcare and chemical sectors, due to concerns over hygiene and contamination, is another critical factor driving the market.
In terms of regional analysis, North America holds the largest market share due to well-established industrial sectors, strict safety regulations, and high awareness about occupational safety. Europe follows closely, driven by strong regulatory frameworks and significant R&D investments in worker safety equipment. However, the Asia-Pacific region is expected to witness the fastest growth during the forecast period, with countries like China and India seeing increased industrialization and infrastructure development. The growth of industries in these regions, coupled with government initiatives to improve worker safety standards, is expected to drive demand for industrial hand protection gloves.
Market Drivers:
Growing Focus on Workplace Safety Regulations:
The increasing emphasis on workplace safety regulations is one of the primary drivers of the Industrial Hand Protection Gloves market. Government bodies across the globe are implementing stringent policies to reduce workplace injuries, particularly in high-risk industries such as construction, manufacturing, and oil and gas. For instance, in the U.S., the Occupational Safety and Health Administration (OSHA) reported that hand injuries accounted for nearly 23% of all workplace injuries in 2022, underscoring the need for protective gloves. The enforcement of safety regulations and the imposition of penalties for non-compliance are pushing companies to prioritize personal protective equipment (PPE), including hand protection gloves.
Rising Industrialization in Emerging Economies:
Emerging economies, particularly in Asia-Pacific and Latin America, are witnessing rapid industrialization, which is fueling the demand for industrial hand protection gloves. The expansion of sectors such as construction, manufacturing, and chemicals in countries like India and Brazil is creating a heightened need for worker safety. For example, according to the Indian Ministry of Labor, industrial accidents in 2023 were most commonly caused by a lack of proper protective equipment, leading to the Indian government mandating stricter safety guidelines for hazardous industries. This rising industrial activity, combined with regulatory pressure, is expected to continue driving demand for protective gloves.
Technological Advancements in Glove Manufacturing:
Technological advancements in glove manufacturing are playing a crucial role in boosting market growth. Innovations such as enhanced cut resistance, anti-vibration features, and chemical-resistant materials are improving the durability and functionality of industrial hand protection gloves. For instance, in 2022, Ansell, a leading manufacturer, launched its HyFlex range with advanced ergonomics and greater dexterity, designed to reduce hand fatigue for workers in the automotive and metal fabrication sectors. These technological improvements are encouraging employers to invest in high-performance gloves that ensure better protection and comfort.
Growing Awareness of Hygiene in Industrial Settings:
The increasing awareness of hygiene and contamination control in industries like healthcare and chemicals is significantly driving the demand for disposable gloves. During the COVID-19 pandemic, the use of disposable gloves surged in various industrial sectors to prevent contamination. For instance, a 2022 survey by the World Health Organization (WHO) revealed that the use of disposable gloves in the healthcare sector rose by 40% in response to hygiene concerns. This trend has continued post-pandemic, with industries focusing on maintaining high hygiene standards, further boosting the adoption of disposable hand protection gloves.
Market Trends:
Increasing Adoption of Sustainable Materials:
A growing trend in the Industrial Hand Protection Gloves market is the shift toward sustainable materials in glove manufacturing. Companies are increasingly focusing on eco-friendly options to meet rising environmental concerns and comply with government regulations on sustainable practices. For instance, in 2023, Showa Group launched a biodegradable nitrile glove that can decompose within five years in a landfill, compared to the traditional gloves that take decades. Governments, especially in Europe, are encouraging the use of biodegradable materials in personal protective equipment (PPE) to reduce environmental impact.
Surge in Demand for Disposable Gloves:
The demand for disposable gloves continues to rise across various industries, primarily driven by heightened hygiene awareness in healthcare, food processing, and chemical industries. Post-pandemic, this trend has persisted as companies emphasize contamination control and hygiene. For example, a 2022 report by the World Health Organization (WHO) noted a 35% increase in the global use of disposable gloves in healthcare settings. In food processing and healthcare sectors, disposable gloves are now considered an essential tool in ensuring both worker and consumer safety, further boosting their demand.
Rising Focus on Ergonomic and Comfort-Oriented Designs:
Another trend shaping the market is the increasing focus on ergonomic designs that enhance user comfort and productivity. Hand protection gloves are being designed with advanced materials that offer better dexterity, flexibility, and reduced hand fatigue. For instance, Ansell’s 2023 launch of its HyFlex series introduced gloves with improved comfort and grip, tailored for industries such as automotive and machinery. Ergonomically designed gloves are becoming increasingly popular, particularly in sectors where precision and hand comfort are critical for worker efficiency.
Integration of Smart Technologies:
The integration of smart technologies into industrial hand protection gloves is an emerging trend aimed at enhancing workplace safety. Companies are experimenting with gloves embedded with sensors that monitor environmental factors or worker biometrics. For instance, in 2022, ProGlove introduced wearable gloves with embedded sensors that track hand movements, helping to reduce repetitive strain injuries. These innovations not only improve worker safety but also provide valuable data to employers, enabling better risk management and operational efficiency in high-risk environments.
Market Challenges Analysis:
Regulatory Compliance and Certification Costs:
One of the significant restraints in the Industrial Hand Protection Gloves market is the high cost associated with regulatory compliance and certification. Manufacturers must ensure that their products meet stringent safety standards set by regulatory bodies such as OSHA in the U.S. and the European Union’s PPE Directive. These requirements often mandate thorough testing and certification processes, which can be costly and time-consuming, particularly for small and medium-sized enterprises (SMEs). Failure to meet these standards can result in penalties or the withdrawal of products from the market, making compliance an essential yet expensive aspect for manufacturers.
Fluctuating Raw Material Prices:
Another challenge faced by the market is the volatility of raw material prices, particularly for rubber, nitrile, and latex, which are essential components in glove manufacturing. Fluctuations in the cost of these materials, driven by factors such as supply chain disruptions and geopolitical issues, can significantly impact the production costs of industrial gloves. For instance, disruptions in natural rubber production due to climate change or trade restrictions can lead to price hikes, squeezing profit margins for manufacturers. These cost pressures are particularly challenging for companies producing high volumes of disposable gloves, where margins are typically thinner.
Environmental Concerns and Waste Management:
The disposal of industrial gloves, particularly single-use gloves, poses environmental challenges, with many countries facing increased pressure to manage PPE waste. Traditional gloves made from non-biodegradable materials contribute to landfill waste, and their disposal can be harmful to the environment. Governments and environmental agencies are pushing for sustainable alternatives, but the cost and technical limitations of developing eco-friendly materials remain significant barriers. This creates a challenge for manufacturers to balance sustainability goals with cost-effective production.
Market Segmentation Analysis:
By Type, the market is divided into disposable and reusable gloves. Disposable gloves, typically used in industries like healthcare and food processing, are designed for single use, while reusable gloves, which are more durable and cost-effective over time, are favored in manufacturing, construction, and heavy industries. The demand for both types is driven by the specific needs of industries, with disposable gloves gaining traction post-pandemic due to heightened hygiene awareness.
By Technology, the market includes advanced materials such as nitrile, latex, rubber, and neoprene, as well as specialized glove technologies like cut-resistant, chemical-resistant, and heat-resistant gloves. Technological advancements in materials, aimed at improving durability, ergonomics, and safety, have led to the development of innovative glove designs tailored for specific industrial applications.
By End User, the market caters to a range of sectors including manufacturing, construction, oil and gas, healthcare, and food processing. The manufacturing and construction sectors dominate the market, driven by stringent safety regulations and the need for protective gear in hazardous work environments. However, the healthcare and food processing sectors have seen rapid growth in demand for disposable gloves due to hygiene concerns and regulatory compliance requirements.
Segmentations:
By Type- Disposable Gloves
- Reusable Gloves
- Natural Rubber Gloves/Latex
- Nitrile Gloves
- Vinyl Gloves
- Others (Neoprene, Polyethylene, Polyvinyl Alcohol, Polyvinyl Chloride)
- Construction
- Chemical
- Automotive Sectors
- Electronics Industry
- Healthcare
- Others
- North America
- US
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- UK
- Spain
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC
- Israel
- Rest of Middle East
- Africa
- South Africa
- North Africa
- Central Africa
Regional Analysis:
North America
North America holds the largest market share in the Industrial Hand Protection Gloves market, accounting for approximately 35% of the global market. The region's dominance is driven by well-established industrial sectors, strict safety regulations, and a strong focus on worker protection. The United States leads this region, with industries such as manufacturing, oil and gas, and healthcare adhering to stringent safety standards mandated by the Occupational Safety and Health Administration (OSHA). Major players in the region, such as Honeywell and Ansell, continually innovate their product lines to meet the high demand for advanced protection gloves. Additionally, the presence of key end-user industries, robust infrastructure, and government policies supporting occupational safety further contribute to the market's growth in North America.
Europe
Europe accounts for approximately 30% of the global market share. Countries such as Germany, the United Kingdom, and France lead the region in terms of adoption and innovation in industrial hand protection gloves. The European Union's stringent regulations, including the PPE Directive, require high safety standards across industries, ensuring consistent demand for protective gloves. The presence of large manufacturing and chemical industries in Germany and France has further boosted the demand for advanced protection gloves. Additionally, ongoing technological advancements in glove materials, such as cut-resistant and chemical-resistant gloves, are fueling growth in this region. European companies are also investing in sustainable materials and eco-friendly production methods, aligning with the region's environmental goals.
Asia-Pacific
The Asia-Pacific region is expected to witness the fastest growth in the Industrial Hand Protection Gloves market, with a projected market share of around 25% by 2032. The growth in this region is primarily driven by rapid industrialization in countries like China, India, and Southeast Asian nations. Governments in these countries are increasingly focusing on improving workplace safety standards, which is expected to drive the demand for industrial gloves. For instance, India's Ministry of Labor has been strengthening occupational safety regulations, leading to increased adoption of protective gloves in construction and manufacturing industries. Additionally, lower production costs and a growing workforce are attracting global manufacturers to set up production facilities in the region, further boosting market demand.
Latin America and Middle East & Africa
Latin America and the Middle East & Africa collectively account for around 10% of the global Industrial Hand Protection Gloves market. In Latin America, countries like Brazil and Mexico are witnessing a gradual rise in the adoption of safety gloves as industrial activities grow. The construction and oil & gas sectors are major drivers of demand in this region. In the Middle East & Africa, countries such as Saudi Arabia and the UAE are investing heavily in industrial infrastructure, which is expected to increase the demand for industrial hand protection gloves. However, challenges such as limited healthcare access and economic constraints in some parts of these regions may slow down market growth. Nevertheless, as industrialization progresses and workplace safety becomes a priority, the market holds long-term potential in these regions.
Key Player Analysis:
- Ansell Limited
- Honeywell International Inc.
- Top Glove Corporation Bhd
- 3M Company
- Hartalega Holdings Berhad
- Kimberly-Clark Corporation
- Superior Glove Works Ltd.
- Lakeland Industries, Inc.
- MCR Safety
- Riverstone Holdings Limited
Competitive Analysis:
The Industrial Hand Protection Gloves Market is highly competitive, with both global and regional players striving to maintain market share through product innovation, strategic partnerships, and geographical expansion. Major players like Ansell Limited, Honeywell International Inc., and 3M Company dominate the market due to their extensive product portfolios, strong brand presence, and advanced R&D capabilities. These companies are focusing on introducing technologically advanced gloves with enhanced durability, cut resistance, and ergonomics to cater to various industrial needs. Mid-sized companies such as Superior Glove Works Ltd. and Lakeland Industries target niche markets by offering specialized gloves tailored for specific industries, such as chemical resistance and anti-vibration. The increasing emphasis on sustainability and the adoption of eco-friendly materials have also led key players to invest in greener alternatives. The competitive landscape is further shaped by price pressures and the need to comply with stringent safety regulations across different regions.
Recent Developments:
- Ansell Limited expanded its global presence by launching a new packing and irradiation facility in Kovai, India, in June 2023. The company invested approximately $80 million in this facility, aiming to boost production capacity and strengthen its foothold in the region, further enhancing its product offerings and growth strategy.
- In February 2023, Ansell acquired the remaining 50% stake in Careplus (M) Sdn Bhd, a leading surgical glove manufacturer. This acquisition allows Ansell full control over the operations and opens new avenues for product development and capacity expansion, solidifying its position in the surgical glove market.
- In September 2022, J. Keller & Associates expanded its SAFEGEAR Industrial Gloves line to include a wider range of ANSI cut levels, from A1 to A9. This expansion includes high-performance gloves with advanced materials, such as steel and tungsten fibers, enhancing protection and expanding market reach.
- Supermax Corp Bhd announced a strategic partnership with Minco Wholesale & Supply Inc. in August 2022 to distribute Supermax’s healthcare products, including industrial rubber gloves, across North America. This partnership is aimed at expanding market penetration in the region.
Market Concentration & Characteristics:
The Industrial Hand Protection Gloves Market is moderately concentrated, with a mix of global players such as Ansell Limited, Honeywell International Inc., and 3M Company dominating the market due to their extensive product portfolios, robust supply chains, and significant R&D investments. These key players leverage innovation in materials and ergonomics to cater to diverse industry demands across sectors like manufacturing, construction, and healthcare. Mid-sized and regional companies, such as Superior Glove Works and TOWA Corporation, maintain a competitive edge by offering specialized gloves tailored to niche markets like chemical resistance and cut protection. The market is characterized by ongoing technological advancements, increasing emphasis on worker safety, and stringent regulatory frameworks that ensure high standards of protection. Despite the dominance of major players, the presence of numerous smaller companies fosters competition, particularly in emerging markets with growing industrial sectors.
Report Coverage:
The research report offers an in-depth analysis based on Type, Material, End-use Industry, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The growing emphasis on workplace safety regulations will continue driving demand for industrial hand protection gloves across multiple sectors, particularly in high-risk industries.
- Technological advancements in materials such as cut-resistant, heat-resistant, and chemical-resistant gloves will lead to enhanced durability and functionality, boosting adoption.
- Increased demand for sustainable and eco-friendly gloves will rise as environmental concerns push manufacturers to develop biodegradable or recyclable products.
- The Asia-Pacific region will experience rapid growth due to industrial expansion in countries like China and India, coupled with rising awareness of worker safety.
- Manufacturers will invest more in smart gloves equipped with sensors that monitor environmental conditions, providing real-time data to enhance workplace safety.
- Disposable gloves will continue to witness high demand, especially in healthcare, food processing, and chemical industries, due to heightened hygiene standards.
- Partnerships and collaborations between glove manufacturers and end-user industries will increase, improving product customization and service delivery.
- Market consolidation is expected as large players acquire smaller companies to strengthen their product portfolios and expand geographically.
- Supply chain challenges, particularly in raw material sourcing, may impact pricing and availability, pushing companies to explore alternative materials.
- Increased automation and mechanization in manufacturing will drive demand for specialized gloves that offer enhanced protection and comfort for workers operating complex machinery.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Industrial Hand Protection Gloves Market?
What factors are driving the growth of the Industrial Hand Protection Gloves Market?
What are some challenges faced by the Industrial Hand Protection Gloves Market?
Who are the major players in the Industrial Hand Protection Gloves Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Industrial Hand Protection Gloves Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Industrial Hand Protection Gloves Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 11,880 million → forecast year: USD 32,487.84 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Industrial Hand Protection Gloves Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Industrial Hand Protection Gloves Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Industrial Hand Protection Gloves Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Industrial Hand Protection Gloves Market Drivers
- 3.3 Industrial Hand Protection Gloves Market Restraints & Challenges
- 3.4 Industrial Hand Protection Gloves Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Industrial Hand Protection Gloves Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Industrial Hand Protection Gloves Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Industrial Hand Protection Gloves category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Industrial Hand Protection Gloves Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Industrial Hand Protection Gloves Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Industrial Hand Protection Gloves market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Industrial Hand Protection Gloves Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Industrial Hand Protection Gloves Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Industrial Hand Protection Gloves Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Industrial Hand Protection Gloves (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Industrial Hand Protection Gloves Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Industrial Hand Protection Gloves Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Industrial Hand Protection Gloves Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Industrial Hand Protection Gloves Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Industrial Hand Protection Gloves Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Industrial Hand Protection Gloves Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Industrial Hand Protection Gloves Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Industrial Hand Protection Gloves Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Industrial Hand Protection Gloves Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
