
Market Overview
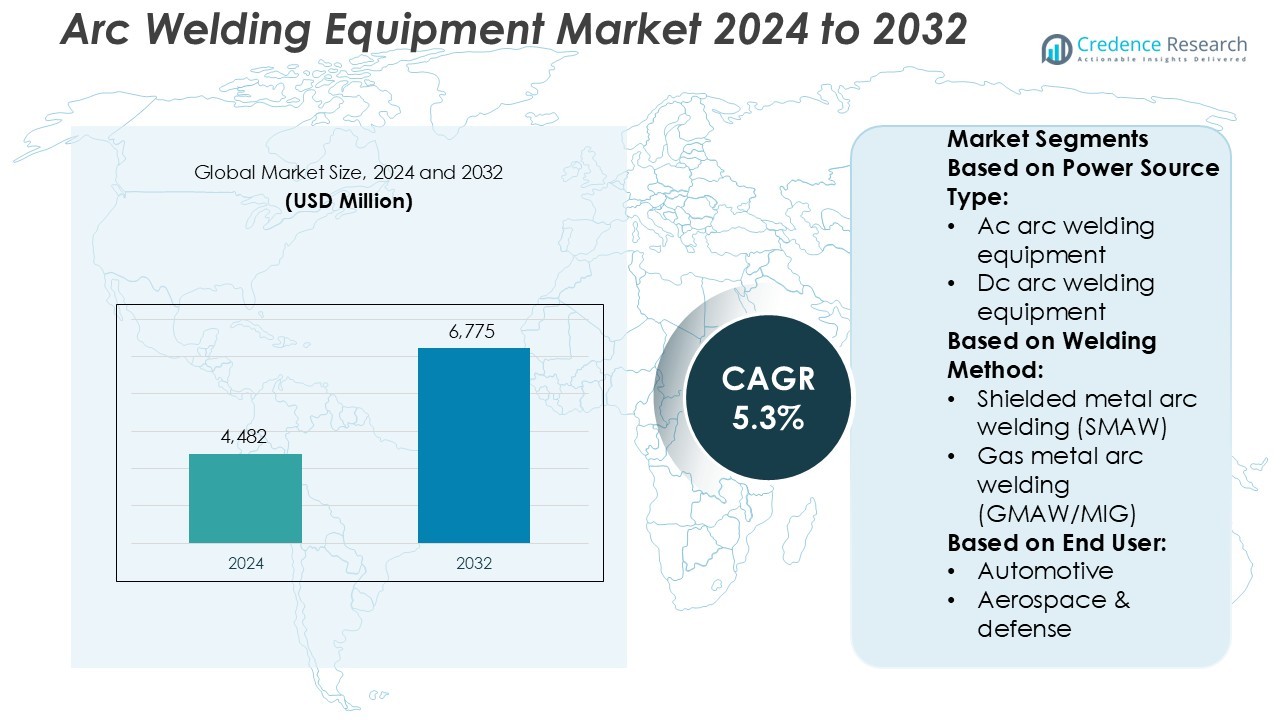
Arc Welding Equipment Market size was valued USD 4,482 million in 2024 and is anticipated to reach USD 6,775 million by 2032, at a CAGR of 5.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Arc Welding Equipment Market Size 2024 | USD 4,482 Million |
| Arc Welding Equipment Market, CAGR | 5.3% |
| Arc Welding Equipment Market Size 2032 | USD 6,775 Million |
The Arc Welding Equipment Market is led by prominent players including Kemppi Oy, Atlas Copco, Air Liquide Welding, Panasonic Welding Systems Co., Ltd., Emerson Electric, Fronius International GmbH, Obara Corporation, Colfax Corporation, Robert Bosch, and Stanley Decker. These companies focus on automation, digital integration, and energy-efficient technologies to enhance welding performance and reliability. Product innovation, strategic partnerships, and expansion into emerging markets remain key competitive strategies. Asia-Pacific dominates the global market with a 37% share, driven by rapid industrialization, large-scale infrastructure development, and strong manufacturing growth in countries such as China, India, Japan, and South Korea.
Market Insights
- The Arc Welding Equipment Market was valued at USD 4,482 million in 2024 and is projected to reach USD 6,775 million by 2032, growing at a CAGR of 5.3%.
- Rising demand from manufacturing, construction, and automotive sectors drives the adoption of advanced welding systems.
- Automation, digital integration, and energy-efficient inverter technologies are shaping market trends toward high-performance welding solutions.
- The competitive landscape features strong innovation and global expansion efforts by leading players, though high equipment costs and skilled labor shortages remain challenges.
- Asia-Pacific holds a dominant 37% regional share, supported by rapid industrialization and infrastructure growth, while DC arc welding equipment leads by power source type due to its precision and consistent output.
Market Segmentation Analysis:
By Power Source Type
DC arc welding equipment holds the dominant share of the Arc Welding Equipment Market. Its popularity stems from superior control, stable arcs, and deeper weld penetration compared to AC systems. DC power sources are preferred in industries such as automotive and heavy manufacturing, where precision and consistent quality are crucial. AC welding equipment remains in demand for aluminum and repair work due to its lower cost and versatility. The “others” category includes hybrid and inverter-based sources gaining adoption for energy efficiency and portability in small-scale and field operations.
- For instance, Kemppi’s Minarc T 223 DC portable TIG machine outputs up to 220 amps and weighs only 9.6 kg. DC power sources are preferred in industries such as automotive and heavy manufacturing, where precision and consistent quality are crucial.
By Welding Method
Gas metal arc welding (GMAW/MIG) leads the market with the largest share among welding methods. The process offers high deposition rates, ease of automation, and suitability for a range of metals, making it a standard in automotive and fabrication industries. Shielded metal arc welding (SMAW) continues to be used for its simplicity and low equipment cost, particularly in construction and repair applications. Flux-cored arc welding (FCAW) finds growing use in structural steelwork due to its high productivity in outdoor conditions, while other methods serve niche and specialized welding needs.
- For instance, Atlas Copco’s Industrial Technique division integrated a robotic welding cell in a vehicle chassis line that achieved a wire-feed rate of 12 m/min and a deposition current of 350 A using a GMAW system in 2023 (internal case study).
By End User
The manufacturing sector dominates the market, accounting for the largest end-user share. Rising automation and demand for durable, high-quality joints in machinery and equipment production drive adoption. Automotive and construction industries also represent significant consumers, leveraging welding systems for body frames, infrastructure, and pipelines. The aerospace and defense sector demands advanced, precision-controlled welding systems for lightweight alloys. Oil and gas industries invest in robust systems for high-pressure pipeline welding, while others include small fabrication workshops and custom component producers contributing to overall market growth.
Key Growth Drivers
- Rising Industrial Automation and Manufacturing Expansion The increasing adoption of automated welding systems across manufacturing facilities drives market growth. Automation enhances weld precision, productivity, and consistency while minimizing material waste and labor dependency. Expanding automotive, construction, and heavy machinery sectors further strengthen equipment demand. Growing investments in smart factories and Industry 4.0 integration promote the use of advanced robotic and inverter-based arc welding systems for high-speed, multi-axis operations across global production environments.
- For instance, Air Liquide’s subsidiary Airgas offers the BotX™ Cobot Welding System which clients report achieved a 2 × to 3 × increase in productivity compared with manual welding.
- Increasing Infrastructure and Construction Activities Rapid urbanization and infrastructure development across emerging economies boost demand for arc welding equipment. Large-scale projects in transportation, energy, and commercial construction require reliable welding tools for structural integrity and long-term performance. Governments are investing heavily in bridges, pipelines, and industrial facilities, creating a robust need for efficient, portable welding systems. Additionally, the focus on sustainable and modular construction techniques supports the adoption of energy-efficient arc welding equipment in both on-site and off-site applications.
- For instance, Panasonic’s Indian arm launched the IGBT-controlled DC TIG welding power source model YD-400AT3DJU at its Jhajjar, Haryana facility that supports weld currents as low as 4 amps and is built in a hermetically sealed, dust-proof and waterproof structure.
- Technological Advancements in Welding Equipment The introduction of inverter technology, digital control interfaces, and energy-efficient systems has transformed welding operations. These innovations provide enhanced arc stability, reduced power consumption, and higher operational flexibility. Manufacturers are integrating IoT-enabled monitoring, adaptive controls, and predictive maintenance features to improve productivity and reduce downtime. Such technological progress encourages industries to upgrade legacy systems, leading to sustained equipment demand and increased penetration of advanced arc welding solutions across industrial applications.
Key Trends & Opportunities
- Growing Shift Toward Energy-Efficient and Portable Systems Manufacturers are focusing on developing lightweight, portable arc welding systems that consume less energy without compromising performance. Compact inverter-based machines are becoming popular for remote and on-site applications. These systems meet sustainability targets and reduce carbon footprints. The growing preference for mobility and eco-friendly solutions among contractors and fabrication units creates lucrative opportunities for equipment suppliers emphasizing low-energy, high-efficiency technologies.
- For instance, Emerson launched the “Energy Manager” plug-and-play solution that monitors up to 10 endpoints (expandable to 50) in real-time, helping manufacturers reduce idle-machine energy by up to 30 %.
- Rising Demand for Automated and Robotic Welding Solutions The integration of robotics with arc welding processes is reshaping modern production lines. Automated welding offers precision, repeatability, and reduced cycle times in high-volume manufacturing environments. Automotive and aerospace industries are adopting robotic systems to meet tight tolerances and quality standards. This trend opens opportunities for vendors to provide integrated robotic-welding packages and AI-based process control tools that ensure consistent weld quality under varying material and environmental conditions.
- For instance, Fronius’s robotic welding power-source platform “TPS/i Robotics” supports welding currents up to 600 A, enabling simultaneous use of standard, pulse, and CMT processes in robot-mounted systems.
- Expansion in Renewable Energy and Offshore Projects Growing investments in wind, solar, and offshore energy infrastructure present emerging opportunities for arc welding manufacturers. The need for durable welds in turbine towers, offshore platforms, and energy storage structures drives specialized equipment demand. The development of corrosion-resistant materials and advanced welding consumables further supports these projects. This transition toward renewable energy infrastructure fuels market expansion across both developed and developing economies.
Key Challenges
- Shortage of Skilled Welding Workforce A global shortage of skilled welders poses a major challenge to the arc welding equipment market. Operating advanced systems requires technical proficiency, yet many regions face declining enrollment in vocational welding programs. The widening skills gap restricts productivity and limits the adoption of automated systems. Manufacturers and training institutes are addressing this by developing simulation-based training and remote learning modules to upskill technicians and support industry modernization.
- High Initial Cost and Maintenance RequirementsThe high cost of advanced arc welding systems, particularly automated and robotic setups, acts as a restraint for small and medium enterprises. Initial investment, combined with ongoing maintenance and consumable costs, can hinder adoption. Additionally, downtime due to component wear or software calibration increases operational expenses. Manufacturers are responding with modular systems, leasing options, and service-based models to make advanced equipment more accessible and cost-effective for smaller production units.
Regional Analysis
North America
North America holds a market share of 28% in the Arc Welding Equipment Market. The region’s strong industrial base, especially in automotive, aerospace, and energy sectors, drives consistent demand for advanced welding systems. The United States leads adoption due to high automation levels and technological innovation in manufacturing. Growth in oil and gas pipeline projects further boosts demand for portable and high-performance arc welders. Government investments in infrastructure rehabilitation and renewable energy expansion support market stability, while the presence of major manufacturers fosters ongoing product advancements across the region.
Europe Europe accounts for 24% of the global arc welding equipment market, driven by its robust automotive and industrial machinery sectors. Germany, Italy, and France dominate with advanced production capabilities and emphasis on energy-efficient welding technologies. The European Union’s stringent safety and emission standards encourage manufacturers to adopt eco-friendly, low-emission welding systems. Automation and robotic welding are gaining traction in automotive and shipbuilding industries. Ongoing infrastructure renewal projects, coupled with steady demand from renewable energy equipment manufacturing, further enhance regional market performance and technology adoption across industrial segments.
Asia-Pacific
Asia-Pacific leads the Arc Welding Equipment Market with a 37% market share, making it the dominant regional segment. Rapid industrialization, strong construction activity, and large-scale manufacturing expansion in China, India, Japan, and South Korea drive growth. The region benefits from low production costs, growing foreign investments, and rising demand for consumer goods and vehicles. Local manufacturers are increasingly adopting automated and inverter-based welding systems for enhanced productivity. Government initiatives promoting industrial modernization and infrastructure development continue to boost demand, making Asia-Pacific a global manufacturing and welding technology hub.
Latin America
America captures 6% of the global market share, supported by expanding construction, oil and gas, and automotive industries. Brazil and Mexico are key contributors, driven by growing industrial production and infrastructure projects. The rising adoption of energy-efficient and portable arc welding systems is enhancing operational efficiency in manufacturing and repair sectors. Government-led development in renewable energy and transportation networks is expected to accelerate market growth. However, limited technological integration and high import dependency may restrain adoption compared to more industrialized regions.
Middle East & Africa
The Middle East & Africa region holds a 5% share in the global Arc Welding Equipment Market. Growth is primarily driven by oil and gas pipeline projects, infrastructure development, and the establishment of new industrial zones. Countries such as Saudi Arabia, the UAE, and South Africa are witnessing increased use of automated welding systems to improve efficiency and quality in energy and construction sectors. Investments in renewable energy and industrial diversification are strengthening regional demand. However, slower technological adoption and limited local manufacturing capabilities pose mild growth constraints.
Market Segmentations:
By Power Source Type:
- Ac arc welding equipment
- Dc arc welding equipment
By Welding Method:
- Shielded metal arc welding (SMAW)
- Gas metal arc welding (GMAW/MIG)
By End User:
- Automotive
- Aerospace & defense
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Arc Welding Equipment Market features strong competition among key players such as Kemppi Oy, Atlas Copco, Air Liquide Welding, Panasonic Welding Systems Co., Ltd., Emerson Electric, Fronius International GmbH, Obara Corporation, Colfax Corporation, Robert Bosch, and Stanley Decker. The Arc Welding Equipment Market is highly competitive, driven by rapid technological advancements and growing demand for automation. Manufacturers are investing in research and development to create energy-efficient, portable, and digitally integrated welding systems. The market is witnessing a strong shift toward inverter-based and robotic welding technologies that enhance productivity and precision in industrial applications. Strategic collaborations, mergers, and product innovations remain key strategies to strengthen global presence. Companies are also expanding their service networks and adopting smart monitoring systems to improve operational efficiency and meet evolving customer requirements across industries.
Key Player Analysis
- Kemppi Oy
- Atlas Copco
- Air Liquide Welding
- Panasonic Welding Systems Co., Ltd.
- Emerson Electric
- Fronius International GmbH
- Obara Corporation
- Colfax Corporation
- Robert Bosch
- Stanley Decker
Recent Developments
- In April 2025, TRUMPF and SCHMID Group partnered to co-develop laser-plus-wet-chemistry processes for glass interposers used in advanced semiconductor packages, broadening TRUMPF’s photonics exposure beyond metal welding.
- In June 2024, Burnsview Secondary School in North Delta received a $3,500 grant from the CWB Welding Foundation to support its welding education program. The funds will be used to purchase a TIG welder, offering students hands-on experience with industry-standard equipment and materials.
- In March 2023, voestalpine Böhler Welding Group GmbH launched Böhler Welding`s Crane & Lifting Full Welding Solution. The product helped the company to achieve 50% faster welding speed.
- In February 2023, Miller Electric Mfg. LLC launched the Copilot Collaborative Welding System in February 2023. It is a cobot with advanced capabilities intended for welders and shops new to robotic welding who are looking for solutions to keep up with demand.
Report Coverage
The research report offers an in-depth analysis based on Power Source Type, Welding Method, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue to grow with rising adoption of automated and robotic welding systems.
- Demand for energy-efficient and inverter-based welding equipment will increase across industries.
- Integration of IoT and AI technologies will enhance real-time monitoring and process control.
- Infrastructure expansion and industrialization in emerging economies will boost equipment sales.
- Portable and lightweight welding machines will gain popularity in construction and repair sectors.
- Manufacturers will focus on digital welding solutions to improve precision and productivity.
- Training programs and simulation tools will address the shortage of skilled welders.
- Strategic collaborations and mergers will strengthen global supply and innovation capacity.
- Growth in renewable energy and transportation sectors will create new application opportunities.
- Sustainability goals will drive the development of low-emission and eco-friendly welding systems.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Arc Welding Equipment Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Arc Welding Equipment Market projected to grow between 2025 and 2032?
Which Arc Welding Equipment Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Arc Welding Equipment Market?
Who are the leading companies in the Arc Welding Equipment Market?
Which region commanded the largest share of the Arc Welding Equipment Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4,482 million → 2032: USD 6,775 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Arc Welding Equipment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Arc Welding Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Arc Welding Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Arc Welding Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Arc Welding Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Arc Welding Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Arc Welding Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Arc Welding Equipment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4,482 million → 2032: USD 6,775 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Arc Welding Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Arc Welding Equipment Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Arc Welding Equipment Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Arc Welding Equipment Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

