
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Inorganic Flame Retardants Market Size 2024 | USD 10575 Million |
| Inorganic Flame Retardants Market, CAGR | 7.4% |
| Inorganic Flame Retardants Market Size 2032 | USD 18720.37 Million |
Market Overview:
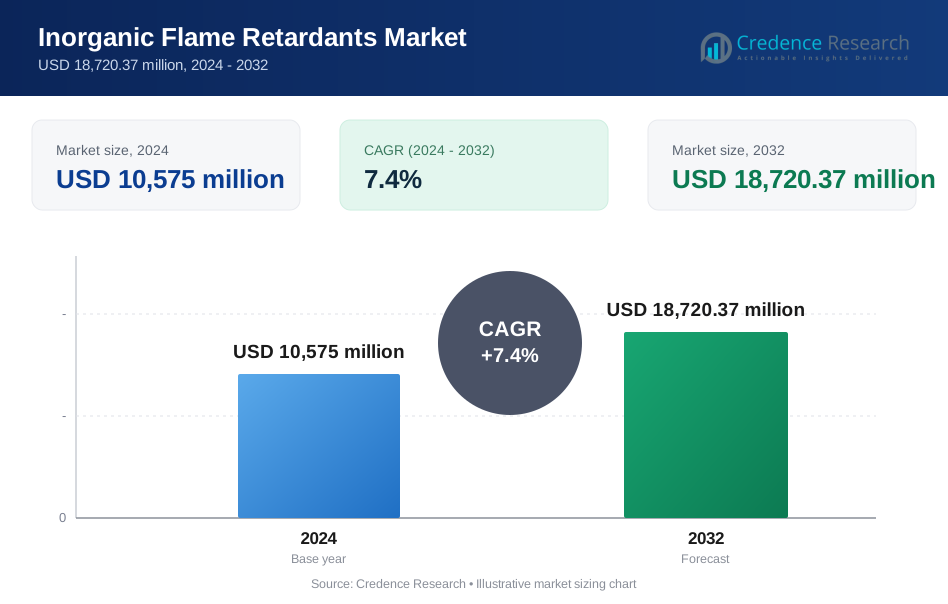
Inorganic Flame Retardants Market size was valued at USD 10575 million in 2024 and is anticipated to reach USD 18720.37 million by 2032, at a CAGR of 7.4% during the forecast period (2024-2032).
The growing emphasis on fire safety measures, particularly in residential and commercial buildings, is a major driver for the inorganic flame retardants market. Governments worldwide are enforcing stricter fire safety regulations, fueling the demand for non-toxic and eco-friendly flame retardants. Additionally, the expanding use of electronic devices and electric vehicles (EVs) has increased the need for flame-retardant materials to enhance safety standards. Industries are shifting towards halogen-free retardants due to environmental concerns, further boosting the adoption of aluminum hydroxide (ATH), magnesium hydroxide (MDH), and antimony trioxide-based flame retardants. Increasing research and development activities focused on improving the efficiency and sustainability of flame retardants are also driving market growth. Moreover, the growing awareness about workplace fire hazards and the increasing integration of flame retardants in plastics, coatings, and textiles are further stimulating market expansion. The rising adoption of bio-based and recycled flame retardants is also expected to create lucrative opportunities for manufacturers.
North America and Europe dominate the market due to stringent fire safety regulations and the well-established automotive and construction sectors. The Asia-Pacific region is expected to witness the fastest growth, driven by rapid industrialization, increasing infrastructure development, and the expansion of the electronics and automotive sectors in countries like China, India, and Japan. Government initiatives promoting fire safety and rising investments in manufacturing facilities further support regional market expansion. Additionally, the booming real estate sector and rising consumer preference for flame-retardant home furnishing materials are contributing to market growth in emerging economies. Meanwhile, the Middle East and Africa are also seeing gradual growth, particularly in construction and oil & gas industries where fire safety is a critical concern. The rising adoption of stringent industrial safety norms in sectors like petrochemicals and transportation is further driving demand in these regions.
Market Insights:
- The inorganic flame retardants market was valued at USD 10,575 million in 2024 and is projected to reach USD 18,720.37 million by 2032, growing at a CAGR of 7.4% during the forecast period.
- Stringent fire safety regulations in industries such as construction, automotive, and electronics are driving the demand for non-toxic and eco-friendly flame retardants worldwide.
- The electronics and electric vehicle (EV) sectors are key contributors to market growth, with increasing demand for fire-resistant batteries, circuit boards, and wiring systems.
- Halogen-free flame retardants, such as aluminum hydroxide (ATH) and magnesium hydroxide (MDH), are gaining popularity due to environmental concerns and strict regulations on hazardous chemicals.
- The Asia-Pacific region leads the market with a 40% share, driven by industrialization, infrastructure development, and the expanding automotive and electronics sectors in China, India, and Japan.
- North America (25%) and Europe (30%) remain dominant players due to well-established industries, regulatory enforcement, and increasing adoption of sustainable fire safety solutions.
- Rising investments in research and development (R&D) are fostering innovation in bio-based, recyclable, and high-efficiency flame retardants, opening new opportunities for market expansion.
Market Drivers:
Stringent Fire Safety Regulations and Compliance Requirements
Governments and regulatory bodies worldwide are implementing strict fire safety standards across industries, driving demand for inorganic flame retardants. Construction materials, automotive components, and electronic devices must comply with fire-resistant norms to reduce fire hazards and enhance safety. Regulations such as REACH (Registration, Evaluation, Authorization, and Restriction of Chemicals) in Europe and the National Fire Protection Association (NFPA) standards in the U.S. mandate the use of effective flame retardants in multiple applications. For instance, the European Union's REACH regulation has led to a significant reduction in the use of hazardous substances in electrical and electronic equipment, promoting the adoption of safer, halogen-free flame retardants. Compliance with these regulations is compelling industries to adopt non-toxic, halogen-free, and environmentally friendly flame retardants, further fueling market growth.
Expanding Electronics and Electric Vehicle (EV) Industry
The rapid expansion of the electronics and EV sectors is a significant driver of the inorganic flame retardants market. With the increasing demand for consumer electronics, lithium-ion batteries, and high-performance electrical components, the need for fire-resistant and thermally stable materials has surged. Electric vehicles, in particular, require effective flame retardants to ensure battery safety and reduce fire risks associated with thermal runaway. For instance, Tesla has implemented stringent fire safety measures in their vehicles, incorporating advanced flame retardants to mitigate fire risks. The shift toward lightweight and flame-retardant polymer materials in EVs and electronic devices is boosting demand for aluminum hydroxide (ATH), magnesium hydroxide (MDH), and antimony trioxide-based flame retardants.
Growing Demand for Eco-Friendly and Halogen-Free Flame Retardants
Rising environmental concerns and health risks associated with halogen-based flame retardants are prompting industries to transition toward sustainable and non-toxic alternatives. Inorganic flame retardants, such as ATH and MDH, provide excellent fire resistance without releasing harmful gases during combustion. For instance, BASF has developed eco-friendly flame retardants that meet the stringent environmental standards set by the European Chemicals Agency (ECHA). The increasing preference for low-smoke, non-corrosive, and recyclable materials is influencing manufacturers to develop eco-friendly flame-retardant solutions. The adoption of bio-based and recycled flame retardants aligns with global sustainability goals, driving innovation and creating new growth opportunities in the market.
Rising Industrial Applications and Infrastructure Development
The construction, automotive, and industrial sectors are witnessing a surge in demand for fire-resistant materials due to increasing infrastructure projects and stringent safety standards. Governments in emerging economies are investing in smart cities, residential buildings, and commercial complexes, reinforcing the demand for inorganic flame retardants in insulation, paints, and coatings. For instance, in India, the National Building Code (NBC) mandates the use of non-combustible materials in construction to enhance fire safety. Additionally, industries such as oil & gas, aerospace, and textiles require high-performance flame-retardant materials to enhance workplace safety and minimize fire risks. The integration of flame retardants into plastics, coatings, and textiles is further expanding the market’s application scope, ensuring long-term industry growth.
Market Trends:
Rising Demand for Halogen-Free Flame Retardants
The industry is witnessing a strong shift towards halogen-free flame retardants due to growing environmental concerns and stringent regulations on hazardous substances. Traditional halogenated retardants release toxic gases and harmful byproducts during combustion, leading industries to adopt eco-friendly alternatives such as aluminum hydroxide (ATH), magnesium hydroxide (MDH), and antimony trioxide. For instance, in 2024, Volvo Cars reported a significant surge in electrified vehicle sales, reflecting the company’s continued commitment to sustainable mobility. This trend aligns with increasing government policies promoting sustainable fire safety solutions, particularly in construction, electronics, and automotive applications.
Expanding Applications in Electric Vehicles and Electronics
With the rapid growth of electric vehicles (EVs) and consumer electronics, the demand for high-performance flame-retardant materials is accelerating. EV batteries, charging systems, and electronic circuits require flame-retardant components to enhance safety and prevent fire hazards. For instance, in June 2023, Avient launched halogen-free flame-retardant Thermoplastic Elastomer (TPE) grades made with sustainable raw materials for USB-C cable jackets. The increasing focus on lightweight, durable, and fire-resistant materials in automotive and electronics manufacturing is driving innovation in inorganic flame retardants, ensuring compliance with evolving safety standards.
Increased R&D for Advanced and Sustainable Solutions
Manufacturers are investing heavily in research and development (R&D) to improve the efficiency and sustainability of inorganic flame retardants. The industry is focusing on developing bio-based and recycled flame retardants, minimizing environmental impact while maintaining fire resistance. For instance, in July 2022, BASF and THOR GmbH combined their expertise to introduce non-halogenated flame retardance additives for plastic components or composites. Additionally, advancements in nano-engineered flame retardants are enhancing their performance by improving thermal stability and mechanical properties, making them more suitable for high-performance applications.
Growing Adoption in Infrastructure and Industrial Applications
The construction and industrial sectors are increasingly incorporating flame-retardant coatings, insulation, and plastics to meet stringent fire safety regulations. Expanding infrastructure projects, particularly in Asia-Pacific and the Middle East, are driving demand for high-performance inorganic flame retardants. For instance, in 2024, the United Nations Development Program’s (UNDP) Peoples’ Climate Vote survey highlighted the growing global awareness of environmental impact, with 80% of respondents advocating for stronger government action to address the climate crisis. Additionally, industries such as oil & gas, textiles, and aerospace are prioritizing fire-resistant materials, reinforcing market growth and technological advancements.
Market Challenges Analysis:
High Cost and Performance Limitations
One of the primary challenges in the inorganic flame retardants market is the high cost of production and raw materials. Compared to traditional halogen-based retardants, halogen-free inorganic flame retardants, such as aluminum hydroxide (ATH) and magnesium hydroxide (MDH), often require higher loading levels to achieve the desired fire resistance, which can impact material properties like mechanical strength, flexibility, and durability. This can limit their adoption in applications where maintaining structural integrity is crucial, such as automotive components and advanced electronics. Additionally, the processing complexity and compatibility issues with different polymers further add to the manufacturing costs, making it challenging for companies to balance performance, affordability, and sustainability.
Stringent Regulations and Environmental Concerns
While inorganic flame retardants are considered safer than their halogenated counterparts, regulatory restrictions on mining, processing, and waste management pose significant hurdles to market growth. Regulations such as REACH (Registration, Evaluation, Authorization, and Restriction of Chemicals) in Europe and EPA (Environmental Protection Agency) guidelines in the U.S. impose strict environmental and safety standards, affecting the supply chain and production scalability. Additionally, concerns regarding the long-term environmental impact of flame-retardant additives, including potential toxicity and disposal challenges, are prompting further research into bio-based and recyclable alternatives. Ensuring compliance with evolving fire safety and environmental standards while maintaining cost efficiency remains a critical challenge for manufacturers and end users alike.
Market Opportunities:
The inorganic flame retardants market is poised for significant growth due to increasing demand for eco-friendly and high-performance fire safety solutions across industries. The transition toward halogen-free and non-toxic flame retardants presents a major opportunity, as governments and regulatory bodies enforce stricter fire safety standards worldwide. Industries such as construction, automotive, electronics, and textiles are increasingly adopting aluminum hydroxide (ATH), magnesium hydroxide (MDH), and antimony trioxide-based retardants to meet sustainability and safety requirements. Additionally, the rising focus on bio-based and recyclable flame retardants is driving research and development, enabling manufacturers to innovate and introduce environmentally friendly alternatives that align with global sustainability goals.
Expanding industrial applications, particularly in electric vehicles (EVs), renewable energy, and aerospace, are further boosting market potential. The growing adoption of flame-retardant materials in EV batteries, circuit boards, and insulation components enhances fire safety and performance in next-generation transportation and electronics. Additionally, infrastructure development in emerging economies, particularly in Asia-Pacific and the Middle East, is increasing the demand for fire-resistant coatings, insulation, and building materials. The oil & gas, chemical processing, and industrial manufacturing sectors also present significant opportunities, as they require high-performance flame-retardant solutions to comply with stringent safety regulations. With continuous advancements in nanotechnology and material science, the market is set to benefit from innovative formulations that improve efficiency, durability, and environmental compliance, ensuring long-term growth and expansion.
Market Segmentation Analysis:
By Type
The inorganic flame retardants market is categorized into aluminum hydroxide (ATH), magnesium hydroxide (MDH), antimony trioxide, and boron compounds, each offering distinct fire-resistant properties. ATH and MDH lead the market due to their halogen-free composition, non-toxic nature, and excellent fire suppression capabilities. Antimony trioxide, often used in combination with other retardants, enhances smoke suppression and flame resistance, making it a critical additive in various industrial applications. Meanwhile, boron-based compounds are gaining attention for their thermal stability and eco-friendly characteristics, expanding their use in fire-resistant materials.
By Application
The market serves multiple industries, with the construction sector holding the largest share, driven by stringent fire safety regulations that mandate the use of flame-retardant coatings, insulation, and structural materials in residential and commercial buildings. The automotive industry is witnessing increasing demand, particularly with the rise of electric vehicles (EVs), where fire-resistant battery enclosures and interior components are essential for safety. The electronics sector also relies heavily on inorganic flame retardants for circuit boards, cables, and consumer devices, ensuring compliance with international fire safety standards. Additionally, the textile industry is experiencing growing adoption in protective clothing, home furnishings, and industrial applications. Industries such as oil & gas, aerospace, and manufacturing are integrating high-performance flame retardants to meet strict safety regulations, further expanding market opportunities and reinforcing the need for fire-resistant solutions across various sectors.
Segmentations:
By Type
- Aluminum Hydroxide (ATH)
- Magnesium Hydroxide (MDH)
- Antimony Trioxide
- Boron Compounds
- Others
By Application
- Construction
- Automotive
- Electronics
- Textiles
- Oil & Gas
- Aerospace
- Industrial Manufacturing
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a market share of 25%, driven by stringent fire safety regulations and environmental policies. The United States, Canada, and Mexico have well-established construction, automotive, and electronics industries, which contribute to the increasing demand for inorganic flame retardants. Regulatory frameworks such as the National Fire Protection Association (NFPA) standards and Environmental Protection Agency (EPA) guidelines mandate the use of fire-resistant materials, fostering market growth. The rising adoption of electric vehicles (EVs) and advanced electronics is further fueling the demand for halogen-free flame retardants, particularly aluminum hydroxide (ATH) and magnesium hydroxide (MDH). Additionally, the expansion of smart cities and green buildings is driving innovation in sustainable fire safety solutions, strengthening North America's position in the market.
Europe
Europe accounts for a market share of 30%, supported by strict environmental policies and increasing adoption of eco-friendly flame retardants. Countries such as Germany, the U.K., France, and Italy are major contributors to market growth due to their strong automotive, aerospace, and construction sectors. The Registration, Evaluation, Authorization, and Restriction of Chemicals (REACH) regulations promote the use of low-toxicity and halogen-free flame retardants, pushing manufacturers to invest in sustainable alternatives. The automotive industry, particularly the electric vehicle segment, is witnessing significant expansion, increasing the need for fire-resistant battery components and lightweight polymer materials. Additionally, the electronics sector in Europe is integrating flame-retardant materials into circuit boards, cables, and insulation, reinforcing the market’s growth trajectory.
Asia-Pacific
Asia-Pacific dominates the market with a market share of 40%, driven by rapid industrialization, infrastructure development, and high demand for consumer electronics. Countries such as China, India, Japan, and South Korea are at the forefront of market expansion, supported by increasing investments in construction, automotive, and electronics manufacturing. The region's booming real estate sector is driving the adoption of flame-retardant coatings, insulation, and plastics to meet fire safety standards. Additionally, the growing electric vehicle (EV) market, particularly in China and India, is accelerating demand for inorganic flame retardants in battery components, wiring, and vehicle interiors. Rising government initiatives promoting fire safety regulations and the expansion of manufacturing facilities further support market growth, solidifying Asia-Pacific’s leadership in the inorganic flame retardants market.
Key Player Analysis:
- Albemarle Corporation
- ICL Group Ltd.
- Clariant AG
- Nabaltec AG
- Lanxess AG
- Huber Engineered Materials
- BASF SE
- Italmatch Chemicals S.p.A.
- Kyowa Chemical Industry Co., Ltd.
- J.M. Huber Corporation
- Niknam Chemicals Pvt. Ltd.
- Chemische Fabrik Budenheim KG
Competitive Analysis:
The inorganic flame retardants market is highly competitive, with key players focusing on product innovation, sustainability, and regulatory compliance to strengthen their market presence. For instance, Albemarle Corporation has recently launched a new line of eco-friendly flame retardants that meet stringent European Union fire safety standards, showcasing their commitment to environmental responsibility and regulatory compliance. Albemarle Corporation is a leading player with a strong global footprint, offering advanced flame-retardant solutions tailored for various industries, including construction and automotive.
ICL Group Ltd. specializes in eco-friendly and halogen-free flame retardants, leveraging its expertise in chemical innovation and sustainable manufacturing. Clariant AG is recognized for its high-performance, non-toxic flame retardants, focusing on environmental safety and regulatory adherence. Nabaltec AG stands out for its specialized aluminum hydroxide (ATH) and magnesium hydroxide (MDH) offerings, catering to the growing demand for halogen-free solutions in multiple sectors.
Recent Developments:
- In December 2024, ICL Group Ltd. announced the launch of VeriQuel R100, an innovative, reactive phosphorus flame retardant designed for rigid polyurethane insulation products. This product offers a more sustainable alternative to traditional additive flame retardants, aligning with stricter global regulations on environmental safety.
- In November 2024, Clariant AG launched its next-generation melamine-free flame retardant, Exolit™ AP 422 A, providing superior fire resistance and meeting stringent safety and sustainability demands. This product addresses concerns surrounding melamine as a Substance of Very High Concern (SVHC) and provides safer usage in critical industries.
- In September 2023, Lanxess AG developed a non-halogen flame retardant primarily intended for use in glass fiber-reinforced polymers, which are used to make goods for the electronics and electrical industries.
Market Concentration & Characteristics:
The inorganic flame retardants market is moderately concentrated, with a mix of global leaders and specialized regional players driving innovation and market expansion. Albemarle Corporation, ICL Group Ltd., Clariant AG, and Nabaltec AG hold significant market shares, leveraging their strong R&D capabilities, advanced production technologies, and extensive distribution networks. The market is characterized by a growing preference for halogen-free and eco-friendly flame retardants, with increasing regulatory pressure shaping product development. Companies are focusing on strategic collaborations, mergers, and capacity expansion to strengthen their competitive position. The demand for high-performance materials in construction, automotive, and electronics sectors continues to influence market dynamics, with leading players investing in sustainable and high-efficiency formulations. As fire safety standards become more stringent, market leaders emphasize compliance-driven product innovation, ensuring long-term growth and technological advancements in fire-resistant materials.
Report Coverage:
The research report offers an in-depth analysis based on Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for halogen-free and eco-friendly inorganic flame retardants will continue to rise as regulatory bodies enforce stricter fire safety and environmental standards.
- Advancements in nanotechnology and material science will enhance the performance of flame retardants, improving their thermal stability and fire resistance.
- The expansion of electric vehicles (EVs) and renewable energy sectors will drive the need for high-performance flame-retardant materials in batteries, wiring, and insulation components.
- Infrastructure development in emerging economies will increase the adoption of fire-resistant coatings, insulation materials, and construction components.
- The electronics and semiconductor industries will experience significant growth, further boosting the demand for flame-retardant materials in circuit boards, cables, and enclosures.
- Manufacturers will invest in bio-based and recyclable flame retardants, aligning with global sustainability goals and reducing environmental impact.
- Strategic mergers, acquisitions, and partnerships will shape market dynamics as key players expand their product portfolios and geographic reach.
- The rise in workplace safety regulations across industries such as oil & gas, aerospace, and manufacturing will create new opportunities for advanced fire-resistant solutions.
- Increasing research and development (R&D) investments will lead to cost-effective, high-performance formulations, making inorganic flame retardants more competitive.
- Global supply chain optimization and capacity expansion will be crucial for meeting rising market demand and ensuring stable product availability.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Fire Safety Regulations and Compliance Requirements
Governments and regulatory bodies are enforcing strict fire safety standards across industries such as construction, automotive, and electronics, compelling the adoption of inorganic flame retardants to meet compliance and reduce fire hazards.
Expanding Electronics and Electric Vehicle (EV) Industry
The rapid growth of the electronics and EV sectors is increasing the need for fire-resistant and thermally stable materials, driving demand for inorganic flame retardants in batteries, circuit boards, and wiring systems.
Growing Demand for Eco-Friendly and Halogen-Free Flame Retardants
Environmental concerns and health risks associated with halogen-based retardants are pushing industries toward sustainable, non-toxic alternatives like ATH and MDH, which offer fire resistance without releasing harmful gases.
Rising Industrial Applications and Infrastructure Development
Increasing infrastructure projects and industrial expansion, especially in emerging economies, are boosting the use of flame-retardant coatings, insulation, and plastics in construction, oil & gas, and manufacturing sectors.
Increased R&D for Advanced and Sustainable Solutions
Manufacturers are investing in research and development to create bio-based, recyclable, and high-efficiency flame retardants, enabling innovation and supporting the market’s shift toward sustainability and regulatory compliance.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the inorganic flame retardants market?
What are the key drivers of market growth?
Which industries are major consumers of inorganic flame retardants?
Which regions dominate the inorganic flame retardants market?
What are the emerging trends in the market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Aluminum Hydroxide (ATH)
- 1.2.2 Magnesium Hydroxide (MDH)
- 1.2.3 Antimony Trioxide
- 1.2.4 Boron Compounds
- 1.2.5 Others
- 1.3 By Application
- 1.3.1 Construction
- 1.3.2 Automotive
- 1.3.3 Electronics
- 1.3.4 Textiles
- 1.3.5 Oil & Gas
- 1.3.6 Aerospace
- 1.3.7 Industrial Manufacturing
- 1.3.8 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 10,575 million → 2032: USD 18,720.37 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Inorganic Flame Retardants Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Inorganic Flame Retardants Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Inorganic Flame Retardants Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Inorganic Flame Retardants Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Inorganic Flame Retardants Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Inorganic Flame Retardants Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Inorganic Flame Retardants Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Inorganic Flame Retardants Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 10,575 million → 2032: USD 18,720.37 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Inorganic Flame Retardants Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Aluminum Hydroxide (ATH)
- 12.3.7.2 Magnesium Hydroxide (MDH)
- 12.3.7.3 Antimony Trioxide
- 12.3.7.4 Boron Compounds
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Construction
- 12.4.7.2 Automotive
- 12.4.7.3 Electronics
- 12.4.7.4 Textiles
- 12.4.7.5 Oil & Gas
- 12.4.7.6 Aerospace
- 12.4.7.7 Industrial Manufacturing
- 12.4.7.8 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Inorganic Flame Retardants End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Inorganic Flame Retardants Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Inorganic Flame Retardants Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Inorganic Flame Retardants Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Albemarle Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 ICL Group Ltd.
- 18.4 Clariant AG
- 18.5 Nabaltec AG
- 18.6 Lanxess AG
- 18.7 Huber Engineered Materials
- 18.8 BASF SE
- 18.9 Italmatch Chemicals S.p.A.
- 18.10 Kyowa Chemical Industry Co., Ltd.
- 18.11 J.M. Huber Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

