
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
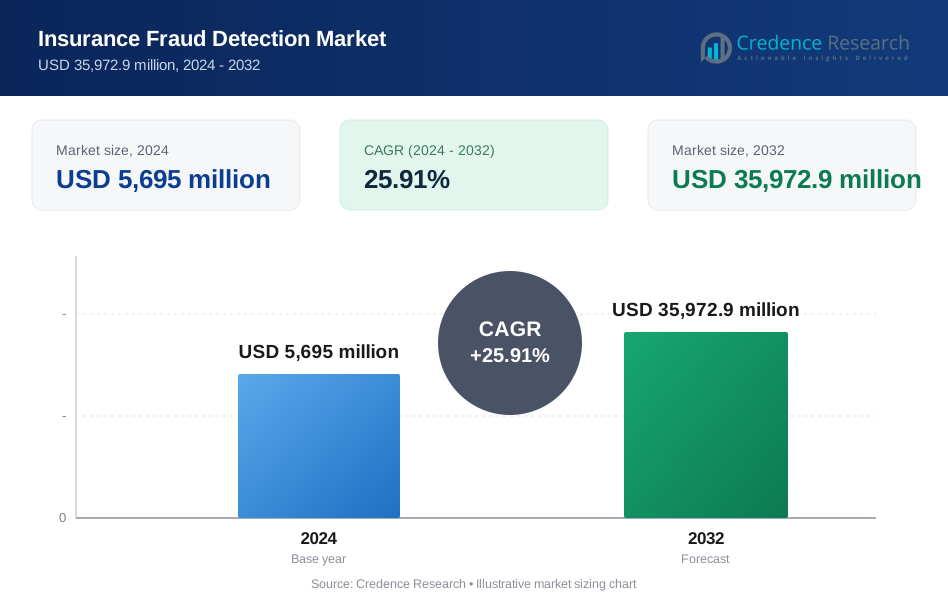
| Insurance Fraud Detection Market Size 2024 | USD 5,695 Million |
| Insurance Fraud Detection Market, CAGR | 25.91% |
| Insurance Fraud Detection Market Size 2032 | USD 35,972.9 Million |
Market Overview
The Insurance Fraud Detection Market is projected to grow from USD 5,695 million in 2024 to USD 35,972.9 million by 2032, reflecting a robust compound annual growth rate (CAGR) of 25.91%.
The insurance fraud detection market is driven by the increasing adoption of advanced technologies like AI, machine learning, and big data analytics to enhance fraud detection capabilities. Rising insurance claims fraud, coupled with the growing need for improved operational efficiency, propels market demand. The shift towards automation and the integration of predictive analytics are key trends, enabling insurers to detect fraudulent activities more proactively. Additionally, stricter regulatory requirements and the rising awareness of the financial impact of fraud are further accelerating the adoption of fraud detection solutions across the global insurance sector.
The Insurance Fraud Detection market is experiencing significant growth across various regions, driven by increasing fraud cases and the adoption of advanced technologies. North America leads the market, with robust technological infrastructure and high demand for fraud detection solutions in sectors like BFSI and healthcare. Europe follows closely, with stringent regulations promoting the use of fraud detection systems. Key players in the market include SAS Institute Inc., IBM, FICO, Oracle, LexisNexis Risk Solutions, Capgemini, and BAE Systems, who offer innovative solutions like fraud analytics, authentication, and governance, helping insurers mitigate risks effectively.
Market Drivers
Rising Insurance Fraud
The growing complexity of fraud schemes is a key driver in the need for enhanced fraud detection solutions. For instance, the Coalition Against Insurance Fraud reports that an estimated 20% of insurance claims are fraudulent. Furthermore, the globalization of insurance markets has opened up new avenues for fraud, as international borders provide additional opportunities for fraudulent claims. Additionally, while digital transformation has streamlined many processes, it has also created new risks, including cyberattacks and data breaches, which contribute to the rising number of fraudulent claims.
Regulatory Compliance
Governments worldwide are imposing stricter regulations on insurance companies to curb fraud and protect consumers, further driving the demand for robust fraud detection mechanisms. For instance, the General Data Protection Regulation (GDPR) and the California Consumer Privacy Act (CCPA) require insurers to implement stringent measures to safeguard sensitive customer data. These regulations require insurers to implement stringent measures to safeguard sensitive customer data and ensure that fraud prevention processes align with legal requirements, creating a need for more comprehensive solutions.
Advanced Technologies
The integration of artificial intelligence (AI) and machine learning (ML) in fraud detection is revolutionizing the insurance industry. Big data analytics further enhances this capability by enabling insurers to process large volumes of data, uncover hidden trends, and predict risks. Additionally, blockchain technology improves transparency, security, and traceability in insurance transactions, helping insurers reduce the likelihood of fraud and increasing trust in the system.
Cost Reduction and Efficiency
Effective fraud detection plays a crucial role in reducing claims costs for insurers. By identifying and preventing fraudulent claims early, insurers can significantly lower their payout costs. Automated fraud detection systems streamline operations and reduce the need for manual intervention, improving overall operational efficiency. This combination of cost savings and enhanced efficiency not only boosts profitability but also ensures insurers can focus resources on legitimate claims, benefiting both the company and its customers.
Market Trends
Rising Sophistication of Fraud Schemes and Regulatory Pressures
The increasing sophistication of fraud schemes is a significant trend in the insurance fraud detection market. Fraudsters are now employing more complex techniques to deceive insurers, making detection more challenging. The growing reliance on digital platforms has further exacerbated this issue, as cyberattacks, identity theft, and online fraud have become more prevalent. Additionally, the globalization of insurance markets has increased the risk of cross-border fraud, making it harder for insurers to detect fraudulent activities that span multiple regions. Governments worldwide are responding to this threat by imposing stricter regulations on insurance companies, emphasizing the need for robust fraud detection mechanisms. Compliance with data privacy laws such as GDPR and CCPA is becoming a key concern, with insurers required to safeguard sensitive information and ensure that fraud prevention processes comply with legal standards.
Technological Advancements and Focus on Operational Efficiency
Advancements in technology are driving the evolution of insurance fraud detection. For instance, AI and ML algorithms can analyze vast datasets to identify patterns and anomalies indicative of fraudulent activity. Big data analytics further enhances fraud detection capabilities by uncovering hidden trends and risks that may otherwise go unnoticed. Blockchain technology is also gaining traction in the insurance industry, offering enhanced transparency, security, and traceability in transactions, thereby reducing the likelihood of fraud. These technological innovations are not only helping insurers identify fraudulent claims but also improving operational efficiency. Real-time fraud detection systems are being implemented to stop fraudulent claims before they are processed, while predictive analytics allows insurers to identify potential fraudsters and high-risk claims more proactively. Additionally, the focus on customer experience is evident as insurers aim to expedite claims processing and reduce costs, ensuring a faster, more efficient service for legitimate customers. To support these advancements, insurers are increasingly partnering with technology providers, leveraging cloud-based solutions that offer scalability, flexibility, and cost-effectiveness.
Market Challenges Analysis
Challenges with Data Quality and Privacy Constraints
One of the key challenges in insurance fraud detection is managing data quality and availability. For instance, a study by BMC Medical Informatics highlights that analyzing extensive healthcare data is hindered by complexity, data quality issues, and the need for real-time detection. Inconsistent, incomplete, or low-quality data from multiple sources can significantly hinder accurate analysis, making it difficult for insurers to detect fraudulent activity effectively. Additionally, the implementation of stringent data privacy regulations such as GDPR and CCPA limits the access and sharing of data, further complicating the task of building comprehensive datasets for fraud detection. These regulations restrict the ability to pool valuable data across platforms, preventing insurers from gaining a broader perspective on potential fraud risks and hindering the creation of more effective, holistic fraud detection models.
Technological and Workforce Barriers in Fraud Detection
As fraudsters continuously evolve their techniques to bypass detection systems, insurers face mounting challenges in keeping up with these increasingly sophisticated fraud schemes. For instance, the rise of organized crime syndicates involved in insurance fraud further complicates efforts, requiring more advanced, coordinated fraud detection strategies. At the same time, insurers face significant hurdles in balancing accuracy in fraud detection. False positives, where legitimate claims are incorrectly flagged, can damage customer relationships and cause operational inefficiencies. On the other hand, false negatives, where fraudulent claims are missed, can lead to substantial financial losses. Furthermore, technological limitations present additional barriers, as developing accurate AI and ML models requires considerable expertise, and these advanced systems can be computationally expensive, especially when processing large datasets. Compounding these challenges is a shortage of skilled professionals in the field of data science, machine learning, and fraud investigation. Attracting and retaining top talent to address these complex issues has become increasingly difficult, given the high demand and competition for skilled professionals in fraud detection roles.
Market Segmentation Analysis:
By Component:
The Insurance Fraud Detection market is segmented into solutions and services, both crucial for preventing fraudulent activities. Fraud Analytics stands out as a key solution, leveraging advanced data analysis techniques such as machine learning and artificial intelligence (AI) to identify suspicious patterns and anomalies in insurance claims. Authentication solutions are also essential, ensuring that only authorized users can access sensitive data, thus preventing identity theft and unauthorized claims. The Governance, Risk, and Compliance (GRC) solutions help insurers meet regulatory requirements while managing the risks associated with fraud. Other specialized solutions are also in demand, tailored to specific fraud scenarios. In addition to solutions, services such as fraud detection consulting, system integration, and support services enable insurers to implement and maintain effective fraud prevention systems, ensuring optimal performance and compliance.
By Application:
The market is further segmented by application, addressing different aspects of insurance fraud. Claims Fraud remains the most significant application, with insurers using fraud detection technologies to uncover false or exaggerated claims, thereby protecting their bottom line. Identity Theft is also a growing concern, as fraudsters gain unauthorized access to personal data and make fraudulent claims under false identities. Payment and Billing Fraud is another major application, with insurers deploying detection tools to identify fraudulent payment activities, ensuring that billing practices remain legitimate. Money Laundering is a critical concern in the insurance sector, where fraudsters may use insurance policies to launder illicit funds. In response, insurers are adopting anti-money laundering (AML) technologies to detect suspicious financial transactions and maintain compliance with global regulations. Each of these applications requires targeted fraud detection strategies, highlighting the diverse needs within the market.
Segments:
Based on Component:
- Solutions
- Fraud Analytics
- Authentication
- Governance, Risk, and Compliance (GRC)
- Other Solutions
- Services
Based on Application:
- Claims Fraud
- Identity Theft
- Payment and Billing Fraud
- Money Laundering
Based on End-User Industry:
- Automotive
- BFSI (Banking, Financial Services, and Insurance)
- Healthcare
- Retail
- Other End-User Industries
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds the largest market share in the global insurance fraud detection market, accounting for approximately 40% of the total market. The region benefits from a highly developed insurance sector, with significant investments in advanced fraud detection technologies, including AI, machine learning, and data analytics. The growing sophistication of fraud schemes, along with strict regulatory frameworks such as the Health Insurance Portability and Accountability Act (HIPAA) and General Data Protection Regulation (GDPR) in the U.S. and Canada, has driven insurers to adopt more robust fraud detection solutions. The demand for real-time fraud detection systems and predictive analytics is rising, especially within industries such as banking, financial services, and insurance (BFSI), where fraud is prevalent. Moreover, the increasing use of digital platforms and online transactions in the region has exposed insurers to a higher risk of digital fraud, prompting the adoption of comprehensive fraud management systems. North America’s strong technological infrastructure and collaborative efforts between insurers and technology providers make it a key player in the global market.
Europe
Europe holds the second-largest share of the insurance fraud detection market, contributing to around 30% of the total market share. The region is experiencing rapid adoption of advanced fraud detection solutions, driven by stringent regulatory measures like the European Union's Anti-Money Laundering Directive (AMLD) and General Data Protection Regulation (GDPR), which mandate strong fraud prevention systems. European insurers are increasingly relying on AI, machine learning, and big data analytics to identify fraudulent patterns and prevent financial losses. Countries such as the UK, Germany, and France are at the forefront of adopting insurance fraud detection technologies, with a particular focus on combating claims fraud, payment fraud, and money laundering activities. The growing complexity of fraud techniques, along with the expansion of digital insurance platforms, has led to an increasing need for real-time monitoring systems and predictive fraud analytics in the region. With Europe’s advanced technological landscape and regulatory environment, the market is expected to continue expanding, presenting numerous opportunities for growth in the coming years.
Key Player Analysis
- SAS Institute Inc.
- Oracle
- Experian Information Solutions, Inc.
- IBM
- Capgemini
- FICO
- BAE Systems
- LexisNexis Risk Solutions
- DXC Technology Company
- FRISS
Competitive Analysis
The Insurance Fraud Detection market is highly competitive, with several leading players offering advanced solutions to combat fraud. Companies like SAS Institute Inc., IBM, FICO, LexisNexis Risk Solutions, Oracle, Capgemini, DXC Technology Company, FRISS, BAE Systems, and Experian Information Solutions, Inc. are at the forefront. Companies are focusing on leveraging advanced technologies such as artificial intelligence (AI), machine learning (ML), and big data analytics to enhance fraud detection capabilities. These solutions aim to address various types of fraud, including claims fraud, identity theft, payment fraud, and money laundering. The market is characterized by a mix of specialized fraud detection providers and larger technology firms expanding their portfolios with fraud prevention services. In response to evolving fraud schemes, these players continually innovate and collaborate with industry stakeholders, striving to offer scalable and flexible solutions that meet regulatory requirements and improve operational efficiency.
Recent Developments
- In May 2024, Solutis, a Brazilian technology organization, announced a strategic partnership with FICO. The collaboration is focused on assisting medium-sized banks and insurance businesses in avoiding fraud and major losses, promoting financial inclusion, and streamlining additional business decisions.
- In June 2024, ForMotiv, one of the prominent companies in behavioral data science solutions, and FRISS, a preferred partner of multiple insurance industry participants for trust automation solutions, joined forces to offer new insights regarding intent and applicant behaviors, to enhance fraud detection capabilities and risk assessment processes of organizations. Predictive AI models by FRISS and behavioral analytics by ForMotiv are expected to assist insurers to improve their ability to identify potential frauds while attaining greater accuracy and efficiency.
- In May 2023, Insurance data analytics provider Verisk partnered with CCC Intelligent Solutions, a cloud platform for the P&C insurance market, to address the risk of insurance fraud. The partnership will integrate Verisk's claims fraud detection analytics with CCC's claims platform.
- In March 2023, Shift Technology, a provider of AI-driven decision automation and optimization solutions for the global insurance industry, introduced the General Insurance Association of Singapore (GIA), which will be extending its usage of Shift Claims Fraud Detection on behalf of its member insurers. This strategic expansion builds on the successes of the GIA Fraud Management System (FMS) and will assist travel insurance fraud. This planned expansion allows them to maximize the potential of the travel module and comes at an opportune time to increase global travel. The collaboration with Shift gives them an important way to detect and manage fraudulent claims at scale. It also augments their sector's existing fraud detection and management efforts.
Market Concentration & Characteristics
The Insurance Fraud Detection market is moderately concentrated, with a mix of established players and emerging companies driving innovation. Large technology firms, including those with a strong presence in AI, machine learning, and data analytics, dominate the market, leveraging their expertise to provide comprehensive fraud detection solutions. These companies typically offer a wide range of solutions, such as fraud analytics, authentication, and governance, risk, and compliance (GRC) services, catering to diverse industries like healthcare, automotive, and BFSI. Smaller specialized firms focus on niche areas, offering tailored solutions for specific fraud types such as claims fraud or identity theft. The market is highly competitive, with players consistently upgrading their technologies and methodologies to keep pace with the evolving tactics of fraudsters. Partnerships between insurers, technology providers, and data analytics firms are common, as collaboration becomes crucial for addressing complex fraud challenges in an increasingly digital landscape.
Report Coverage
The research report offers an in-depth analysis based on Component, Application, End-User Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Insurance Fraud Detection market is expected to experience significant growth due to increasing fraud incidents and the demand for advanced solutions.
- AI and machine learning will continue to play a pivotal role in identifying complex fraud patterns and improving detection accuracy.
- Integration of blockchain technology is anticipated to enhance transparency and security in insurance transactions, reducing fraud risks.
- Real-time fraud detection systems will become increasingly critical for insurers to prevent fraudulent claims before they are processed.
- The rise of digital platforms will lead to greater focus on detecting online fraud, including identity theft and cyberattacks.
- Regulatory pressures will drive insurers to adopt more robust fraud detection measures to comply with global data privacy laws.
- Cloud-based solutions will gain traction, offering insurers scalability, cost-effectiveness, and improved fraud prevention capabilities.
- Increased collaboration between insurance companies and technology providers will foster the development of more sophisticated fraud detection tools.
- Predictive analytics will help insurers identify high-risk claims and potential fraudsters, leading to proactive fraud management strategies.
- The growing use of social media monitoring will assist in identifying fraudulent behavior and suspicious activities related to insurance claims.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Insurance Fraud Detection Market?
What factors are driving the growth of the Insurance Fraud Detection Market?
What are the key segments within the Insurance Fraud Detection Market?
What are some challenges faced by the Insurance Fraud Detection Market?
Who are the major players in the Insurance Fraud Detection Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Insurance Fraud Detection Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Insurance Fraud Detection Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 5,695 million → 2032: USD 35,972.9 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Insurance Fraud Detection Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Insurance Fraud Detection Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Insurance Fraud Detection Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Insurance Fraud Detection Market Drivers
- 3.3 Insurance Fraud Detection Market Restraints & Challenges
- 3.4 Insurance Fraud Detection Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Insurance Fraud Detection Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Insurance Fraud Detection Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Insurance Fraud Detection category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Insurance Fraud Detection Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Insurance Fraud Detection Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Insurance Fraud Detection. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Insurance Fraud Detection Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Insurance Fraud Detection Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Insurance Fraud Detection Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Insurance Fraud Detection (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Insurance Fraud Detection
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Insurance Fraud Detection Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Insurance Fraud Detection Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Insurance Fraud Detection Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Insurance Fraud Detection Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Insurance Fraud Detection Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Insurance Fraud Detection Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Insurance Fraud Detection Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Insurance Fraud Detection Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
