
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
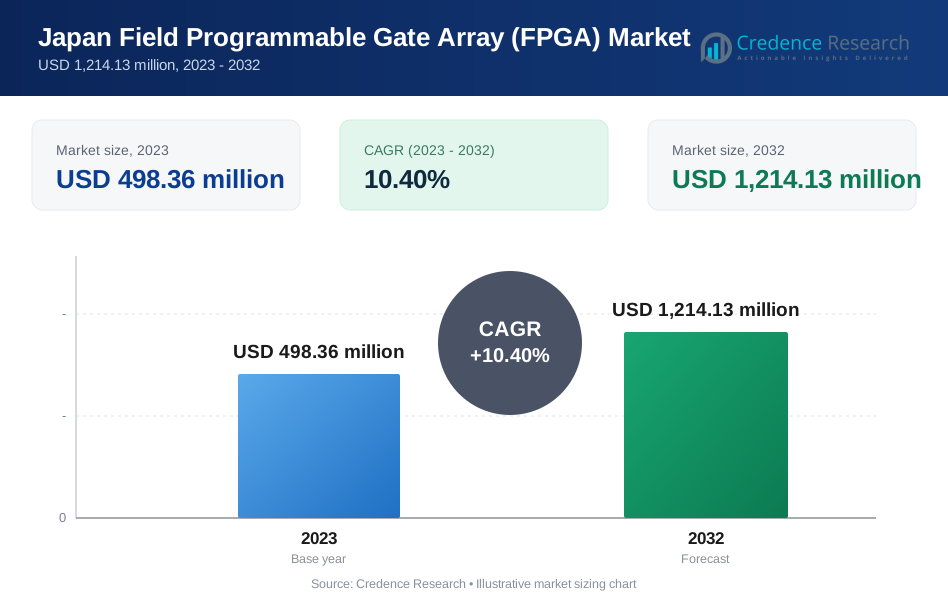
| Japan Field Programmable Gate Array (FPGA) Market Size 2023 | USD 498.36 Million |
| Japan Field Programmable Gate Array (FPGA) Market, CAGR | 10.40% |
| Japan Field Programmable Gate Array (FPGA) Market Size 2032 | USD 1,214.13 Million |
Market Overview
The Japan Field Programmable Gate Array (FPGA) Market is projected to grow from USD 498.36 million in 2023 to USD 1,214.13 million by 2032, reflecting a compound annual growth rate (CAGR) of 10.40%.
The Japan Field Programmable Gate Array (FPGA) Market is experiencing robust growth, driven by the increasing demand for high-speed data processing and the widespread adoption of FPGAs in telecommunications and automotive industries. Key trends include the integration of AI and machine learning capabilities, which are expanding FPGA applications in smart devices and IoT ecosystems. Additionally, advancements in FPGA technology that enhance power efficiency and processing capabilities are further stimulating market expansion. These factors, coupled with Japan’s strong focus on technological innovation, are setting a dynamic pace for the FPGA market's growth in the region.
The Japan Field Programmable Gate Array (FPGA) Market is a vital part of the Asia-Pacific region, driven by the country's strong focus on technological innovation and advanced manufacturing capabilities. Key players such as Intel Corporation, Xilinx, Inc., and Lattice Semiconductor Corporation dominate the market, leveraging Japan's robust electronics and automotive sectors. These companies are instrumental in deploying cutting-edge FPGA solutions across various industries, from consumer electronics to automotive and industrial applications. Japan’s strategic emphasis on integrating FPGAs into 5G infrastructure and smart technologies further enhances its position in the global FPGA landscape.
Market Drivers
Advancements in the Automotive Industry
The automotive sector in Japan is embracing Field Programmable Gate Arrays (FPGAs) to enhance the capabilities of Advanced Driver Assistance Systems (ADAS). For instance, Japanese automakers are aggressively investing in and studying new developments in electric cars (EVs), hydrogen fuel cell technology, and even autonomous driving systems. As autonomous driving technologies evolve, the need for high-performance computing to process sensor data and execute complex algorithms is increasing. FPGAs provide the necessary flexibility and efficiency for real-time processing within these systems. Additionally, the rising popularity of electric vehicles (EVs) supports the expanded use of FPGAs in managing critical functions such as powertrain control and battery management systems, aligning with the industry’s push towards more innovative and sustainable automotive solutions.
Integration in Consumer Electronics and Industrial Automation
In consumer electronics, FPGAs are integral to improving image and video processing capabilities in devices such as cameras, smartphones, and televisions. For instance, throughout 2023, the industry has witnessed shifts in consumer preferences post-pandemic, the remarkable ascent of generative AI, and increased integration of the connected world and internet of things (IoT).They enhance content quality through advanced compression and enhancement techniques. For gaming consoles, FPGAs provide additional processing power, enriching gaming experiences with superior performance and new features. In industrial settings, FPGAs facilitate the automation of processes in robotics and factory systems, improving precision in tasks like motion control and real-time decision-making, thereby driving efficiency and productivity in manufacturing operations.
Enhanced Capabilities in 5G Infrastructure
In the realm of 5G infrastructure, FPGAs play a pivotal role by enabling high-speed data transmission essential for modern telecommunications. They facilitate the implementation of software-defined networking (SDN) and network function virtualization (NFV), which are crucial for creating flexible and scalable network architectures. Furthermore, the massive proliferation of IoT devices across industries necessitates efficient data processing and management, areas where FPGAs excel due to their ability to rapidly handle complex computations and support vast networks of connected devices.
High-Performance Computing (HPC) Applications
FPGAs are increasingly utilized in high-performance computing (HPC) to accelerate artificial intelligence (AI) and machine learning (ML) applications. These applications benefit from FPGAs' ability to perform parallel processing and adapt to custom hardware configurations, thus enhancing efficiency and processing power. Additionally, in scientific computing, FPGAs contribute to faster and more precise simulations and modeling in critical fields such as physics, chemistry, and engineering, enabling researchers to achieve more accurate results with reduced computational time.
Market Trends
Integration and Advancements in Automotive and 5G Technologies
The Japan FPGA market is witnessing a significant surge in demand within the automotive sector, notably in the realms of Advanced Driver Assistance Systems (ADAS) and autonomous driving technologies. For instance, in the realm of automotive technologies, FPGAs are being utilized in Japan for fine-tuned motor control, power conversion, and inverters in electric vehicles, thereby optimizing power and efficiency to extend the range of the vehicle. FPGAs are increasingly favored for their ability to efficiently manage real-time processing of extensive sensor data and complex algorithms, a necessity in modern automotive designs. Additionally, the rising popularity of electric vehicles (EVs) is further amplifying the demand for FPGAs to optimize powertrain control, battery management, and other essential systems, marking a pivotal shift towards more electrified transportation options. Concurrently, the development of 5G infrastructure is accelerating the adoption of FPGAs, particularly through their applications in software-defined networking (SDN) and network function virtualization (NFV). These technologies are crucial for establishing flexible and scalable network architectures needed to support the expansive growth of IoT devices, ensuring efficient data management across increasingly complex network environments.
Expansion in High-Performance Computing and Enhanced Power Efficiency
In high-performance computing (HPC), FPGAs are becoming indispensable for accelerating AI and machine learning algorithms that require parallel processing and customized hardware setups, thereby enhancing computational efficiencies and capabilities in data-intensive fields such as AI research and scientific computing. Moreover, FPGAs are increasingly integrated with other technologies to form comprehensive system-on-chip (SoC) solutions, combining CPUs, GPUs, and other critical components on a single chip, which optimizes performance across various applications. This integration supports heterogeneous computing systems that effectively allocate computational tasks to the most suitable hardware components, optimizing performance for diverse workloads. Additionally, there is a growing emphasis on developing energy-efficient FPGA designs and implementing advanced power management techniques. These advancements are crucial in meeting the increasing demand for low-power consumption in mobile and IoT applications, aligning with global trends towards sustainability and longer battery life in electronic devices. These trends, combined with the introduction of new FPGA architectures and the entry of innovative players, are driving a competitive and dynamic market landscape.
Market Challenges Analysis
Financial and Technical Barriers in FPGA Implementation
The implementation of FPGA technology in the Japan market encounters significant financial challenges, primarily due to the high costs associated with designing and developing FPGA-based systems. For instance, FPGA-based systems must comply with standards such as ISO 13485, IEC 62304, and FDA guidelines to facilitate approval and market entry. These systems, particularly in complex applications, require substantial investment not only in hardware but also in sophisticated toolchains and software, which can be prohibitively expensive. This financial barrier restricts access for smaller companies and individual innovators who might lack the capital to invest in such advanced technology. Moreover, the inherent complexity of FPGA design and programming adds another layer of challenge. There is a steep learning curve involved for engineers, particularly for those without prior experience in FPGA technology. While design tools for FPGAs have evolved over time, they remain complex and time-consuming to master, potentially slowing down development processes and increasing time-to-market for new technologies and products.
Operational Challenges and Market Dynamics
Operational challenges such as power consumption and thermal management further complicate the deployment of FPGAs. These devices can consume substantial energy, particularly in high-performance applications, posing challenges in battery-powered devices or environments with limited power availability. Additionally, managing the heat generated by densely packed FPGA systems is crucial; inadequate thermal management can lead to performance degradation or failures, impacting the reliability of critical applications. Supply chain constraints also pose significant hurdles, with a limited number of suppliers leading to potential delays and price fluctuations due to long lead times for custom devices. Furthermore, the competition from alternative technologies like ASICs, which offer higher performance and lower power consumption, and GPUs, favored for AI and ML workloads, pressures the FPGA market. Regulatory and standards compliance for safety, reliability, and security in critical applications, such as automotive and IoT, adds another layer of complexity, requiring rigorous design and validation processes to meet stringent industry standards, thus impacting the adoption and innovation pace within the FPGA landscape.
Market Segmentation Analysis:
By Type:
The Japan Field Programmable Gate Array (FPGA) Market is segmented into low-end, mid-range, and high-end categories. Low-end FPGAs are popular in cost-sensitive applications, providing sufficient performance for basic tasks in consumer electronics and smaller industrial applications. Mid-range FPGAs, which offer a balance of performance and cost, are increasingly adopted in sectors such as automotive and telecommunications, where moderate complexity and flexibility are required. High-end FPGAs dominate segments that demand the highest performance levels, such as in data centers, advanced automotive systems, and cutting-edge industrial automation. These high-end solutions are crucial for handling intensive processing tasks, including real-time data analytics, AI, and machine learning applications. The increasing need for more powerful and efficient FPGAs to support emerging technologies is driving growth across all three segments, with high-end FPGAs expected to see the most significant expansion due to their critical role in advanced computing applications.
By Application:
In terms of application, the Japan FPGA market spans various industries, including consumer electronics, automotive, industrial, military, and aerospace. Consumer electronics represent a substantial segment, utilizing FPGAs for image processing, signal conversion, and enhancing multimedia capabilities in devices such as smartphones and televisions. The automotive sector is another major application area, employing FPGAs for advanced driver assistance systems (ADAS), autonomous driving features, and electric vehicle powertrain management. Industrial applications involve the use of FPGAs for process control, automation, and robotics, enhancing efficiency and precision. In the military and aerospace sectors, FPGAs are valued for their reliability and ability to handle complex data processing tasks in radar systems, communication, and electronic warfare. The versatility of FPGAs, along with their adaptability to various application requirements, ensures their continued relevance and expansion across these diverse industries, catering to Japan's advanced technological needs.
Segments:
Based on Type:
- Low-End
- Mid-Range
- High-End
Based on Application:
- Consumer Electronics
- Automotive
- Industrial
- Military & Aerospace
- Others
Based on Technology:
- SRAM
- EEPROM
- Antifuse
- Flash
- Others
Based on the Region:
- Kanto region
- Chubu region
- Kansai region
- Kyushu region
- Kinki region
- Tohoku
- Chugoku
- Shikoku
Regional Analysis
Kanto region
The Kanto region, which includes Tokyo and its surrounding prefectures, holds the largest market share at approximately 45% of Japan's FPGA market value. This dominance is largely attributed to the high concentration of electronics manufacturers, telecommunications companies, and research institutions in the area. Tokyo, as the nation's technological hub, drives significant demand for FPGAs in various applications, including 5G infrastructure, artificial intelligence, and data centers. The region's focus on cutting-edge technologies and digital transformation initiatives further fuels the growth of the FPGA market. Additionally, the presence of major semiconductor companies and their research facilities in Kanto contributes to continuous innovation and adoption of advanced FPGA technologies, solidifying the region's leading position in the market.
Kinki region
The Kinki region, centered around Osaka and encompassing several prefectures in western Japan, accounts for about 30% of the country's FPGA market share. This region's significant market presence is driven by its strong industrial base, particularly in the automotive, robotics, and industrial automation sectors. Kinki's emphasis on smart manufacturing and Industry 4.0 initiatives creates a substantial demand for FPGAs in programmable logic devices and embedded systems. The region also benefits from its concentration of consumer electronics manufacturers, who increasingly incorporate FPGAs into their products for enhanced performance and flexibility. Furthermore, Kinki's growing focus on renewable energy and smart grid technologies contributes to the expanding use of FPGAs in power management and control systems. The collaboration between industry and academia in this region also plays a crucial role in driving innovation and adoption of FPGA technologies across various sectors, further strengthening Kinki's position in Japan's FPGA market landscape.
Key Player Analysis
- Intel Corporation
- Xilinx, Inc.
- Qualcomm Technologies, Inc.
- NVIDIA Corporation
- Broadcom
- Quicklogic Corporation
- Lattice Semiconductor Corporation
- Achronix Semiconductor Corporation
- Microchip Technology Inc.
Competitive Analysis
In the Japan Field Programmable Gate Array (FPGA) Market, leading players such as Intel Corporation, Xilinx, Inc., Qualcomm Technologies, Inc., NVIDIA Corporation, Broadcom, Quicklogic Corporation, Lattice Semiconductor Corporation, Achronix Semiconductor Corporation, and Microchip Technology Inc. dominate the competitive landscape. These companies drive the market by offering a wide range of FPGA solutions tailored to meet the specific needs of industries like automotive, telecommunications, and consumer electronics. Their strong focus on research and development enables them to introduce advanced products with higher performance, efficiency, and integration capabilities. Strategic partnerships and collaborations with Japanese electronics and automotive giants further strengthen their market positions, enabling them to deliver customized solutions and enhance local customer support. Additionally, the ability of these companies to scale production and maintain supply chain reliability gives them a competitive edge, ensuring they can meet the growing demand for FPGAs in various high-tech applications across Japan.
Recent Developments
- In February 2024, Qualcomm unveiled the Snapdragon X80 5G Modem-RF System, a new 5G modem with fully integrated NB-NTN satellite communications support.
- In 2024, NVIDIA announced its role in developing Japan’s generative AI infrastructure.
- In June 2024, Lattice introduced new logic-optimized Lattice Certus™-NX FPGA devices to its small FPGA portfolio.
- In June 2024, Intel collaborated with Japan’s Sharp and 14 other Japanese companies to use Sharp’s underutilized LCD plants in Japan for researching advanced semiconductor production technology.
- In December 2023, QuickLogic’s CEO was invited to speak at the International Conference on Field Programmable Technology (FPT’23) in Yokohama, Japan.
Market Concentration & Characteristics
The Japan Field Programmable Gate Array (FPGA) Market is characterized by moderate to high market concentration, with a few key players holding significant market shares. Companies such as Intel Corporation, Xilinx, Inc., and Lattice Semiconductor Corporation lead the market due to their extensive product portfolios, technological expertise, and strong R&D capabilities. These players are pivotal in driving innovation and setting industry standards, leveraging their resources to develop high-performance, low-power, and scalable FPGA solutions tailored for diverse applications. The market is marked by a focus on advanced technology integration, including AI, machine learning, and 5G infrastructure, aligning with Japan’s broader technological objectives. Additionally, the presence of established semiconductor manufacturing facilities in Japan supports the high-quality production and supply of FPGAs. Strategic alliances and collaborations with local tech firms further enhance market dynamics, ensuring that the leading players maintain a dominant position while fostering innovation and meeting the evolving needs of the industry.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Technology and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for FPGAs will continue to rise, driven by advancements in AI and machine learning applications.
- Increased adoption of autonomous driving technologies will fuel the growth of FPGAs in the automotive sector.
- Expansion of 5G infrastructure will significantly boost the need for high-performance FPGAs to support network flexibility and scalability.
- The growing number of IoT devices will require efficient data processing, enhancing the demand for FPGAs.
- Developments in consumer electronics will spur demand for FPGAs to improve multimedia processing and device functionality.
- The industrial automation sector will increasingly rely on FPGAs for real-time control and decision-making applications.
- Military and aerospace applications will continue to drive FPGA innovation, focusing on high reliability and advanced processing capabilities.
- The integration of FPGAs with system-on-chip (SoC) solutions will provide more comprehensive and efficient computing options.
- A focus on power efficiency will lead to the development of energy-saving FPGA architectures, especially for mobile and IoT applications.
- Collaborations between key industry players and Japanese tech companies will foster innovation and expand FPGA applications in the region.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Japan Field Programmable Gate Array (FPGA) Market?
What factors are driving the growth of the Japan Field Programmable Gate Array (FPGA) Market?
What are the key segments within the Japan Field Programmable Gate Array (FPGA) Market?
What are some challenges faced by the Japan Field Programmable Gate Array (FPGA) Market?
Who are the major players in the Japan Field Programmable Gate Array (FPGA) Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Japan Field Programmable Gate Array (FPGA) Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Japan Field Programmable Gate Array (FPGA) Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 498.36 million → 2032: USD 1,214.13 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Japan Field Programmable Gate Array (FPGA) Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Japan Field Programmable Gate Array (FPGA) Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Japan Field Programmable Gate Array (FPGA) Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Japan Field Programmable Gate Array (FPGA) Market Drivers
- 3.3 Japan Field Programmable Gate Array (FPGA) Market Restraints & Challenges
- 3.4 Japan Field Programmable Gate Array (FPGA) Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Japan Field Programmable Gate Array (FPGA) Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Japan Field Programmable Gate Array (FPGA) Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Japan Field Programmable Gate Array (FPGA) category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Japan Field Programmable Gate Array (FPGA) Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Japan Field Programmable Gate Array (FPGA) Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Japan Field Programmable Gate Array (FPGA) market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Japan Field Programmable Gate Array (FPGA) Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Japan Field Programmable Gate Array (FPGA) Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Japan Field Programmable Gate Array (FPGA) Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Japan Field Programmable Gate Array (FPGA) (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Japan Field Programmable Gate Array (FPGA) Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Japan Field Programmable Gate Array (FPGA) Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Japan Field Programmable Gate Array (FPGA) Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Japan Field Programmable Gate Array (FPGA) Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Japan Field Programmable Gate Array (FPGA) Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Japan Field Programmable Gate Array (FPGA) Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Japan Field Programmable Gate Array (FPGA) Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Japan Field Programmable Gate Array (FPGA) Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Japan Field Programmable Gate Array (FPGA) Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
