
Market Overview
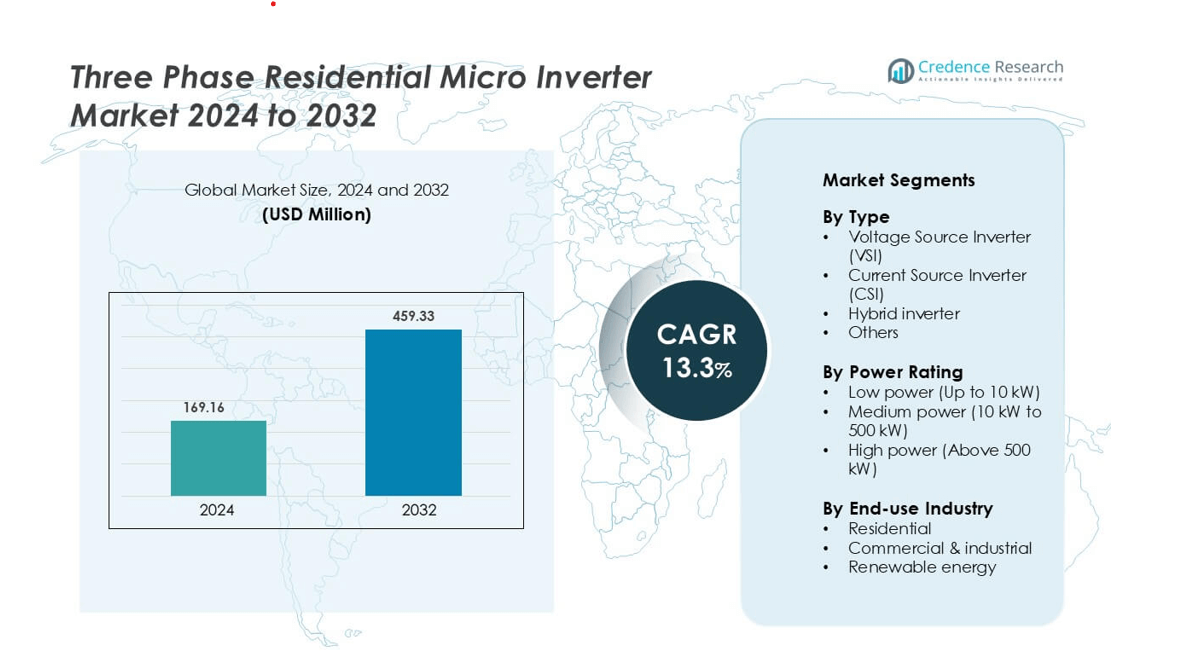
Three Phase Residential Micro Inverter market was valued at USD 169.16 million in 2024 and is anticipated to reach USD 459.33 million by 2032, growing at a CAGR of 13.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Three Phase Residential Micro Inverter MarketSize 2024 | USD 169.16 million |
| Three Phase Residential Micro Inverter Market, CAGR | 13.3% |
| Three Phase Residential Micro Inverter Market Size 2032 | USD 459.33 million |
The leading players in the global three‑phase residential micro‑inverter market include Altenergy Power System, Darfon Electronics Corporation, Enphase Energy, Hoymiles, JMHPOWER, Sparq System, Sungrow, Solax Power, Sunrover Power and Tata Power Solar. Among regions, North America leads with roughly 35.2% of the market share, driven by high residential solar adoption, widespread three‑phase wiring in homes and strong installer networks.
Market Insights
- The global three‑phase residential micro‑inverter market stood at USD 169.16 million in 2024 and is projected to reach USD 459.33 million by 2032, growing at a CAGR of 13.3 %.
- Rising residential solar adoption and stricter grid‑integration requirements are driving demand for panel‑level optimisation and three‑phase micro-inverters.
- Key trends include bundled energy‑storage integration, advanced monitoring systems, and cost-effective solutions targeting emerging markets.
- Competitive intensity remains high as leading players expand globally, while high upfront costs and installer skill gaps act as market restraints.
- Regionally, North America leads with roughly 35.2 % market share, followed by Asia-Pacific, driven by infrastructure expansion and increasing solar adoption.
Market Segmentation Analysis:
By Type
In the Three Phase Residential Micro Inverter market, the Voltage Source Inverter (VSI) segment dominates with the largest market share, capturing around 52% of total revenue. Its dominance is driven by superior efficiency, reliable voltage regulation, and compatibility with residential solar systems. The CSI and Hybrid inverter segments are growing steadily, supported by technological advancements that enhance grid stability and enable bidirectional power flow. Demand for VSI units is further bolstered by increasing residential rooftop solar adoption, rising awareness of energy independence, and government incentives for renewable energy integration. The “Others” segment remains niche but benefits from specialized applications.
- For instance, SMA Solar Technology AG’s “Sunny Tripower X 12/15/20/25 kW” three-phase inverter series offers a maximum efficiency of 98.2%, supports a maximum PV generator power of 18,000 Wp, has a maximum input voltage of 1000 Vdc, and includes three independent MPP trackers.
By Power Rating
Low-power micro inverters (up to 10 kW) lead the market with approximately 58% share due to their suitability for individual residential installations. Medium-power inverters (10–500 kW) and high-power inverters (above 500 kW) are witnessing growth in multi-unit residences and small commercial setups. The low-power segment benefits from easier installation, lower cost, and compatibility with decentralized solar setups. Drivers include the rising adoption of rooftop solar systems, urban energy efficiency initiatives, and increasing consumer demand for reliable energy solutions.
- For instance, Enphase’s IQ7+ micro-inverter supports a recommended PV module pairing of 235 W to 440 W, has a maximum input DC voltage of 60 V, and delivers a peak AC output power of 295 VA per unit
By End-use Industry
The residential segment is the dominant end-user, holding nearly 60% of the market, supported by widespread adoption of rooftop solar systems. Commercial and industrial applications are expanding due to energy cost savings, sustainability mandates, and large-scale solar integration projects. The renewable energy sector drives adoption across all segments, particularly in regions with strong solar capacity growth and government incentives. Residential dominance is fueled by rising consumer awareness of green energy, technological improvements in inverter efficiency, and supportive policies for distributed energy resources.
Key Growth Drivers
Surge in Residential Solar Adoption
The expansion of rooftop solar systems in homes directly drives demand for three‑phase residential micro inverters. Homeowners seek efficient devices that convert DC from solar panels into balanced three‑phase AC, improving energy use and export potential. Regulation and incentives for residential solar deployments further support adoption. As homeowners upgrade systems or install new PV arrays, manufacturers of three‑phase micro inverters capture increased volume. This residential solar uptake strengthens the market foundation and accelerates equipment penetration.
- For instance, Hoymiles HMT‑1800‑6T is a three-phase micro-inverter rated at 1,800 VA output, supports up to 6 PV modules per unit, has a maximum DC input voltage of 60 V, and operates from a startup DC voltage of 22 V.
Grid Modernisation and Energy Stability Requirements
tility efforts towards smarter grids, increased reliability and energy resilience heighten the need for advanced inverter solutions. Three‑phase micro inverters enable better grid interaction, phase balancing and fault tolerance in residential settings. With grid‑tie mandates and net‑metering policies, these inverters help homeowners meet regulatory standards and feed surplus power back efficiently. The combination of regulatory compliance and grid stability improves market prospects for three‑phase models.
- For instance, the NEP BDM-800 single phase microinverter is indeed rated for 800 W output, produces a pure sine AC waveform, and is suitable for residential on-grid applications where grid compliance is essential.
Technological Innovation in Materials and Monitoring
Manufacturers are investing in new materials, embedded sensors and monitoring platforms that boost performance of three‑phase residential micro inverters. Innovations such as improved conversion efficiency, thermal management, online diagnostics and IoT connectivity make these inverters more appealing. These enhancements reduce downtime, increase lifespan and improve power harvest from the panels. As premium features become standard, the perceived value increases and drives adoption across mid‐ and high‐tier residential projects.
Key Trends & Opportunities
Integration with Battery Storage and Smart Home Systems
A key trend in the three‑phase residential micro inverter market is the integration with energy storage systems and smart‑home platforms. Homeowners increasingly demand systems that not only convert solar power but also manage storage and enable home energy optimisation via apps. This convergence opens opportunities for micro inverter providers to bundle storage, monitoring and control services, enhancing average selling price and unlocking higher margin segments.
- For instance, SolarEdge’s Home solution combines the Home Hub inverter with modular Home Battery units (each module provides 4.6 kWh usable capacity), supports 5 kW continuous battery discharge per battery and allows stacking up to three modules for extended backup and app-based control via the mySolarEdge platform.
Emergence of Emerging Markets and Entry‑Level Segments
Markets in Asia‑Pacific, Latin America and Middle East are emerging as growth hotspots for residential solar and related equipment. Rising disposable incomes and urban expansion support deployment of three‑phase inverter systems, even in multi‑phase residential buildings. Brands that introduce cost‑effective entry‑level three‑phase solutions tailored for these regions can capture substantial early market share. This geographic diversification presents untapped opportunity beyond mature markets.
- For instance, WAAREE introduced its W3 range of three-phase on-grid inverters for residential/rooftop use in India with models from 50 kW to 80 kW output and integrated Wi-Fi/GPRS remote monitoring – targeting multi-unit apartment blocks and small commercial rooftops in emerging markets.
Key Challenges
High Initial Cost and Complexity of Three‑Phase Systems
One significant challenge in the market is the higher upfront cost and complexity associated with three‑phase micro inverters compared to simpler single‑phase systems. These costs may deter homeowners, especially in markets where single‑phase supply prevails or where budget constraints exist. Installation, configuration and wiring of three‑phase systems can also be more demanding. Such barriers limit uptake in cost‑sensitive residential segments and slow growth in some geographies.
Compatibility, Standards and Grid‑Integration Hurdles
Another major restraint relates to compatibility issues with existing grid infrastructure and the need to comply with varied regional standards. Residential installations may face grid‑connection limitations, phase imbalance concerns or regulatory constraints when deploying three‑phase micro inverters. These technical and regulatory hurdles raise entry barriers for manufacturers and installers. Until harmonisation improves, these issues remain a drag on broader market adoption.
Regional Analysis
North America
North America commands a leading share of approximately 35.2% of the three‑phase residential micro‑inverter market. The region benefits from mature rooftop solar adoption, extensive three‑phase home wiring, and stringent grid‑tie standards that favour panel‑level conversion. Manufacturers focus on high‑efficiency products and advanced monitoring systems to meet homeowner expectations. Innovation and large residential solar portfolios further boost the segment’s dominance, while expansion into multi‑unit housing and refurbishment of older systems sustain long‑term demand.
Europe
Europe holds a market share near 23.6% in the three‑phase residential micro‑inverter sector. The region’s growth is underpinned by aggressive decarbonisation policies, strong home‑solar subsidies, and prevalent three‑phase electrical wiring in multi‑storey residences. Key countries such as the UK, Germany and France lead in installations of panel‑level inverters. Suppliers capitalise on strong consumer awareness, bundled smart‑home energy systems and retrofit opportunities in aging housing stock to maintain momentum.
Asia Pacific
Asia Pacific accounts for approximately 20% of the global market for three‑phase residential micro‑inverters. Rapid urbanisation, rising disposable income and expanding solar infrastructure drive uptake in India, China and Southeast Asia. While many homes still use single‑phase supply, multi‑unit residential developments increasingly adopt three‑phase systems to support rooftop PV. Vendors target this region with cost‑effective entry‑level solutions to tap growth before market saturation in mature territories.
Latin America
Latin America holds roughly a 9.6% share of the global market for three‑phase residential micro‑inverters. Growth stems from expanding solar programmes, rising energy costs, and increased residential electricity consumption in Brazil and Argentina. Homes in many countries are moving toward three‑phase connections to support larger PV systems and appliances, creating openings for specialized micro‑inverter solutions. The region’s price sensitivity drives focus on value‑oriented offerings and local distribution networks.
Middle East & Africa (MEA)
The Middle East & Africa region contributes around 4.2% to the global three‑phase residential micro‑inverter market. Significant drivers include investments in sports and residential infrastructure, increased electrification and solar uptake in Gulf states and North Africa. With many homes already wired for three‑phase load, micro‑inverter adoption accelerates in new residential builds and solar retrofit projects. However, economic variances and diverse regulatory frameworks present challenges to uniform market expansion.
Market Segmentations:
By Type
- Voltage Source Inverter (VSI)
- Current Source Inverter (CSI)
- Hybrid inverter
- Others
By Power Rating
- Low power (Up to 10 kW)
- Medium power (10 kW to 500 kW)
- High power (Above 500 kW)
By End-use Industry
- Residential
- Commercial & industrial
- Renewable energy
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the three‑phase residential micro‑inverter market remains moderately consolidated, with key players such as Enphase Energy, Sungrow, Hoymiles and Tata Power Solar driving innovation and scaling globally. These firms leverage deep R&D, strategic alliances and strong installer networks to lead in premium segment adoption; smaller rivals focus on cost‑efficient entry models to capture emerging markets. Intense rivalry compels frequent product launches, performance upgrades and aggressive pricing. At the same time, regional manufacturers exploit local distribution and market knowledge to challenge incumbents, especially in Asia Pacific and Latin America. As a result, differentiation via advanced monitoring, grid‑support functions and smart home integration is becoming vital to maintain competitive advantage in this evolving space.
Key Player Analysis
- Sungrow
- Tata Power Solar
- Solax Power
- Darfon Electronics Corporation
- Sunrover Power
- Hoymiles
- Enphase
- Altenergy Power System
- JMHPOWER
- Sparq System
Recent Developments
- In June 2024, Hoymiles introduced a 5 kW three-phase microinverter designed specifically for large residential PV systems and commercial applications. This new product boasts a maximum input voltage of 140 V and is equipped with four Maximum Power Point Tracking units, with one input designated for each MPPT. The company aims to continue to reinforce its position by this launch as a leader in innovative solar solutions, catering to the growing demand for reliable and efficient microinverter systems.
- In May 2022, China-based inverter manufacturer APsystems introduced a three-phase microinverter designed for residential and commercial solar projects, featuring a power output of up to 2,000 VA. This microinverter includes reactive power control, enabling it to interact effectively with power grids. This functionality helps manage fluctuations in photovoltaic power while providing a reliable solution for small and medium-sized commercial solar installations worldwide
Report Coverage
The research report offers an in-depth analysis based on Type, Power rating, End use Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Manufacturers will increasingly launch three‑phase residential micro inverters with integrated battery storage to capture the growing energy storage market.
- Adoption of smart grid‑compatible three‑phase micro inverters will accelerate as grid codes evolve to favour panel‑level power conversion and phase balancing.
- Growth will expand in multi‑unit residential buildings as three‑phase wiring becomes standard in urban housing, driving increased installer demand.
- Vendors will push cost‑reduced models to penetrate emerging markets in Asia Pacific and Latin America, creating new entry‑level volume streams.
- Inverter makers will leverage IoT and AI‑enabled monitoring features in three‑phase systems to boost service revenue and system optimisation.
- Strategic partnerships with solar panel manufacturers and home‑energy platforms will grow, enabling bundled residential solutions featuring three‑phase micro inverters.
- Premium three‑phase micro inverters will capture share as homeowners upgrade to higher‑wattage solar modules requiring multi‑input optimisation.
- Regulatory incentives for distributed energy systems will favour three‑phase micro inverter adoption in residential settings.
- Intense competition and increasing module‑level electronics exposure will drive consolidation and margin pressure among three‑phase micro inverter providers.
- Rising consumer interest in sustainable homes will push manufacturers to offer eco‑friendly three‑phase micro inverters with recycled materials and extended lifespans.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Three Phase Residential Micro Inverter market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Three Phase Residential Micro Inverter market projected to grow between 2025 and 2032?
Which Type segment held the largest share in 2024?
What are the primary factors fueling the growth of the Three Phase Residential MicroInverter market?
Who are the leading companies in the Three Phase Residential Micro Inverter market?
Which region commanded the largest share in the 2024 Three Phase Residential Micro Inverter market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 169.16 million → 2032: USD 459.33 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Three Phase Residential Micro Inverter Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Three Phase Residential Micro Inverter Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Three Phase Residential Micro Inverter Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Three Phase Residential Micro Inverter Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Three Phase Residential Micro Inverter Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Three Phase Residential Micro Inverter Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Three Phase Residential Micro Inverter Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Three Phase Residential Micro Inverter Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 169.16 million → 2032: USD 459.33 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Three Phase Residential Micro Inverter Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Three Phase Residential Micro Inverter Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Three Phase Residential Micro Inverter Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Three Phase Residential Micro Inverter Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

