
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Lead Free Piezoelectric Ceramic Material Market Size 2024 | USD 1,250 million |
| Lead Free Piezoelectric Ceramic Material Market , CAGR | 8.3% |
| Lead Free Piezoelectric Ceramic Material Market Size 2032 | USD 2,366 million |
Market Overview
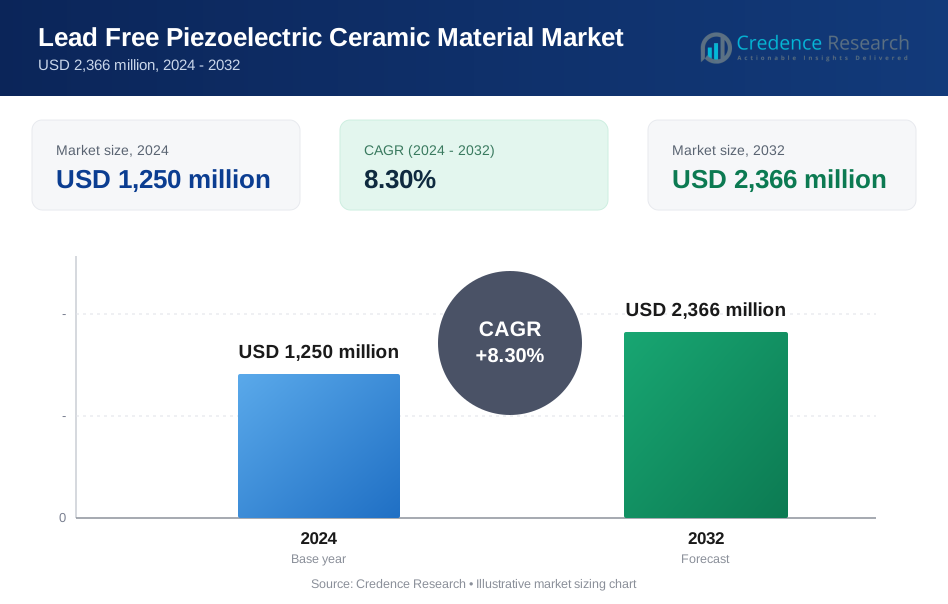
Lead Free Piezoelectric Ceramic Material Market size was valued at USD 1,250 million in 2024 and is anticipated to reach USD 2,366 million by 2032, at a CAGR of 8.3% during the forecast period.
The Lead Free Piezoelectric Ceramic Material market is experiencing robust growth due to increasing regulatory pressure to eliminate hazardous substances such as lead in electronic components, along with rising demand for environmentally friendly and sustainable materials across industries. Expanding applications in automotive sensors, medical ultrasound devices, and consumer electronics drive adoption, as manufacturers seek high-performance, non-toxic alternatives to conventional piezoelectric ceramics. Advancements in material science and manufacturing processes further enhance product efficiency and cost-effectiveness, enabling wider market penetration. Key trends include the integration of lead-free ceramics in next-generation actuators and transducers, growing investment in research and development for improved electrical and mechanical properties, and the emergence of new compositions such as bismuth sodium titanate and potassium sodium niobate. Collectively, these factors contribute to a dynamic market environment that prioritizes sustainability, regulatory compliance, and technological innovation in lead free piezoelectric ceramic materials.
The geographical analysis of the Lead Free Piezoelectric Ceramic Material Market highlights robust growth across North America, Europe, and Asia Pacific, driven by technological innovation, regulatory compliance, and expanding applications in sectors such as automotive, medical devices, and consumer electronics. North America and Europe lead in research, product development, and early adoption of sustainable materials, while Asia Pacific rapidly expands manufacturing capacity and serves as a major production hub for electronics and industrial automation. Latin America and the Middle East & Africa show emerging demand in niche applications, gradually increasing their market presence. Among the leading companies shaping the competitive landscape are KYOCERA Corporation, known for its broad portfolio and innovation, Murata Manufacturing Co., Ltd, recognized for advanced material solutions, and CeramTec GmbH, a prominent player in high-performance ceramics. CTS Corporation also stands out for its global reach and focus on high-reliability piezoelectric products.
Market Insights
- The Lead Free Piezoelectric Ceramic Material Market is projected to grow from USD 1,250 million in 2024 to USD 2,366 million by 2032, at a CAGR of 8.3%.
- Growing regulatory pressure to phase out hazardous substances and increasing demand for sustainable materials are driving market expansion.
- Integration of lead-free ceramics in next-generation sensors, actuators, and electronic devices is a prominent trend, supported by ongoing research in material science.
- Key players such as KYOCERA Corporation, Murata Manufacturing Co., Ltd, CeramTec GmbH, and CTS Corporation focus on innovation, product diversification, and strategic partnerships to strengthen their competitive positions.
- Complex manufacturing processes, high raw material costs, and technical challenges in achieving performance parity with lead-based ceramics restrain widespread market adoption.
- North America and Europe lead the market with advanced R&D, strong regulatory environments, and established industries, while Asia Pacific demonstrates rapid growth through cost-effective manufacturing and rising demand in automotive and electronics.
- Emerging opportunities include the adoption of lead-free ceramics in renewable energy, medical imaging, and wearable devices, as well as advancements in material science and automation that improve efficiency and support broader market penetration.
Market Drivers
Rising Regulatory Pressure for Environmentally Safe Materials is Accelerating Market Growth
Lead Free Piezoelectric Ceramic Material Market is benefiting from stringent environmental regulations and global initiatives aimed at phasing out hazardous substances, especially lead, in electronic and industrial applications. Governments across North America, Europe, and Asia-Pacific are implementing strict policies to reduce the use of toxic materials, which prompts manufacturers to adopt safer alternatives. The market responds positively to these mandates by innovating lead-free compositions that meet or exceed the required standards. International agreements, such as the Restriction of Hazardous Substances (RoHS) directive, play a critical role in shaping product development strategies. Companies actively invest in research to create compliant materials without sacrificing performance. These efforts increase demand for lead-free piezoelectric ceramics, supporting long-term market growth.
- For instance, the European Union’s Restriction of Hazardous Substances (RoHS) directive mandates the elimination of lead-based materials in electronics, driving demand for lead-free alternatives.
Expanding Applications Across Multiple End-Use Industries are Supporting Adoption
Lead Free Piezoelectric Ceramic Material Market is witnessing significant uptake in sectors such as automotive, healthcare, consumer electronics, and industrial automation. The need for reliable and non-toxic components in ultrasonic sensors, actuators, and medical devices is propelling demand. The automotive industry integrates lead-free ceramics into advanced driver-assistance systems and electric vehicles for improved safety and sustainability. Medical equipment manufacturers rely on these materials for sensitive applications, including imaging and diagnostics. Consumer electronics companies choose lead-free options to align with environmental standards and cater to eco-conscious consumers. This widespread adoption fuels overall market expansion.
- For instance, lead-free piezoelectric ceramics are increasingly used in medical imaging devices, ultrasonic sensors, and automotive safety applications.
Technological Advancements and Product Innovation are Enhancing Performance and Competitiveness
Lead Free Piezoelectric Ceramic Material Market benefits from continuous advancements in material science and engineering. Researchers develop new compositions such as bismuth sodium titanate and potassium sodium niobate, which offer improved electrical and mechanical properties. Enhanced manufacturing techniques lower production costs while ensuring consistent quality. Innovations allow for better temperature stability, higher sensitivity, and longer operational life in end products. These improvements position lead-free ceramics as viable replacements for traditional lead-based materials. Industry players gain a competitive edge by launching advanced products that address emerging customer requirements.
Rising Demand for Sustainable and Cost-Effective Solutions is Shaping Market Dynamics
Lead Free Piezoelectric Ceramic Material Market experiences strong demand from organizations seeking sustainable solutions without compromising functionality or budget. Eco-friendly practices become a priority across industries, prompting companies to source materials with a lower environmental footprint. Lead-free ceramics offer a balance of performance, safety, and cost-effectiveness, making them attractive for large-scale integration. The trend toward circular economy principles reinforces the preference for recyclable and non-toxic components. Growing awareness of health and environmental risks associated with lead further accelerates the market shift. It creates new opportunities for suppliers to expand their portfolios and reach a broader customer base.
Market Trends
Integration of Lead-Free Ceramics in Advanced Electronic Devices is Gaining Traction
Lead Free Piezoelectric Ceramic Material Market is witnessing a notable trend toward the integration of lead-free ceramics in next-generation electronic devices and systems. Manufacturers prioritize non-toxic materials for sensors, actuators, and microelectromechanical systems (MEMS), addressing both performance and regulatory concerns. It supports the development of compact, high-precision devices for applications in automotive safety, consumer electronics, and industrial automation. The move to lead-free alternatives aligns with global sustainability goals, encouraging innovation in product design and manufacturing techniques. Companies focus on enhancing the miniaturization and efficiency of these components to meet the demands of rapidly evolving end-use sectors. Industry leaders invest in proprietary formulations that provide superior functional characteristics.
- For instance, researchers are developing lead-free piezoelectric ceramics using bismuth sodium titanate and potassium sodium niobate to comply with environmental regulations.
Research and Development Focus on New Compositions is Accelerating Material Innovation
Lead Free Piezoelectric Ceramic Material Market trends reflect strong investment in research and development for new, high-performance material compositions. It features growing interest in alternatives such as bismuth sodium titanate, potassium sodium niobate, and other perovskite-based systems. These innovations aim to improve piezoelectric coefficients, temperature stability, and durability while eliminating toxic elements. Collaborative efforts between academic institutions and industry players speed up the commercialization of novel materials. Research initiatives also target scalable, cost-effective synthesis processes to facilitate widespread market adoption. Companies launch pilot programs and demonstration projects to validate performance in real-world environments.
Expansion into Emerging Markets and New Applications is Broadening Market Scope
Lead Free Piezoelectric Ceramic Material Market is expanding beyond traditional sectors, reaching new geographies and applications. It finds traction in energy harvesting, wearable devices, and environmental monitoring systems, reflecting a shift toward diversified end-use cases. Growth in emerging economies, particularly in Asia-Pacific and Latin America, opens new avenues for market participants. Strategic partnerships and local manufacturing investments support greater accessibility and customization for regional demands. Companies adapt their marketing and distribution strategies to capture untapped opportunities. The broadening application base drives higher consumption and fosters market resilience.
- For instance, lead-free piezoelectric ceramics are finding new uses in fields like energy harvesting technology, automotive systems, and medical devices.
Digitalization and Automation are Influencing Manufacturing and Supply Chain Practices
Lead Free Piezoelectric Ceramic Material Market is undergoing transformation through the adoption of digital technologies and automation in production and logistics. It allows for more precise control over product quality, reduces operational costs, and shortens time-to-market for new materials. The use of data analytics, IoT-enabled monitoring, and automated testing enhances transparency and traceability throughout the supply chain. Companies leverage advanced manufacturing platforms to scale production efficiently and respond rapidly to shifting customer needs. Digital tools support continuous improvement and compliance with evolving regulatory standards. These trends collectively enhance the competitiveness and adaptability of market participants.
Market Challenges Analysis
Complex Manufacturing Processes and Performance Limitations Hinder Widespread Adoption
Lead Free Piezoelectric Ceramic Material Market faces significant challenges related to complex manufacturing processes and technical performance limitations. It requires precise control over composition and processing conditions to achieve the desired electrical and mechanical properties, which increases production costs and slows scalability. Achieving performance parity with traditional lead-based ceramics, especially in terms of sensitivity, stability, and longevity, remains a technical barrier. Manufacturers often encounter issues with reproducibility and material consistency at high volumes. These factors impact the willingness of end users to transition fully to lead-free options. Companies must invest heavily in research and process optimization to address these persistent challenges.
- For instance, achieving performance parity with traditional lead-based ceramics remains a challenge, as lead-free alternatives often exhibit lower piezoelectric coefficients and reduced thermal stability.
Supply Chain Constraints and High Raw Material Costs Impact Market Growth
Lead Free Piezoelectric Ceramic Material Market experiences supply chain constraints and elevated raw material costs, which can limit profitability and market expansion. It depends on specialized raw materials such as bismuth, sodium, and potassium, which are subject to price volatility and geopolitical risks. Limited availability of high-purity feedstocks affects both cost and product quality, increasing the burden on manufacturers. Supply disruptions can delay production schedules and erode customer confidence. Companies must manage these risks while maintaining competitive pricing strategies. These supply-side issues pose ongoing challenges for both established players and new entrants.
Market Opportunities
Expansion into High-Growth Sectors and Emerging Applications Presents Significant Opportunity
Lead Free Piezoelectric Ceramic Material Market finds significant opportunity in expanding its presence across high-growth sectors such as electric vehicles, medical imaging, and industrial automation. It serves as a critical component in advanced sensors, actuators, and transducers, meeting the rising demand for non-toxic and sustainable materials. The transition to renewable energy and increased adoption of IoT devices create new avenues for innovative lead-free ceramic solutions. Companies can leverage partnerships with technology leaders to co-develop application-specific materials. Customized solutions for niche industries such as aerospace and wearable technology can further differentiate market offerings. Growth in these segments enables market participants to capture higher-value opportunities.
Advancements in Material Science and Manufacturing Enable Market Differentiation
Lead Free Piezoelectric Ceramic Material Market benefits from advancements in material science and manufacturing, which create opportunities for superior product performance and cost efficiency. It enables the development of ceramics with enhanced piezoelectric coefficients, higher temperature stability, and longer operational lifespans. Automation and digitalization in production streamline manufacturing processes and lower operational expenses. Research collaborations between industry and academia accelerate the discovery of novel material compositions. Companies that invest in intellectual property and scale up innovative manufacturing techniques can position themselves as leaders in the global market. These advancements pave the way for broader adoption and increased competitiveness.
Market Segmentation Analysis:
By Composition:
Lead Free Piezoelectric Ceramic Material Market segments by composition into Barium Titanate (BaTiO3), Potassium Sodium Niobate (KNN), Calcium Zirconate (CaZrO3), Sodium Bismuth Titanate (NBT), and others. Barium Titanate remains a leading choice due to its strong dielectric and piezoelectric properties, making it suitable for a wide range of applications, from capacitors to actuators. Potassium Sodium Niobate offers high environmental compatibility and is preferred in applications where non-toxicity is critical, such as medical devices and consumer electronics. Calcium Zirconate contributes to improved thermal stability, serving high-temperature applications in automotive and industrial sectors. Sodium Bismuth Titanate demonstrates potential for high-energy and high-frequency performance, gaining traction in advanced transducers and sensors. The ‘others’ category includes emerging compositions that target niche applications and provide tailored material solutions for specific end-use requirements.
By Application: Lead Free Piezoelectric Ceramic Material Market covers telecommunications, automotive, medical devices, consumer electronics, and industrial automation. It supports telecommunications through the development of filters, resonators, and signal processors that demand reliability and lead-free compliance. The automotive segment integrates lead-free ceramics into advanced driver assistance systems, sensors, and safety mechanisms, supporting the shift toward electric and hybrid vehicles. Medical devices benefit from these materials in ultrasound imaging, diagnostics, and implantable sensors, where biocompatibility and safety remain essential. Consumer electronics rely on lead-free ceramics for touch sensors, microphones, and haptic feedback systems. Industrial automation leverages these materials in robotics, precision control, and energy management solutions, enhancing efficiency and system integrity.
By Product Type: Lead Free Piezoelectric Ceramic Material Market segments by product type into actuators, transducers, sensors, energy harvesters, and others. Actuators use these ceramics for precision movement in automotive and industrial applications, where responsiveness and non-toxicity are priorities. Transducers, widely adopted in medical imaging and ultrasonic testing, benefit from the improved performance and regulatory compliance of lead-free options. Sensors represent a core market, with applications in environmental monitoring, automotive safety, and wearable devices. Energy harvesters use lead-free ceramics to convert ambient mechanical energy into electrical power, enabling self-powered systems in remote or wireless applications. The ‘others’ category captures innovative products that extend the reach of lead-free piezoelectric technology into specialized markets.
Segments:
Based on Composition
- Barium Titanate (BaTiO3)
- Potassium Sodium Niobate (KNN)
- Calcium Zirconate (CaZrO3)
- Sodium Bismuth Titanate (NBT)
- Others
Based on Application:
- Telecommunications
- Automotive
- Medical Devices
- Consumer Electronics
- Industrial Automation
Based on Product Type:
- Actuators
- Transducers
- Sensors
- Energy Harvesters
- Others
Based on End User Industry:
- Healthcare
- Aerospace
- Consumer Goods
- Electrical and Electronics
- Manufacturing
Based on Performance Characteristics:
- High Temperature Performance
- High Voltage Applications
- High Stability
- Frequency Response
- Durability and Reliability
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America accounts for approximately 28% of the global Lead Free Piezoelectric Ceramic Material Market, driven by robust investments in research, early adoption of advanced material technologies, and stringent environmental regulations. The United States leads the regional growth, leveraging its strong presence in high-tech manufacturing and well-established automotive and medical device industries. Regulatory initiatives such as RoHS compliance and increasing consumer preference for sustainable products further encourage manufacturers to transition toward lead-free solutions. Leading research institutions and collaborations between universities and industry accelerate the commercialization of novel compositions, especially in sectors like medical imaging and consumer electronics. The region also benefits from a thriving industrial automation sector that requires high-performance, lead-free actuators and sensors. The supportive innovation ecosystem enables North America to maintain a prominent share in this dynamic market, positioning it as a key hub for future technological advancements.
Europe
Europe holds the largest share, at 32% of the global Lead Free Piezoelectric Ceramic Material Market, reflecting the continent’s strict regulatory environment and sustained focus on sustainability. The European Union’s comprehensive legislation restricting hazardous substances, combined with incentives for eco-friendly innovation, drives strong demand for lead-free ceramics. Major economies such as Germany, France, and the UK foster high adoption rates in automotive, industrial, and electronics applications. European manufacturers emphasize the integration of lead-free piezoelectric ceramics in electric vehicles, renewable energy solutions, and next-generation consumer electronics. The region’s established supply chains and active participation in research projects position it at the forefront of global advancements. Strategic partnerships between material producers and OEMs enable rapid prototyping and market introduction of new compositions, reinforcing Europe’s leadership in the segment.
Asia Pacific Asia Pacific represents 25% of the Lead Free Piezoelectric Ceramic Material Market, making it the fastest-growing region. High-volume electronics manufacturing in China, Japan, South Korea, and Taiwan underpins rapid market expansion. Local players focus on cost-effective production and scaling up output to meet strong domestic and export demand. The region’s burgeoning automotive and industrial automation sectors increasingly rely on lead-free ceramics for sensors, transducers, and energy harvesting devices. Governments support innovation through subsidies and R&D incentives, propelling Asia Pacific’s competitive advantage. The region also serves as a critical source of raw materials such as bismuth and potassium, enabling vertical integration and cost control. Growing investment in medical device manufacturing further strengthens its position as a leading consumer of advanced lead-free piezoelectric solutions.
Latin America Latin America holds an 8% share of the Lead Free Piezoelectric Ceramic Material Market, characterized by emerging demand in telecommunications, automotive, and industrial automation. Brazil and Mexico drive much of the regional activity, supported by rising manufacturing capabilities and the adoption of environmental standards. The automotive sector integrates lead-free ceramics for safety and diagnostic systems, while local electronics assembly industries gradually adopt eco-friendly alternatives. Latin America faces challenges related to technological capability and limited local research, but increasing partnerships with global suppliers and technology providers are facilitating knowledge transfer and product adoption. Investments in infrastructure and the expansion of industrial automation applications are likely to drive future growth, albeit at a measured pace compared to other regions.
Middle East & Africa Middle East & Africa represent 7% of the global Lead Free Piezoelectric Ceramic Material Market, with adoption primarily concentrated in niche applications and specialized industrial sectors. The region’s market growth remains gradual due to limited manufacturing infrastructure and lower overall demand for advanced ceramics. However, key economies such as the UAE and South Africa show rising interest in smart infrastructure, renewable energy, and medical devices. Multinational companies operating in the region often import high-value components, creating demand for compliant lead-free materials. Local governments promote sustainability and technology transfer through targeted investment incentives. The potential for future growth exists as industrial automation and clean energy projects gain traction, but current market share reflects the nascent stage of adoption.
Key Player Analysis
- KYOCERA Corporation (Japan)
- CeramTec GmbH (Germany)
- CTS Corporation (US)
- Murata Manufacturing Co., Ltd (Japan)
- TDK Corporation (Japan)
- Physik Instrumente (PI) GmbH & Co. (Germany)
- APC International, Ltd (US)
- L3Harris Technologies, Inc (US)
- HOERBIGER Motion Control GmbH (Germany)
- Piezo Technologies (US)
Competitive Analysis
The competitive landscape of the Lead Free Piezoelectric Ceramic Material Market is characterized by a mix of established multinational corporations and specialized manufacturers, each leveraging technological innovation and global reach to maintain market leadership. Key players include KYOCERA Corporation, CeramTec GmbH, CTS Corporation, Murata Manufacturing Co., Ltd, TDK Corporation, Physik Instrumente (PI) GmbH & Co., APC International, Ltd, L3Harris Technologies, Inc, HOERBIGER Motion Control GmbH, and Piezo Technologies. These companies focus on expanding their portfolios with advanced lead-free compositions such as barium titanate and potassium sodium niobate, catering to high-growth segments like automotive, medical devices, and industrial automation. Continuous investment in research and development enables them to improve material performance, durability, and compliance with stringent environmental regulations. Strategic partnerships, mergers, and acquisitions allow leading players to access new technologies and enter emerging regional markets. Many of these firms emphasize vertical integration, quality control, and customization to address specific customer requirements. The combination of strong technical capabilities, global distribution networks, and a commitment to sustainability positions these key companies at the forefront of market innovation and future growth.
Recent Developments
- In 2023, CTS Corporation has acquired maglab AG a Switzerland-based innovator in electric vehicle sensors. This acquisition has helped the company to strengthen its product portfolio in the automotive application in the Europe region.
- In 2022, CTS Corporation has acquired Ferroperm Piezoceramics from Meggitt PLC Denmark based high-quality and innovative piezoceramic technology. This has helped the company to strengthen its geographical presence in Europe and North America.
Market Concentration & Characteristics
The Lead Free Piezoelectric Ceramic Material Market demonstrates moderate to high market concentration, with a limited number of multinational corporations and specialized firms holding significant market shares. It features strong barriers to entry due to the need for advanced manufacturing capabilities, technical expertise, and compliance with strict environmental regulations. Leading players set industry standards through innovation, patent portfolios, and vertical integration, while smaller firms often focus on niche applications or regional markets. The market is characterized by rapid technological advancement, customer-driven customization, and a focus on sustainability. End users value high-performance, non-toxic materials for applications across automotive, medical, industrial, and consumer electronics sectors. Ongoing research and regulatory evolution continue to shape product development, making adaptability and investment in innovation essential traits for sustained competitiveness in this sector.
Report Coverage
The research report offers an in-depth analysis based on Composition, Application, Product Type, End User Industry, Performance Characteristics and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to witness significant growth due to increasing demand for environmentally friendly and sustainable materials across various industries.
- Advancements in material science and manufacturing processes are enhancing product efficiency and cost-effectiveness, enabling wider market penetration.
- The integration of lead-free ceramics in next-generation actuators and transducers is a key trend, driven by the need for high-performance, non-toxic alternatives.
- Growing investment in research and development is leading to improved electrical and mechanical properties of lead-free piezoelectric materials.
- The emergence of new compositions such as bismuth sodium titanate and potassium sodium niobate is expanding the application scope of lead-free ceramics.
- The market is experiencing robust growth due to increasing regulatory pressure to eliminate hazardous substances like lead in electronic components.
- Expanding applications in automotive sensors, medical ultrasound devices, and consumer electronics are driving adoption of lead-free piezoelectric ceramics.
- The trend toward circular economy principles is reinforcing the preference for recyclable and non-toxic components in various industries.
- Companies are actively investing in research to create compliant materials without sacrificing performance, increasing demand for lead-free piezoelectric ceramics.
- The market is poised for dynamic growth, prioritizing sustainability, regulatory compliance, and technological innovation in lead-free piezoelectric ceramic materials.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Lead Free Piezoelectric Ceramic Material Market?
What factors are driving the growth of the Lead Free Piezoelectric Ceramic Material Market?
What are some challenges faced by the Lead Free Piezoelectric Ceramic Material Market?
Who are the major players in the Lead Free Piezoelectric Ceramic Material Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Lead Free Piezoelectric Ceramic Material Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Lead Free Piezoelectric Ceramic Material Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,250 million → 2032: USD 2,366 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Lead Free Piezoelectric Ceramic Material Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Lead Free Piezoelectric Ceramic Material Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Lead Free Piezoelectric Ceramic Material Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Lead Free Piezoelectric Ceramic Material Market Drivers
- 3.3 Lead Free Piezoelectric Ceramic Material Market Restraints & Challenges
- 3.4 Lead Free Piezoelectric Ceramic Material Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Lead Free Piezoelectric Ceramic Material Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Lead Free Piezoelectric Ceramic Material Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Lead Free Piezoelectric Ceramic Material category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Lead Free Piezoelectric Ceramic Material Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Lead Free Piezoelectric Ceramic Material Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Lead Free Piezoelectric Ceramic Material market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Lead Free Piezoelectric Ceramic Material Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Lead Free Piezoelectric Ceramic Material Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Lead Free Piezoelectric Ceramic Material Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Lead Free Piezoelectric Ceramic Material (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Lead Free Piezoelectric Ceramic Material Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Lead Free Piezoelectric Ceramic Material Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Lead Free Piezoelectric Ceramic Material Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Lead Free Piezoelectric Ceramic Material Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Lead Free Piezoelectric Ceramic Material Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Lead Free Piezoelectric Ceramic Material Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Lead Free Piezoelectric Ceramic Material Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Lead Free Piezoelectric Ceramic Material Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Lead Free Piezoelectric Ceramic Material Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
