
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| North America Automotive Lead Acid Battery Market Size 2023 | USD 7,434.65 million |
| North America Automotive Lead Acid Battery Market, CAGR | 8.1% |
| North America Automotive Lead Acid Battery Market Size 2032 | USD 15,014.57 million |
Market Overview
North America Automotive Lead Acid Battery market size was valued at USD 7,434.65 million in 2023 and is anticipated to reach USD 15,014.57 million by 2032, at a CAGR of 8.1% during the forecast period (2023-2032).
The North America Automotive Lead Acid Battery market is driven by several key factors, including the increasing demand for vehicles, particularly in the electric vehicle (EV) sector, where lead acid batteries remain a cost-effective solution for energy storage. The rising adoption of energy-efficient and eco-friendly technologies in automotive applications further fuels market growth. Additionally, the automotive industry's shift towards enhanced vehicle performance, longer battery life, and reduced emissions aligns with the capabilities of lead acid batteries. Trends such as advancements in battery manufacturing technologies and improved recycling methods also contribute to market expansion, as manufacturers focus on sustainability and reducing environmental impact. Furthermore, regulatory policies promoting cleaner energy solutions and electric mobility are expected to accelerate the adoption of lead acid batteries in North American vehicles. These combined drivers and trends indicate a promising growth trajectory for the automotive lead acid battery market in the region.
The North America automotive lead acid battery market is primarily driven by robust vehicle production, a strong automotive aftermarket, and increasing adoption of advanced battery technologies across the U.S., Canada, and Mexico. The region benefits from a mature automotive infrastructure and a well-established distribution network that supports both OEM and replacement battery demand. Technological advancements in start-stop systems and growing interest in micro-hybrid vehicles are contributing to the rising popularity of AGM and EFB batteries. The U.S. leads in innovation and consumption, while Canada and Mexico play crucial roles in manufacturing and cross-border trade. Prominent players operating in the market include Clarios, East Penn Manufacturing Company, EnerSys, C&D Technologies, Inc., Crown Battery, and Stryten Energy. These companies are actively investing in R&D, expanding production capabilities, and forming strategic partnerships with automotive OEMs to enhance their regional presence and meet evolving consumer and environmental demands.
Market Insights
- The North America Automotive Lead Acid Battery market was valued at USD 7,434.65 million in 2023 and is projected to reach USD 15,014.57 million by 2032, growing at a CAGR of 8.1% from 2023 to 2032.
- The Global Automotive Lead Acid Battery market was valued at USD 21,181.34 million in 2023 and is expected to reach USD 43,052.54 million by 2032, growing at a CAGR of 8.2% from 2023 to 2032.
- Increasing vehicle production and growing demand for cost-effective energy storage solutions are propelling market growth.
- The market is witnessing a shift towards advanced flooded and enhanced flooded batteries for improved performance in start-stop vehicle systems.
- Leading players such as Clarios, East Penn Manufacturing, and EnerSys are focusing on expanding product portfolios and regional presence to gain a competitive edge.
- Rising adoption of electric vehicles and availability of alternative battery chemistries like lithium-ion may limit market expansion in the long run.
- The United States dominates the regional market, driven by strong automotive manufacturing infrastructure and rising aftermarket demand.
- Canada is also emerging as a key market due to increased investments in automotive technologies and battery recycling initiatives.
Report Scope
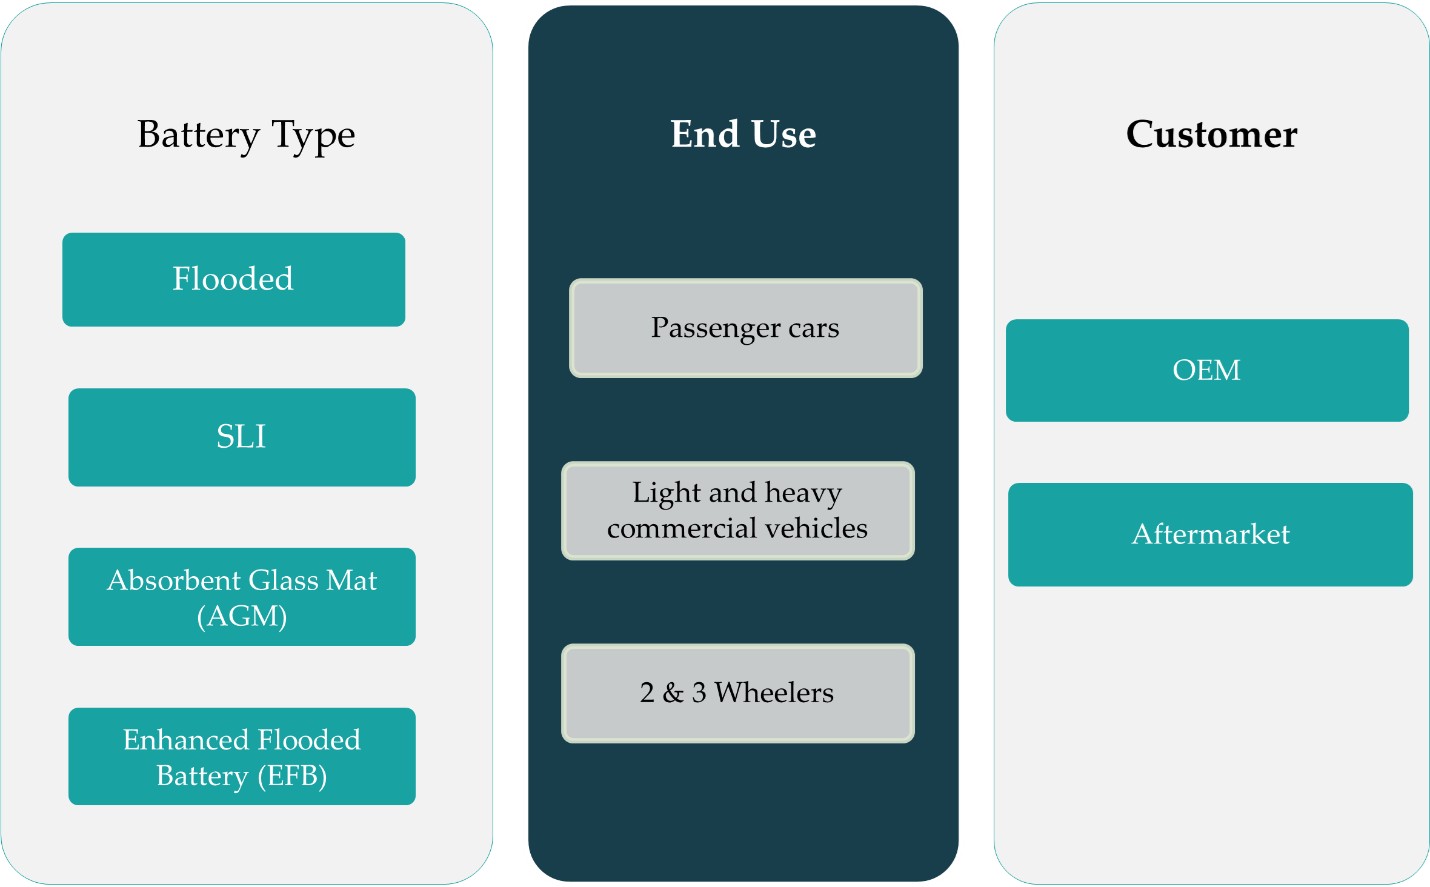
This report segments the North America Automotive Lead Acid Battery Market as follows:
Market Drivers
Growing Vehicle Production and Demand
The automotive industry in North America is witnessing steady growth in vehicle production, which directly drives the demand for lead acid batteries. Despite the increasing popularity of electric vehicles (EVs), conventional vehicles still rely heavily on lead acid batteries due to their cost-effectiveness, reliability, and efficient performance. For instance, the North American automotive industry continues to prioritize lead-acid batteries due to their high recyclability and cost-effectiveness. The continued demand for internal combustion engine (ICE) vehicles, along with the expanding number of hybrid and electric vehicles that utilize lead acid batteries for auxiliary power, ensures sustained growth in the market. The surge in vehicle production across North America, particularly in the United States and Canada, continues to support the increased use of lead acid batteries, both in new and replacement applications.
Regulatory Support and Green Energy Policies
Government regulations and green energy policies in North America also drive the demand for lead acid batteries in the automotive sector. Policies aimed at reducing carbon emissions and promoting energy efficiency encourage the adoption of vehicles with advanced energy storage systems, including those using lead acid batteries. For instance, the U.S. Department of Energy has launched initiatives to support battery recycling and sustainability efforts in the automotive sector. In addition, many states and provinces offer incentives for the use of environmentally friendly technologies, such as electric and hybrid vehicles, which often incorporate lead acid batteries for various functions. Regulatory support for the adoption of low-emission vehicles, coupled with efforts to enhance the energy storage capacity of vehicles, creates a favorable environment for the automotive lead acid battery market. The ongoing development of stricter environmental standards, such as the Corporate Average Fuel Economy (CAFE) regulations in the U.S., further drives the need for efficient, affordable, and sustainable battery solutions, enhancing the growth of lead acid battery adoption across the region.
Cost-Effectiveness and Reliability
One of the most significant drivers of the North American automotive lead acid battery market is the cost-effectiveness of these batteries compared to alternative options. Lead acid batteries are affordable to produce, which makes them an attractive option for automakers and consumers alike. The simplicity of their design also contributes to their widespread use and reliability, offering a robust power source for vehicles, particularly for starting, lighting, and ignition (SLI) purposes. As automakers look for ways to reduce production costs, lead acid batteries provide a low-cost, proven solution. Additionally, these batteries have a long history of dependable performance, making them an ideal choice for both traditional and newer automotive applications, further bolstering their market presence.
Advancements in Battery Recycling and Sustainability
Advancements in battery recycling and sustainability efforts play a significant role in driving the growth of the North American automotive lead acid battery market. The ability to recycle lead acid batteries efficiently has improved over time, with nearly 97% of the components of these batteries being recyclable. This has contributed to a more sustainable industry, aligning with the increasing focus on reducing waste and promoting circular economies within the automotive sector. As regulatory bodies and automakers push for more environmentally friendly solutions, the lead acid battery's high recyclability makes it an appealing option for meeting sustainability targets. The continued development of advanced recycling technologies and better recovery methods for lead, a key component of these batteries, further enhances the attractiveness of lead acid batteries in automotive applications.
Market Trends
Shift Toward Energy-Efficient Vehicles
One of the key trends driving the North American automotive lead acid battery market is the growing shift toward energy-efficient vehicles. As automakers focus on improving fuel economy and reducing carbon footprints, lead acid batteries remain essential for meeting the energy storage needs of both traditional internal combustion engine (ICE) vehicles and hybrid electric vehicles (HEVs). While hybrid vehicles increasingly incorporate more advanced battery technologies like lithium-ion, lead acid batteries are still widely used for auxiliary functions, such as powering lighting, HVAC systems, and other electronics. This trend highlights the ongoing relevance of lead acid batteries, as automakers seek cost-effective solutions for energy storage and management across various vehicle types.
Advancements in Battery Technology and Design
Advancements in lead acid battery technology and design are another prominent trend in the North American automotive market. Manufacturers are continually improving the performance, efficiency, and lifespan of these batteries through innovations in materials and construction. For instance, the U.S. Department of Energy’s Storage Innovations 2030 initiative is exploring advancements in lead-acid battery technology to enhance energy storage capabilities. For example, the development of absorbed glass mat (AGM) and enhanced flooded batteries (EFB) has led to better power output, faster recharge times, and improved overall durability. These advancements make lead acid batteries even more suitable for modern automotive applications, as vehicles demand more from their power sources. The increased performance and longevity of these batteries, combined with their relatively low cost, contribute to their sustained dominance in the automotive market.
Growth in Vehicle Electrification and Hybridization
The electrification and hybridization of vehicles in North America continue to grow, impacting the automotive lead acid battery market. Although lithium-ion batteries dominate the electric vehicle (EV) segment, lead acid batteries still play a significant role in hybrid vehicles, where they provide reliable energy storage for non-propulsion functions, such as powering lights, air conditioning, and infotainment systems. For instance, the North American automotive industry is witnessing a steady increase in hybrid vehicle adoption, reinforcing the demand for lead-acid batteries. Additionally, some newer hybrid models are utilizing lead acid batteries in conjunction with more advanced energy storage technologies to enhance overall vehicle performance and reduce costs. As the automotive industry increasingly adopts hybrid and electric vehicle technologies, lead acid batteries will continue to find niche applications that complement more sophisticated power systems.
Increasing Focus on Sustainability and Recycling
Sustainability is becoming a growing trend in the North American automotive industry, and this is particularly relevant to the lead acid battery market. With a focus on reducing environmental impact, automakers and battery manufacturers are investing in more efficient recycling processes for lead acid batteries. Lead acid batteries are among the most recycled consumer products globally, with over 95% of the materials in these batteries being recoverable. This trend aligns with increasing consumer demand for sustainable products and practices. As automakers and manufacturers strive to meet stringent environmental regulations and sustainability goals, the high recyclability of lead acid batteries becomes a critical factor, ensuring their continued relevance in the automotive sector.
Market Challenges Analysis
Competition from Alternative Battery Technologies
A significant challenge facing the North American automotive lead acid battery market is the increasing competition from alternative battery technologies, particularly lithium-ion (Li-ion) batteries. Lithium-ion batteries, with their higher energy density, lighter weight, and longer lifespan, are increasingly favored in electric and hybrid vehicles, posing a threat to the dominance of lead acid batteries. For instance, automakers in North America are integrating lithium-ion batteries into hybrid models to meet stringent emission regulations and improve vehicle performance. As the automotive industry moves towards greater electrification, lithium-ion technology continues to evolve, offering enhanced performance at competitive prices. Although lead acid batteries remain cost-effective for conventional vehicles and certain hybrid applications, their limitations in energy storage capacity and performance efficiency make them less desirable compared to newer, more advanced battery technologies. This growing shift towards Li-ion and other alternative batteries could limit the future growth prospects of lead acid batteries in the automotive sector.
Environmental and Health Concerns
Despite the high recyclability of lead acid batteries, there are significant environmental and health concerns associated with their production and disposal. Lead, a toxic heavy metal, poses risks to both human health and the environment if not properly managed during battery manufacturing, recycling, or disposal processes. Although regulatory frameworks and recycling initiatives have mitigated some of these risks, public awareness of the dangers posed by lead exposure continues to grow. Additionally, the increasing push for green and sustainable technologies in the automotive industry places pressure on lead acid batteries to meet stricter environmental standards. These concerns, along with the rising popularity of cleaner, more eco-friendly energy storage solutions, could present challenges for the continued widespread adoption of lead acid batteries in the automotive market, especially as consumers and automakers prioritize sustainability in their purchasing decisions.
Market Opportunities
The North America automotive lead acid battery market is poised to benefit from rising demand for reliable energy storage systems in conventional and hybrid vehicles. As internal combustion engine (ICE) vehicles continue to dominate the regional market, particularly in commercial and off-road segments, the need for cost-effective and durable battery technologies remains high. Lead acid batteries, with their established infrastructure, low cost, and recyclability, offer a favorable solution. Moreover, the growing trend of vehicle electrification, especially in start-stop systems and micro-hybrids, has opened new avenues for enhanced flooded batteries (EFB) and absorbent glass mat (AGM) variants. These advanced lead acid batteries are increasingly being integrated into vehicles to support improved fuel efficiency and emission reductions, creating lucrative opportunities for battery manufacturers. Additionally, increasing government emphasis on sustainable transportation and recycling regulations is expected to favor lead acid battery usage due to its high recyclability rate, enhancing its competitive edge against alternative chemistries.
Furthermore, the aftermarket demand for automotive lead acid batteries is witnessing steady growth, driven by aging vehicle fleets and consumer preference for regular battery replacements. North America, particularly the U.S. and Canada, has a large base of vehicles in operation, many of which require periodic battery replacements, thereby supporting sustained market growth. In parallel, the expansion of e-commerce platforms and digital retailing is streamlining battery distribution, making it easier for consumers to access a wide range of products. This is encouraging local and international players to invest in online channels and regional manufacturing facilities to cater to evolving consumer needs. Additionally, strategic partnerships with automotive OEMs and the expansion of dealership networks are enabling battery suppliers to strengthen their market presence. These developments, coupled with technological innovations aimed at improving battery lifespan and cold-cranking performance, are expected to create robust growth prospects for the North America automotive lead acid battery market.
Market Segmentation Analysis:
By Battery Type:
The North America automotive lead acid battery market is segmented by battery type into Flooded, Starting, Lighting, and Ignition (SLI), Absorbent Glass Mat (AGM), and Enhanced Flooded Batteries (EFB). Among these, the flooded battery segment continues to hold a significant share due to its cost-effectiveness and widespread use in conventional internal combustion engine (ICE) vehicles. SLI batteries also maintain strong demand, primarily in entry-level passenger vehicles and commercial fleets where reliable performance and affordability are prioritized. However, the market is experiencing a noticeable shift towards AGM and EFB batteries, driven by increasing adoption of vehicles equipped with start-stop technology and micro-hybrid systems. AGM batteries offer superior deep cycling capabilities and are well-suited for modern vehicles with high electrical loads. Meanwhile, EFB batteries are gaining momentum for their enhanced charge acceptance and durability under partial state-of-charge operations. This evolution reflects the region’s growing emphasis on fuel efficiency and emissions compliance, prompting automakers to adopt advanced battery solutions tailored to meet stricter regulatory and consumer expectations.
By End Use: By end use, the North America automotive lead acid battery market is categorized into passenger cars, light and heavy commercial vehicles, and 2 & 3 wheelers. The passenger car segment dominates the market, supported by the region’s high vehicle ownership rates and consistent demand for battery replacements in aging fleets. As automakers integrate more electronic features in modern cars, the demand for batteries that can support both traditional engine functions and auxiliary power needs has risen sharply. Light and heavy commercial vehicles represent a significant growth area, particularly in logistics and transportation sectors where fleet reliability is critical. These vehicles often operate under demanding conditions, making lead acid batteries an attractive option due to their robustness and easy serviceability. Although the 2 & 3 wheelers segment holds a comparatively smaller market share in North America, it is gaining attention in niche markets and urban areas, especially with rising interest in last-mile delivery solutions. Each end-use category presents tailored growth opportunities based on evolving mobility needs and vehicle usage patterns.
Segments:
Based on Battery Type:
- Flooded
- SLI
- Absorbent Glass Mat
- Enhanced Flooded Battery
Based on End Use:
- Passenger cars
- Light and heavy commercial vehicles
- 2 & 3 Wheelers
Based on Customer:
- OEM
- Aftermarket
Based on the Geography:
- S.
- Canada
- Mexico
Regional Analysis
United States
United States dominates the North America automotive lead acid battery market, accounting for approximately 72% of the regional market share. This leadership position is attributed to the country’s expansive vehicle fleet, well-established automotive aftermarket industry, and significant presence of major OEMs and battery manufacturers. High vehicle ownership rates, coupled with a growing demand for replacement batteries in both passenger and commercial vehicles, continue to fuel market growth. Moreover, the U.S. market has seen rising integration of start-stop systems in vehicles, which has driven the demand for enhanced flooded batteries (EFB) and absorbent glass mat (AGM) variants. Government initiatives aimed at improving fuel economy and reducing carbon emissions further strengthen the role of lead acid batteries in supporting hybrid vehicle platforms, particularly in micro-hybrid configurations.
Canada
Canada holds around 15% of the North American automotive lead acid battery market. The country’s market is driven primarily by a steady rise in vehicle registrations, especially in provinces such as Ontario, Quebec, and British Columbia. Cold weather conditions across much of Canada result in more frequent battery replacements, boosting demand for high-performance, cold-cranking capable batteries. The Canadian automotive aftermarket is well-regulated and supported by numerous retail chains and service centers, contributing to consistent battery sales. Additionally, Canada’s commitment to environmental sustainability and its strong battery recycling infrastructure enhance the acceptance and preference for lead acid batteries, as their recyclability helps meet national environmental standards. Local production and cross-border trade with the U.S. further solidify Canada’s role in the regional supply chain.
Mexico
Mexico captures approximately 9% of the North American market share for automotive lead acid batteries. Growth in this region is fueled by the expansion of the country’s automotive manufacturing sector, which serves as a significant hub for both domestic and export markets. The increasing adoption of passenger vehicles, commercial fleets, and light trucks is creating steady demand for lead acid batteries. Additionally, economic development and rising income levels are leading to greater vehicle ownership and, in turn, higher battery consumption. Mexico also benefits from trade agreements such as USMCA, which enable smoother supply chain logistics and encourage international investment in battery manufacturing and distribution facilities.
Key Player Analysis
- Camel Group Co., Ltd.
- C&D Technologies, Inc.
- Clarios
- CSB Energy Technology Co., Ltd.
- East Penn Manufacturing Company
- EnerSys
- Exide Industries Ltd.
- GS Yuasa Corporation
- Crown Battery
- Leoch International Technology Limited
- Mebco
- Robert Bosch LLC
- Stryten Energy
Competitive Analysis
The North America automotive lead acid battery market is characterized by the presence of several established players that maintain a competitive edge through innovation, strategic partnerships, and strong distribution networks. Leading companies such as Clarios, East Penn Manufacturing, EnerSys, Exide Technologies, Crown Battery Manufacturing, and Power Sonic Corporation dominate the regional landscape with diversified product offerings tailored to both OEM and aftermarket segments. These players emphasize research and development to enhance battery performance, improve cycle life, and support start-stop and hybrid vehicle technologies. Companies are focusing on the development of enhanced flooded batteries (EFB) and absorbent glass mat (AGM) batteries to support modern vehicles equipped with start-stop systems and high electrical loads. Technological advancements aimed at increasing battery lifespan, improving performance in extreme climates, and ensuring faster recharge rates are helping firms differentiate their offerings. Additionally, many manufacturers are investing in sustainable practices such as battery recycling and environmentally friendly production processes to meet stringent regional regulations and appeal to eco-conscious consumers. Competitive pricing, after-sales service, and long-term warranty offerings further influence customer loyalty and brand preference. The market also witnesses intense rivalry in the aftermarket segment, where brand visibility, distribution reach, and reliability play critical roles. To remain competitive, firms continue to expand their manufacturing capabilities across North America and strengthen relationships with automotive OEMs. This evolving landscape is defined by innovation, regulatory compliance, and a growing demand for efficient, cost-effective energy storage solutions in conventional and hybrid vehicles.
Recent Developments
- In November 2024, EnerSys showcased the iQ Mini™ battery monitoring device and maintenance-free NexSys® Thin Plate Pure Lead (TPPL) batteries, which offer longer service life and faster recharge rates.
- In July 2024, Exide Industries Ltd. introduced an advanced Absorbent Glass Mat (AGM) battery for Starting, Lighting, and Ignition (SLI) applications in the automotive market. This new battery is designed to deliver enhanced performance, including improved starting power, and potentially longer lifespan compared to traditional lead-acid batteries.
- In August 2023, Clarios, a global leader in advanced low-voltage battery manufacturing and recycling, is acquiring Paragon GmbH & Co. KGaA’s power business, which specializes in batteries and battery management systems for the automotive industry. This acquisition enhances Clarios' engineering capabilities and supports its low-voltage and lithium-ion projects, significantly expanding the team dedicated to developing new low-voltage architectures.
- In May 2023, C&D Technologies, Inc. introduced the Pure Lead Max (PLM) VRLA battery, designed for long lifespan and improved performance in UPS and data center applications.
- In April 2023, the acquisition of IBCS by EnerSys is a strategic move to expand its motive power services and strengthen its presence in the UK market. This addition will enhance EnerSys's range of battery-related services, including installation, maintenance, repair, and replacement.
Market Concentration & Characteristics
The North America automotive lead acid battery market exhibits moderate to high market concentration, with a few well-established manufacturers dominating a significant portion of the market share. These companies benefit from long-standing relationships with original equipment manufacturers (OEMs), strong brand recognition, and extensive distribution networks. The market is characterized by high entry barriers due to the capital-intensive nature of battery manufacturing, stringent regulatory compliance requirements, and the need for advanced technological capabilities. Additionally, product standardization and economies of scale further strengthen the position of key players. Despite the dominance of a few major firms, the aftermarket segment remains fragmented, offering opportunities for regional and niche suppliers. The market is also defined by consistent demand from internal combustion engine (ICE) vehicles, along with growing applications in hybrid vehicles that require reliable power sources for auxiliary functions. Overall, the North American market maintains a stable and mature profile, driven by performance reliability and cost-effectiveness.
Report Coverage
The research report offers an in-depth analysis based on Battery Type, End Use, Customer and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to witness steady growth driven by consistent demand from internal combustion engine vehicles.
- Start-stop technology adoption in passenger and commercial vehicles will boost the need for enhanced lead acid batteries.
- Replacement demand in the aftermarket segment will continue to support long-term market expansion.
- Manufacturers will increasingly invest in recycling infrastructure to meet environmental regulations and ensure raw material availability.
- Technological advancements will improve battery life, performance, and charge efficiency.
- Hybrid vehicle adoption will create additional demand for auxiliary lead acid battery applications.
- Market players will focus on cost optimization and regional manufacturing to strengthen supply chains.
- Regulatory support for sustainable battery production will drive innovations in eco-friendly processes.
- Rising vehicle parc and aging vehicles in North America will contribute to recurring battery replacement needs.
- Competitive pricing and expanded service networks will remain crucial for market share retention.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Vehicle Production and Demand
Steady growth in vehicle production across North America, especially in the U.S. and Canada, is directly increasing the demand for lead acid batteries for both new vehicles and replacements, as conventional vehicles continue to dominate the market.
Regulatory Support and Green Energy Policies
Government initiatives and regulations aimed at reducing emissions and promoting energy efficiency are encouraging the adoption of advanced lead acid batteries, particularly in vehicles with start-stop and hybrid systems, supporting market expansion.
Cost-Effectiveness and Reliability
Lead acid batteries remain a preferred choice due to their affordability, proven reliability, and robust performance for starting, lighting, and ignition applications, making them attractive for both automakers and consumers seeking low-cost solutions.
Advancements in Battery Recycling and Sustainability
High recyclability rates and ongoing improvements in recycling technologies make lead acid batteries an environmentally responsible option, aligning with increasing industry and regulatory focus on sustainability and circular economy practices.
Technological Advancements in Battery Design
Innovations such as AGM and EFB batteries are enhancing battery performance, lifespan, and suitability for modern vehicles with higher electrical loads and start-stop systems, driving further adoption in the automotive sector.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the North America Automotive Lead Acid Battery?
What factors are driving the growth of the North America Automotive Lead Acid Battery?
What are some challenges faced by the North America Automotive Lead Acid Battery?
Who are the major players in the North America Automotive Lead Acid Battery?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Passenger Cars
- 1.2.2 Light and Heavy Commercial Vehicles
- 1.2.3 2 & 3 Wheelers
- 1.3 By Customer
- 1.3.1 OEM
- 1.3.2 Aftermarket
- 1.4 By Battery Type
- 1.4.1 Flooded
- 1.4.2 Starting, Lighting, and Ignition (SLI)
- 1.4.3 Absorbent Glass Mat (AGM)
- 1.4.4 Enhanced Flooded Battery (EFB)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 7,434.65 million → 2032: USD 15,014.57 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 North America Automotive Lead Acid Battery Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 North America Automotive Lead Acid Battery Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 North America Automotive Lead Acid Battery Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 North America Automotive Lead Acid Battery Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 North America Automotive Lead Acid Battery Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 North America Automotive Lead Acid Battery Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 North America Automotive Lead Acid Battery Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 North America Automotive Lead Acid Battery Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 7,434.65 million → 2032: USD 15,014.57 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 North America Automotive Lead Acid Battery Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Passenger Cars
- 12.3.7.2 Light and Heavy Commercial Vehicles
- 12.3.7.3 2 & 3 Wheelers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Customer - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 OEM
- 12.4.7.2 Aftermarket
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Battery Type - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Flooded
- 12.5.7.2 Starting, Lighting, and Ignition (SLI)
- 12.5.7.3 Absorbent Glass Mat (AGM)
- 12.5.7.4 Enhanced Flooded Battery (EFB)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 North America Automotive Lead Acid Battery End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 North America Automotive Lead Acid Battery Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Country-Level Shares, 2023
- 14.2 Country Market Size Comparison, 2023
- 14.3 Country Market Forecasts, 2023-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 North America Automotive Lead Acid Battery Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 North America Automotive Lead Acid Battery Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Clarios
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 East Penn Manufacturing Company
- 18.4 EnerSys
- 18.5 C&D Technologies, Inc.
- 18.6 Crown Battery
- 18.7 Stryten Energy
- 18.8 Exide Industries Ltd.
- 18.9 GS Yuasa Corporation
- 18.10 Leoch International Technology Limited
- 18.11 Robert Bosch LLC
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

