
Market Overview
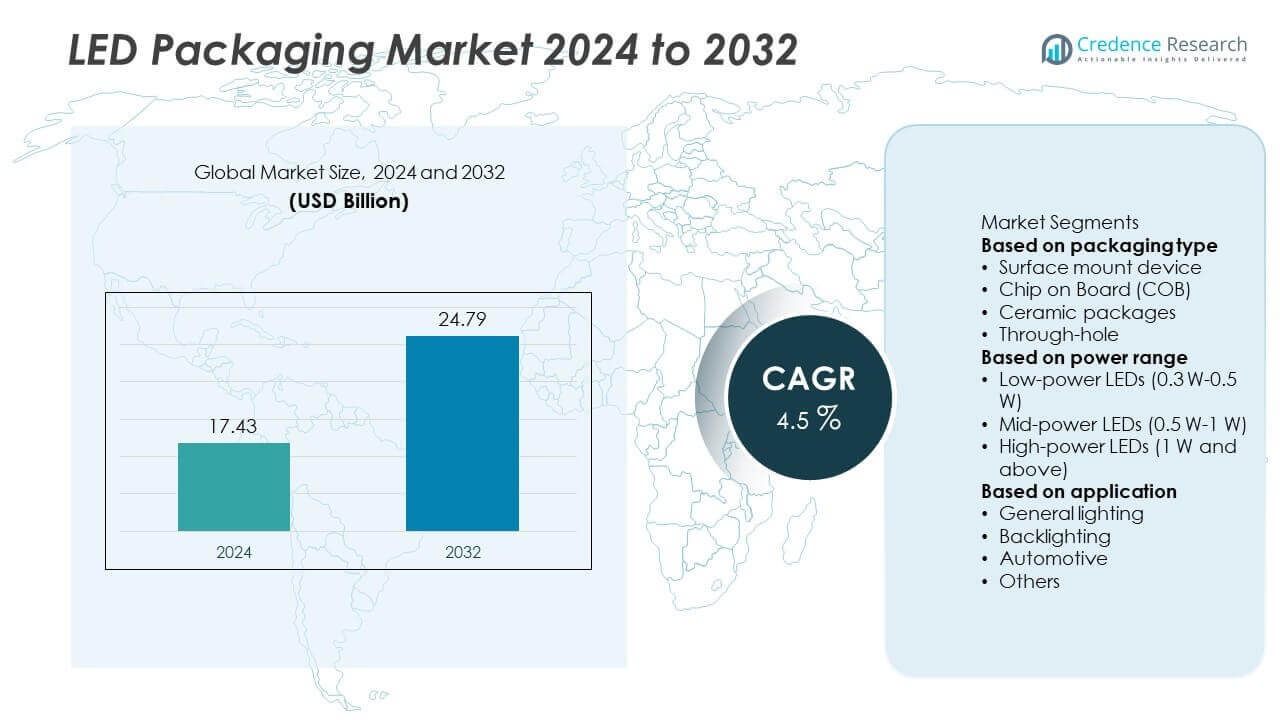
The LED Packaging market was valued at USD 17.43 billion in 2024 and is projected to reach USD 24.79 billion by 2032, expanding at a CAGR of 4.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| LED Packaging Market Size 2024 | USD 17.43 Billion |
| LED Packaging Market, CAGR | 4.5% |
| LED Packaging Market Size 2032 | USD 24.79 Billion |
The LED packaging market is driven by top players including Samsung Electronics Co. Ltd., Nichia Corporation, Seoul Semiconductor Co., Ltd., Lumileds Holding B.V., Ams-Osram AG, Everlight Electronics Co., Ltd., MLS Co., Ltd., Cree LED, LG Innotek, and Toyoda Gosei Co., Ltd. These companies lead through innovations in chip-on-board, surface mount device, and ceramic packaging to improve performance, heat dissipation, and energy efficiency. They actively invest in R&D, strategic collaborations, and capacity expansions to strengthen market presence. Regionally, Asia-Pacific dominated with 36% share in 2024, supported by large-scale manufacturing and strong consumer electronics demand, followed by North America at 27% share and Europe at 25% share, reflecting robust adoption in automotive and general lighting applications.
Market Insights
- The LED packaging market was valued at USD 17.43 billion in 2024 and is projected to reach USD 24.79 billion by 2032, expanding at a CAGR of 4.5% during the forecast period.
- Rising demand for energy-efficient solutions drives adoption, with general lighting leading the market at 52% share in 2024, supported by government initiatives and widespread replacement of traditional lighting systems.
- Key trends include the growing integration of LED packages in automotive applications, miniaturization for compact devices, and expanding use in smart and connected lighting systems.
- The market is highly competitive with major players such as Samsung Electronics, Nichia Corporation, Seoul Semiconductor, Lumileds, Ams-Osram, Everlight Electronics, MLS, Cree LED, LG Innotek, and Toyoda Gosei focusing on innovation, R&D investments, and global expansion.
- Regionally, Asia-Pacific dominated with 36% share, followed by North America at 27%, Europe at 25%, while Latin America and the Middle East & Africa accounted for 7% and 5%
Market Segmentation Analysis:
By Packaging Type
Surface mount device (SMD) packaging dominated the LED packaging market in 2024, holding 48% share. Its widespread use is driven by compact size, high efficiency, and versatility across lighting applications. SMD LEDs are extensively adopted in general lighting, automotive, and display technologies due to their improved heat dissipation and durability. Manufacturers prefer SMD packaging for cost efficiency and scalability in mass production. With rising demand for energy-efficient lighting solutions and growing LED penetration in residential and commercial sectors, SMD packaging continues to lead over chip-on-board (COB) and ceramic alternatives.
- For instance, Samsung Electronics has developed numerous advanced LED technologies, including innovations in phosphor blends and thermal management for automotive lighting. The company has made incremental and significant improvements in luminous efficacy over time, such as achieving a record-high efficacy of 235 lumens per watt with a new package in 2021.
By Power Range
Mid-power LEDs, ranging from 0.5 W to 1 W, captured the largest share of the LED packaging market in 2024, accounting for 44% share. These LEDs strike a balance between energy efficiency and brightness, making them ideal for indoor lighting, displays, and signage. They offer longer lifespans, lower thermal output, and cost benefits compared to high-power variants. The rapid adoption of mid-power LEDs in commercial lighting, office spaces, and retail environments has fueled demand. Their expanding role in smart lighting systems and IoT-enabled applications reinforces their dominance across global markets.
- For instance, Cree LED, a subsidiary of Penguin Solutions (formerly SMART Global Holdings), supplies a broad portfolio of mid-power, high-power, and other application-optimized LED components.
By Application
General lighting led the LED packaging market in 2024, representing 52% share. Rising adoption of LEDs for residential, commercial, and industrial illumination has accelerated this segment’s dominance. Governments worldwide promote LED use through energy-saving policies and subsidies, strengthening their integration into sustainable building projects. Improved performance of LED packaging technologies, including better heat management and higher luminous efficiency, further boosts application in general lighting. While automotive and backlighting applications are growing steadily, especially with EV adoption and display demand, general lighting remains the key driver of global LED packaging market expansion.
Key Growth Drivers
Rising Demand for Energy-Efficient Lighting
Global initiatives promoting energy conservation drive adoption of LED technology, with LED packaging playing a central role in performance and efficiency. Governments support the transition through subsidies, tax benefits, and stricter energy regulations, accelerating replacement of conventional lighting. LED packages deliver superior brightness, longer lifespan, and reduced power consumption, making them a preferred choice for residential, commercial, and industrial lighting. Growing awareness of sustainability among consumers and enterprises further boosts demand. This shift toward eco-friendly lighting continues to reinforce the dominance of LED packaging solutions worldwide.
- For instance, ams OSRAM (formerly OSRAM Opto Semiconductors) achieved €1.448 billion in opto semiconductor revenue in fiscal year 2024, continuing to advance energy-efficient LED technology for commercial applications.
Expanding Automotive Applications
The automotive sector is increasingly adopting LED packaging solutions for headlamps, tail lamps, and interior lighting. High-power and mid-power LED packages improve brightness, thermal management, and durability, meeting evolving safety and design standards. With the rise of electric and autonomous vehicles, manufacturers demand advanced LED packaging for enhanced aesthetics and energy savings. Automakers also integrate adaptive and smart lighting systems, driving innovation in this space. The growing emphasis on energy-efficient, high-performance vehicle lighting ensures that automotive applications remain a strong growth driver for the LED packaging market.
- For instance, Nichia Corporation is a prominent supplier of automotive LEDs, including the advanced µPLS (Micro Pixelated Light Solution) developed with Infineon, which was implemented in premium vehicles starting in 2023.
Growth in Display and Backlighting Systems
The surge in demand for smartphones, televisions, laptops, and digital signage has accelerated LED packaging use in backlighting. Surface mount devices and mid-power LEDs dominate this space due to compact size and efficient luminous output. Increasing penetration of high-definition and OLED displays further supports adoption of advanced LED packaging technologies. Expansion of e-commerce and advertising industries boosts demand for digital display solutions, where LED packages ensure enhanced brightness and reliability. As global consumers shift toward high-quality displays, LED packaging remains a critical component enabling superior visual performance.
Key Trends and Opportunities
Adoption of Smart and Connected Lighting
Smart lighting systems integrated with IoT and AI create new opportunities for LED packaging. Mid-power and COB LED packages are increasingly used in connected lighting for homes, offices, and smart cities. These systems enable remote control, energy monitoring, and adaptive illumination, enhancing user convenience and efficiency. Governments investing in smart infrastructure further drive demand for LED packaging technologies. As IoT ecosystems expand, the integration of intelligent lighting with energy management platforms offers manufacturers strong opportunities to capitalize on this trend.
- For instance, Signify (formerly Philips Lighting) has deployed millions of IoT-connected LED light points globally, enabling real-time energy monitoring and automated dimming for commercial buildings.
Miniaturization and Advanced Materials Development
The trend toward compact and high-performance electronic devices accelerates innovation in LED packaging design. Manufacturers focus on developing smaller, thermally efficient packages with improved reliability and luminous efficacy. Use of advanced ceramic substrates and innovative encapsulation materials enhances durability and performance under harsh conditions. This supports adoption in automotive, aerospace, and industrial applications. Miniaturized LED packaging also aligns with design trends in consumer electronics and wearable devices. Continuous R&D in advanced materials positions manufacturers to deliver high-value solutions, expanding the addressable market for LED packaging.
- For instance, the former Cree Corporate, now Cree LED, has demonstrated the capability of its ceramic-based, high-power XLamp LEDs to deliver excellent luminous efficacy (over 140 lm/W has been reported), operate at high junction temperatures (up to 150°C), and achieve long L70 lifetimes exceeding 60,000 hours under standard testing conditions.
Key Challenges
High Initial Manufacturing and Development Costs
Despite long-term savings, LED packaging requires significant upfront investment in advanced manufacturing technologies and materials. Complex processes, including thermal management and encapsulation, add to production expenses. Smaller companies face barriers in adopting these technologies due to limited budgets. This cost challenge restricts widespread adoption in price-sensitive markets and creates reliance on subsidies and incentives. Without cost-competitive solutions, LED packaging adoption may remain concentrated in developed regions with stronger purchasing power.
Thermal Management and Performance Limitations
Effective heat dissipation remains a critical challenge for LED packaging, especially in high-power applications. Excessive heat reduces lifespan, lowers efficiency, and limits performance in demanding environments like automotive and industrial systems. Advanced materials and design improvements are required to address these issues, but they increase costs and manufacturing complexity. Failure to manage thermal challenges may slow adoption in high-growth areas such as electric vehicles and large-scale industrial lighting. Overcoming these limitations is vital for sustaining long-term competitiveness in the LED packaging market.
Regional Analysis
North America
North America held 27% share of the LED packaging market in 2024, driven by strong adoption in general lighting, automotive, and display applications. The United States leads the region with high demand for energy-efficient solutions supported by government programs promoting sustainable infrastructure. The rise of smart homes and offices further accelerates the use of advanced LED packages. Automotive manufacturers also contribute significantly, adopting high-power LED packages for headlamps and interior lighting. Investments in R&D and a strong presence of technology companies ensure North America remains a key market for LED packaging innovation and growth.
Europe
Europe accounted for 25% share of the LED packaging market in 2024, supported by strict energy efficiency regulations and widespread LED adoption across residential and industrial sectors. Countries such as Germany, France, and the United Kingdom are at the forefront of implementing eco-friendly lighting solutions. Automotive applications play a major role, with European automakers adopting advanced LED packages to improve vehicle performance and aesthetics. Growing investments in smart city projects and sustainable infrastructure also fuel demand. The region’s strong emphasis on environmental goals ensures steady growth for the LED packaging market.
Asia-Pacific
Asia-Pacific dominated the LED packaging market in 2024 with 36% share, making it the largest regional market. China, Japan, South Korea, and India lead in LED manufacturing and consumption, supported by large-scale production facilities and cost advantages. Expanding demand from consumer electronics, general lighting, and automotive sectors drives growth. Governments across the region encourage energy-saving programs and subsidies for LED adoption, reinforcing market expansion. Rising urbanization and infrastructure development further support demand for LED packaging. With growing exports and strong investments in R&D, Asia-Pacific continues to lead global production and innovation in LED packaging.
Latin America
Latin America represented 7% share of the LED packaging market in 2024, with Brazil and Mexico being key contributors. Rising demand for energy-efficient lighting in residential, commercial, and public infrastructure projects drives adoption. Government initiatives supporting renewable energy and efficient lighting systems also contribute to market growth. The region’s automotive sector increasingly integrates LED packages for safety and design improvements. However, economic constraints and limited manufacturing capabilities restrict faster adoption. Partnerships with global LED manufacturers and increasing awareness of energy savings are expected to create steady growth opportunities across Latin America.
Middle East & Africa
The Middle East & Africa accounted for 5% share of the LED packaging market in 2024, with growth led by Gulf countries and South Africa. Rising investments in infrastructure, smart cities, and commercial projects boost demand for LED solutions. Government initiatives aimed at reducing energy consumption support the adoption of LED lighting in public and industrial sectors. Automotive and general lighting are key application areas, while growing urbanization strengthens market opportunities. However, limited local production and higher costs of advanced packaging technologies remain challenges. Despite this, expanding infrastructure investments will gradually enhance regional market penetration.
Market Segmentations:
By packaging type
- Surface mount device
- Chip on Board (COB)
- Ceramic packages
- Through-hole
By power range
- Low-power LEDs (0.3 W-0.5 W)
- Mid-power LEDs (0.5 W-1 W)
- High-power LEDs (1 W and above)
By application
- General lighting
- Backlighting
- Automotive
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the LED packaging market is defined by leading players such as Samsung Electronics Co. Ltd., Nichia Corporation, Seoul Semiconductor Co., Ltd., Lumileds Holding B.V., Ams-Osram AG, Everlight Electronics Co., Ltd., MLS Co., Ltd., Cree LED, LG Innotek, and Toyoda Gosei Co., Ltd. These companies focus on advancing packaging technologies such as surface mount device (SMD), chip-on-board (COB), and ceramic solutions to enhance efficiency, heat dissipation, and brightness. Strategic initiatives include expanding production facilities, investing in miniaturization, and integrating smart features to support applications in general lighting, automotive, and consumer electronics. Partnerships with automotive OEMs and consumer electronics firms strengthen their market position, while investments in R&D drive innovations in high-power and mid-power LED packaging. Sustainability and compliance with energy regulations remain key focus areas, pushing companies to develop eco-friendly and cost-effective solutions. Competition is intense, with firms leveraging global reach, innovation, and strategic collaborations to secure growth.
Key Player Analysis
- Samsung Electronics Co. Ltd.
- Nichia Corporation
- Seoul Semiconductor Co., Ltd.
- Lumileds Holding B.V.
- Ams-Osram AG
- Everlight Electronics Co., Ltd.
- MLS Co., Ltd.
- Cree LED
- LG Innotek
- Toyoda Gosei Co., Ltd.
Recent Developments
- In August 2025, Samsung was reported to push System-on-Panel (SoP) packaging for ultra-large panels, which is an advanced packaging method for semiconductors, potentially affecting LED driver / display integration.
- In March 2025, ams-OSRAM, along with Nichia, developed micro-LED solutions that enable over a 100× increase in resolution vs discrete LED matrix modes, representing packaging innovation in microLED integration.
- In January 2025, Nichia began mass production of a deep UV LED (280 nm, NCSU434D) in December 2024, pushing advances in package for UV applications.
- In November 2023, Samsung published about its advanced heterogeneous integration / advanced packaging business combining memory, logic, chiplets, etc.
Report Coverage
The research report offers an in-depth analysis based on packaging type, power range, application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will grow with rising adoption of energy-efficient lighting solutions worldwide.
- General lighting will remain the largest application segment supported by government energy policies.
- Automotive demand will expand as EVs and smart lighting systems gain momentum.
- Mid-power LED packages will dominate due to efficiency and cost-effectiveness.
- Chip-on-board (COB) and ceramic packages will see increasing use in high-performance applications.
- Miniaturization will drive adoption in consumer electronics and portable devices.
- Smart and connected lighting systems will create strong opportunities for innovation.
- Asia-Pacific will maintain leadership supported by large-scale manufacturing and exports.
- North America and Europe will grow steadily with automotive and industrial applications.
- Competition will intensify as players invest in R&D and strategic partnerships.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Government Energy Efficiency Initiatives
Global and regional government policies promoting energy conservation, such as subsidies and stricter energy regulations, are accelerating the adoption of LED technology and, by extension, advanced LED packaging solutions. These initiatives drive the replacement of traditional lighting with LEDs in residential, commercial, and industrial sectors.
Expansion of Automotive LED Applications
The automotive industry is increasingly integrating LED packaging for headlamps, tail lamps, and interior lighting, driven by the need for improved brightness, energy savings, and advanced design features. The rise of electric and autonomous vehicles further boosts demand for high-performance LED packaging.
Growth in Smart and Connected Lighting
The proliferation of IoT-enabled and smart lighting systems is creating new opportunities for LED packaging, especially for mid-power and COB packages. These systems require advanced packaging for features like remote control, adaptive illumination, and energy monitoring, fueling market growth.
Miniaturization and Advanced Materials
Trends toward smaller, more efficient electronic devices are pushing manufacturers to innovate in LED packaging design, focusing on miniaturization and the use of advanced materials. This enables higher reliability, better thermal management, and supports adoption in compact consumer electronics and wearables.
Rising Demand from Display and Backlighting Systems
The surge in demand for high-definition displays in smartphones, TVs, laptops, and digital signage is driving the use of advanced LED packaging, particularly SMD and mid-power LEDs. These applications require compact, efficient, and reliable LED packages to deliver superior visual performance.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for LED Packaging market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the LED Packaging market projected to grow between 2025 and 2032?
Which LED Packaging market segment held the largest share in 2024?
What are the primary factors fueling the growth of the LED Packaging market?
Who are the leading companies in the LED Packaging market?
Which region commanded the largest share of the LED Packaging market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 General lighting
- 1.2.2 Backlighting
- 1.2.3 Automotive
- 1.2.4 Others
- 1.3 By Power Range
- 1.3.1 Low-power LEDs (0.3 W-0.5 W)
- 1.3.2 Mid-power LEDs (0.5 W-1 W)
- 1.3.3 High-power LEDs (1 W and above)
- 1.4 By Packaging Type
- 1.4.1 Surface mount device (SMD)
- 1.4.2 Chip on Board (COB)
- 1.4.3 Ceramic packages
- 1.4.4 Through-hole
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 17.43 billion → 2032: USD 24.79 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global LED Packaging Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global LED Packaging Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global LED Packaging Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global LED Packaging Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global LED Packaging Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global LED Packaging Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global LED Packaging Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global LED Packaging Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 17.43 billion → 2032: USD 24.79 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global LED Packaging Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 General lighting
- 12.3.7.2 Backlighting
- 12.3.7.3 Automotive
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Power Range - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Low-power LEDs (0.3 W-0.5 W)
- 12.4.7.2 Mid-power LEDs (0.5 W-1 W)
- 12.4.7.3 High-power LEDs (1 W and above)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Packaging Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Surface mount device (SMD)
- 12.5.7.2 Chip on Board (COB)
- 12.5.7.3 Ceramic packages
- 12.5.7.4 Through-hole
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global LED Packaging End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global LED Packaging Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global LED Packaging Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global LED Packaging Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Samsung Electronics Co. Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Nichia Corporation
- 18.4 Seoul Semiconductor Co., Ltd.
- 18.5 Lumileds Holding B.V.
- 18.6 Ams-Osram AG
- 18.7 Everlight Electronics Co., Ltd.
- 18.8 MLS Co., Ltd.
- 18.9 Cree LED
- 18.10 LG Innotek
- 18.11 Toyoda Gosei Co., Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

