
LED lights Market Overview:
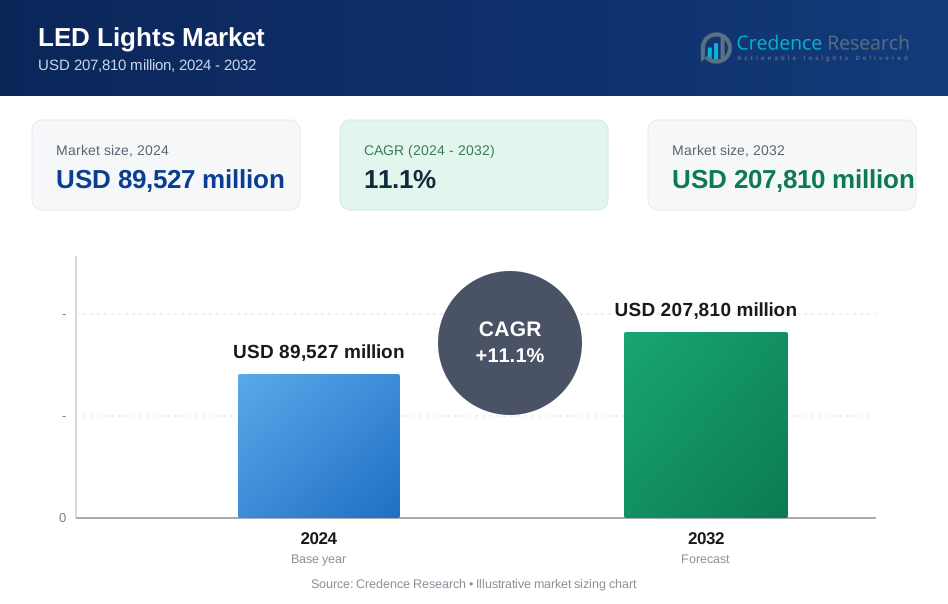
The global LED lights market size was valued at USD 89,527 million in 2024 and is anticipated to reach USD 207,810 million by 2032, at a CAGR of 11.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| LED lights Market Size 2024 | USD 89,527 million |
| LED lights Market, CAGR | 11.1% |
| LED lights Market Size 2032 | USD 207,810 million |
The global LED lights market is led by top players including Signify Holding, Acuity Brands, Panasonic Corporation, Seoul Semiconductor, Zumtobel Group, and Cree Lighting. These companies dominate through broad product portfolios, strong R&D capabilities, and expansive global distribution. Signify and Acuity Brands lead in smart lighting systems, while Seoul Semiconductor and Zumtobel focus on industrial and automotive-grade LEDs. Panasonic and Cree strengthen their presence in energy-efficient and commercial lighting segments. Asia-Pacific holds the largest market share at over 40%, driven by large-scale manufacturing, rising urban infrastructure, and strong government support in China, India, and Japan. Europe follows with nearly 25%, supported by energy regulations and smart city investments.

LED lights Market Insights
- The global LED lights market was valued at USD 89,527 million in 2024 and is projected to reach USD 207,810 million by 2032, growing at a CAGR of 11.1% during the forecast period.
- Market growth is driven by strong demand for energy-efficient lighting, government bans on incandescent bulbs, and large-scale replacement of conventional lighting across residential, commercial, and public infrastructure.
- Key trends include rising adoption of smart and connected LED systems, growth of horticultural and UV LEDs, and increasing use of SMD and COB LEDs, which together account for a major share of installations.
- The competitive landscape features global players such as Signify, Acuity Brands, Panasonic, and Seoul Semiconductor, competing on smart lighting platforms, efficiency, and product breadth.
- Asia-Pacific leads with over 40% market share, followed by Europe at around 25% and North America above 20%, while illumination applications dominate overall segment demand.
LED lights Market Segmentation Analysis:
By LED Type
SMD LEDs hold the largest market share in the LED lights market due to their superior brightness, compact size, and efficiency across varied applications. Their versatility enables use in residential, commercial, and industrial lighting systems. The segment benefits from rapid adoption in smart lighting, backlighting, and automotive interiors. COB LEDs follow closely, offering high lumen density and thermal efficiency, ideal for high-power applications. Traditional and miniature LEDs serve cost-sensitive uses, while RGB and UV/IR LEDs gain traction in entertainment, medical, and sensor-based systems. OLEDs and high-power LEDs also find niche demand in display and industrial applications.
- For instance, Nichia’s 757 series SMD LEDs (like the Nichia NFSW757H and Nichia NFSW757G variants) offer an efficacy of up to 230 lumens per watt at 65 mA with a size of 3.0×3.0 mm, and are used widely in bulbs and panels.
By Application
Illumination/Lighting Applications dominate the market with the highest revenue share, driven by large-scale deployment in homes, offices, streets, and factories. Energy savings, long lifespan, and favorable regulations support widespread replacement of conventional bulbs. Display & signage applications form the second-largest segment, led by advertising, transportation hubs, and digital billboards. Specialty and scientific uses, including UV sterilization, spectroscopy, and optical communication, contribute steady growth. Security applications also expand with growing use of IR LEDs in surveillance systems and motion sensors, further supported by increasing adoption of smart home technologies and perimeter security setups.
- For instance, Philips Master LEDtube InstantFit products last over 50,000 hours and reduce energy use by up to 50% in offices and schools.
By Industry
The consumer electronics segment leads in market share, fueled by high-volume usage in display panels, indicators, backlights, and wearables. LEDs enhance device slimness, brightness, and energy efficiency, boosting integration in smartphones, TVs, and laptops. The automotive segment ranks second, driven by LED headlamps, ambient lighting, and dashboard indicators. Agriculture & horticulture applications grow due to LED grow lights that support controlled environment farming. Industrial equipment uses LEDs in machine vision and status indicators. Highway & roads lighting expands through government-led streetlight replacement programs. The “Others” category includes sectors such as healthcare, aviation, and marine.
LED lights Market Key Growth Drivers
Global Push for Energy Efficiency and Emission Reduction
Governments worldwide actively promote LED lighting as part of climate goals and energy-efficiency mandates. LEDs consume up to 80% less power than traditional incandescent bulbs, making them central to national energy conservation plans. Programs like India’s UJALA scheme and the EU’s EcoDesign Directive have accelerated large-scale LED adoption across public infrastructure and residential sectors. Incentives, subsidies, and regulatory bans on inefficient lighting further boost demand. In developing economies, LEDs improve grid stability and reduce peak power loads. In commercial sectors, operational cost savings from LED retrofitting make adoption financially attractive. These policy-driven initiatives ensure strong baseline demand and long-term market growth for LED technologies across both developed and emerging regions.
- For instance, under India’s UJALA program, over 360 million LED bulbs were distributed by Energy Efficiency Services Limited (EESL), cutting annual energy consumption by nearly 47 billion kWh.
Expanding Urban Infrastructure and Smart City Projects
Rapid urbanization, particularly in Asia-Pacific and Africa, drives demand for efficient lighting in new infrastructure. Smart city initiatives integrate LED lights with IoT-enabled systems for adaptive lighting, motion sensing, and energy monitoring. Municipalities favor LEDs for their long service life, low maintenance, and controllability. Projects in cities like Dubai, Singapore, and Barcelona demonstrate widespread LED integration in streets, public spaces, and transportation hubs. In smart buildings, LEDs support automation through centralized lighting control systems, enhancing comfort and efficiency. The growing adoption of digital infrastructure further accelerates LED usage in parking systems, public safety, and architectural lighting. This trend ensures sustained uptake across government and commercial infrastructure segments.
- For example, Barcelona deployed over 1,100 smart LED streetlights with motion sensors and remote-control systems via its Urban Platform.
Growing Demand Across Automotive and Consumer Electronics Industries
The automotive sector increasingly adopts LEDs for headlamps, tail lights, interior accents, and ambient lighting. OEMs use LEDs to improve vehicle aesthetics, energy efficiency, and design flexibility. Daytime running lights (DRLs) and adaptive lighting systems enhance road safety and compliance with global vehicle regulations. In consumer electronics, LEDs support high-resolution displays, thinner devices, and power savings in smartphones, laptops, TVs, and wearables. Miniaturization and multi-color capability fuel innovations in RGB lighting for gaming and smart home devices. With both industries experiencing rising demand for feature-rich, compact, and energy-saving components, LEDs are firmly positioned as the preferred lighting technology across these high-volume verticals.
LED lights Market Key Trends & Opportunities
Integration of LEDs with IoT and Smart Lighting Systems
The shift toward connected lighting transforms LEDs from simple light sources to intelligent network nodes. Smart LEDs, paired with IoT platforms, enable remote operation, dimming, occupancy sensing, and adaptive brightness. This enhances energy optimization in commercial buildings, offices, and smart homes. Voice-assistant integration (e.g., Alexa, Google Assistant) supports home automation trends. Wireless protocols like Zigbee, Wi-Fi, and Bluetooth facilitate seamless connectivity. Companies such as Signify, Acuity Brands, and Cree focus on intelligent lighting platforms for both retrofits and new installations. This trend creates strong opportunities for solution providers that combine hardware, software, and analytics, driving recurring revenue models through lighting-as-a-service (LaaS) offerings.
- For instance, Signify’s Interact platform manages over 160 million connected light points globally, enabling real-time dimming, scheduling, and energy analytics across offices, stadiums, and highways.
Surge in Horticultural and UV/IR LED Applications
Niche applications are emerging as significant growth pockets in the LED market. In agriculture, horticultural LEDs offer controlled spectra for plant growth in greenhouses and vertical farms. Tailored light wavelengths optimize yield, shorten growth cycles, and reduce pesticide use. UV LEDs are gaining ground in water and air purification systems due to their effectiveness in sterilization without chemicals. IR LEDs power advanced features in surveillance cameras, gesture recognition, and biometric security. These specialized applications benefit from performance advancements and cost reduction in LED technology. As awareness and ROI improve, manufacturers increasingly invest in R&D to meet growing demand in these technically demanding and regulation-sensitive sectors.
LED lights Market Key Challenges
Price Sensitivity and Market Saturation in General Lighting
The LED general lighting segment faces increasing commoditization, particularly in residential and commercial bulbs. Price wars among manufacturers, especially in Asia, reduce margins and pressure small players. As many regions near full penetration of LED retrofits, replacement cycles slow down, leading to demand flattening. Customers increasingly compare products based on price, not performance, forcing vendors to reduce costs and streamline portfolios. While premium LED features such as dimmability or tunable white offer differentiation, uptake remains limited in price-sensitive markets. This price-driven competition restricts profitability and innovation, compelling manufacturers to seek growth in premium and application-specific segments such as smart lighting, UV/IR, and automotive.
Thermal Management and Component Integration Complexities
Despite performance benefits, LEDs generate significant heat, particularly in high-power and compact applications. Managing thermal output without compromising product size or longevity is a key challenge. Poor heat dissipation reduces lumen output, accelerates aging, and affects safety. Advanced heat sink designs and materials increase system cost and complexity. In compact electronics and automotive lights, integration of drivers, sensors, and control units into small housings further complicates design. Reliability issues arise when thermal management is suboptimal. OEMs and lighting designers must balance performance, form factor, and cost, which delays time-to-market and limits mass adoption in some advanced use cases.
LED lights Market Regional Analysis
North America
North America holds a significant share of the global LED lights market, driven by early adoption of energy-efficient technologies and strong regulatory support. The region accounts for over 20% of the market, led by the U.S., where government initiatives such as ENERGY STAR and rebate programs promote LED usage. Commercial and industrial sectors actively replace traditional lighting with smart LED systems to reduce energy bills and emissions. Infrastructure upgrades in public spaces, offices, and highways further boost demand. The presence of major players like Acuity Brands and Cree Inc. supports ongoing innovation and competitive pricing in the region.
Europe
Europe represents nearly 25% of the global LED lights market, with growth driven by strict energy regulations and sustainability targets under the European Green Deal. Countries like Germany, France, and the U.K. have phased out inefficient lighting, creating robust demand for LED retrofits in residential, commercial, and municipal sectors. The EU’s EcoDesign and RoHS directives further accelerate LED adoption. Smart city investments and heritage building renovations continue to fuel demand for adaptive and aesthetic lighting solutions. European manufacturers emphasize eco-friendly designs and circular lighting systems, reinforcing the region’s leadership in sustainable and intelligent lighting deployments.
Asia-Pacific
Asia-Pacific dominates the global LED lights market with over 40% share, led by China, India, Japan, and South Korea. China, as the largest producer and consumer, drives demand through urban infrastructure, industrial lighting, and exports. India’s UJALA scheme and smart city missions accelerate public LED deployments. Japan and South Korea focus on smart, high-performance lighting for urban and commercial spaces. Rapid urbanization, rising middle-class income, and strong manufacturing capabilities fuel regional growth. Cost advantages, government subsidies, and mass production scale help regional players maintain competitive pricing and global export momentum in both basic and advanced LED technologies.
Latin America
Latin America contributes a moderate share of around 6–8% to the global LED lights market, with growth anchored in urban expansion, rising electricity costs, and infrastructure modernization. Brazil and Mexico lead regional demand due to commercial and residential retrofitting programs. Government energy efficiency policies support public lighting upgrades and promote LED-based solutions in transportation and industrial facilities. Local manufacturing remains limited, with high reliance on imports from Asia. As awareness increases around cost-saving potential and environmental benefits, LED adoption accelerates in urban and semi-urban zones, especially in smart city pilot projects and retail developments.
Middle East & Africa (MEA)
The Middle East & Africa region holds a smaller share of approximately 5–6%, but shows rising demand due to urban infrastructure projects and energy diversification efforts. GCC countries, especially the UAE and Saudi Arabia, invest heavily in smart city lighting, sustainable construction, and hospitality sectors. Government-backed initiatives promote LED retrofits in public buildings and streets to reduce grid pressure. Africa sees increasing demand in off-grid and solar-integrated LED systems to address rural electrification. Though market penetration remains uneven, rising construction, tourism growth, and infrastructure funding continue to create long-term opportunities across MEA’s commercial and residential lighting segments.
LED lights Market Segmentations:
By LED Type:
- Traditional LEDs
- SMD LEDs
- High-Power LEDs
- RGB LEDs
- UV/IR LEDs
- OLEDs
- Miniature LEDs
- Chip-On-Board (COB) LEDs
By Application:
- Display & Signage Applications
- Illumination/Lighting Applications
- Specialty Applications
- Scientific and Communication Applications
- Security Applications
By Industry:
- Consumer Electronics
- Automotive
- Agriculture & Horticulture
- Industrial Equipment
- Highway & Roads
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
LED lights Market Competitive Landscape
The LED lights market remains highly competitive, with established players and innovative entrants vying for share through product differentiation, pricing strategies, and technological advancement. Companies like Signify Holding, Acuity Brands, Panasonic Corporation, and Seoul Semiconductor lead with strong global presence, diversified product lines, and smart lighting portfolios. Firms such as Cree Lighting and Zumtobel Group focus on high-performance lighting for industrial and commercial sectors, while Nanoleaf and YEELIGHT cater to smart home and decorative lighting segments. Asian manufacturers contribute significantly to price competitiveness and volume exports. Partnerships, mergers, and acquisitions continue to shape the market as players expand into connected lighting, horticultural LEDs, and automotive applications. Competitive pressure drives ongoing R&D investment, particularly in energy efficiency, miniaturization, and intelligent lighting platforms. Branding, sustainability compliance, and integration with IoT ecosystems are becoming key differentiators across residential, commercial, and public infrastructure projects.
Key Player Analysis
- Panasonic Corporation
- Signify Holding
- Acuity Brands, Inc.
- Seoul Semiconductor Co., Ltd.
- Zumtobel Group AG
- Hubbell
- Cree Lighting USA LLC
- LSI Industries Inc.
- Siteco GmbH
- Dialight
- Nanoleaf
- SAVANT TECHNOLOGIES LLC
- YEELIGHT
- Syska
- Halonix Technologies Private Limited
Recent Developments
- In March 2025, Signify Holding announced a joint venture with Dixon Technologies (India) Ltd., subject to regulatory approvals. This partnership aims to manufacture high-quality lighting products and accessories for prominent brands in the competitive Indian market. The joint venture will focus on producing a wide range of innovative and cost-effective lighting solutions, including LED bulbs, downlights, spotlights, battens, rope lights, strips, and various LED lighting accessories, all made in India.
- In 2023, YEELIGHT launched its new LED product, The Yeelight Beam, featuring a tabletop-style design with a headphone stand. This light is easy to set up and can be controlled with multiple smart control applications such as Apple HomeKit, Amazon Alexa, and Google.
- In October 2023, electric company Halonix Technologies launched an LED bulb, UP-DOWN GLOW, featuring three switch-enabled modes in India. This light's dome, an upper part and stem, and a lower part glow in multiple colors, enhancing the consumer's experience.
Report Coverage
The research report offers an in-depth analysis based on LED Type, Application, Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The LED lights market is expected to grow steadily at a strong double-digit CAGR through 2032.
- Smart LED adoption will rise sharply across residential, commercial, and municipal sectors worldwide.
- Horticultural and UV/IR LEDs will gain share due to increased demand in agriculture and sanitation.
- Integration with IoT platforms will enhance the value proposition of LED lighting systems.
- Asia-Pacific will remain the dominant region, maintaining over 40% of global market share.
- Europe and North America will see growth in smart city projects and retrofitting programs.
- SMD and COB LEDs will retain the largest share due to high efficiency and design flexibility.
- Automotive and consumer electronics industries will expand LED usage for advanced lighting features.
- Price competition and market saturation in general lighting may slow margins for basic products.
- Companies will focus on energy-saving designs, smart controls, and new application-specific solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Global Push for Energy Efficiency and Emission Reduction
Government mandates and incentives to phase out incandescent bulbs and reduce energy consumption are accelerating the adoption of LED lighting worldwide. LEDs' ability to cut power usage by up to 80% compared to traditional lighting makes them central to national energy conservation and climate action plans.
Expanding Urban Infrastructure and Smart City Projects
Rapid urbanization and the proliferation of smart city initiatives, especially in Asia-Pacific and the Middle East, are driving large-scale deployment of LED lighting in streets, public spaces, and buildings. Integration with IoT platforms for adaptive and energy-efficient lighting further boosts demand.
Growth in Automotive and Consumer Electronics Industries
Automotive manufacturers are increasingly using LEDs for headlamps, interior lighting, and safety features, while consumer electronics companies integrate LEDs into displays, backlights, and wearables. The demand for compact, energy-efficient, and feature-rich lighting solutions in these sectors is fueling market expansion.
Rising Adoption of Smart and Connected Lighting Systems
The shift toward smart homes and buildings is increasing demand for connected LED lighting that can be remotely controlled, dimmed, and integrated with voice assistants and building management systems. This trend is creating new revenue streams and driving upgrades in both residential and commercial sectors.
Government-Led Infrastructure Modernization and Retrofitting Programs
Public sector initiatives to upgrade streetlights, schools, and municipal buildings with LED solutions are providing a stable foundation for market growth. These programs, often supported by subsidies and regulatory mandates, are accelerating the replacement of conventional lighting on a mass scale.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the LED lights market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the LED lights market projected to grow between 2024 and 2032?
Which LED lights market segment held the largest share in 2024?
What are the primary factors fueling the growth of the LED lights market?
Who are the leading companies in the LED lights market?
Which region commanded the largest share of the LED lights market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Industry
- 1.2.1 Consumer Electronics
- 1.2.2 Automotive
- 1.2.3 Agriculture & Horticulture
- 1.2.4 Industrial Equipment
- 1.2.5 Highway & Roads
- 1.2.6 Others
- 1.3 By LED Type
- 1.3.1 Traditional LEDs
- 1.3.2 SMD LEDs
- 1.3.3 High-Power LEDs
- 1.3.4 RGB LEDs
- 1.3.5 UV/IR LEDs
- 1.3.6 OLEDs
- 1.3.7 Miniature LEDs
- 1.3.8 Chip-On-Board (COB) LEDs
- 1.4 By Application
- 1.4.1 Illumination/Lighting Applications
- 1.4.2 Display & Signage Applications
- 1.4.3 Specialty Applications
- 1.4.4 Scientific and Communication Applications
- 1.4.5 Security Applications
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 89,527 million → 2032: USD 207,810 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global LED Lights Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global LED Lights Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global LED Lights Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global LED Lights Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global LED Lights Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global LED Lights Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global LED Lights Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global LED Lights Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 89,527 million → 2032: USD 207,810 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global LED Lights Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Industry - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Consumer Electronics
- 12.3.7.2 Automotive
- 12.3.7.3 Agriculture & Horticulture
- 12.3.7.4 Industrial Equipment
- 12.3.7.5 Highway & Roads
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By LED Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Traditional LEDs
- 12.4.7.2 SMD LEDs
- 12.4.7.3 High-Power LEDs
- 12.4.7.4 RGB LEDs
- 12.4.7.5 UV/IR LEDs
- 12.4.7.6 OLEDs
- 12.4.7.7 Miniature LEDs
- 12.4.7.8 Chip-On-Board (COB) LEDs
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Illumination/Lighting Applications
- 12.5.7.2 Display & Signage Applications
- 12.5.7.3 Specialty Applications
- 12.5.7.4 Scientific and Communication Applications
- 12.5.7.5 Security Applications
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global LED Lights End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global LED Lights Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global LED Lights Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global LED Lights Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Signify Holding
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Acuity Brands
- 18.4 Panasonic Corporation
- 18.5 Seoul Semiconductor
- 18.6 Zumtobel Group
- 18.7 Cree Lighting
- 18.8 Nanoleaf
- 18.9 YEELIGHT
- 18.10 Halonix Technologies
- 18.11 Hubbell
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

