
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
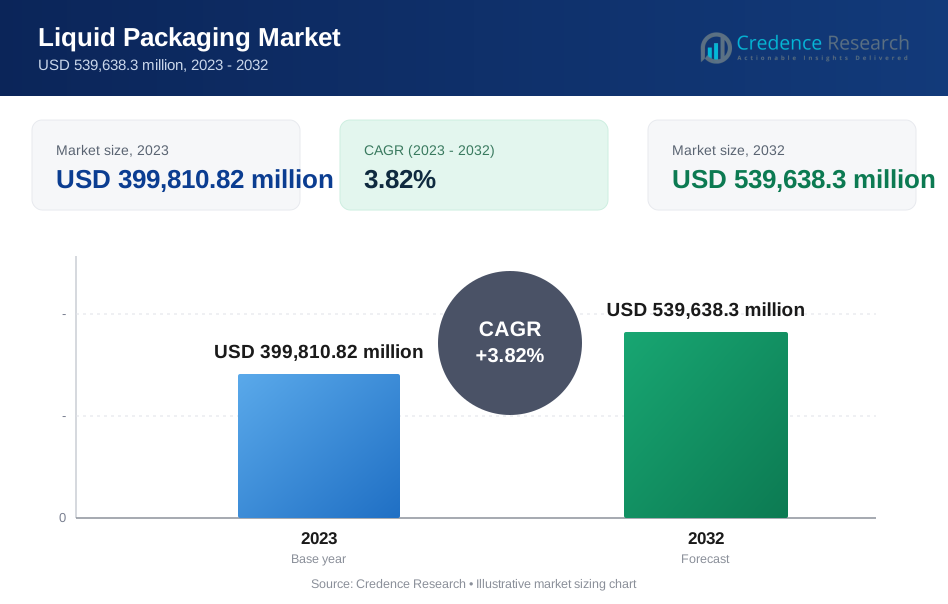
| Liquid Packaging Market Size 2023 | USD 399,810.82 Million |
| Liquid Packaging Market, CAGR | 3.82% |
| Liquid Packaging Market Size 2032 | USD 539,638.3 Million |
Market Overview
The global Liquid Packaging market is projected to grow from USD 399,810.82 million in 2023 to an estimated USD 539,638.3 million by 2032, with a compound annual growth rate (CAGR) of 3.82% from 2024 to 2032. This substantial market size reflects the increasing demand for liquid packaging solutions across various industries, including beverages, pharmaceuticals, and personal care products. The market is expanding due to advancements in packaging technology, which enhance the durability and sustainability of liquid packaging materials. The growth trajectory indicates a robust demand for innovative packaging solutions that meet stringent regulatory standards and consumer preferences.
Several key drivers and trends are shaping the liquid packaging market. The rising consumption of beverages, particularly bottled water and functional drinks, is a significant driver. Additionally, the pharmaceutical industry's growth, driven by increased health awareness and the demand for liquid medications, is fueling market expansion. Trends such as eco-friendly packaging, which reduce environmental impact, and the integration of smart packaging technologies that enhance product safety and consumer interaction, are gaining traction. The shift towards lightweight and recyclable materials is also prominent, reflecting a broader trend towards sustainability and resource efficiency.
Geographically, the liquid packaging market is witnessing varied growth patterns across different regions. North America and Europe are mature markets with a strong focus on sustainability and advanced packaging technologies. The Asia-Pacific region is experiencing rapid growth due to increasing urbanization, rising disposable incomes, and a burgeoning middle class with heightened consumption of packaged goods. Key players in the liquid packaging market include Tetra Pak International S.A., Amcor Limited, The Dow Chemical Company, and Reynolds Group Holdings Limited. These companies are at the forefront of innovation, continually investing in research and development to introduce advanced packaging solutions that cater to evolving market demands and regulatory requirements.
Market Drivers
Rising Demand in the Beverage Industry
The global liquid packaging market is significantly driven by the burgeoning demand within the beverage industry. This sector, encompassing a wide array of products such as bottled water, soft drinks, juices, alcoholic beverages, and functional drinks, represents a substantial portion of the overall liquid packaging market. The increasing consumer preference for convenient, ready-to-drink beverages has led to an upsurge in demand for innovative and efficient packaging solutions. Bottled water, in particular, has seen exponential growth due to heightened health consciousness and concerns over water purity. Similarly, the functional drinks segment, which includes energy drinks, sports drinks, and nutraceutical beverages, is expanding rapidly, further propelling the need for diverse and specialized packaging solutions that preserve the integrity and extend the shelf life of these products.
Advancements in Packaging Technology
Technological advancements play a pivotal role in driving the global liquid packaging market. Innovations in packaging materials and techniques have resulted in the development of more durable, lightweight, and sustainable packaging solutions. High-barrier films, aseptic packaging, and smart packaging technologies are examples of advancements that enhance the functionality and appeal of liquid packaging. High-barrier films offer superior protection against oxygen, moisture, and light, thereby extending the shelf life of liquid products. For example, high-barrier films, which offer superior protection against oxygen, moisture, and light, have increased the shelf life of liquid products by up to 50%. Aseptic packaging, which involves sterilizing the packaging material and the liquid product separately before filling, ensures product safety and eliminates the need for preservatives. Smart packaging technologies, incorporating features such as QR codes, RFID tags, and temperature indicators, provide consumers with real-time information about the product's quality, authenticity, and usage instructions. These innovations not only meet the stringent regulatory standards but also cater to the evolving consumer preferences for convenience, safety, and sustainability.
Growth of the Pharmaceutical Industry
The pharmaceutical industry is another critical driver of the global liquid packaging market. The increasing prevalence of chronic diseases, aging populations, and rising health awareness have led to a surge in demand for pharmaceutical products, including liquid medications, syrups, and vaccines. The packaging of these liquid pharmaceutical products requires stringent adherence to regulatory standards to ensure the safety, efficacy, and stability of the medications. This has resulted in a heightened demand for specialized liquid packaging solutions that offer tamper-evidence, child-resistance, and accurate dosing capabilities. The COVID-19 pandemic further underscored the importance of robust pharmaceutical packaging, as the distribution of liquid vaccines and therapeutics required secure and efficient packaging solutions to maintain the cold chain and prevent contamination. Consequently, the pharmaceutical sector's growth significantly contributes to the expansion of the liquid packaging market.
Increasing Focus on Sustainability and Eco-Friendly Packaging
Sustainability has emerged as a paramount concern for consumers, manufacturers, and regulatory bodies alike, driving significant changes in the liquid packaging market. The increasing awareness of environmental issues such as plastic pollution and resource depletion has spurred a demand for eco-friendly packaging solutions. Manufacturers are investing in the development and adoption of biodegradable, recyclable, and reusable packaging materials to reduce the environmental impact of their products. For instance, bio-based plastics, derived from renewable resources such as corn starch and sugarcane, offer a sustainable alternative to conventional petroleum-based plastics. Additionally, the shift towards lightweight packaging materials not only reduces transportation costs and carbon emissions but also appeals to environmentally conscious consumers. Regulatory frameworks and initiatives aimed at promoting sustainability, such as the European Union’s Circular Economy Action Plan and various plastic ban regulations worldwide, further accelerate the adoption of sustainable packaging practices. This increasing focus on sustainability drives innovation and growth in the liquid packaging market, as companies strive to meet both consumer expectations and regulatory requirements.
Market Trends
Sustainability and Eco-Friendly Packaging
The trend towards sustainability is profoundly impacting the liquid packaging market. Consumers and regulatory bodies alike are demanding environmentally friendly packaging solutions. For instance, the trend towards sustainability is profoundly impacting the liquid packaging market. The use of biodegradable, compostable, and recyclable materials has increased by approximately 15% annually. Innovations such as bio-based plastics and plant-based packaging are gaining traction, reducing the reliance on traditional plastic and minimizing environmental impact. Companies are investing in the development of lightweight packaging that reduces transportation costs and carbon emissions, aligning with global sustainability goals.
Smart Packaging Technologies
Smart packaging technologies are revolutionizing the liquid packaging market. These technologies incorporate elements like QR codes, RFID tags, and temperature indicators, providing consumers with real-time information about the product. Smart packaging enhances product safety, helps in tracking and tracing, and improves inventory management. For example, temperature-sensitive smart packaging ensures that products such as pharmaceuticals and perishable beverages maintain their integrity throughout the supply chain, offering added value and assurance to consumers.
Aseptic Packaging
Aseptic packaging is becoming increasingly popular in the liquid packaging market. This method involves sterilizing the packaging material and the liquid product separately before filling. Aseptic packaging ensures longer shelf life without the need for preservatives, making it ideal for dairy products, juices, and other beverages. It also supports the growing demand for minimally processed food and beverages, catering to health-conscious consumers who prefer products with fewer additives and preservatives.
Personalization and Customization
Personalization is a growing trend in the liquid packaging market, driven by the desire to enhance consumer engagement and brand loyalty. Advanced printing technologies enable brands to create customized packaging designs, limited edition packaging, and personalized labels. This trend is particularly prominent in the beverage industry, where companies are using unique packaging designs to stand out on the shelves and connect with consumers on a personal level. Customization also extends to functional aspects, such as ergonomic designs that improve user convenience.
E-commerce Friendly Packaging
With the rise of e-commerce, the demand for packaging solutions that are suited for online retail is increasing. Liquid packaging needs to be robust enough to withstand the rigors of shipping and handling while maintaining the integrity of the product. E-commerce-friendly packaging often includes features such as tamper-evident seals, spill-proof designs, and compact, lightweight formats that reduce shipping costs and improve consumer convenience. This trend is driving innovation in packaging design and material selection to meet the unique demands of the e-commerce market.
Focus on Health and Safety
The COVID-19 pandemic has heightened awareness of health and safety, influencing trends in the liquid packaging market. There is a growing demand for packaging solutions that ensure product hygiene and safety. This includes tamper-evident packaging, single-serve packaging to reduce cross-contamination, and packaging materials with antimicrobial properties. Consumers are increasingly prioritizing products that offer enhanced safety features, prompting manufacturers to innovate and adapt to these changing preferences.
Increased Use of Flexible Packaging
Flexible packaging is gaining popularity in the liquid packaging market due to its versatility, cost-effectiveness, and sustainability benefits. Pouches, bags, and other flexible formats are being used for a wide range of liquid products, from beverages to household cleaners. Flexible packaging offers advantages such as reduced material usage, lower transportation costs, and ease of storage and disposal. It also allows for creative design possibilities, enabling brands to differentiate their products and appeal to environmentally conscious consumers.
Market Restraints and Challenges
Environmental Concerns and Regulatory Pressures
One of the primary restraints in the liquid packaging market is the increasing scrutiny regarding environmental sustainability and regulatory compliance. The extensive use of plastic packaging, which contributes to pollution and waste, has led to stringent regulations aimed at reducing plastic usage and promoting recycling. Governments and environmental bodies worldwide are implementing bans on single-use plastics and mandating the use of recyclable or biodegradable materials. While these measures are essential for environmental protection, they pose significant challenges for manufacturers in terms of adapting production processes, sourcing sustainable materials, and managing higher costs associated with eco-friendly alternatives.
High Cost of Sustainable Packaging Solutions
Transitioning to sustainable packaging solutions often involves considerable costs. The development and implementation of biodegradable, compostable, or recyclable packaging materials are typically more expensive than conventional plastic packaging. These costs include research and development, material sourcing, and modifications to existing manufacturing processes. Small and medium-sized enterprises (SMEs), in particular, may find it challenging to absorb these additional expenses, potentially affecting their competitive edge in the market. The high cost of sustainable packaging can also lead to increased product prices, which might deter price-sensitive consumers.
Technical Challenges in Packaging Innovation
Innovating new packaging solutions, particularly those that meet sustainability criteria, comes with technical challenges. Developing materials that are not only eco-friendly but also durable, flexible, and capable of preserving the quality and safety of liquid products is complex. For instance, creating biodegradable packaging that offers the same level of barrier protection as traditional plastics is a significant challenge. Additionally, integrating smart packaging technologies, such as RFID tags and temperature indicators, into liquid packaging requires sophisticated technology and expertise. These technical hurdles can slow down the innovation process and increase the time-to-market for new packaging solutions.
Supply Chain and Logistics Issues
The liquid packaging market faces supply chain and logistics challenges, particularly in the context of global disruptions such as the COVID-19 pandemic. Supply chain bottlenecks, fluctuations in raw material availability, and increased transportation costs can hinder the timely production and distribution of packaging materials. The complexity of managing a global supply chain, coupled with the need for consistent quality and regulatory compliance across different regions, adds to the operational challenges. Ensuring that packaging materials reach manufacturers without delays or quality compromises is crucial, but disruptions can lead to production halts and financial losses.
Consumer Perception and Acceptance
While there is a growing demand for sustainable packaging, consumer perception and acceptance remain challenges. Some consumers may still prefer traditional packaging due to familiarity, perceived convenience, or skepticism about the performance of new materials. Educating consumers about the benefits and efficacy of sustainable packaging is essential but can be a time-consuming and resource-intensive process. Additionally, shifting consumer habits and expectations towards accepting higher costs for sustainably packaged products is a gradual process that requires strategic marketing and communication efforts.
Market Segmentation Analysis
By Material
The liquid packaging market is segmented by materials including paperboard, plastics, glass, and metal. Paperboard is favored for its recyclability and eco-friendly properties, making it a sustainable alternative to plastic for beverages like milk and juices. Despite environmental concerns, plastics dominate the market due to their versatility, durability, and cost-effectiveness, with innovations in biodegradable and recyclable plastics addressing sustainability issues. Glass packaging, preferred for premium products, ensures no interaction with contents, making it ideal for the beverage and pharmaceutical sectors. Metal packaging, particularly aluminum, is valued for its strength and recyclability, extensively used for carbonated beverages, canned foods, and industrial liquids due to its excellent barrier properties.
By Packaging
Flexible packaging, including pouches, bags, and other flexible formats, is gaining popularity due to its lightweight nature, reduced material usage, and convenience, making it widely used in the food and beverage industry. Conversely, rigid packaging, which includes bottles, cans, and cartons, offers robust protection and durability, remaining essential for products that require stable and tamper-evident packaging, such as pharmaceuticals and household care products.
By Technology
Aseptic liquid packaging is essential for extending the shelf life of perishable liquids without preservatives, making it a prominent choice in the dairy, juice, and pharmaceutical industries. Blow molding, primarily used for producing plastic bottles and containers, is efficient for mass production and meets the demand for lightweight, cost-effective packaging solutions. Form fill seal technology, which integrates forming, filling, and sealing into a single process, enhances efficiency and reduces contamination risks, making it widely adopted for packaging liquids in both flexible and rigid formats.
By End User
The liquid packaging market is driven by several key segments. The food and beverage segment leads, demanding diverse packaging solutions to cater to various product needs, from beverages to liquid food items. In the personal care industry, packaging must be both aesthetically appealing and functional for products like shampoos, lotions, and liquid soaps, emphasizing convenience and shelf appeal. The pharmaceutical segment is critical due to stringent regulatory standards and the need for tamper-evident, sterile packaging for liquid medications, syrups, and vaccines. Household care products require packaging that prioritizes safety, functionality, and ease of use for items like detergents and cleaners. The industrial segment needs robust, often bulk packaging solutions for chemicals, lubricants, and other industrial liquids, with an emphasis on durability and safety.
Segments
Based on Material
- Paperboard
- Plastics
- Glass
- Metal
Based on Packaging
- Flexible Packaging
- Rigid Packaging
Based on Technology
- Aseptic Liquid Packaging
- Blow Molding
- Form Fill Seal
Based on End User
- Food & Beverage
- Personal Care
- Pharmaceutical
- Household Care
- Industrial
By Region
-
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
- North America
Regional Analysis
North America (25%):
North America holds a significant share of the liquid packaging market, accounting for approximately 25% of the global market. The region's mature market is driven by high consumption of packaged beverages, pharmaceuticals, and personal care products. The United States, in particular, is a major contributor due to its advanced packaging technologies and stringent regulatory standards that ensure product safety and sustainability. The growing demand for convenient, on-the-go liquid products and the increasing emphasis on sustainable packaging solutions are key factors propelling the market in this region. Additionally, the presence of major packaging companies and ongoing innovations in smart packaging technologies further bolster North America's market position.
Europe (30%):
Europe represents about 30% of the global liquid packaging market, driven by strong regulatory frameworks promoting sustainability and environmental responsibility. The European Union's stringent regulations on plastic usage and waste management have accelerated the adoption of recyclable and biodegradable packaging materials. Countries like Germany, France, and the United Kingdom are at the forefront, with significant investments in research and development for eco-friendly packaging solutions. The region's focus on reducing carbon footprints and the high demand for premium and organic beverages contribute to the robust growth of the liquid packaging market in Europe. Additionally, consumer awareness and preference for sustainable packaging options play a crucial role in shaping market trends.
Asia-Pacific (35%):
The Asia-Pacific region holds the largest share of the liquid packaging market, accounting for around 35% of the global market. This dominance is attributed to rapid urbanization, increasing disposable incomes, and a growing middle-class population. Countries like China, India, and Japan are major contributors, with a high demand for packaged food and beverages, pharmaceuticals, and personal care products. The burgeoning e-commerce sector and the shift towards convenient, ready-to-drink beverages are significant drivers of market growth. Furthermore, the region's focus on improving healthcare infrastructure and increasing investments in the pharmaceutical sector contribute to the expanding liquid packaging market. The trend towards lightweight and cost-effective packaging solutions also fuels market growth in this region.
Key players
- Tetra Pak International S.A.
- Amcor Limited
- The Dow Chemical Company
- Reynolds Group Holdings Limited
- SIG Combibloc Group AG
- Elopak AS
- Mondi Group
- Smurfit Kappa Group
- Berry Global Inc.
- Sealed Air Corporation
Competitive Analysis
The liquid packaging market is characterized by intense competition among key players striving to gain a larger market share through innovation and sustainability. Companies like Tetra Pak International S.A. and Amcor Limited lead the market with their extensive product portfolios and strong emphasis on research and development. These market leaders continuously innovate to provide eco-friendly and technologically advanced packaging solutions. SIG Combibloc Group AG and Elopak AS focus on aseptic and sustainable packaging technologies, catering to the growing demand for longer shelf life and reduced environmental impact. Meanwhile, Mondi Group and Smurfit Kappa Group leverage their extensive distribution networks and expertise in paper-based packaging to offer sustainable alternatives to plastic packaging. The competitive landscape is further shaped by strategic mergers, acquisitions, and partnerships, as companies aim to expand their geographical reach and product offerings to meet the evolving needs of consumers and regulatory requirements.
Recent Developments
In October 2023, Tetra Pak announced its partnership with Colombian coffee producer Olam Specialty Coffee to create a fully recyclable paper-based pouch for ground coffee. This innovative packaging solution eliminates the need for aluminum foil and plastic, addressing consumer demand for sustainable and eco-friendly options. By leveraging their expertise in packaging and sustainability, Tetra Pak and Olam Specialty Coffee aim to reduce the environmental impact of coffee packaging and align with global trends towards sustainability.
In November 2023, Amcor, a prominent player in the flexible packaging industry, introduced its AmLite HeatSeal pouch, specifically designed for hot-fill applications. This innovative pouch can endure high temperatures, making it an excellent choice for packaging hot beverages like soups and sauces. The AmLite HeatSeal pouch combines durability with convenience, addressing the growing demand for packaging solutions that maintain product integrity under extreme conditions, and reinforcing Amcor's position as a leader in flexible packaging technology.
In April 2023, AptarGroup acquired Peli BioThermal to strengthen its position in the liquid packaging market for the pharmaceutical and healthcare sectors. This strategic acquisition enhances AptarGroup's capabilities in providing advanced packaging solutions that meet the stringent requirements of the healthcare industry. By integrating Peli BioThermal's expertise in temperature-controlled packaging, AptarGroup aims to offer more robust and reliable solutions for transporting and storing temperature-sensitive pharmaceutical products, thereby expanding its market presence and competitive edge.
Market Concentration and Characteristics
The liquid packaging market exhibits moderate to high market concentration, characterized by the dominance of a few key players such as Tetra Pak International S.A., Amcor Limited, and The Dow Chemical Company. These industry leaders drive innovation and set industry standards with their extensive research and development efforts, diverse product portfolios, and global distribution networks. The market is marked by rapid advancements in sustainable and smart packaging technologies, responding to regulatory pressures and consumer demand for eco-friendly and convenient packaging solutions. Competitive dynamics are further shaped by strategic mergers, acquisitions, and collaborations aimed at expanding market reach and enhancing technological capabilities.
Report Coverage
The research report offers an in-depth analysis based on Material, Packaging, Technology and End User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will see a significant shift towards sustainable packaging solutions, with increasing investments in biodegradable and recyclable materials to meet environmental regulations and consumer preferences.
- Smart packaging technologies will become more prevalent, offering enhanced product safety, real-time tracking, and improved consumer engagement through features like QR codes and temperature indicators.
- The demand for aseptic packaging will continue to rise, driven by the need for longer shelf life and preservation of nutritional value in perishable liquid products, especially in the food and beverage industry.
- Flexible packaging formats such as pouches and bags will gain popularity due to their lightweight, cost-effectiveness, and convenience, particularly in the beverage and personal care sectors.
- Emerging markets in Asia-Pacific, Latin America, and Africa will experience robust growth, fueled by urbanization, rising disposable incomes, and increasing consumption of packaged liquids.
- The liquid packaging market will prioritize health and safety features, including tamper-evident and antimicrobial packaging, to address heightened consumer awareness post-COVID-19.
- Continuous technological advancements in materials and manufacturing processes will drive the development of more efficient, durable, and eco-friendly liquid packaging solutions.
- The growth of e-commerce will spur demand for robust, spill-proof, and lightweight packaging solutions designed to withstand the rigors of shipping and handling.
- Stricter environmental regulations and policies will push manufacturers to innovate and adopt sustainable practices, significantly influencing market dynamics and product offerings.
- Companies will increasingly engage in mergers, acquisitions, and partnerships to enhance their capabilities, expand their market reach, and accelerate the development of innovative packaging solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Demand in the Beverage Industry
The surge in consumption of bottled water, functional drinks, and ready-to-drink beverages is driving the need for innovative and efficient liquid packaging solutions that preserve product integrity and extend shelf life.
Advancements in Packaging Technology
Innovations such as high-barrier films, aseptic packaging, and smart packaging technologies are enhancing durability, safety, and sustainability, making liquid packaging more appealing to both manufacturers and consumers.
Growth of the Pharmaceutical Industry
The increasing prevalence of chronic diseases and demand for liquid medications and vaccines require specialized, tamper-evident, and regulatory-compliant packaging, fueling market expansion in the pharmaceutical segment.
Increasing Focus on Sustainability and Eco-Friendly Packaging
Heightened environmental awareness and regulatory pressures are pushing manufacturers to adopt biodegradable, recyclable, and lightweight materials, driving growth in sustainable liquid packaging solutions.
Expansion of E-commerce and On-the-Go Consumption
The rise of e-commerce and consumer preference for convenient, portable liquid products are boosting demand for robust, spill-proof, and lightweight packaging formats that can withstand shipping and handling.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the global liquid packaging market in 2023 and 2032, and what is the CAGR?
What is driving the growth of the global liquid packaging market?
How is sustainability influencing the liquid packaging market?
Which regions are leading the liquid packaging market, and why?
Who are the key players in the liquid packaging market?
What are the recent developments in the liquid packaging market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Food & Beverage
- 1.2.2 Personal Care
- 1.2.3 Pharmaceutical
- 1.2.4 Household Care
- 1.2.5 Industrial
- 1.3 By Material
- 1.3.1 Paperboard
- 1.3.2 Plastics
- 1.3.3 Glass
- 1.3.4 Metal
- 1.4 By Packaging
- 1.4.1 Flexible Packaging
- 1.4.2 Rigid Packaging
- 1.5 By Technology
- 1.5.1 Aseptic Liquid Packaging
- 1.5.2 Blow Molding
- 1.5.3 Form Fill Seal
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 399,810.82 million → 2032: USD 539,638.3 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Liquid Packaging Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Liquid Packaging Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Liquid Packaging Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Liquid Packaging Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Liquid Packaging Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Liquid Packaging Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Liquid Packaging Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Liquid Packaging Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 399,810.82 million → 2032: USD 539,638.3 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Liquid Packaging Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Food & Beverage
- 12.3.7.2 Personal Care
- 12.3.7.3 Pharmaceutical
- 12.3.7.4 Household Care
- 12.3.7.5 Industrial
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Paperboard
- 12.4.7.2 Plastics
- 12.4.7.3 Glass
- 12.4.7.4 Metal
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Packaging - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Flexible Packaging
- 12.5.7.2 Rigid Packaging
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Technology - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Aseptic Liquid Packaging
- 12.6.7.2 Blow Molding
- 12.6.7.3 Form Fill Seal
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Liquid Packaging End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Liquid Packaging Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Liquid Packaging Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Liquid Packaging Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Tetra Pak International S.A.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Amcor Limited
- 18.4 The Dow Chemical Company
- 18.5 Reynolds Group Holdings Limited
- 18.6 SIG Combibloc Group AG
- 18.7 Elopak AS
- 18.8 Mondi Group
- 18.9 Smurfit Kappa Group
- 18.10 Berry Global Inc.
- 18.11 Sealed Air Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

