
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Luxury Alcohol Market Size 2024 | USD 295.75 million |
| Luxury Alcohol Market, CAGR | 5.77% |
| Luxury Alcohol Market Size 2032 | USD 460.84 million |
Market Overview:
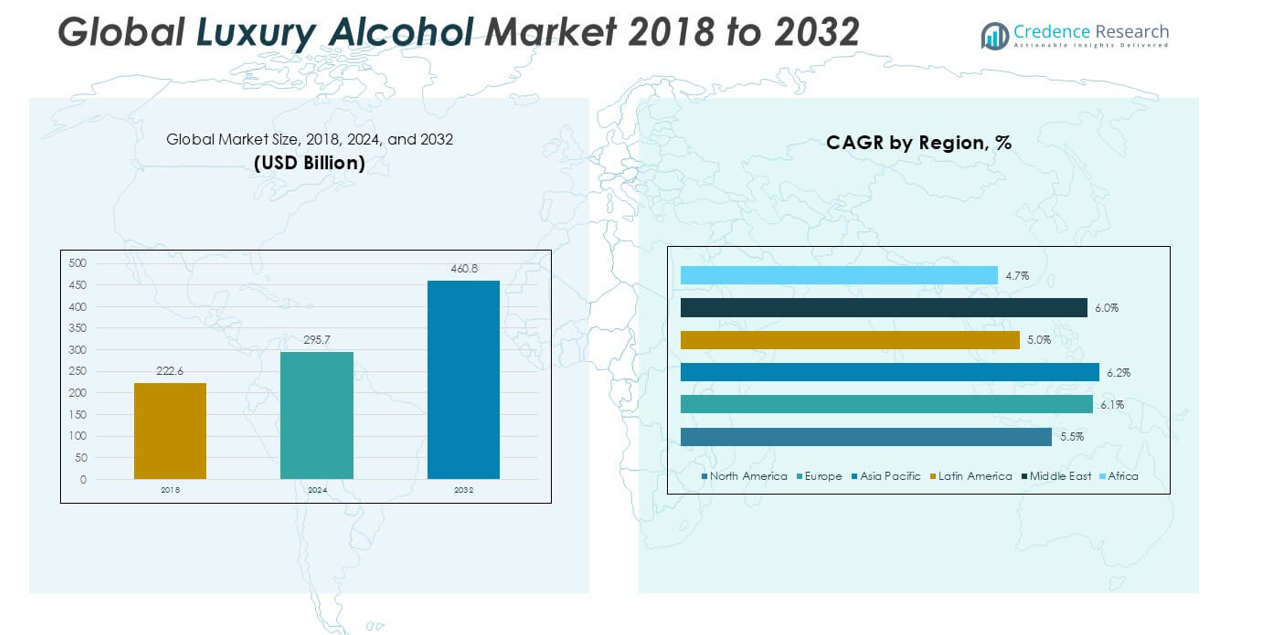
The Luxury Alcohol market size was valued at USD 222.67 million in 2018 and USD 295.75 million in 2024, and is anticipated to reach USD 460.84 million by 2032, at a CAGR of 5.77% during the forecast period.
The luxury alcohol market is led by prominent players such as Pernod Ricard, Diageo plc, Suntory Holdings Limited, LVMH, Bacardi Limited, and Rémy Cointreau, all of whom maintain robust global portfolios and significant brand equity. These companies excel through innovation, targeted product launches, and strong distribution networks, reinforcing their dominance in both spirits and premium wine segments. North America stands out as the leading region, holding approximately 32.6% of the global market share in 2024, followed by Europe and Asia Pacific. This regional leadership is driven by high consumer spending, established luxury hospitality venues, and a strong culture of premium alcohol consumption.
Market Insights
- The luxury alcohol market was valued at USD 295.75 million in 2024 and is projected to reach USD 460.84 million by 2032, registering a CAGR of 5.77% during the forecast period.
- Premiumization and rising disposable incomes are key drivers, with affluent consumers seeking exclusive spirits and wines, especially in urban and hospitality settings.
- Trends such as experiential consumption, sustainable packaging, and limited-edition releases are shaping the industry, while on-trade channels and luxury spirits lead segment growth.
- The market is dominated by leading players like Pernod Ricard, Diageo plc, Suntory Holdings Limited, LVMH, and Bacardi Limited, who maintain competitive advantage through product innovation and brand heritage.
- North America commands the largest regional share at 32.6% in 2024, followed by Europe at 27.8% and Asia Pacific at 25.3%; luxury spirits account for the largest segment share, with whiskey and red wines driving overall category expansion.
Market Segmentation Analysis:
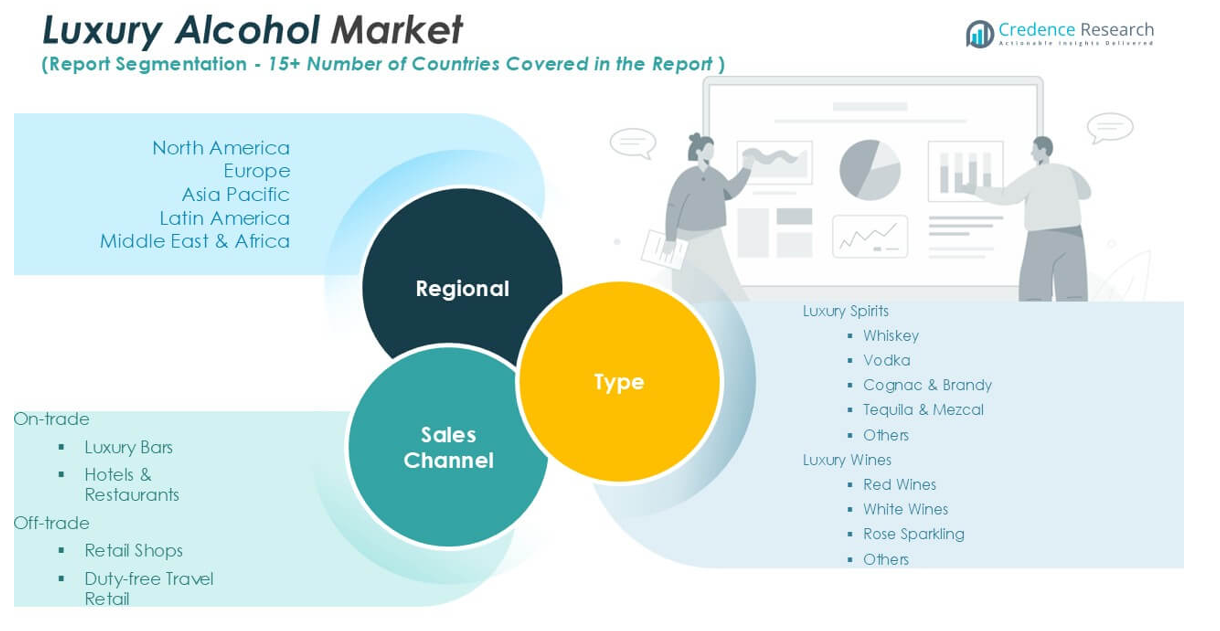
By Type: Within the luxury alcohol market, luxury spirits represent the largest segment, accounting for a significant market share due to strong global demand for premium whiskey, cognac, and vodka. Whiskey leads the category, driven by heritage branding, exclusive releases, and rising consumer interest in aged and limited-edition variants. Meanwhile, luxury wines continue to gain traction, with red wines dominating based on their broad appeal among affluent consumers and frequent use in high-end dining and gifting occasions. Premiumization trends and the emergence of new luxury wine labels further fuel category expansion.
- For instance, Diageo released 10,000 bottles of its Johnnie Walker Blue Label Ghost and Rare Glenury Royal, which sold out within a month of launch, demonstrating rapid uptake for luxury limited editions.
By Sales Channel:
The on-trade segment, which includes luxury bars and hotels & restaurants, holds the dominant share of the luxury alcohol market. This is supported by increasing consumption of premium alcoholic beverages in exclusive venues, where consumers seek curated experiences and personalized service. Luxury bars, in particular, drive revenue with bespoke cocktail offerings and high-end bottle service. The off-trade segment, led by retail shops, has also witnessed steady growth as affluent consumers invest in rare and collectible bottles for personal consumption or gifting, while duty-free travel retail remains a vital channel for international buyers.
- For instance, Pernod Ricard expanded its Martell cognac collection in global duty-free shops, placing over 250,000 bottles across 25 major airport locations worldwide.
Market Overview
Expanding On-Trade and Experiential Consumption
The proliferation of luxury bars, upscale restaurants, and experiential hospitality venues accelerates demand for premium alcoholic beverages. Consumers prioritize immersive drinking experiences, driving sales of luxury spirits and wines in on-trade channels. Curated tastings, mixology events, and bespoke service options have become integral to the luxury alcohol value chain, fostering brand loyalty and enhancing consumer engagement. This dynamic, experience-driven model supports long-term market expansion and deepens consumer relationships with premium brands.
- For instance, Bacardi Limited partnered with over 500 luxury hospitality venues to host its annual Bacardi Legacy Global Cocktail Competition, attracting more than 3,000 professional bartenders worldwide.
Innovation in Product Offerings and Packaging
Continuous innovation in luxury alcohol product development and packaging acts as a significant growth driver. Brands introduce rare cask finishes, bespoke blends, and unique flavor profiles to differentiate themselves in a competitive landscape. Limited-edition packaging, personalized labeling, and luxury gift sets further attract discerning buyers. Such innovations heighten exclusivity and drive interest among collectors and enthusiasts, supporting premium pricing strategies and expanding the overall market footprint.
- For instance, Rémy Cointreau’s Louis XIII introduced a personalized decanter service, which allows customers to engrave their name and has processed more than 2,500 custom orders since its launch.
Premiumization and Consumer Affluence
Rising disposable incomes and an expanding global affluent class serve as primary growth drivers in the luxury alcohol market. Discerning consumers increasingly seek premium experiences, gravitating toward exclusive, limited-edition spirits and high-end wines. Brand heritage, craftsmanship, and provenance influence purchasing decisions, leading to greater willingness to invest in luxury labels. Premiumization not only elevates the value proposition but also enables brands to command higher margins, making it a crucial factor fueling consistent market growth.
Key Trends & Opportunities
Trend Toward Sustainable and Authentic Offerings
A notable trend shaping the luxury alcohol market is the emphasis on sustainability and authenticity. Brands increasingly adopt eco-friendly packaging, organic ingredients, and responsible sourcing practices to appeal to environmentally conscious consumers. Transparent storytelling around heritage and artisanal methods also resonates strongly, creating new opportunities for differentiation and premium positioning. This shift not only aligns with evolving consumer values but also enhances brand reputation in a crowded market.
- For instance, Suntory Holdings reduced its carbon emissions by 56,000 tons annually after switching to lightweight glass bottles for its premium spirits range.
Growth of E-Commerce and Direct-to-Consumer Sales
E-commerce and direct-to-consumer channels present substantial opportunities for luxury alcohol brands to expand their reach. Digital platforms enable personalized engagement, convenient purchasing, and access to exclusive releases. Online sales facilitate data-driven marketing strategies and targeted promotions, broadening brand visibility among global audiences. This channel shift supports higher margins and creates new touchpoints for building long-term consumer relationships, particularly as affluent buyers increasingly value convenience and exclusivity.
- For instance, Bacardi’s e-commerce sales for its luxury spirits portfolio grew by 65,000 individual orders through its official online stores in a single calendar year.
Key Challenges
Stringent Regulations and Import Restrictions
The luxury alcohol market faces significant challenges due to complex regulatory environments and varying import restrictions across regions. High taxes, advertising limitations, and shifting compliance requirements often hinder market entry and impact profitability for global brands. Navigating these barriers necessitates substantial investment in compliance and localization strategies, which can slow expansion and limit access to emerging high-growth markets.
Counterfeit Products and Brand Imitation
Counterfeiting and imitation of luxury alcohol brands pose a major challenge, undermining consumer trust and eroding brand equity. The proliferation of fake bottles and unauthorized distribution channels threatens the authenticity that is central to the luxury proposition. Brands must invest in advanced authentication technologies, traceability solutions, and consumer education to mitigate these risks and safeguard their premium positioning.
Changing Consumer Preferences and Health Concerns
Evolving consumer attitudes toward health and wellness increasingly impact the luxury alcohol market. Growing awareness of the health risks associated with alcohol consumption leads some consumers to moderate their intake or shift preferences toward low- and no-alcohol alternatives. Brands must adapt by innovating with healthier formulations, transparent labeling, and responsible marketing to remain relevant and address the shifting priorities of a health-conscious consumer base.
Regional Analysis
North America North America held the largest share of the luxury alcohol market in 2024, accounting for USD 96.30 million, up from USD 73.73 million in 2018. The region is expected to reach USD 146.68 million by 2032, reflecting a CAGR of 5.5%. North America represents approximately 32.6% of the global market in 2024, driven by a strong culture of premium spirits consumption and robust growth in the U.S. on-trade segment. Brand loyalty, high disposable income, and consumer interest in rare and collectible spirits continue to underpin market dominance in this region.
Europe
Europe captures a substantial share of the luxury alcohol market, with a value of USD 82.27 million in 2024, up from USD 61.01 million in 2018. The region is projected to reach USD 130.74 million by 2032, achieving a CAGR of 6.0%. Europe’s market share in 2024 stands at roughly 27.8%. The region benefits from a rich heritage in both wine and spirits production, with leading luxury brands headquartered in France, Italy, and the UK. Consumer sophistication and a strong tradition of luxury consumption support sustained market expansion.
Asia Pacific
Asia Pacific accounted for USD 74.65 million in the luxury alcohol market in 2024, rising from USD 54.93 million in 2018 and forecasted to reach USD 119.82 million by 2032, at a CAGR of 6.2%. The region holds about 25.3% of the global market in 2024. Rapid urbanization, a growing middle and upper class, and increasing exposure to Western luxury brands drive demand. Key markets such as China, Japan, and South Korea are fueling robust consumption, with luxury spirits and high-end wines gaining popularity among affluent consumers.
Latin America
Latin America’s luxury alcohol market was valued at USD 28.36 million in 2024, up from USD 22.27 million in 2018, and is set to reach USD 41.66 million by 2032, at a CAGR of 5.0%. Representing roughly 9.6% of the global market in 2024, the region’s growth is supported by expanding urban populations, increasing premiumization, and the emergence of upscale hospitality venues. Brazil and Mexico are key contributors, as rising disposable incomes and growing interest in international spirits and wines foster market development.
Middle East
The Middle East luxury alcohol market reached USD 8.32 million in 2024, increasing from USD 6.19 million in 2018, and is projected to attain USD 13.18 million by 2032, with a CAGR of 6.0%. The region accounts for about 2.8% of the global market in 2024. Growth is primarily concentrated in countries with more liberal alcohol policies and thriving tourism sectors, such as the UAE. The influx of expatriates and tourists, coupled with investments in high-end hospitality, supports rising demand for premium alcoholic beverages.
Africa
Africa recorded a market value of USD 5.86 million for luxury alcohol in 2024, rising from USD 4.54 million in 2018 and anticipated to reach USD 8.76 million by 2032, with a CAGR of 5.2%. Africa comprises nearly 2.0% of the global market in 2024. Market expansion is driven by a gradual increase in affluence, urbanization, and evolving consumer preferences toward luxury products. While still emerging, the continent shows potential in metropolitan centers where a growing elite is developing a taste for premium wines and spirits.
Market Segmentations:
By Type:
- Luxury Spirits
- Whiskey
- Vodka
- Cognac & Brandy
- Tequila & Mezcal
- Others
- Luxury Wines
- Red Wines
- White Wines
- Rose Sparkling
- Others
By Sales Channel:
- On-trade
- Luxury Bars
- Hotels & Restaurants
- Off-trade
- Retail Shops
- Duty-free Travel Retail
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the luxury alcohol market is characterized by the presence of several prominent global players, each leveraging their heritage, brand reputation, and diversified product portfolios to capture market share. Companies such as Pernod Ricard, Diageo plc, Suntory Holdings, LVMH, and Bacardi Limited maintain strong positions through ongoing innovation, strategic acquisitions, and targeted marketing campaigns that appeal to affluent consumers. These industry leaders consistently invest in limited-edition releases, premium packaging, and experiential marketing to strengthen customer loyalty and reinforce brand exclusivity. In addition to established spirits houses, boutique producers like Screaming Eagle and Penfolds contribute to market dynamism with highly sought-after wines and exclusive offerings. Increasing competition drives companies to enhance product authenticity, traceability, and sustainability. Strategic partnerships, expansion into emerging markets, and a focus on digital engagement further define the market’s competitive strategies as players vie to differentiate themselves in a rapidly evolving luxury segment.
Key Player Analysis
- Pernod Ricard
- Diageo plc
- Suntory Holdings Limited
- Davide Campari-Milano N.V.
- SAZERAC CO, INC
- LVMH
- Bacardi Limited
- Rémy Cointreau
- Heaven Hill Brands
- Constellation Brands, Inc.
- Highwood Distillers
- Screaming Eagle
- Penfolds
Recent Developments
- In June 2025, Diageo India (United Spirits Limited - USL) acquired a majority stake in NAO Spirits, the maker of premium Indian craft gins "Greater Than" and "Hapusa". This acquisition signifies Diageo's strategic move to expand its portfolio of local, authentic brands and explore growth opportunities within the Indian craft spirits market. The deal was valued at an enterprise value of ₹130 crore.
- In May 2025, Campari Group's first quarter 2025 performance was softened by macroeconomic volatility, Easter timing, and phasing of investments, though sell-out outperformed spirits markets across most regions. The company's board confirmed Luca Garavoglia as Chairman.
- In May 2025, Rémy Cointreau company appointed Franck Marilly, a luxury industry veteran, as CEO (effective June 25, 2025). Marilly is expected to focus on sustainable growth, premiumization, and digital expansion, including a strategic shift toward higher-margin XO and VSOP cognacs and increased direct sales of LOUIS XIII.
- In May 2025, Diageo India launched "Driver Sensitisation Tab Labs" in Goa as part of their "Wrong Side of the Road" initiative. This initiative, in partnership with BharatCaresand the Directorate of Transport, aims to promote responsible alcohol consumption and improve road safety by educating new drivers on responsible driving habits.
- In December 2024, Suntory Global Spirits opened the first Bowmore boutique in travel retail at London Heathrow Terminal 5, partnering with Avolta, a move to enhance their luxury whisky presence in the travel sector.
Market Concentration & Characteristics
The luxury alcohol market displays a moderately concentrated structure, with a handful of multinational companies controlling a substantial portion of global sales. It is defined by high brand loyalty, strong heritage value, and a premium product mix dominated by spirits such as whiskey, cognac, and vodka, along with high-end wines. Leading firms such as Pernod Ricard, Diageo plc, LVMH, and Bacardi Limited set benchmarks in innovation, marketing, and distribution, while boutique producers offer exclusive, limited-edition labels to appeal to collectors and enthusiasts. The market operates within a highly regulated environment that emphasizes authenticity, traceability, and responsible marketing practices. It shows a preference for exclusive experiences, sustainable packaging, and product differentiation, helping brands maintain pricing power and consumer engagement. Strategic partnerships, global distribution expansion, and digital engagement play critical roles in shaping competitive dynamics. Regional variations exist, but the core market characteristics of exclusivity, quality, and consumer aspiration remain consistent across key geographies
Report Coverage
The research report offers an in-depth analysis based on Type, Sales Channel, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Luxury alcohol brands will expand their presence in emerging markets driven by growing affluence and urbanization.
- Producers will introduce more low- and no-alcohol premium alternatives to cater to health-conscious consumers.
- Sustainable sourcing and eco‑friendly packaging will shape product development and brand narratives.
- Digital platforms and e‑commerce channels will gain prominence for direct-to-consumer sales and exclusive launches.
- Personalized offerings, such as bespoke labeling and limited editions, will attract collectors and niche audiences.
- Brand collaborations with luxury lifestyle sectors will enhance visibility and widen distribution reach.
- Data-driven marketing will deliver targeted campaigns and improve consumer engagement.
- Regulations on alcohol advertising and cross-border trade will drive innovation in compliant promotional strategies.
- The market will see increased consolidation as leading players pursue strategic acquisitions and joint ventures.
- Technology-enabled traceability solutions, like blockchain, will reinforce brand credibility and combat counterfeiting.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Luxury Alcohol Market?
What factors are driving the growth of the Luxury Alcohol Market?
What are some challenges faced by the Luxury Alcohol Market?
Who are the major players in the Luxury Alcohol Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Luxury Alcohol Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Luxury Alcohol Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 295.75 million → 2032: USD 460.84 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Luxury Alcohol Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Luxury Alcohol Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Luxury Alcohol Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Luxury Alcohol Market Drivers
- 3.3 Luxury Alcohol Market Restraints & Challenges
- 3.4 Luxury Alcohol Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Luxury Alcohol Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Luxury Alcohol Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Luxury Alcohol category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Luxury Alcohol Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Luxury Alcohol Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Luxury Alcohol. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Luxury Alcohol Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Luxury Alcohol Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Luxury Alcohol Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Luxury Alcohol (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Luxury Alcohol
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Luxury Alcohol Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Luxury Alcohol Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Luxury Alcohol Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Luxury Alcohol Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Luxury Alcohol Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Luxury Alcohol Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Luxury Alcohol Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Luxury Alcohol Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
