
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Luxury Products for Kids market Size 2024 | USD 35,139.9 million |
| Luxury Products for Kids market, CAGR | 5.90% |
| Luxury Products for Kids market Size 2032 | USD 55,510.7 million |
Market Overview:
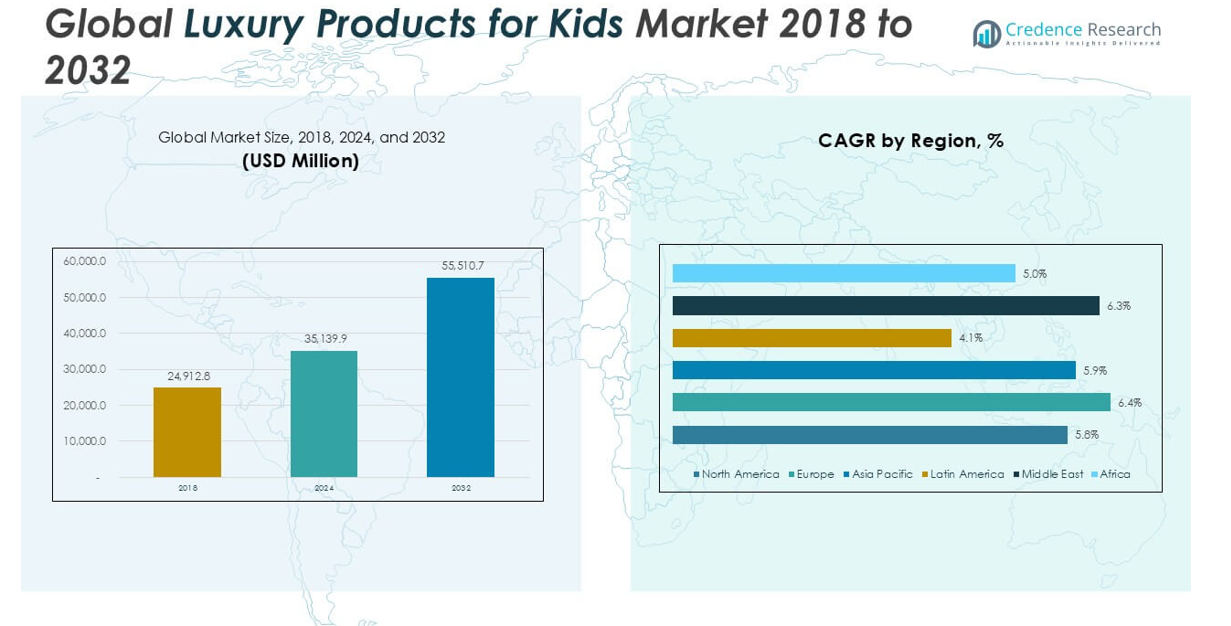
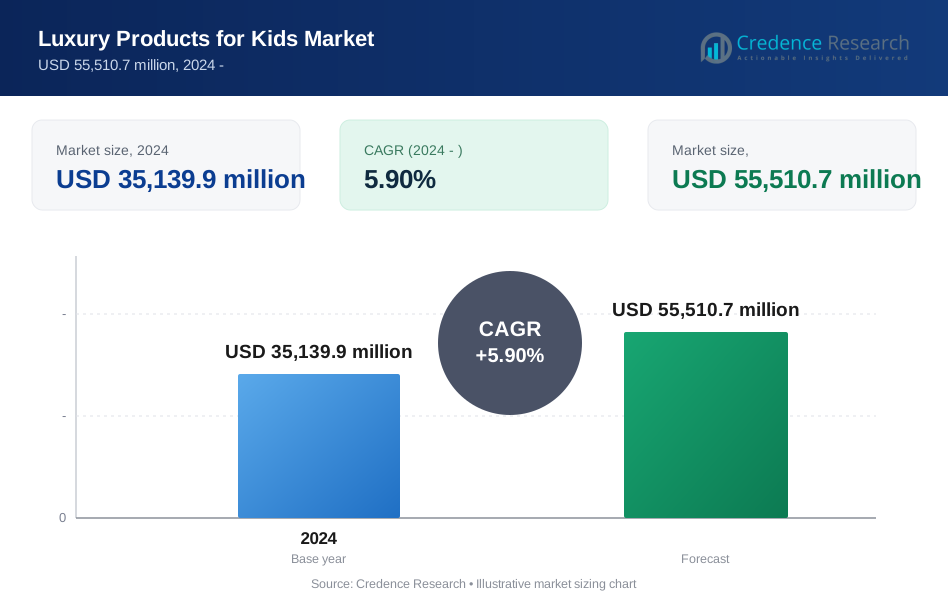
The Luxury Products for Kids market size was valued at USD 24,912.8 million in 2018 and reached USD 35,139.9 million in 2024. It is anticipated to reach USD 55,510.7 million by 2032, at a CAGR of 5.90% during the forecast period.
Top players in the Luxury Products for Kids market include GUCCI Group, United Colors of Benetton, Jack & Jill Clothing Inc., J Crew Group Inc., DKNY, Burberry Group, GIORGIO Armani S.p.A, Fendi Kids, and Moncler Enfant, all of which drive industry standards through premium offerings and distinctive brand identities. These companies lead in product innovation, quality, and exclusive collections, appealing to affluent consumers worldwide. Asia Pacific emerges as the leading region, capturing a 32.9% market share in 2024, driven by rapid urbanization, rising disposable income, and strong demand for branded luxury children’s products, followed by North America and Europe.
Market Insights
- The Luxury Products for Kids market reached USD 35,139.9 million in 2024 and is projected to reach USD 55,510.7 million by 2032, registering a CAGR of 5.90% during the forecast period.
- Market growth is driven by rising disposable incomes, evolving parental preferences for premium quality, and the influence of social media and celebrity endorsements on purchasing decisions.
- The apparel segment holds the largest share, exceeding 30% of the market, while the 1-5 age group represents the most lucrative segment due to high parental investment in early childhood.
- Intense competition among top players such as GUCCI Group, United Colors of Benetton, and Burberry Group fuels innovation and brand collaborations, though high price sensitivity and the proliferation of counterfeit products remain key restraints.
- Asia Pacific dominates with a 32.9% share in 2024, followed by North America and Europe, reflecting strong demand and expanding consumer bases in these regions.
Market Segmentation Analysis:
By Product
Apparel holds the largest share in the Luxury Products for Kids market, accounting for over 30% of total revenue. High demand for premium clothing brands, rising disposable incomes, and a growing trend toward designer outfits for children drive this dominance. Parents increasingly seek fashionable, high-quality garments for special occasions and everyday use, supporting continued growth in this segment. Toys and Games and Baby Care Products also contribute significantly, with innovation, safety standards, and the appeal of branded or educational toys boosting their market presence.
- For instance, in 2023, Burberry Kids launched 134 new children's wear styles globally, with 28 exclusive pieces available only through its online store.
By Age Group
The 1-5 age group represents the dominant sub-segment, capturing nearly 45% of the Luxury Products for Kids market. Parents of younger children prioritize high-quality, safe, and comfortable products, leading to increased expenditure on luxury items for this age range. This group benefits most from premium apparel, toys, and baby care products, as consumers focus on providing the best for infants and toddlers. The 6-10 and 11-15 segments show steady growth as demand for branded items and trend-driven purchases rises with age.
- For instance, Fendi Kids introduced 67 new products in 2023 specifically targeted at the 1-5 age group, expanding its range in the segment.
By Sales Channel
Online Stores emerge as the leading sales channel, accounting for over 35% of market revenue in the Luxury Products for Kids market. The shift to digital platforms, convenience of home delivery, and access to exclusive collections fuel this growth. E-commerce offers a wide variety of luxury brands and personalized shopping experiences, appealing to modern consumers. Retail Stores and Supermarket/Hypermarkets remain important, but the expanding digital landscape and increased trust in online transactions drive the dominance of Online Stores in this segment.
Market Overview
Rising Disposable Income and Changing Lifestyle Preferences
Growth in disposable income among urban families significantly boosts spending on luxury products for children. As parents prioritize quality, safety, and branded appeal for their kids, demand for premium apparel, toys, and accessories increases. This trend is reinforced by social media influences and celebrity endorsements, which encourage aspirational purchasing and enhance brand visibility, resulting in higher market penetration for luxury children’s products.
- For instance, GUCCI Kids saw a 41% year-over-year increase in direct sales from its capsule collection promoted by celebrity brand ambassadors in 2023, selling 19,000 units in the first quarter alone.
Expansion of E-Commerce and Digital Retail Channels
The proliferation of online shopping platforms serves as a major growth driver in the Luxury Products for Kids market. E-commerce provides access to global brands, exclusive collections, and personalized shopping experiences. Parents increasingly value convenience, wider product selection, and direct-to-door delivery, which drives online sales. Companies invest in user-friendly websites and mobile apps to strengthen digital presence and attract tech-savvy consumers.
- For instance, United Colors of Benetton reported that its kids’ luxury section received 3.2 million unique visitors on its website in 2023, and processed over 720,000 online orders for children’s apparel.
Brand Innovation and Premiumization Strategies
Brands continuously innovate to differentiate their offerings and justify premium pricing in the kids’ luxury segment. Customization options, limited-edition products, and collaborations with designers or celebrities boost appeal and customer loyalty. Enhanced product safety, eco-friendly materials, and attention to comfort further elevate the perceived value, enabling brands to maintain growth and capture discerning parents seeking the best for their children.
Key Trends & Opportunities
Sustainability and Ethical Consumption
The shift toward sustainable and ethically sourced materials creates new opportunities in the market. Parents are more conscious of environmental impacts and social responsibility, prompting brands to launch eco-friendly collections and transparent sourcing practices. This not only strengthens brand reputation but also attracts environmentally aware consumers, supporting long-term market growth.
- For instance, in 2023, GIORGIO Armani S.p.A’s children’s division produced 105,000 garments made from Global Organic Textile Standard (GOTS) certified cotton.
Personalization and Experiential Shopping
Personalized products and experiential retail, such as interactive stores and exclusive events, emerge as key trends. Parents appreciate tailored clothing, custom toys, and memorable shopping experiences for their children. This trend enhances customer engagement, increases brand loyalty, and provides differentiation in a competitive market, opening avenues for premium pricing and higher margins.
- For instance, Moncler Enfant’s flagship stores hosted 18 in-store customization events in 2023, delivering over 1,400 personalized jackets and accessories for children worldwide.
Key Challenges
High Price Sensitivity Among Mass Consumers
Despite rising demand, luxury kids’ products face resistance due to high prices, limiting adoption among middle-income groups. Value-conscious shoppers often opt for affordable alternatives, constraining market expansion. Brands must balance exclusivity with accessibility to broaden their consumer base and achieve sustained growth.
Counterfeit and Imitation Products
The proliferation of counterfeit and imitation luxury products poses a significant challenge. These products undercut genuine brands, erode consumer trust, and impact revenue. Addressing this issue requires continuous investment in brand protection, secure supply chains, and consumer education to maintain the integrity of premium offerings.
Rapidly Changing Fashion Trends
Frequent shifts in children’s fashion trends require brands to adapt quickly, increasing design and production costs. Failure to keep up with evolving preferences can result in lost market share. Companies must invest in agile supply chains and responsive marketing to meet changing demands and retain consumer interest.
Regional Analysis
North America
North America holds a substantial share in the Luxury Products for Kids market, reaching USD 9,205.15 million in 2024, up from USD 6,557.06 million in 2018, and is projected to reach USD 14,449.44 million by 2032. The region accounts for approximately 26.2% of the global market in 2024, supported by a strong preference for branded children’s apparel, toys, and accessories. A steady CAGR of 5.8% highlights robust consumer spending, digital retail expansion, and a mature luxury goods sector, ensuring continued dominance in the premium kids’ segment.
Europe
Europe represents a significant portion of the Luxury Products for Kids market, with a 24.6% market share in 2024, reflecting a value of USD 8,654.96 million compared to USD 5,941.71 million in 2018. The market is projected to reach USD 14,249.60 million by 2032, registering the highest CAGR among major regions at 6.4%. Growth is driven by fashion-conscious consumers, demand for sustainable products, and strong brand heritage across countries like France, Italy, and Germany, consolidating Europe’s position as a leading hub for luxury children’s products.
Asia Pacific
Asia Pacific leads the Luxury Products for Kids market with a market share of 32.9% in 2024, reporting a value of USD 11,570.06 million, up from USD 8,188.85 million in 2018. The region is anticipated to reach USD 18,318.54 million by 2032, growing at a CAGR of 5.9%. Rapid urbanization, rising disposable income, and an expanding population of affluent parents, particularly in China and India, drive demand. The influence of global brands and increasing digital adoption further solidify Asia Pacific’s dominance in the luxury kids’ segment.
Latin America
Latin America accounts for a 8.0% market share in 2024, with the Luxury Products for Kids market reaching USD 2,817.22 million, compared to USD 2,187.35 million in 2018. The region is projected to reach USD 3,885.75 million by 2032, with a CAGR of 4.1%. Growth is moderate, supported by rising middle-class income, evolving consumer preferences, and increasing awareness of branded children’s products. However, economic volatility and limited premium retail infrastructure temper the market’s overall expansion in the region.
Middle East
The Middle East holds a 6.3% share in the Luxury Products for Kids market in 2024, with a market size of USD 2,217.83 million, up from USD 1,537.12 million in 2018. Forecasts suggest it will reach USD 3,608.20 million by 2032, reflecting a strong CAGR of 6.3%. High disposable incomes, a youthful population, and a preference for luxury goods fuel regional demand. Exclusive retail environments and high-profile international brands cater to the region’s affluent consumers, supporting steady market growth.
Africa
Africa represents a smaller but steadily expanding share, with the Luxury Products for Kids market valued at USD 674.69 million in 2024, up from USD 500.75 million in 2018. The market is expected to reach USD 999.19 million by 2032, with a CAGR of 5.0% and a market share of 1.9% in 2024. Growing urbanization, a rising affluent segment, and increased brand awareness are driving gradual uptake of luxury children’s products, although market growth remains constrained by lower purchasing power and limited retail presence.
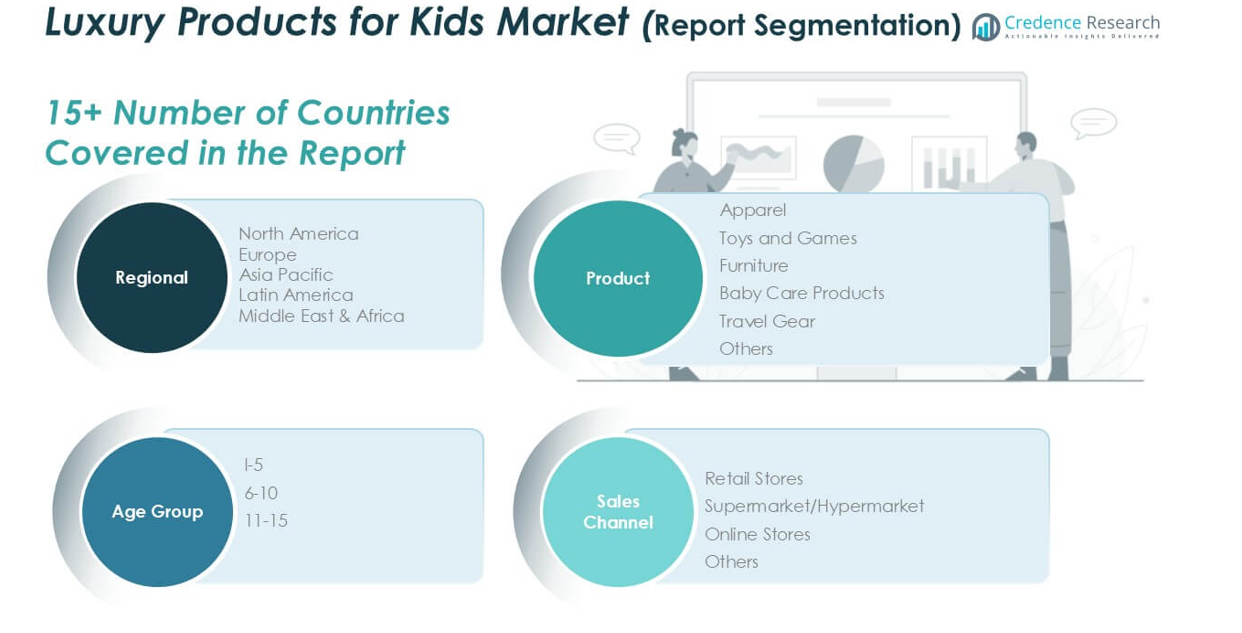
Market Segmentations:
By Product
- Apparel
- Toys and Games
- Furniture
- Baby Care Products
- Travel Gear
- Others
By Age Group
- 1-5
- 6-10
- 11-15
By Sales Channel
- Retail Stores
- Supermarket/Hypermarket
- Online Stores
- Others
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Luxury Products for Kids market features a strong presence of internationally recognized fashion houses and premium brands, each striving to capture market share through innovation, brand heritage, and exclusive offerings. Leading companies such as GUCCI Group, United Colors of Benetton, Jack & Jill Clothing Inc., J Crew Group Inc., DKNY, Burberry Group, GIORGIO Armani S.p.A, Fendi Kids, and Moncler Enfant anchor the market with wide-ranging product portfolios, iconic designs, and strategic collaborations. These brands focus on enhancing their value proposition through high-quality materials, limited-edition collections, and targeted marketing to affluent parents. Expansion into emerging markets, e-commerce channel development, and personalized customer experiences further strengthen their competitive positioning. The market also witnesses increasing investments in sustainability and ethical practices, as consumers become more discerning. Intense competition encourages continuous product innovation and the launch of exclusive offerings, ensuring dynamic growth and high consumer engagement within the luxury kids’ segment.
Key Player Analysis
- GUCCI Group
- United Colors of Benetton
- Jack & Jill Clothing Inc.
- J Crew Group Inc.
- DKNY
- Burberry Group
- GIORGIO Armani S.p.A
- Fendi Kids
- Moncler Enfant
Recent Developments
- In July 2024, Mubadala Capital, the asset management arm of Abu Dhabi’s sovereign wealth fund, acquired a majority stake in high-end stroller brand Bugaboo from Bain Capital. This acquisition, valuing Bugaboo at several hundred million pounds, aims to leverage growth opportunities in markets such as the U.S. and Asia. Bugaboo’s management team remains in place, with Bain retaining a minority stake.
- In June 2024, Heroes, a company specializing in acquiring small businesses that sell baby and youth products through Amazon Marketplace, reported an annual sales growth rate of 201.43% over three years, reaching sales of £82.2 million. The company has raised over £200 million from investors and has acquired brands such as Trunki, Cherish, and Baby Uma, significantly enhancing its market presence.
Market Concentration & Characteristics
The Luxury Products for Kids Market displays a moderate to high level of market concentration, with several leading global brands holding significant shares. It is characterized by the dominance of renowned fashion houses such as GUCCI Group, Burberry Group, United Colors of Benetton, and GIORGIO Armani S.p.A, which set industry benchmarks through exclusive collections and innovation. The market favors established players with strong brand recognition, high-quality materials, and strategic collaborations. Entry barriers remain high due to the need for significant investment in product development, marketing, and distribution networks. It exhibits strong brand loyalty among affluent consumers, who prioritize premium quality, safety, and style for their children. The market features a broad product range that spans apparel, toys, furniture, and travel gear, with apparel emerging as the largest segment. A growing focus on sustainability, ethical sourcing, and digital retail channels further defines market characteristics, shaping the competitive strategies of top players.
Report Coverage
The research report offers an in-depth analysis based on Product, Age Group, Sales Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Luxury Products for Kids Market will expand through rising demand for eco-conscious and ethically sourced goods.
- Luxury brands will increase personalization services to enhance customer experiences.
- E-commerce platforms will gain importance through enhanced virtual showrooms and AI-driven recommendations.
- Collaborations with children's designers and influencers will support brand differentiation.
- Limited-edition and bespoke collections will appeal to affluent parents seeking uniqueness.
- Augmented reality technology will allow virtual fittings and interactive product exploration.
- Expanding into emerging markets will drive revenue from rising middle-class populations.
- Premium baby care and wellness products will receive heightened attention through health-focused innovations.
- Investments in sustainable packaging and recycling programs will strengthen brand trust.
- Loyalty programs and experiential retail events will fuel customer retention.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Disposable Income and Urbanization
Increasing disposable incomes among urban families, especially in Asia Pacific, enable higher spending on premium children's products, fueling demand for luxury apparel, toys, and accessories.
Influence of Social Media and Celebrity Endorsements
Social media platforms and celebrity endorsements amplify brand visibility and aspirational purchasing, encouraging affluent parents to invest in luxury products for their children.
Expansion of E-Commerce and Digital Retail
The growth of online stores and digital retail channels provides convenient access to global luxury brands, exclusive collections, and personalized shopping experiences, significantly boosting market penetration.
Brand Innovation and Premiumization
Continuous innovation, including limited-edition collections, designer collaborations, and customization options, allows brands to differentiate their offerings and justify premium pricing, attracting discerning consumers.
Sustainability and Ethical Consumption
Growing parental awareness of environmental and ethical issues drives demand for eco-friendly, ethically sourced luxury products, prompting brands to invest in sustainable materials and transparent supply chains.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth rate of the Global Luxury Products For Kids market?
What factors are driving the growth of the Luxury Products for Kids Market?
What are the key segments within the Luxury Products for Kids Market?
Who are the major players in the Luxury Products for Kids Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Apparel
- 1.2.2 Toys and Games
- 1.2.3 Furniture
- 1.2.4 Baby Care Products
- 1.2.5 Travel Gear
- 1.2.6 Others
- 1.3 By Age Group
- 1.3.1 1-5
- 1.3.2 6-10
- 1.3.3 11-15
- 1.4 By Sales Channel
- 1.4.1 Retail Stores
- 1.4.2 Supermarket/Hypermarket
- 1.4.3 Online Stores
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 35,139.9 million → 2032: USD 55,510.7 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Luxury Products for Kids Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Luxury Products for Kids Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Luxury Products for Kids Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Luxury Products for Kids Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Luxury Products for Kids Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Luxury Products for Kids Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Luxury Products for Kids Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Luxury Products for Kids Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 35,139.9 million → 2032: USD 55,510.7 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Luxury Products for Kids Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Apparel
- 12.3.7.2 Toys and Games
- 12.3.7.3 Furniture
- 12.3.7.4 Baby Care Products
- 12.3.7.5 Travel Gear
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Age Group - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 1-5
- 12.4.7.2 6-10
- 12.4.7.3 11-15
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Sales Channel - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Retail Stores
- 12.5.7.2 Supermarket/Hypermarket
- 12.5.7.3 Online Stores
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Luxury Products for Kids Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Luxury Products for Kids Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Luxury Products for Kids Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 GUCCI Group
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 United Colors of Benetton
- 17.4 Jack & Jill Clothing Inc.
- 17.5 J Crew Group Inc.
- 17.6 DKNY
- 17.7 Burberry Group
- 17.8 GIORGIO Armani S.p.A
- 17.9 Fendi Kids
- 17.10 Moncler Enfant
- 17.11 Bugaboo
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

