
Market Overview
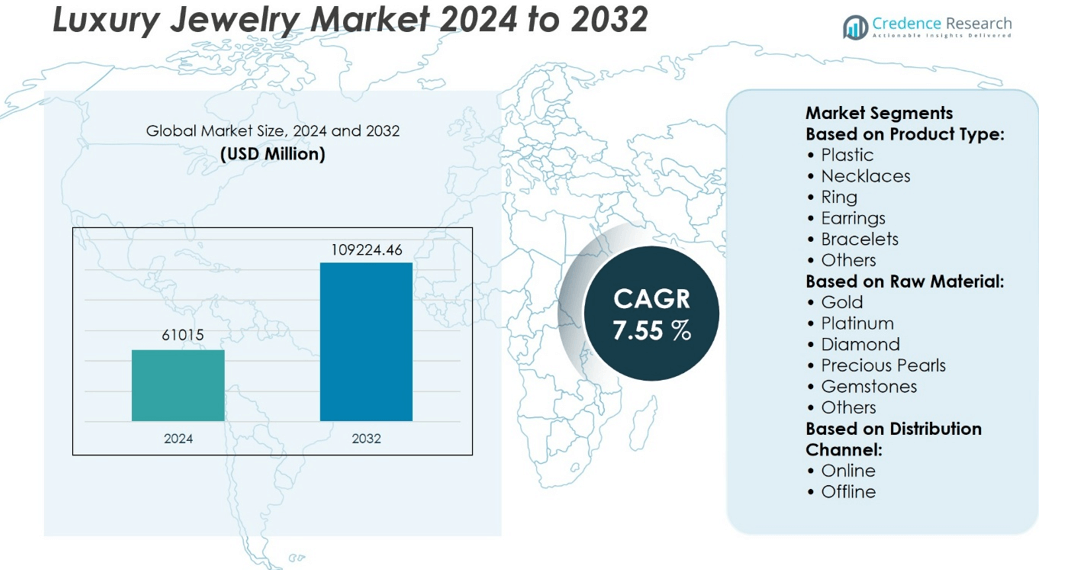
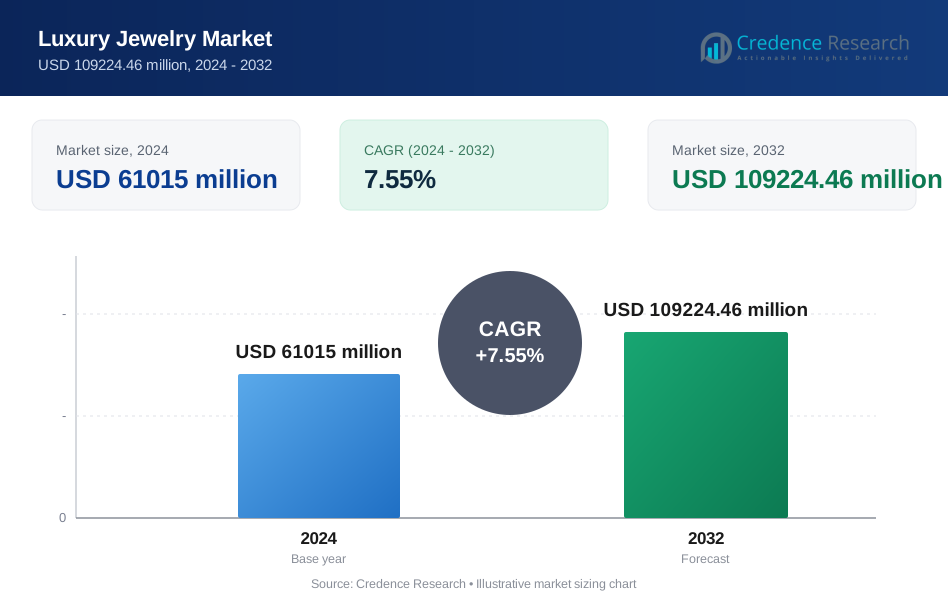
Luxury Jewelry Market size was valued at USD 61015 million in 2024 and is anticipated to reach USD 109224.46 million by 2032, at a CAGR of 7.55% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Luxury Jewelry Market Size 2024 | USD 61015 million |
| Luxury Jewelry Market, CAGR | 7.5% |
| Luxury Jewelry Market Size 2032 | USD 109224.46 million |
The Luxury Jewelry Market grows on strong drivers such as rising disposable income, cultural significance of jewelry in weddings and celebrations, and expanding demand from high-net-worth individuals across global regions. It benefits from increasing adoption of sustainable materials, ethical sourcing, and transparent supply chains that align with evolving consumer values. Digital transformation enhances accessibility through e-commerce, virtual try-ons, and personalized online experiences. Design innovation, blending heritage with modern aesthetics, strengthens brand appeal among younger consumers. The market trends highlight growing interest in gender-neutral collections, bespoke services, and integration of jewelry as both a fashion statement and long-term investment.
The Luxury Jewelry Market shows strong geographical presence, with Asia-Pacific leading due to cultural affinity and rising incomes, North America sustaining growth through high purchasing power, and Europe maintaining strength with heritage brands and tourist demand. The Middle East and Latin America present emerging opportunities fueled by rising affluence and brand expansion. Key players include Cartier, Tiffany & Co., Bvlgari, Van Cleef & Arpels, Chopard, Harry Winston, Graff Diamonds, Piaget, Mikimoto, and Rolex, each reinforcing global market competitiveness.
Market Insights
- The Luxury Jewelry Market size was valued at USD 61015 million in 2024 and is expected to reach USD 109224.46 million by 2032, at a CAGR of 7.55%.
- Rising disposable income and cultural importance of jewelry in weddings and celebrations drive consistent global demand.
- Growing adoption of sustainable materials, ethical sourcing, and transparent supply chains shapes purchasing decisions.
- Digital transformation with e-commerce, virtual try-ons, and personalized services enhances consumer engagement.
- Competition remains strong as leading brands focus on heritage, craftsmanship, exclusivity, and design innovation.
- High costs of raw materials and strict regulations act as restraints, challenging smaller entrants in the market.
- Asia-Pacific dominates growth with cultural affinity and rising incomes, North America thrives on high purchasing power, Europe sustains heritage-driven demand, and the Middle East and Latin America show emerging opportunities supported by brand expansion.
Market Drivers
Rising Demand Driven by High-Net-Worth Individuals and Expanding Affluent Classes
The Luxury Jewelry Market benefits from the steady rise in high-net-worth individuals and the expanding affluent classes in both developed and emerging economies. Consumers with significant disposable income invest in fine jewelry to showcase wealth, heritage, and social standing. It reflects a preference for exclusivity, rarity, and craftsmanship in purchase decisions. Global wealth growth drives consistent demand for premium collections, rare gemstones, and bespoke designs. Luxury brands strengthen their positioning through private showrooms and exclusive launches targeted at elite buyers. This factor elevates the overall growth trajectory of the market.
- For instance, Cartier, part of Richemont Group, reported jewelry sales of €12,480 million in fiscal 2024, supported by strong demand from affluent customers across Asia and the Middle East.
Increasing Consumer Preference for Branded and Authenticated Jewelry Pieces
The Luxury Jewelry Market gains momentum from a rising preference for branded products that guarantee authenticity and enduring value. Buyers prioritize traceability of materials, certified gemstones, and hallmarking processes to ensure credibility. It strengthens trust and promotes loyalty toward established luxury houses. Brands highlight heritage, craftsmanship, and innovation to reinforce exclusivity. Authentication technologies, including blockchain-based certification, enhance buyer confidence. This driver enhances the market’s resilience against counterfeit products.
- For instance, Tiffany & Co., acquired by LVMH in 2021, reported jewelry sales of $5,115 million in fiscal 2023, supported by its Diamond.
Expansion of E-Commerce Channels and Digital Client Engagement Platforms
The Luxury Jewelry Market adapts to changing consumer behavior through digital retail and personalized online experiences. E-commerce platforms introduce wider product visibility, curated catalogs, and secure purchasing frameworks for global clients. It enables international expansion of luxury brands by reaching customers beyond traditional flagship stores. Virtual try-on solutions, AI-driven recommendations, and live consultations replicate the luxury experience online. High-value transactions through secure digital platforms create strong trust among consumers. This factor broadens access to luxury collections and elevates sales opportunities.
Heightened Focus on Sustainability and Ethical Sourcing Practices
The Luxury Jewelry Market evolves through growing emphasis on sustainability, transparency, and ethical sourcing. Consumers seek responsibly mined diamonds, recycled metals, and environmentally conscious practices in jewelry manufacturing. It compels brands to disclose sourcing methods and adopt traceability measures. Government regulations and industry standards reinforce this direction, ensuring compliance with ethical benchmarks. Leading luxury houses integrate sustainability into brand narratives, appealing to socially responsible consumers. This shift strengthens the long-term trust and value perception of the market.
Market Trends
Growing Influence of High Jewelry Collaborations and Limited-Edition Collections
The Luxury Jewelry Market observes strong momentum from collaborations between heritage brands and renowned designers or artists. These partnerships create limited-edition collections that heighten exclusivity and attract elite buyers. It strengthens brand prestige while catering to consumers seeking originality and cultural connection. Limited availability reinforces desirability and premium positioning. Collaborations often integrate unique craftsmanship with modern aesthetics to appeal to younger high-net-worth audiences. This trend elevates luxury jewelry into collectible art forms.
- For instance, Bvlgari, part of LVMH, collaborated with architect Zaha Hadid on the B.Zero1 Design Legend collection, and in 2023 its jewelry division reported sales of 3,079 million, reflecting how innovative collaborations with world-class designers can strengthen exclusivity and drive substantial revenues.
Digital Transformation through Virtual Retail Experiences and Immersive Tools
The Luxury Jewelry Market adapts to digital transformation with technologies that enhance engagement. Virtual try-on solutions, augmented reality, and immersive platforms replicate the in-store luxury experience. It provides consumers with confidence in high-value purchases without physical presence. Brands invest in AI-driven personalization to create tailored product recommendations. Secure digital channels support global expansion while maintaining exclusivity. This trend accelerates the adoption of omnichannel strategies in luxury retail.
- For instance, Cartier integrated augmented reality try-on features and immersive e-commerce platforms across key markets, which contributed to Richemont’s Jewellery Maisons division generating €15,328 million in sales during fiscal year 2025.
Increasing Popularity of Gender-Neutral and Customizable Jewelry Designs
The Luxury Jewelry Market evolves with rising acceptance of gender-neutral collections and customizable pieces. Consumers value personal expression over traditional design boundaries. It drives brands to release versatile collections suited for diverse audiences. Customization options, including engraving and modular designs, strengthen emotional connection and individuality. Younger consumers view jewelry as both an investment and a lifestyle accessory. This trend reshapes creative direction and expands customer inclusivity.
Strong Emphasis on Ethical Luxury and Sustainable Craftsmanship Standards
The Luxury Jewelry Market witnesses a marked shift toward ethical sourcing and sustainable craftsmanship. Responsible mining practices, recycled metals, and lab-grown diamonds gain acceptance among conscious consumers. It compels leading brands to integrate transparency into supply chains and marketing strategies. Certifications and blockchain traceability assure buyers of ethical authenticity. Consumers increasingly favor brands that align with sustainability and social responsibility values. This trend reinforces long-term trust in luxury jewelry investments.
Market Challenges Analysis
Rising Impact of Counterfeiting and Market Saturation in Key Luxury Hubs
The Luxury Jewelry Market faces persistent challenges from counterfeit products and unauthorized replicas that undermine brand integrity. Counterfeiting erodes consumer trust and diverts significant revenue from legitimate channels. It compels brands to invest heavily in authentication technologies and legal enforcement. Market saturation in mature regions further intensifies competition, reducing growth opportunities for established players. Rising consumer expectations for innovation and exclusivity pressure brands to continuously refresh collections. These factors complicate long-term stability in competitive markets.
Escalating Raw Material Costs and Vulnerability to Regulatory Scrutiny
The Luxury Jewelry Market confronts rising costs of precious metals and gemstones, which directly impact margins and pricing strategies. It forces brands to balance between premium positioning and affordability for high-net-worth buyers. Regulatory scrutiny on ethical sourcing, environmental compliance, and labor practices intensifies the operational burden. Transparency requirements demand robust traceability systems, adding cost and complexity to global supply chains. Currency fluctuations further complicate procurement for brands dependent on international sourcing. These challenges place sustained pressure on profitability and operational efficiency.
Market Opportunities
Expansion Potential through Emerging Markets and Wealth Growth in New Economies
The Luxury Jewelry Market holds significant opportunities in emerging economies where rising disposable incomes and expanding affluent classes stimulate demand. It benefits from the growing number of first-time luxury buyers seeking premium products that symbolize status and investment value. Urbanization and lifestyle shifts in Asia-Pacific, Middle East, and parts of Latin America create untapped avenues for luxury brands. Strategic retail expansion into these regions provides access to a wider consumer base. Exclusive boutiques, pop-up experiences, and personalized services can strengthen loyalty in these new markets. This creates a foundation for sustained revenue growth across underpenetrated geographies.
Opportunities through Innovation in Sustainable Materials and Digital Experiences
The Luxury Jewelry Market can leverage innovation in sustainable materials and digital platforms to attract younger, socially conscious buyers. It gains momentum from rising demand for lab-grown diamonds, recycled metals, and ethically sourced gemstones. Transparent supply chains and certification systems reinforce consumer trust. At the same time, digital engagement tools such as virtual try-on, AI-based personalization, and secure e-commerce channels create new sales pathways. Integration of technology with craftsmanship enables brands to extend exclusivity into the online sphere. This dual focus on sustainability and digital luxury offers strong opportunities for long-term differentiation.
Market Segmentation Analysis:
By Product Type
The Luxury Jewelry Market shows versatility across necklaces, rings, earrings, bracelets, and other premium categories. Rings remain central, supported by strong association with weddings, engagements, and milestone celebrations. Necklaces attract significant attention due to their role in high jewelry collections and cultural symbolism. It underlines the enduring relevance of earrings as both fashion statements and investment pieces. Bracelets appeal to younger demographics seeking versatile and collectible designs. Other luxury items, including brooches and bespoke creations, strengthen the overall product mix and cater to niche demand.
By Raw Material
The Luxury Jewelry Market demonstrates strong demand across gold, platinum, diamonds, precious pearls, and gemstones. Gold remains the most widely used material, valued for both cultural significance and investment appeal. Platinum attracts consumers seeking exclusivity and rarity, while diamonds maintain dominance in engagement and wedding collections. It highlights enduring consumer trust in certified diamond jewelry across global markets. Precious pearls and colored gemstones add diversity, appealing to buyers who prioritize uniqueness and aesthetic value. Other innovative materials, including recycled metals and lab-grown diamonds, expand options for socially responsible consumers.
- For instance, Bvlgari, a brand owned by LVMH, contributed to LVMH's impressive Watches & Jewelry division sales of €10,902 million by expanding its Forever and Serpenti collections.
By Distribution Channel
The Luxury Jewelry Market evolves with a dual focus on online and offline channels. Offline retail continues to dominate through flagship stores, exclusive boutiques, and high-end department stores where brand experience and personal interaction remain crucial. It emphasizes the role of offline formats in reinforcing brand heritage and exclusivity. Online channels gain momentum as digital platforms enhance accessibility and personalization. Virtual try-on tools, secure transactions, and curated digital catalogs increase consumer confidence in purchasing high-value items online. Both channels create complementary growth pathways that strengthen the reach and visibility of luxury jewelry brands.
- For instance, Tiffany & Co. strengthened its e-commerce presence by exclusive high-jewelry SKUs in 2023, contributing to LVMH’s Watches & Jewelry division revenue of €10,902 million.
Segments:
Based on Product Type:
- Plastic
- Necklaces
- Ring
- Earrings
- Bracelets
- Others
Based on Raw Material:
- Gold
- Platinum
- Diamond
- Precious Pearls
- Gemstones
- Others
Based on Distribution Channel:
- Online
- Offline
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a 39.2% share of the luxury jewelry market, supported by high purchasing power and established luxury brands. The United States leads demand, particularly in metropolitan areas such as New York and Los Angeles. Consumers in the region value design innovation, personalization, and sustainable sourcing. E-commerce and digital marketing enhance accessibility, while celebrity endorsements and cultural trends drive brand loyalty. North America remains a key hub for innovation and luxury retail.
Europe
Europe accounts for 21.5% share of the global luxury jewelry market. The region is home to some of the most prestigious luxury houses, including those in France, Italy, and Switzerland. Heritage, craftsmanship, and strong tourism activity sustain demand. European consumers favor classic, timeless designs alongside new trends in ethical sourcing and sustainable production. Luxury jewelry is also supported by high tourist spending in destinations like Paris, Milan, and London.
Asia-Pacific
Asia-Pacific dominates the global luxury jewelry market with 66.6% share. The region’s leadership is driven by strong demand in China and India, where jewelry holds cultural importance in weddings, festivals, and investments. Rising disposable income, a growing middle class, and urbanization support continuous growth. Local manufacturing, brand recognition, and increasing customization also strengthen the region’s position. International and domestic players expand aggressively, making Asia-Pacific the largest and fastest-growing market.
Latin America
Latin America represents 4.5% share of the luxury jewelry market. Brazil and Mexico are the largest contributors, supported by growing middle classes and urban populations. Consumers in the region are increasingly adopting international luxury brands, while local jewelers gain popularity through cultural designs. Although smaller in scale, Latin America shows steady growth potential as awareness of global trends and online availability improves.
Middle East & Africa
The Middle East & Africa holds 7.8% share of the market. Demand is concentrated in Gulf countries such as the UAE, Saudi Arabia, and Qatar, where luxury jewelry is integral to cultural traditions and gifting. High-income consumers and a young, aspirational population support market expansion. Events such as jewelry expos in Riyadh and Dubai further encourage growth. Africa also shows rising interest, particularly in South Africa, due to increasing urban affluence.
Key Player Analysis
- Mikimoto
- Graff Diamonds
- Rolex
- Bvlgari
- Harry Winston
- Piaget
- Chopard
- Van Cleef & Arpels
- Tiffany & Co.
- Cartier
Competitive Analysis
The luxury jewelry market features led by Cartier, Tiffany & Co., Bvlgari, Van Cleef & Arpels, Chopard, Harry Winston, Graff Diamonds, Piaget, Mikimoto, and Rolex. The luxury jewelry market is highly competitive, defined by heritage brands with long-standing reputations for craftsmanship, exclusivity, and design excellence. Competition centers on product innovation, rare gemstone sourcing, and the ability to deliver personalized experiences that appeal to affluent consumers. Companies focus on expanding global retail footprints, investing in digital platforms, and strengthening brand loyalty through storytelling and cultural collaborations. Sustainability and ethical sourcing have become critical differentiators, with leading houses promoting transparency in their supply chains to meet shifting consumer expectations. Marketing strategies increasingly combine tradition with modernity, highlighting both artisanal heritage and contemporary lifestyle appeal. As competition intensifies, the market rewards players that balance exclusivity with accessibility, while adapting quickly to evolving consumer values and regional preferences.
Recent Developments
- In February 2025, Tanishq debuted at New York Fashion Week, collaborating with fashion designer, Bibhu Mohapatra. The collaboration featured over 40 creations, complementing Bibhu's 2025 Fall collection inspired by Indian heritage.
- In February 2025, Aesop, known for its unconventional fragrances, collaborated with jeweler Patcharavipa Bodiratnangkura to create a limited-edition rhodium-plated ear cuff, inspired by the brand's floral fragrance "Aurner."
- In January 2025, Graff unveiled a new masterpiece in celebration of Haute Couture Week in Paris showcasing exquisite high jewelry creations.
- In July 2024, Marie Claire USA collaborated with luxury jewelry brand Tacori for the WORTH it content series, exploring the brand's heritage that began three generations ago.
Market Concentration & Characteristics
The Luxury Jewelry Market demonstrates a high level of concentration, with a small group of established global brands controlling significant market share through heritage, exclusivity, and strong distribution networks. It is characterized by premium positioning, limited accessibility, and high brand loyalty, supported by reputations built over decades. The market places strong emphasis on craftsmanship, rare materials, and innovative designs that blend tradition with modern trends. It continues to expand in regions with rising disposable income and cultural affinity for jewelry, while mature markets focus on personalization, ethical sourcing, and sustainable production practices. Competition remains intense, yet differentiated by brand storytelling, bespoke services, and strategic collaborations that enhance exclusivity. High barriers to entry created by capital requirements, brand recognition, and consumer trust reinforce the dominance of incumbents. It reflects a blend of artistry, cultural symbolism, and investment value, shaping luxury jewelry as both a status symbol and a personal expression.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Raw Material, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand further in Asia-Pacific driven by rising incomes and strong cultural demand for jewelry.
- Sustainability will remain a critical focus with brands investing in ethical sourcing and transparent supply chains.
- Digital platforms will play a larger role in sales as consumers increasingly purchase luxury jewelry online.
- Personalization will grow as customers seek unique designs and bespoke services tailored to individual preferences.
- Heritage and craftsmanship will continue to define brand value while appealing to high-net-worth consumers.
- Demand for gender-neutral and versatile designs will increase as fashion trends evolve globally.
- Investment in rare gemstones and high-value collections will rise as consumers view jewelry as both luxury and asset.
- Collaborations with fashion, art, and culture will strengthen brand storytelling and consumer engagement.
- Expansion into emerging markets in Latin America and the Middle East will create new revenue opportunities.
- Innovation in design and integration of modern aesthetics will help established brands retain competitive advantage.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Luxury Jewelry Market?
What factors are driving the growth of the Luxury Jewelry Market?
What are some challenges faced by the Luxury Jewelry Market?
Who are the major players in the Luxury Jewelry Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Luxury Jewelry Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Luxury Jewelry Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 61015 million → 2032: USD 109224.46 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Luxury Jewelry Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Luxury Jewelry Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Luxury Jewelry Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Luxury Jewelry Market Drivers
- 3.3 Luxury Jewelry Market Restraints & Challenges
- 3.4 Luxury Jewelry Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Luxury Jewelry Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Luxury Jewelry Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Luxury Jewelry category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Luxury Jewelry Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Luxury Jewelry Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Luxury Jewelry. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Luxury Jewelry Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Luxury Jewelry Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Luxury Jewelry Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Luxury Jewelry (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Luxury Jewelry
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Luxury Jewelry Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Luxury Jewelry Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Luxury Jewelry Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Luxury Jewelry Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Luxury Jewelry Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Luxury Jewelry Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Luxury Jewelry Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Luxury Jewelry Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
