
Imports supply most of the beef and mutton Malaysians eat
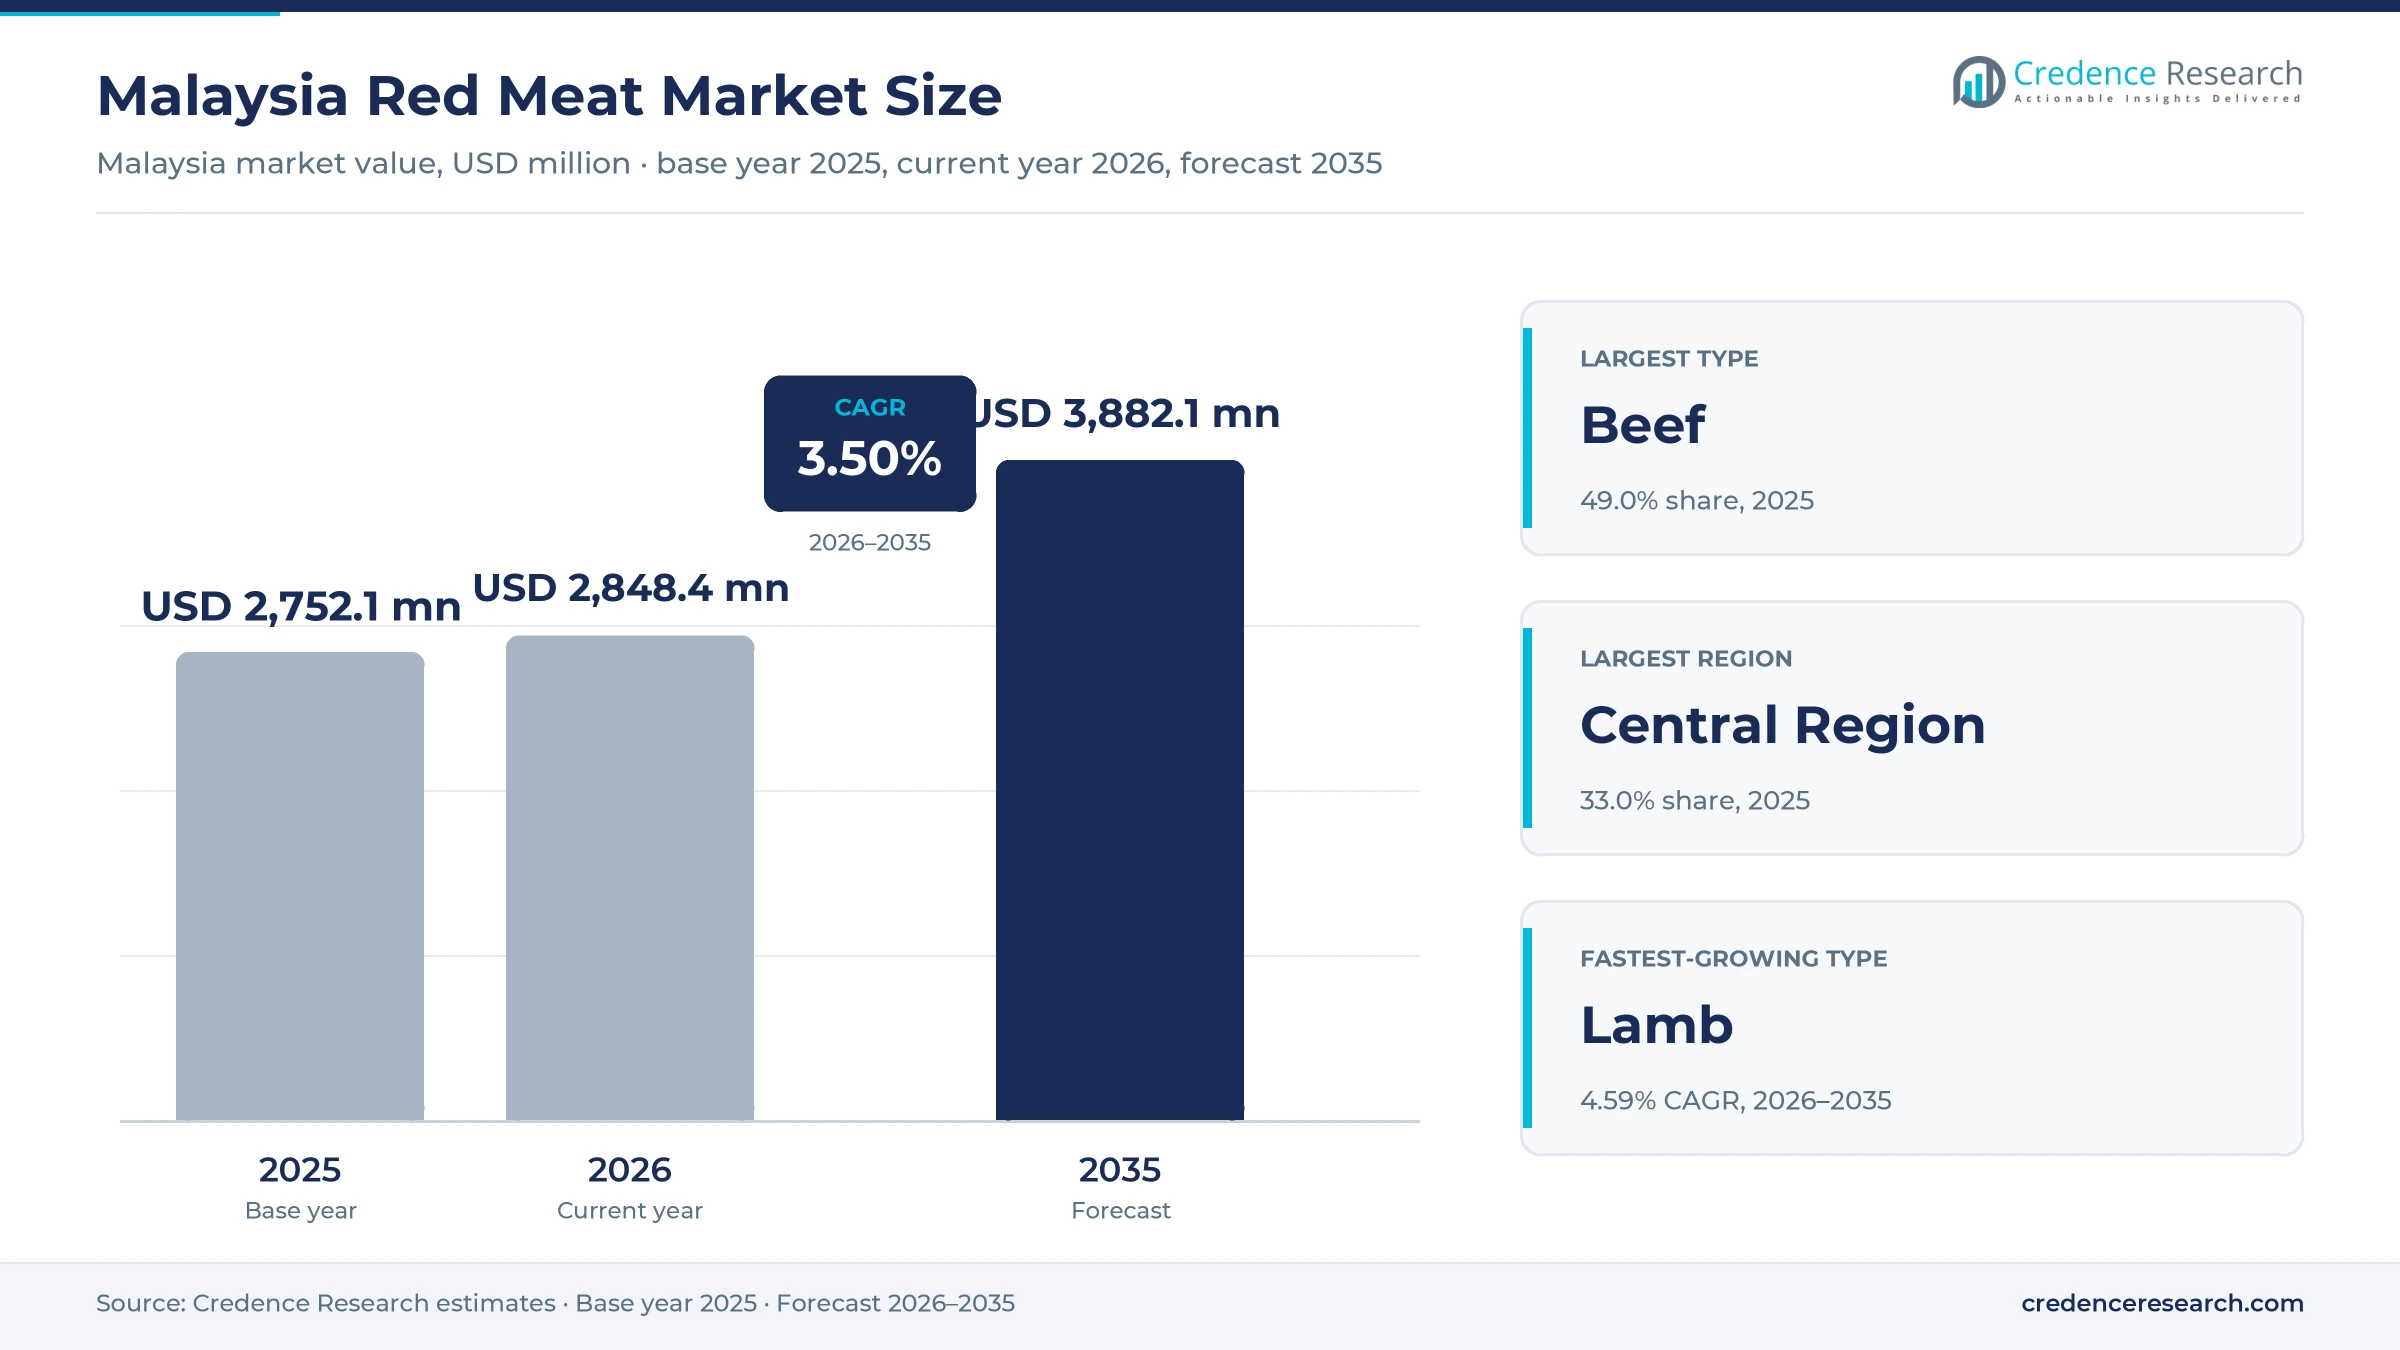
The Malaysia red meat market was valued at USD 2.75 billion in 2025 and is projected to increase from USD 2.85 billion in 2026 to USD 3.88 billion by 2035, registering a CAGR of 3.50% during 2026–2035. Demand comes from beef consumption of 8.6 kg per person in 2025, festival slaughter for Aidiladha and steady pork buying by non-Muslim households. Central Region held the largest regional share, 33.0% in 2025, because the Klang Valley combines the largest population with the densest supermarket and restaurant networks. East Malaysia is the fastest-growing region at 3.94% a year as Sabah upgrades government farms and expands local supply. Imports remain the core of supply, since local farms met less than a fifth of beef needs in 2024. The main policy change is the RM450 million Pengganda 30 herd program announced in February 2026, which aims to lift ruminant self-sufficiency to 50% by 2030.
What does the meat market in Malaysia include and how do buyers purchase?
The market counts the value of beef, buffalo meat, pork, mutton, lamb and goat meat sold in Malaysia as fresh, frozen or processed products through retail and food service channels. Beef and buffalo meat are counted together because Indian buffalo meat supplies most imported beef volume, according to Meat & Livestock Australia. Most households buy local beef and buffalo meat at wet markets, while hotels and restaurants buy imported chilled cuts through distributors.
Poultry, seafood, live animals sold for breeding and plant-based alternatives are excluded from the estimates. The value chain runs from foreign packers and local farms through quarantine stations, halal slaughterhouses and importers to wet market stalls, supermarkets, butchers and caterers.
Malaysia Red Meat Market Insights
- The market stands at USD 2.75 billion in 2025 and is forecast to reach USD 3.88 billion by 2035, a 3.50% CAGR over 2026–2035, as imports keep pace with beef and pork demand.
- The Central Region held 33.0% of value in 2025, since the Petaling and Ulu Langat districts alone had 3.9 million residents.
- Beef led types with 49.0% of 2025 value, as per capita beef consumption reached 8.6 kg, the highest in Southeast Asia.
- Selangor ended pig farming licenses in early 2026, and registered pig farms nationwide fell 22% to 338 in 2025 after swine fever outbreaks.
- Australia and Malaysia signed a halal red meat agreement in April 2026, and 27 Australian plants can now ship halal beef and sheepmeat.
Beef, frozen supply and wet markets hold most value
Why beef leads and lamb grows fastest among red meat types
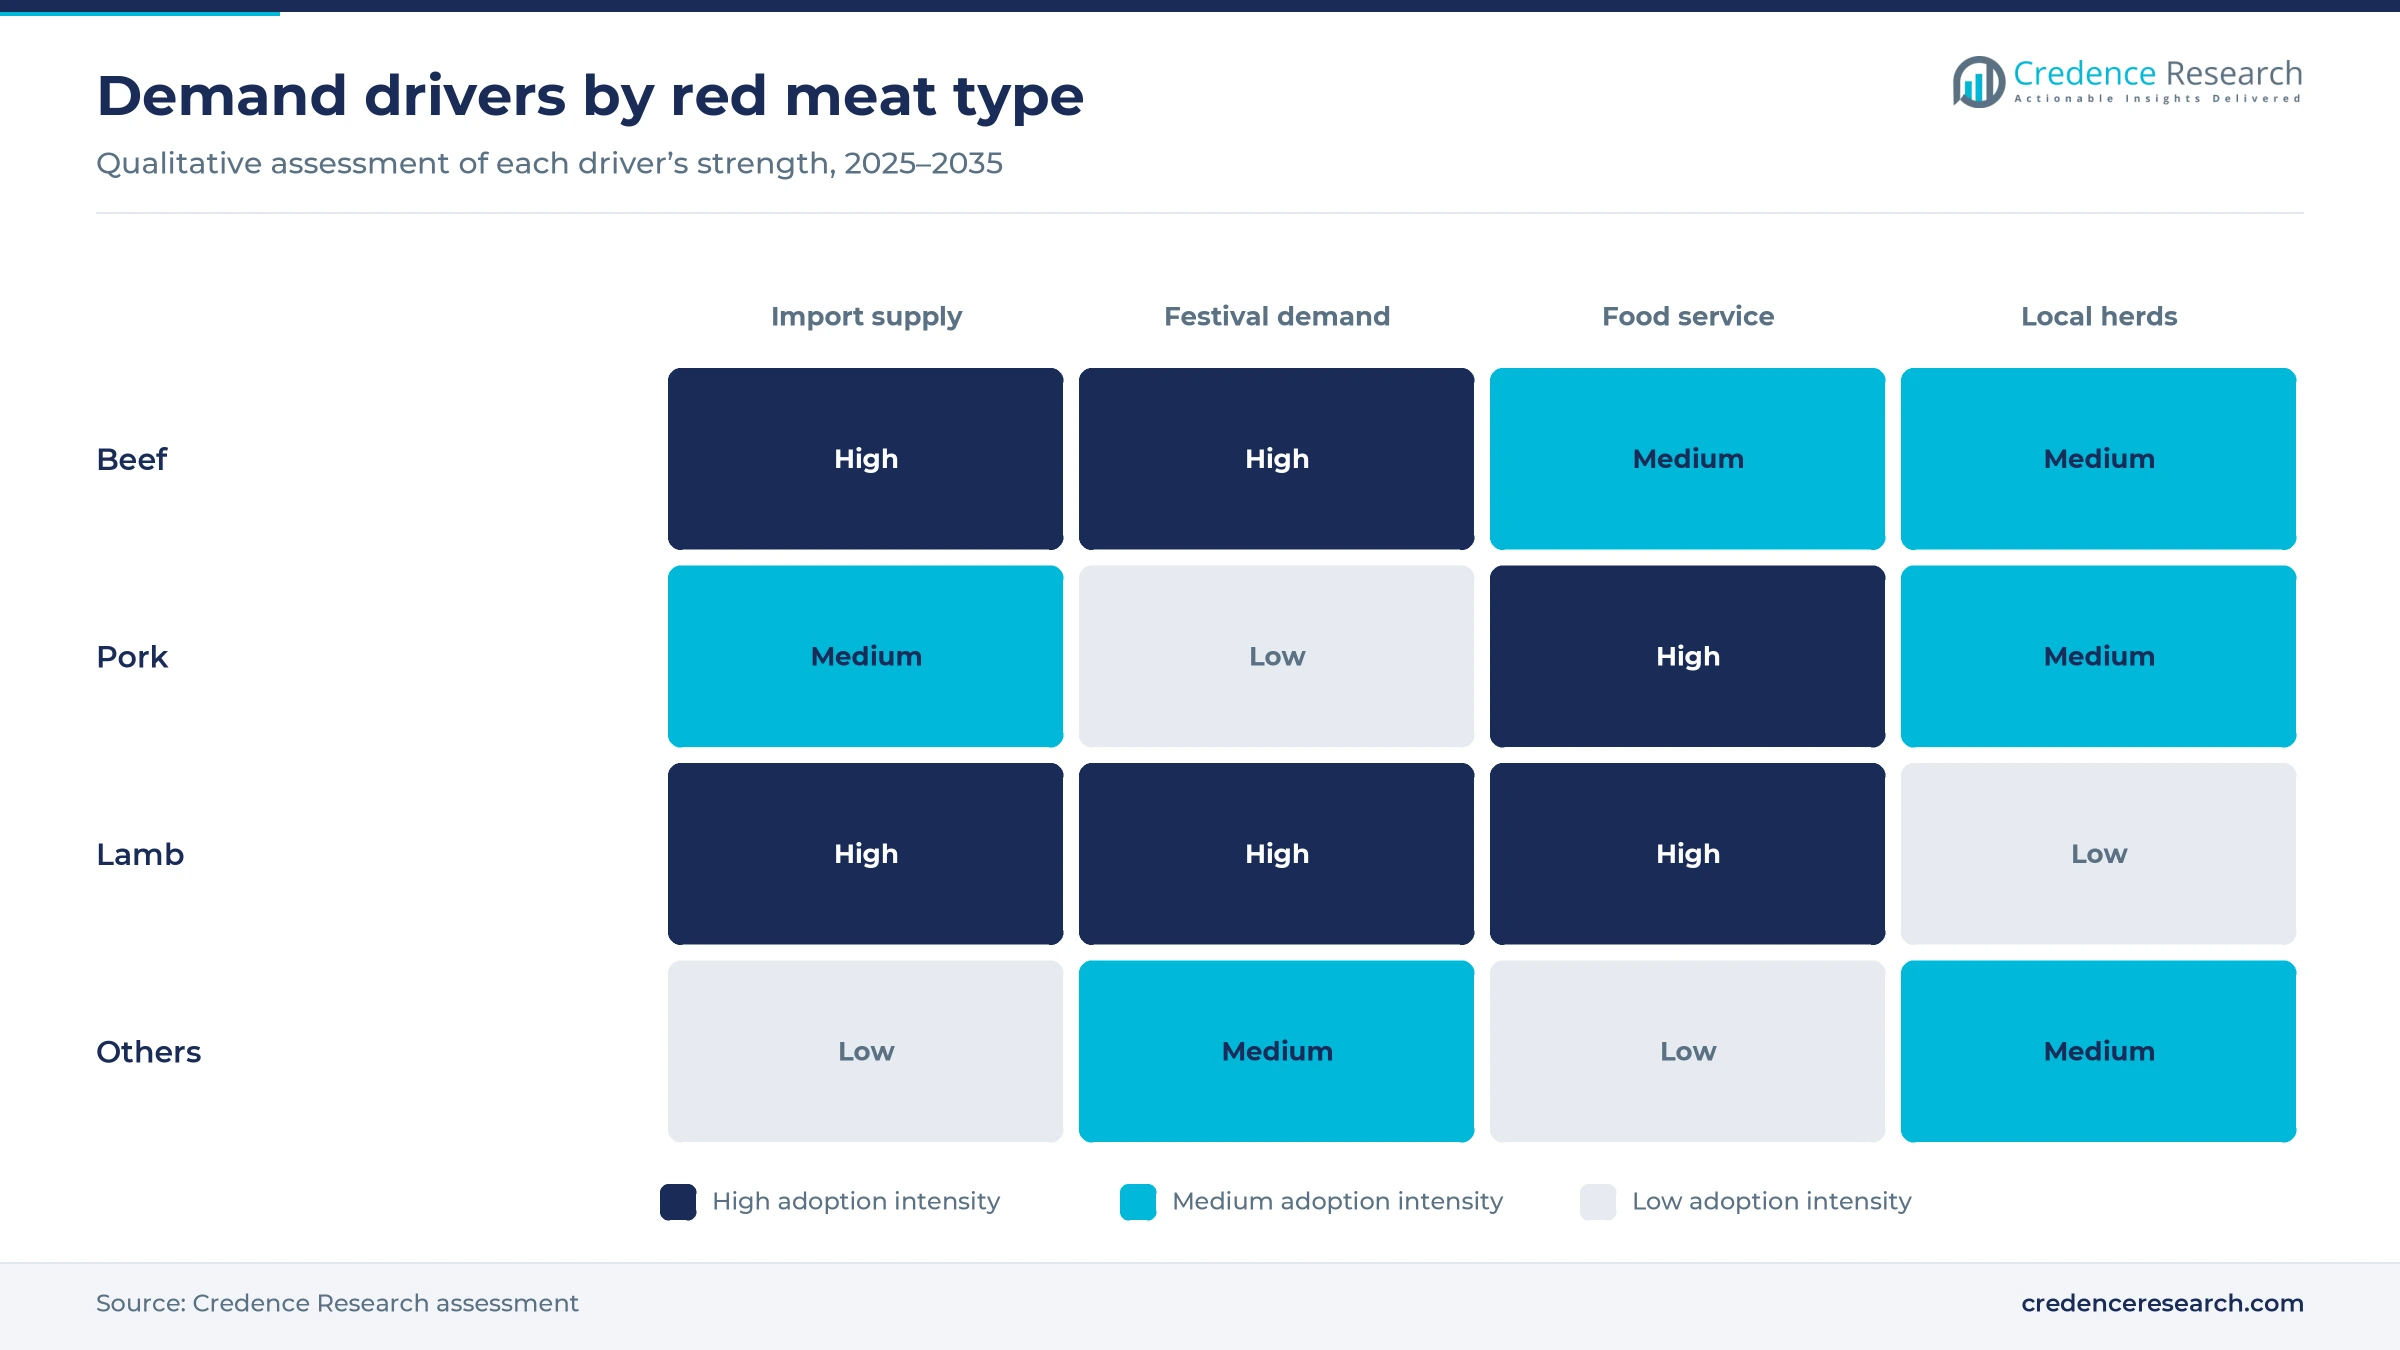
Based on type, the market is categorized into beef, pork, lamb and others. Beef led with 49.0% of 2025 value because Malaysians ate 8.6 kg of beef per person in 2025, the highest level in Southeast Asia, according to Meat & Livestock Australia. Pork follows, since non-Muslim residents, 36.5% of the population, need an estimated 213,927.92 tons in 2026, according to agriculture ministry figures given to Parliament. Lamb grows fastest at 4.59% a year, as sheepmeat imports rose to 46,774 tons worth A$379 million in the 12 months to August 2025, up from A$289 million a year earlier.
How frozen imports lead and processed lines grow fastest
Based on application, the market is categorized into fresh, frozen and processed products. Frozen products led with 46.0% of 2025 value because imports cover more than 80% of beef needs, with local farms meeting only 16.8% in 2024 according to the agriculture ministry, and Indian buffalo meat alone supplied 170,382 tons, or 82% of beef imports, in the 12 months to August 2025, according to MLA. Processed products grow fastest at 4.52% a year, as Johnsonville unit PrimaBaguz employs 330 people in Kuala Lumpur making more than 100 halal lines, including cold cuts and sausages, for restaurants, hotels and caterers.
Why wet markets lead while supermarkets gain the fastest
Based on distribution channel, the market is categorized into supermarkets/hypermarkets, traditional market/wet markets, convenience stores, online retail and others. Traditional Market/Wet Markets led with 48.0% of 2025 value because modern retailers hold only about 39% of grocery sales, and most shoppers still buy local beef and Indian buffalo meat at traditional markets, according to MLA. Supermarkets/Hypermarkets grow fastest at 4.29% a year, as chains open smaller stores of about 1,000 square meters with self-service fresh counters. AEON opened its first AEON STYLE supermarket at Setia EcoHill, Semenyih, on Dec. 12, 2025, with imported meat selections.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Type | Beef | 49.0% | Lamb | 4.59% |
| By Application | Frozen | 46.0% | Processed | 4.52% |
| By Distribution Channel | Traditional Market/Wet Markets | 48.0% | Supermarkets/Hypermarkets | 4.29% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Beef shortfall, halal festivals and pork demand lift sales
Beef demand far exceeds what local herds can supply
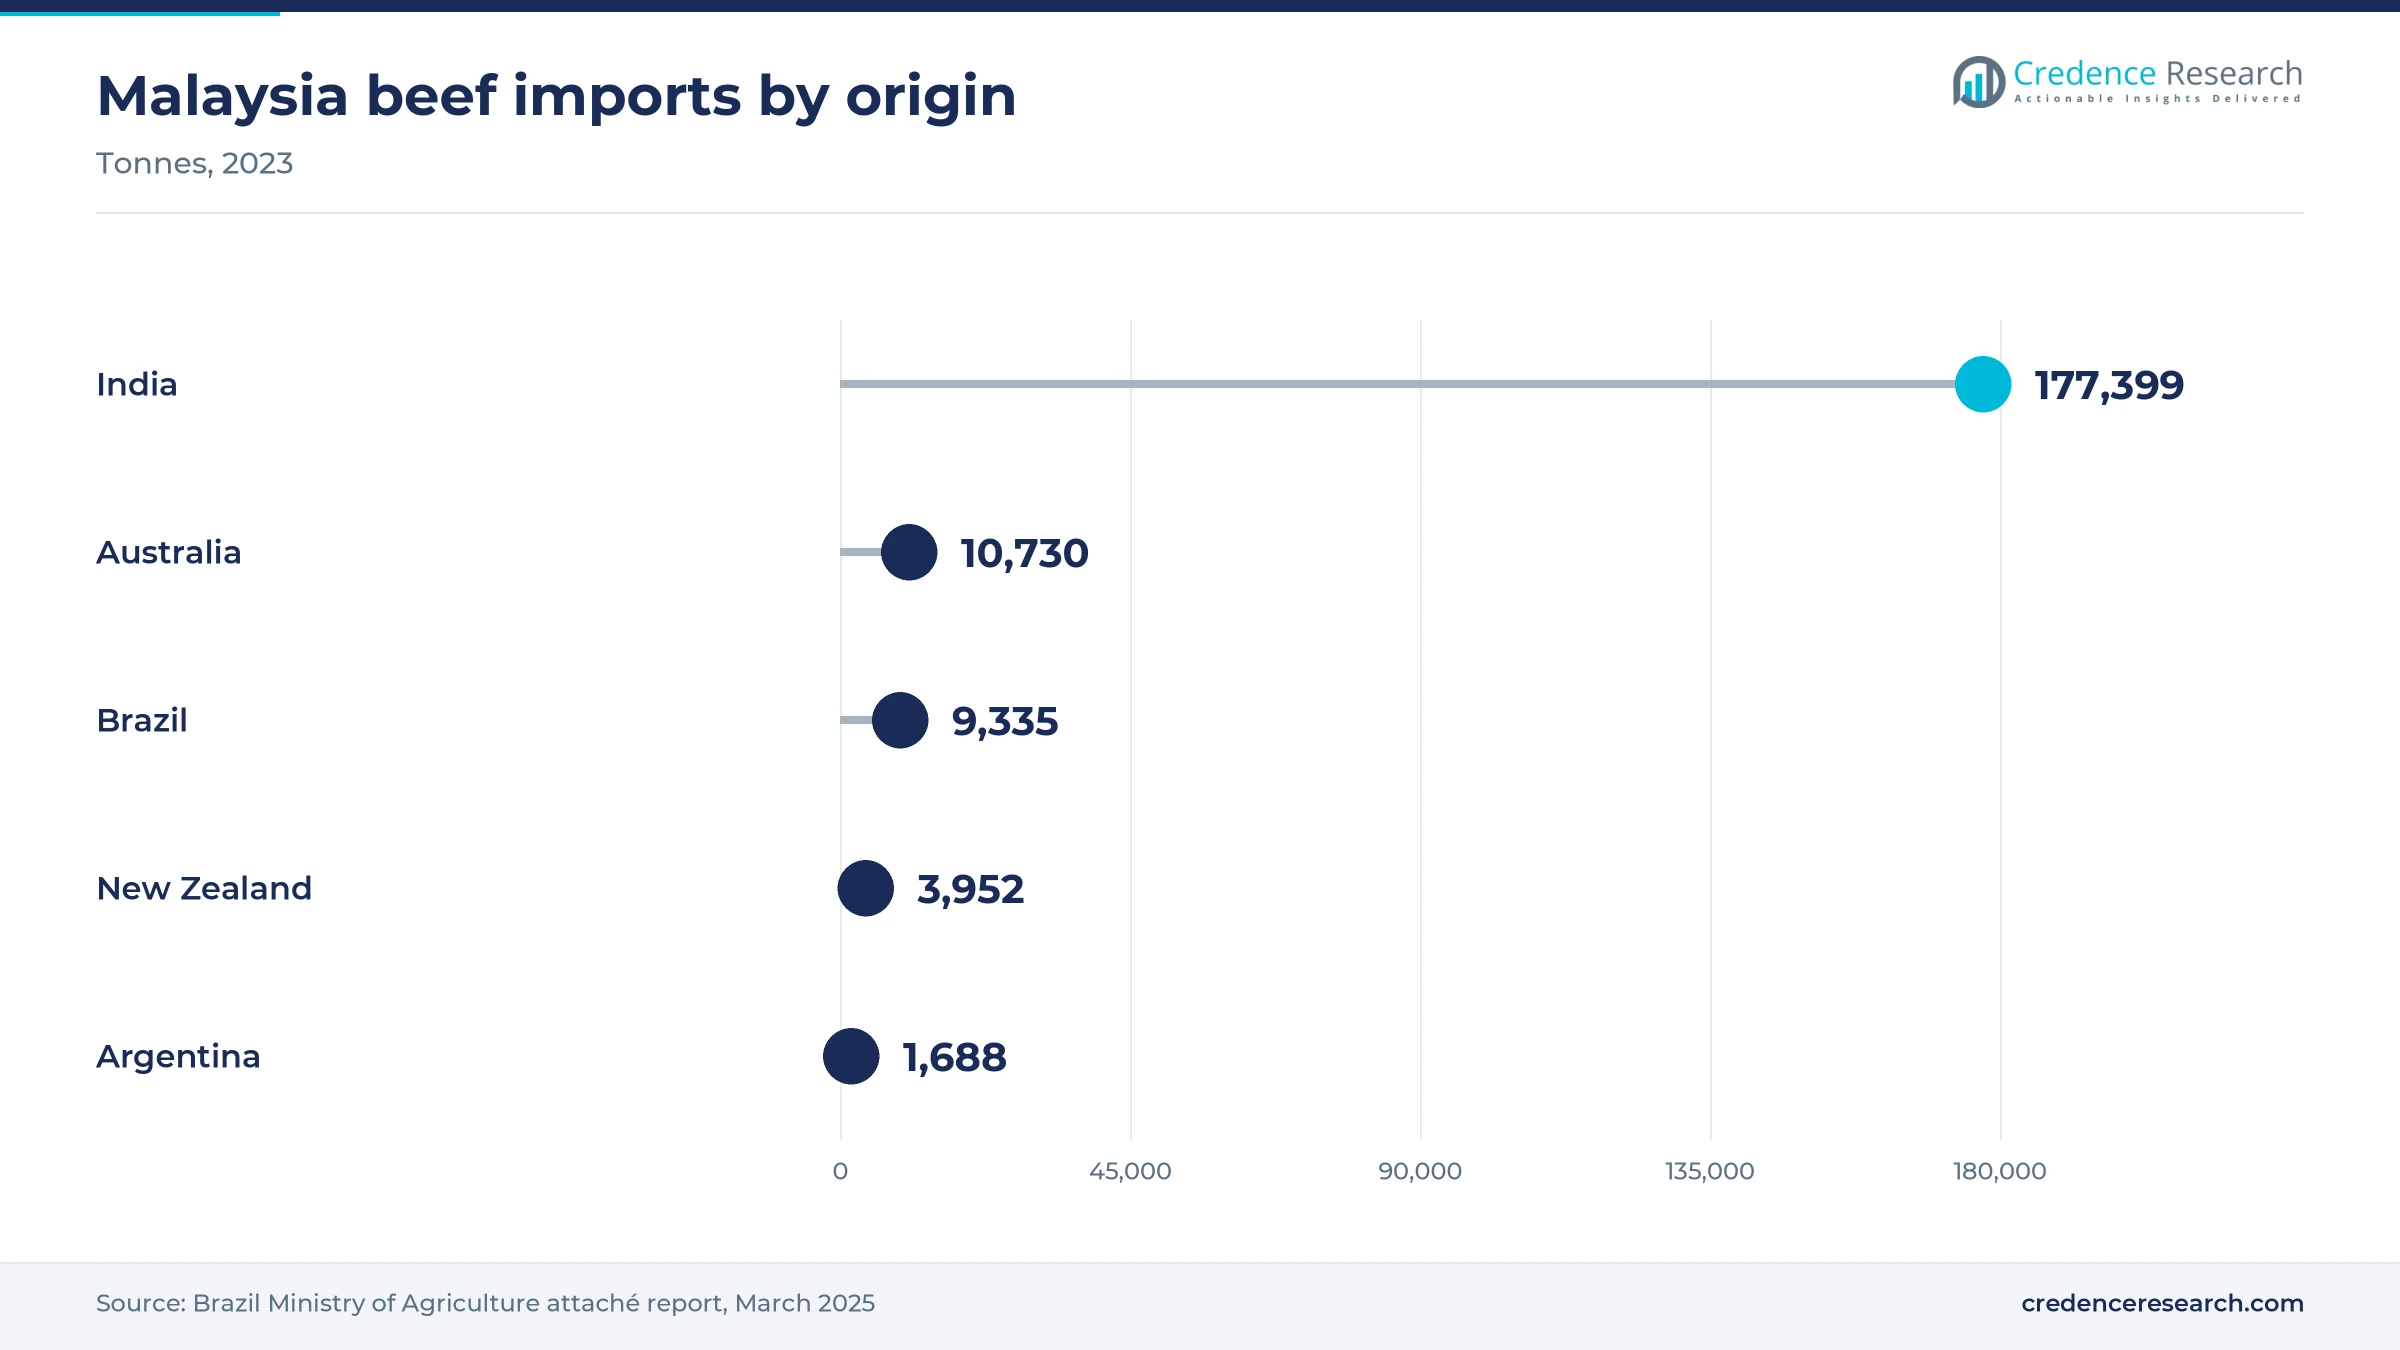
Beef demand runs far ahead of local herds, so imports set most of the volume and price in the market. Agriculture and Food Security Minister Mohamad Sabu said in June 2024 that the country needs 200,000 tons of beef a year, while a written ministry reply put beef self-sufficiency at 16.8% in 2024. Total beef imports passed 200,000 tons in the 12 months to August 2025, according to MLA data, with India holding 82%, Australia 8% and Brazil 8% of volume. The Brazilian agriculture ministry recorded imports of 204,214 tons in 2023, up from 145,200 tons in 2019. As a result, Beef holds 49.0% of 2025 value, and import costs shape retail prices across the country.
Halal rules and Aidiladha keep ruminant demand high
Halal rules and religious festivals keep demand for beef, buffalo and mutton high through the year. Malaysia requires all imported meat to be halal, and the Australian agriculture minister’s office says 27 halal-certified Australian establishments can now export beef, sheep and goat products to the country. Australia shipped 10,876 tons of beef and 39,310 tons of sheepmeat to Malaysia in 2025, worth A$156 million and A$328 million, and it holds about 86% of sheepmeat imports, according to MLA. Festival demand adds a sharp peak, since the agriculture ministry put Aidiladha needs at 40,420 cattle and buffalo in May 2026, and quarantine officers cleared more than 27,000 imported cattle, mostly from Thailand, that month, The Star reported. This pattern supports Lamb, which grows at 4.59% a year.
Pork buying by non-Muslim households sustains volume
Pork is the second pillar of demand, because non-Muslim households, 36.5% of the population, buy it at wet markets, butchers and restaurants. Mohamad Sabu told Parliament in June 2026 that demand should reach an estimated 213,927.92 tons in 2026, while national supply was about 221,958.69 tons in 2025. Local production fell from 136,506.3 tons in 2024 to an estimated 115,283.7 tons in 2025, as registered farms dropped from 435 to 338, according to CodeBlue. Imports therefore fill a larger share of the gap than before. Deputy Minister Chan Foong Hin said in March 2026 that pork self-sufficiency averaged 67.8% in 2024, against a 90% target for 2030. Consequently, pork keeps the second-largest share of value behind beef through 2035.
Public herd programs widen the domestic supply base
Public herd programs are widening the domestic supply base, which supports fresh local beef at wet markets and festival sales. Deputy Minister Chan Foong Hin told the Dewan Rakyat on Feb. 9, 2026, that the government had allocated RM450 million to the Pengganda 30 program, which uses a 90:10 matching grant to multiply cattle and goats by 2030. Ministry secretary-general Isham Ishak said in December 2025 that the national herd of about 886,000 cattle must pass three million by 2040. The ministry also runs 15 satellite farm sites with 67 cattle sheds and feedlot projects at eight locations. As a result, fresh local beef gains supply in markets where frozen imports now dominate.
New beef suppliers and closed pig farms reshape supply
Shift in beef sourcing toward Brazil, Australia and new suppliers
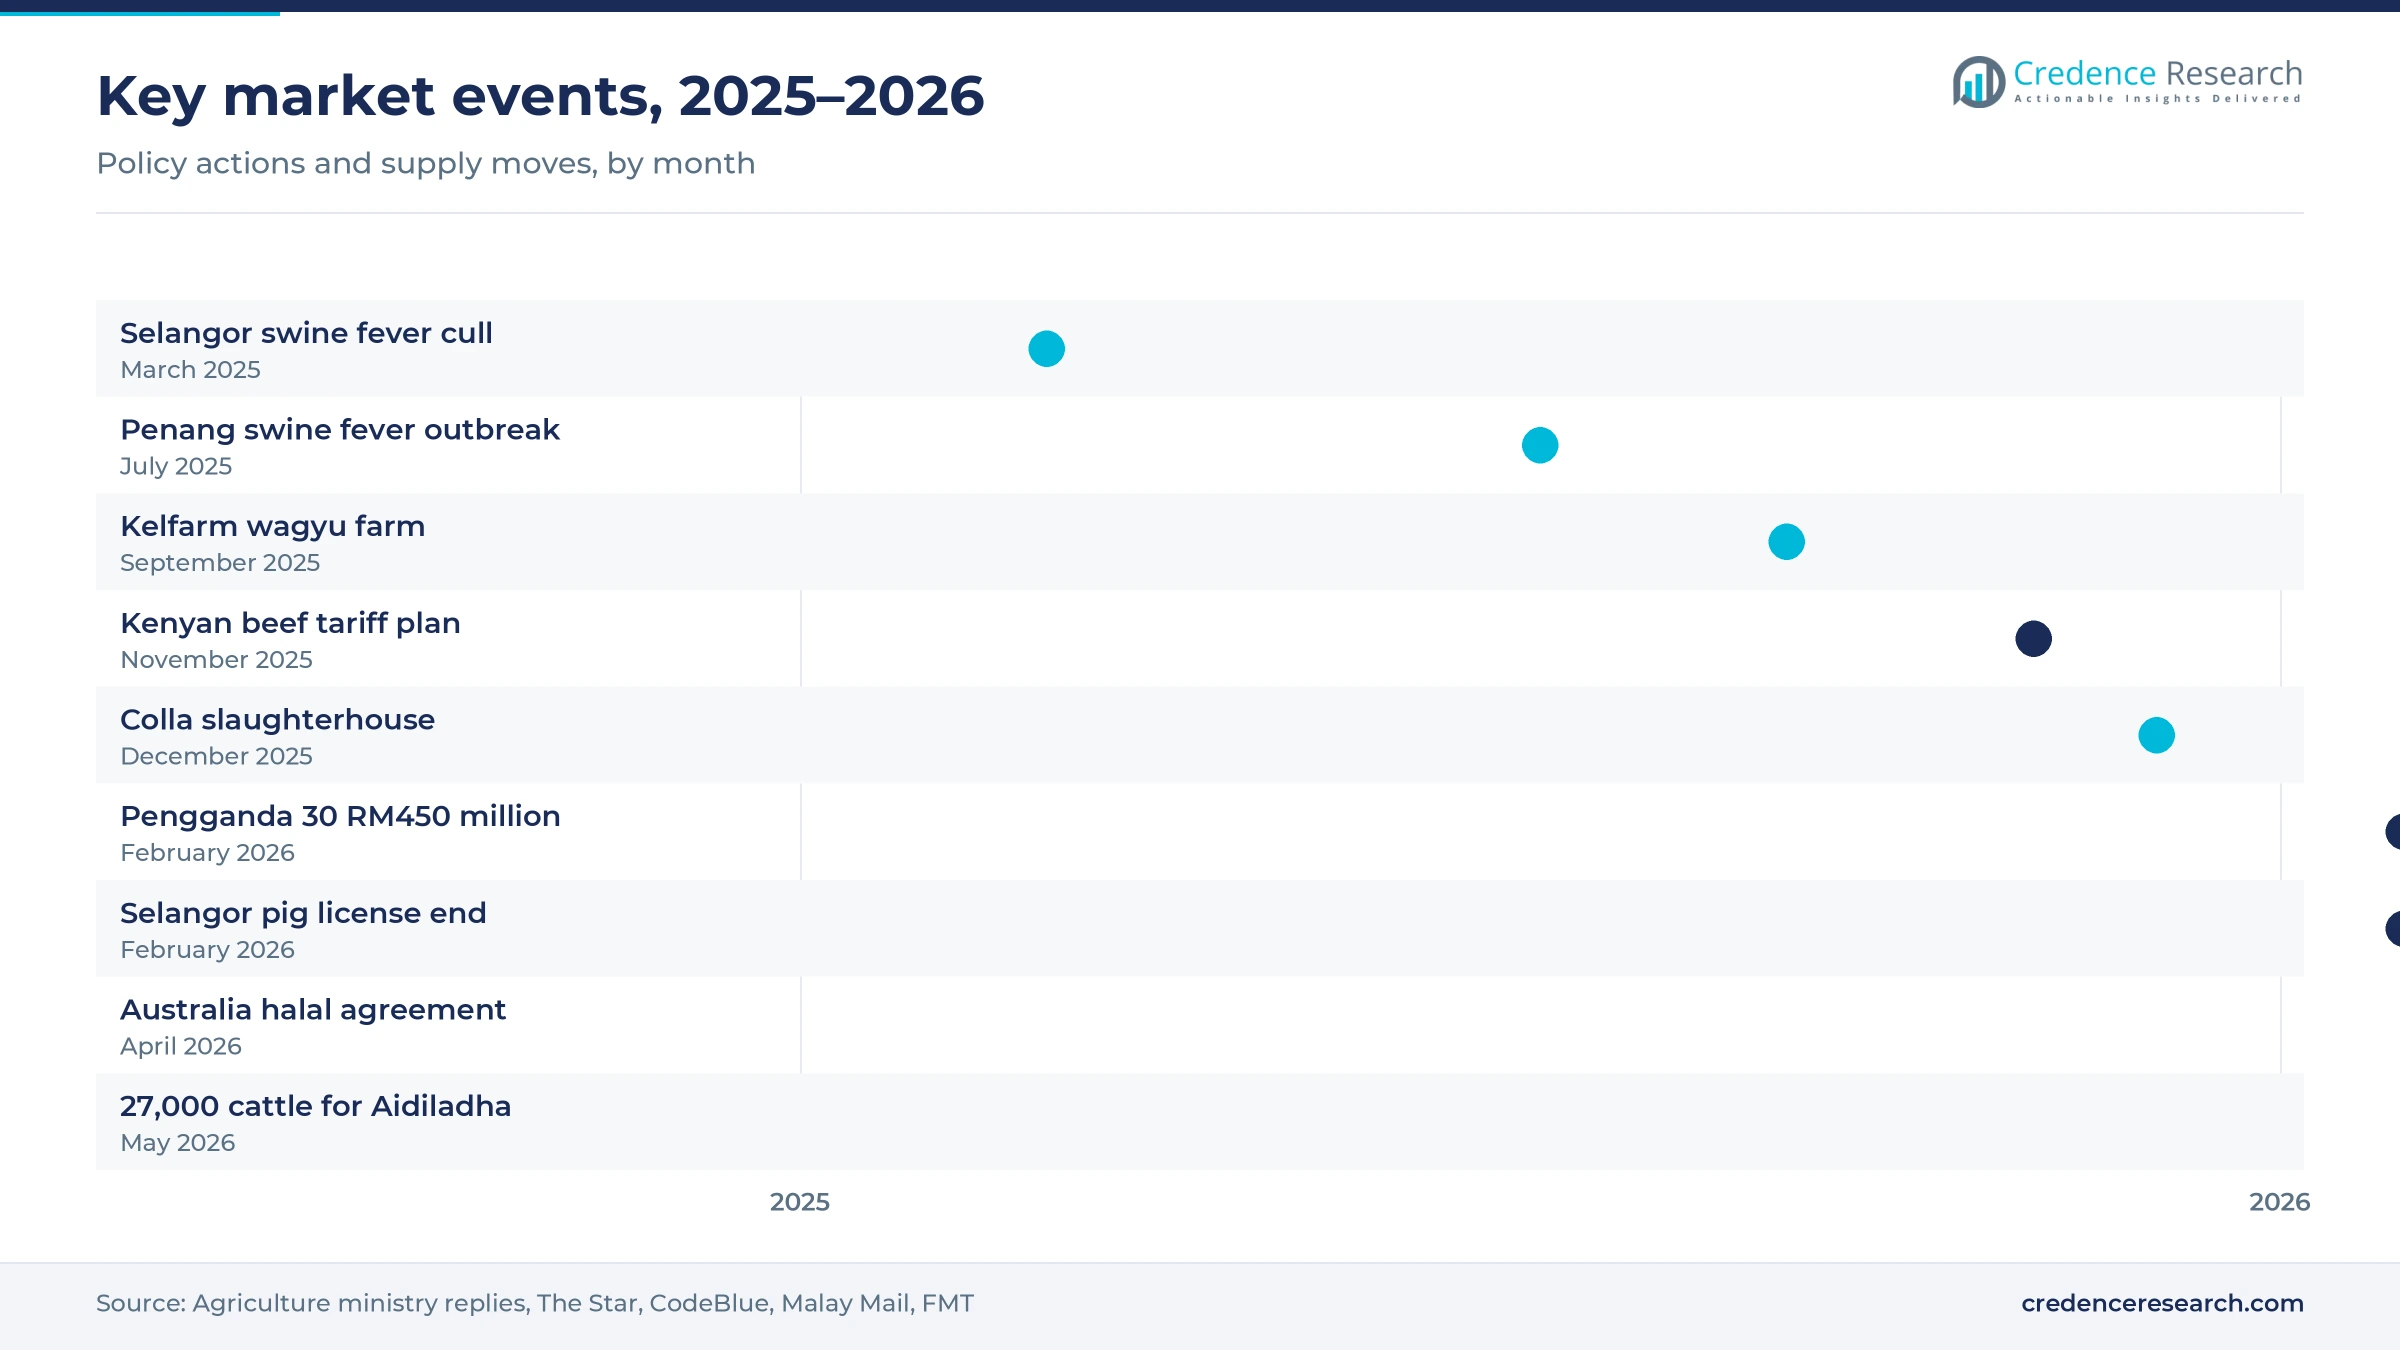
Importers are shifting part of their beef sourcing beyond India, which widens price and quality choices for buyers. Brazilian volumes rose 51% to 15,567 tons in the 12 months to August 2025 while its unit price fell 10%, and Australian volumes rose 16% to 16,522 tons, according to MLA. Uruguay delivered its first halal-certified beef shipment after export approval in July 2025, The Star reported in November 2025. Prime Minister Anwar Ibrahim also backed tariff removal on Kenyan beef in Nairobi on Nov. 25, 2025, calling beef unreasonably expensive. Fillet prices still differ widely, at about RM120 a kilogram for Australian beef, RM80 for Argentine and RM60 for Brazilian, according to a March 2025 Brazilian attaché report.
Rise of closed-house farming as Selangor ends pig rearing
Pig farming is moving toward closed-house systems in fewer states. Selangor stopped issuing pig farming licenses in January 2026, and on Feb. 12, 2026, Menteri Besar Amirudin Shari said the state would meet demand through imports, according to CodeBlue. About 70% of the pork eaten by Selangor’s non-Muslim residents already came from other states. Farmers converting open farms to closed systems can claim Accelerated Capital Allowance and income tax exemptions from 2023 to 2027, Chan Foong Hin said in March 2026. Sarawak has also set up one pig farming area, with three more planned. Nationwide, registered pig farms fell from 435 in 2024 to 338 in 2025. As a result, pork supply is concentrating in fewer and larger units, and East Malaysia gains from new capacity.
Opportunity in premium chilled beef and local wagyu
Premium chilled beef offers an opening for suppliers that can serve hotels, restaurants and corporate buyers. MLA reports that imports of premium chilled beef kept growing in the 12 months to August 2025, with Australia leading, and that Australian beef is typically used in higher-end hotels and restaurants. Local wagyu is also emerging, as wagyu cattle farming reached 481 head in June 2025, up from about 393 in 2024, Mohamad Sabu said when he launched the Kelfarm farm in Kota Baru on Sept. 7, 2025. Wagyu cattle sold for Qurban reached up to RM40,000 an animal in Kelantan in 2026, mostly to corporate groups. These buyers overlap with the premium beef trade across the region, so margins exceed those of commodity cuts.
Opportunity in plantation cattle and halal slaughter capacity
Oil palm estates offer a large, low-cost grazing base for cattle, and the government is asking plantation companies to use it. In a written reply dated Feb. 12, 2026, Mohamad Sabu said breeding cattle projects already cover 2,881 hectares of plantations through farmers’ organizations, and the Department of Veterinary Services has issued an operating guide for integrated beef cattle farming. Sabah plans RM24.3 million of farm upgrades to raise ruminant self-sufficiency from 7.05% to 25% by 2030, according to Malay Mail. Mohamad Sabu also launched the Colla Cattle Farm slaughterhouse on Dec. 11, 2025. Investors that combine estates, feedlots and certified processing lines can serve buyers in both Sabah and the Peninsula.
Swine fever, feed costs and smuggling squeeze producers
African swine fever has cut pig herds and lifted prices
African swine fever is now endemic, and it has removed large parts of the pig herd in key states. The Selangor outbreak of March 2025 led to the culling of 76,000 pigs at 57 farms around Kuala Langat and Sepang, Mohamad Sabu said in a written reply. In Penang, farm numbers fell from about 160 to 120, and a whole pig cost about RM18 a kilogram in May 2025, up from RM13 to RM14 a year earlier. Butchers and pork restaurants therefore face higher costs while farmers rebuild herds slowly.
Imported feed corn keeps livestock costs high
Feed is the largest cost in pig and cattle rearing, and Malaysia has imported all of its grain corn. Penang Pig Farmers Association chairman Wong Fu Sheng said maize rose from RM800 a ton before Covid-19 to as much as RM2,000 at its peak. The ministry now targets about 1.25 million tons of local grain corn a year for feed, Isham Ishak said in December 2025. Until that supply arrives, feedlots and pig farms carry currency and freight risks that imports of finished meat avoid.
Smuggling and border disease risks undercut cattle farmers
Cross-border livestock movements bring disease and price risks that local cattle farmers cannot control. Mohamad Sabu said in September 2025 that 70,000 head of cattle were smuggled into the country during the previous year, undercutting farmers who sell at RM25 to RM35 a kilogram. Legal imports from Thailand must pass a 14-day quarantine for foot and mouth disease and lumpy skin disease, yet the quarantine department recorded non-compliance cases in each of the past two years. Stronger border checks therefore raise holding and testing costs for legal importers.
Price-sensitive shoppers limit how far costs can pass through
Shoppers remain highly sensitive to beef prices, which limits how far retailers can pass on import and feed costs. Economy Minister Akmal Nasrullah Mohd Nasir said average beef prices were RM35.92 a kilogram in April 2026, down 3.8%. Earlier, about 300 kilograms of local beef at RM28 a kilogram sold out within an hour at a Madani Agro Sales event in Dungun in February 2024, while market prices were RM36 to RM38. Sellers of premium cuts therefore depend on a small, higher-income customer base.
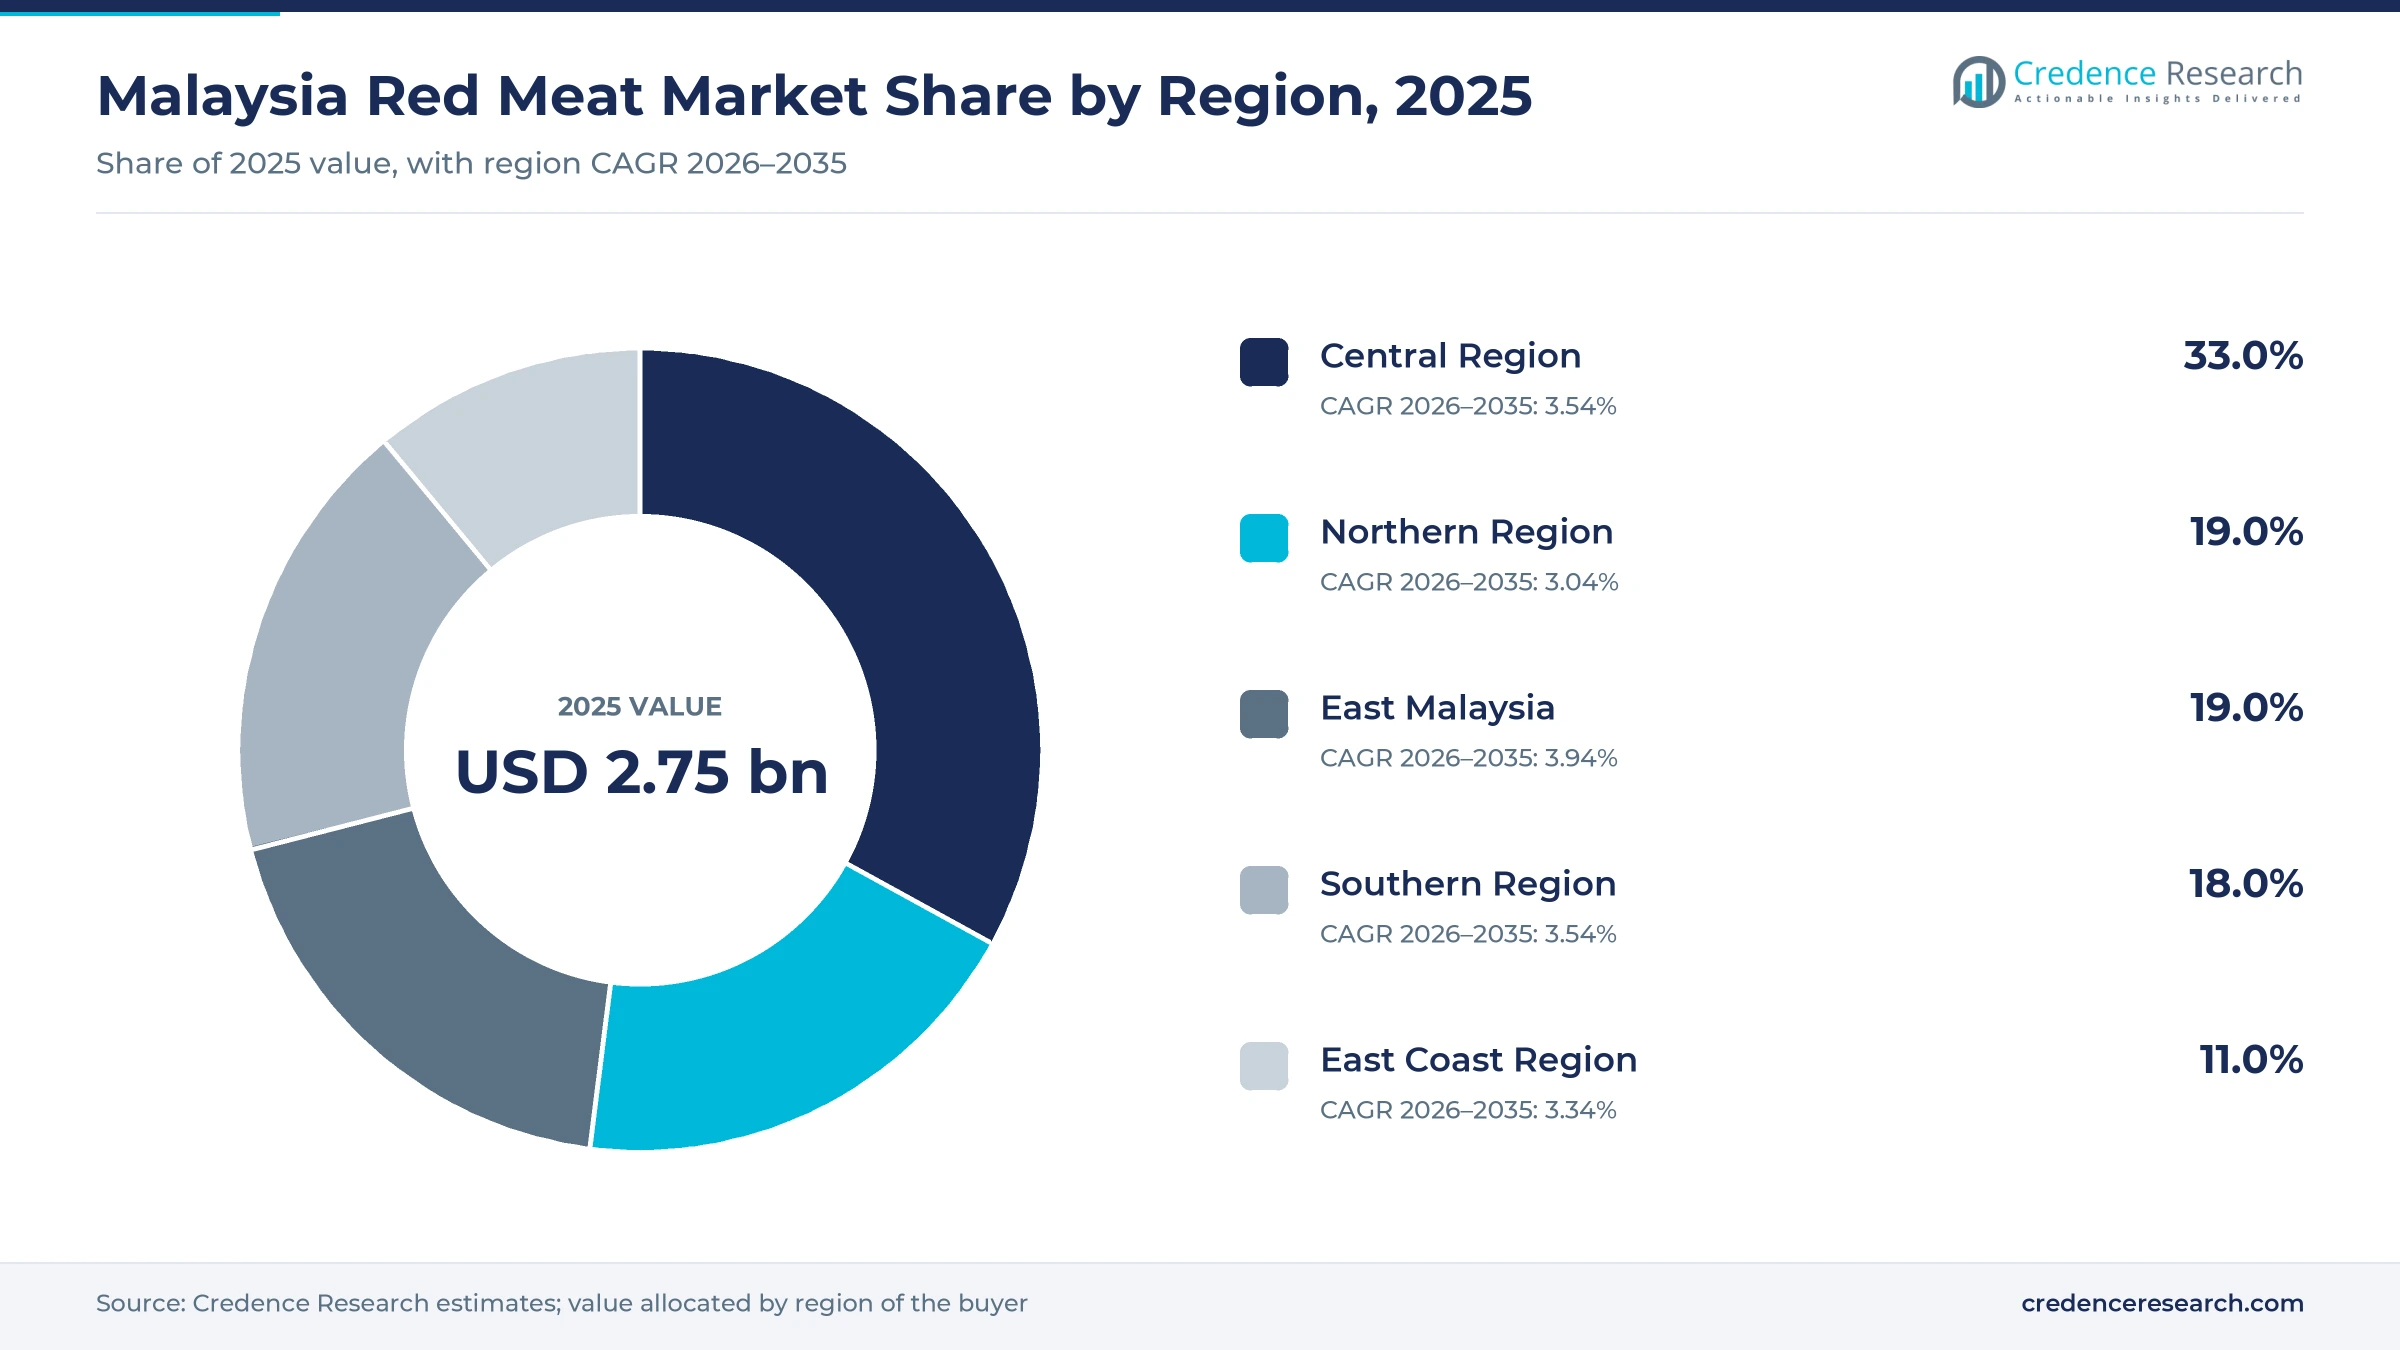
Central Region leads while East Malaysia grows fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Central Region | 0.91 | 33.0% | 3.54% |
| Northern Region | 0.52 | 19.0% | 3.04% |
| East Malaysia | 0.52 | 19.0% | 3.94% |
| Southern Region | 0.50 | 18.0% | 3.54% |
| East Coast Region | 0.30 | 11.0% | 3.34% |
Central Region holds the largest consumer base
The Central Region, covering Selangor, Kuala Lumpur and Putrajaya, held 33.0% of 2025 value and grows at 3.54% a year. Petaling and Ulu Langat, the two most populous Selangor districts, had 2.4 million and 1.5 million residents in 2025, according to the Department of Statistics Malaysia. Supermarkets in this zone carry most imported chilled beef, and AEON opened its first AEON STYLE store in Semenyih in December 2025. Selangor’s decision to end pig farming means its pork will now come from other states and imports.
Northern Region is the gateway for live cattle
The Northern Region, covering Penang, Kedah, Perak and Perlis, held 19.0% of 2025 value and grows at 3.04% a year. It is the main gateway for live cattle, since Thai animals enter through Padang Besar and Bukit Kayu Hitam for a 14-day quarantine before Aidiladha. Penang is also a major pork producer, although African swine fever cut the Bukit Tambun area herd from about 90,000 pigs to between 20,000 and 30,000. Credence Research expects pork volumes here to recover only gradually.
Southern Region draws on Johor’s large population
The Southern Region, covering Johor, Melaka and Negeri Sembilan, held 18.0% of 2025 value and grows at 3.54% a year. Johor Bahru district alone had about 1.8 million residents in 2025, according to the Department of Statistics Malaysia, which makes it the largest consumer base outside the Klang Valley. Melaka pig farms were also hit by swine fever culls, according to the agriculture ministry. Halal food manufacturing is expanding as well, with OTS Holdings opening a RM50 million plant at Simpang Renggam in October 2025.
East Coast Region builds local wagyu herds
The East Coast Region, covering Kelantan, Terengganu and Pahang, held 11.0% of 2025 value and grows at 3.34% a year. Rantau Panjang in Kelantan is one of three entry points for imported live cattle, which supply festival slaughter across the zone. Kelfarm opened a wagyu cattle farm in Kampung Seribong, Kota Baru, in September 2025, while AGK Dairy Fresh in Raub, Pahang, plans to market wagyu once its herd passes 1,000 head. These farms target Qurban buyers and premium restaurants rather than wet market shoppers.
East Malaysia grows fastest as Sabah expands farms
East Malaysia, covering Sabah, Sarawak and Labuan, held 19.0% of 2025 value and grows at 3.94% a year, the fastest of the five zones. Sabah produces only 7.05% of the ruminant meat it eats, so the state is spending RM24.3 million on 18 government farms to reach 25% by 2030. Sabah needed about 16,800 tons of beef a year, its assistant agriculture minister said in May 2023. Sabah and Sarawak also had 118 pig farms in 2023, according to the Department of Veterinary Services.
Herd funding and pig farm rules changed in 2025 and 2026
| Development | Status and market relevance |
|---|---|
| In April 2026, Malaysia’s Islamic development department and Australia’s agriculture department signed an agreement on red meat processing and trade. | Signed; supports halal cooperation with 27 approved Australian plants |
| In February 2026, the government allocated RM450 million to the Pengganda 30 program to multiply cattle and goat herds by 2030. | Under way; uses a 90:10 matching grant with Agrobank financing |
| In February 2026, the Selangor government ended pig farming licenses and said the state would meet pork demand through imports. | In force; existing farms close in stages |
| In December 2025, the agriculture minister launched the Colla Cattle Farm slaughterhouse. | Completed; adds local halal slaughter capacity for beef |
| In May 2026, the quarantine department cleared more than 27,000 imported cattle, mostly from Thailand, for Aidiladha. | Completed; against a ministry estimate of 40,420 cattle and buffalo needed |
Closed farms and halal certification shape supply chains
- Closed-house pig farming qualifies for Accelerated Capital Allowance and income tax exemptions until 2027, which helps farms contain disease and waste.
- Electronic halal certification is part of the cooperation planned under the Australia-Malaysia Strategic Halal Red Meat Partnership, which aims to ease import checks.
- Quarantine screening at government stations holds imported cattle for 14 days while officers monitor foot and mouth disease and lumpy skin disease.
- Integrated plantation grazing follows a Department of Veterinary Services operating guide and already covers 2,881 hectares of oil palm estates.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Indian buffalo meat and Australian cuts set competition
Competition splits into foreign packers, local importers and processors, retailers and a growing group of domestic cattle farms. Indian exporters dominate commodity beef, and Allana has supplied boneless buffalo meat to Malaysia since 1982 through about 15 local distributors, including Ramly Food Processing. Australian packers lead premium chilled beef and sheepmeat with 27 approved halal establishments, while Brazilian, Uruguayan and Argentine suppliers compete on price. In processing, Johnsonville unit PrimaBaguz makes sausages, cold cuts, meatballs and patties for restaurants, hotels and caterers. Retail competition sets wet market stalls against supermarket chains such as AEON, which are opening smaller formats with imported meat ranges. Local producers, including Kelfarm and AGK Dairy Fresh, are building wagyu herds for Qurban and premium buyers. Scale in cold storage, halal certification and access to approved foreign plants decides who can hold prices steady when supply shifts.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Ramly Food Processing | Processor | Halal burger and processed products maker supplied with Indian buffalo meat through Allana |
| Allanasons | Exporter | Indian buffalo meat supplier to Malaysia since 1982 through about 15 distributors |
| Johnsonville (PrimaBaguz) | Processor | Kuala Lumpur plant with 330 staff making more than 100 halal products |
| AEON Co. (M) Bhd. | Retailer | Opened AEON STYLE in Semenyih in December 2025 with imported meat ranges |
| Kelfarm Sdn Bhd | Cattle farm | Wagyu cattle farm in Kota Baru launched in September 2025 |
| AGK Dairy Fresh Sdn Bhd | Cattle farm | Breeding wagyu in Raub, Pahang, with marketing planned above 1,000 head |
| Colla Cattle Farm | Farm and abattoir | Slaughterhouse launched by the agriculture minister in December 2025 |
Importers with diverse halal suppliers hold the edge
Credence Research’s view is that the market’s value will keep rising even if local herds grow more slowly than official targets. Beef self-sufficiency remains far below the 50% goal for 2030, so imported frozen beef should stay the base of supply. Pork is the larger risk, because disease and the Selangor farming ban cut registered farms by 22% in one year. Buyers should therefore secure supply from several approved countries and plants. The strongest positions are likely to belong to importers with halal-approved foreign plants, cold storage in both Peninsular and East Malaysia, and processing lines for restaurant demand.
Official statistics and trade data underpin the estimates
The report uses 2025 as the base year, 2026 as the first forecast year and 2035 as the final year. Market values come from the Credence Research model, and the segment and regional splits are Credence Research estimates. Inputs include Department of Statistics Malaysia population data, agriculture ministry replies to Parliament, Meat & Livestock Australia trade data, a Brazilian agriculture ministry attaché report, company announcements and press reports naming the source organization. No interviews or surveys were conducted for this edition of the report.
Local herds grow but imports still anchor supply to 2035
Sales are forecast to rise from USD 2.85 billion in 2026 to USD 3.88 billion by 2035, a 3.50% CAGR. Beef should keep the largest share, although lamb should gain as Australian sheepmeat supply and restaurant demand expand. Fresh local beef will gain only if Pengganda 30 and plantation grazing raise herds toward the three million cattle the ministry says are needed by 2040. Pork supply will depend on how quickly closed-house farms and imports replace lost Selangor capacity. East Malaysia should grow fastest, while the Central Region remains the largest zone by value.
Frequently Asked Questions
What is the size of the Malaysia red meat market?
How much beef do Malaysians eat?
How much red meat does Australia export to Malaysia?
What is the beef price per kg in Malaysia?
How many cattle are there in Malaysia?
Where does Malaysia import beef from?
Which segment leads the Malaysia red meat market?
How has African swine fever affected pork supply in Malaysia?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Beef
- 1.2.2 Pork
- 1.2.3 Lamb
- 1.2.4 Others
- 1.3 By Application
- 1.3.1 Frozen
- 1.3.2 Fresh
- 1.3.3 Processed
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 2.75 billion → 2035: USD 3.88 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Malaysia Red Meat Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Malaysia Red Meat Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Malaysia Red Meat Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Malaysia Red Meat Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Malaysia Red Meat Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Malaysia Red Meat Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Malaysia Red Meat Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Malaysia Red Meat Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 2.75 billion → 2035: USD 3.88 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Malaysia Red Meat Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Beef
- 12.3.7.2 Pork
- 12.3.7.3 Lamb
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Frozen
- 12.4.7.2 Fresh
- 12.4.7.3 Processed
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Malaysia Red Meat End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Malaysia Red Meat Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Malaysia Red Meat Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Malaysia Red Meat Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Ramly Food Processing
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Allanasons
- 18.4 Johnsonville (PrimaBaguz)
- 18.5 AEON Co. (M) Bhd.
- 18.6 Kelfarm Sdn Bhd
- 18.7 AGK Dairy Fresh Sdn Bhd
- 18.8 Colla Cattle Farm
- 18.9 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

