
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Malaysia Industrial Solvents Market Size 2024 | USD 75.11 million |
| Malaysia Industrial Solvents Market, CGR | 7.25% |
| Malaysia Industrial Solvents Market Size 2032 | USD 131.48 million |
Market Overview
Malaysia Industrial Solvents market size was valued at USD 75.11 million in 2024 and is anticipated to reach USD 131.48 million by 2032, at a CAGR of 7.25% during the forecast period (2024-2032).
The Malaysia industrial solvents market is experiencing steady growth, driven by the country's expanding manufacturing and construction sectors. Increased demand from industries such as automotive, electronics, and paints and coatings is significantly boosting solvent consumption. The government's push for industrial development and infrastructure projects further supports this upward trend. Additionally, rising urbanization and foreign direct investments are contributing to a robust industrial base, thereby enhancing solvent usage. Environmental regulations are prompting a shift toward eco-friendly and bio-based solvents, encouraging innovation and product diversification. Technological advancements in solvent formulations aimed at improving performance and reducing VOC emissions are also gaining traction. Moreover, the growing emphasis on sustainable practices across industries is fostering the adoption of green solvents. These market drivers, coupled with a favorable economic outlook and increasing domestic demand, are expected to sustain the positive momentum in the Malaysian industrial solvents market over the forecast period.
The geographical distribution of Malaysia's industrial solvents market is closely aligned with the country’s major industrial and manufacturing zones. The Central and Southern regions, including Selangor, Kuala Lumpur, and Johor, act as primary demand centers due to their dense concentration of manufacturing hubs, industrial parks, and export-oriented industries. Northern states like Penang also contribute significantly, particularly through their advanced electronics and pharmaceutical sectors. Meanwhile, East Malaysia and the East Coast are witnessing gradual industrial expansion, creating new growth opportunities for solvent suppliers. Key players operating in the Malaysia industrial solvents market include prominent multinational and regional chemical manufacturers such as Malaysia National Petroleum Corporation (CNPC), Formosa Plastics Corporation, Reliance Industries Limited, Sinopec Group, and Mitsubishi Chemical Holdings Corporation. Other notable players include Sumitomo Chemical, Toray Industries, LG Chem, Tata Chemicals, and SK Innovation. These companies are actively investing in product innovation, sustainable solvent solutions, and regional supply chain enhancements to meet evolving industrial demands.
Market Insights
- The Malaysia industrial solvents market was valued at USD 75.11 million in 2024 and is projected to reach USD 131.48 million by 2032, growing at a CAGR of 7.25% during the forecast period.
- The global industrial solvents market was valued at USD 34,660.50 million in 2024 and is expected to reach USD 60,647.79 million by 2032, growing at a CAGR of 7.24% during the forecast period (2024-2032).
- Strong demand from key industries such as automotive, electronics, and paints & coatings is driving market growth.
- The shift toward eco-friendly and bio-based solvents is a major market trend, influenced by stricter environmental regulations and sustainability goals.
- Key players like CNPC, Formosa Plastics, and Reliance Industries are actively expanding their product portfolios and innovating to cater to evolving market needs.
- Fluctuating raw material prices and environmental compliance costs pose significant challenges to manufacturers.
- The Central and Southern regions of Malaysia dominate the solvent market due to their industrial concentration, with growing demand in the East Coast and East Malaysia.
- Technological advancements in solvent recovery and recycling are creating new opportunities in the market.
Report Scope
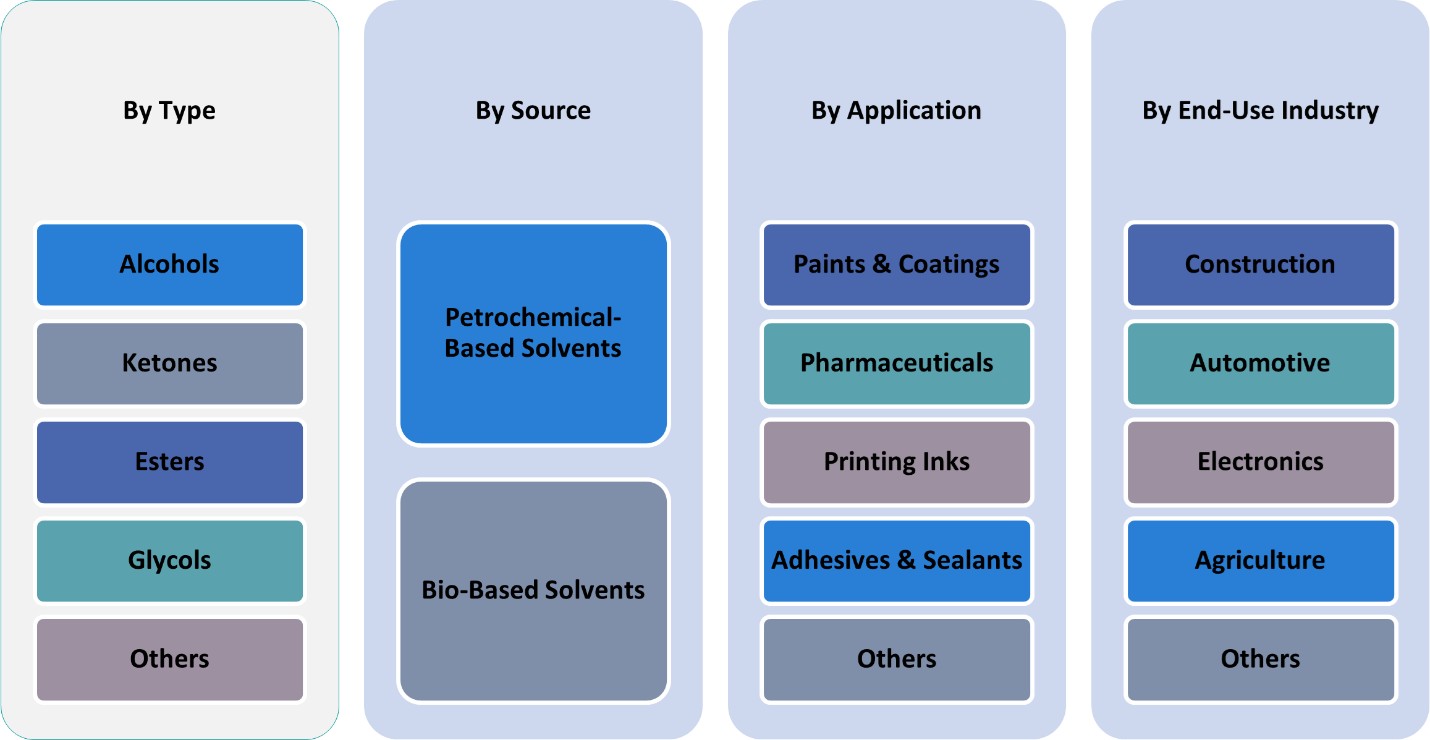
This report segments the Malaysia Industrial Solvents market as follows:
Market Drivers
Robust Growth in Manufacturing and Industrial Activities
Malaysia’s industrial solvents market is being significantly driven by the steady expansion of the country’s manufacturing and industrial base. For instance, Malaysia’s Department of Statistics reported that the manufacturing sector contributed over 23% to the country’s GDP in 2024, with strong growth in electronics, automotive, rubber, and plastics industries. Industrial solvents play a crucial role in these industries, serving as essential agents in cleaning, degreasing, thinning, and chemical synthesis. The government's pro-manufacturing policies, including tax incentives, export facilitation, and industrial infrastructure development, have attracted both domestic and foreign investments. These factors collectively contribute to a rising demand for industrial solvents across diverse end-use sectors.
Boom in Construction and Infrastructure Projects
The rise in construction and infrastructure development is another major driver propelling the growth of industrial solvents in Malaysia. Solvents are vital components in paints, coatings, adhesives, sealants, and other construction-related chemicals. For instance, Malaysia’s Twelfth Malaysia Plan (2021–2025) has allocated significant funding for infrastructure modernization, including transport networks and urban development projects. Ongoing public and private infrastructure projects ranging from transport networks to residential and commercial developments are increasing the need for solvent-based materials. This trend ensures a sustained demand for industrial solvents in construction and allied industries throughout the forecast period.
Growing Demand for Eco-Friendly and Specialty Solvents
Environmental concerns and stricter regulatory standards are prompting a market shift towards eco-friendly and low-VOC (volatile organic compound) solvents. Industries are increasingly adopting green solvents derived from renewable sources to comply with environmental regulations and sustainability goals. This transition is opening new opportunities for innovation and product diversification in the industrial solvents space. Additionally, the growing popularity of high-performance specialty solvents for niche applications in pharmaceuticals, electronics, and personal care products is creating demand for customized solvent solutions. Manufacturers are responding by investing in R&D to develop environmentally responsible alternatives without compromising on performance, thereby enhancing market growth.
Favorable Trade Policies and Economic Outlook
Malaysia's strategic location, strong trade links, and favorable economic policies further strengthen the industrial solvents market. As a key player in ASEAN trade, Malaysia benefits from numerous free trade agreements and export-driven growth, which help bolster its industrial output. The country’s stable economic outlook, backed by recovery in global demand and resilient domestic consumption, provides a conducive environment for industrial growth. Moreover, ongoing investments in infrastructure, logistics, and industrial zones are improving ease of doing business and encouraging solvent manufacturers to scale operations. These supportive macroeconomic factors are expected to amplify solvent demand across various industrial domains over the next decade.
Market Trends
Shift Toward Eco-Friendly and Bio-Based Solvents
Environmental regulations and increased awareness of sustainability are driving a significant shift in Malaysia's industrial solvents market toward eco-friendly and bio-based alternatives. Industries are moving away from traditional solvents with high levels of volatile organic compounds (VOCs) due to their environmental impact. The demand for solvents derived from renewable resources, such as bio-based solvents, is on the rise. These eco-friendly alternatives are less harmful to the environment and safer for workers, aligning with the global trend towards greener industrial practices. This shift is particularly noticeable in industries such as paints and coatings, where the need for sustainable solutions is critical.
Technological Advancements in Solvent Purification and Applications
Technological innovations are enhancing the quality and application scope of industrial solvents in Malaysia. Advances in purification methods, such as distillation, filtration, and extraction, are enhancing the production of ultra-pure solvents. For instance, Malaysia’s solvent market has seen increased investment in research and development, focusing on specialized solvent formulations for high-performance applications. In Malaysia, demand for high purity solvents is increasing as manufacturers adopt advanced purification technologies that meet stringent purity requirements. These high-purity solvents are essential in sectors like pharmaceuticals, electronics, and specialty chemicals, where stringent quality standards are paramount.
Expansion of High-Purity and Specialty Solvent Segments
The demand for high-purity and specialty solvents is expanding in Malaysia, driven by the pharmaceutical, electronics, and biopharmaceutical sectors. For instance, Malaysia’s High Purity Solvents Market report highlights the growing demand for ultra-pure solvents in pharmaceutical and biotechnology applications. The biopharmaceutical sector requires ultra-pure solvents for complex drug formulations, biologics, and cell culture media. In Malaysia, demand for high purity solvents in biopharmaceuticals is rising as companies develop innovative treatments and therapies that require stringent purity standards. Similarly, the electronics industry utilizes these solvents for precision cleaning and manufacturing processes.
Integration of Solvent Recycling and Circular Economy Practices
Malaysia's commitment to sustainability is fostering the integration of solvent recycling and circular economy practices within the industrial solvents market. The government introduced the Sustainable and Circular Economy Roadmap to transition the country towards a circular economy. This approach promotes the efficient use of resources, waste minimization, and the regeneration of natural systems. As a result, industries are increasingly adopting solvent recovery and recycling systems to reduce waste and environmental impact.
Market Challenges Analysis
Stringent Environmental Regulations and Compliance Costs
One of the foremost challenges confronting the industrial solvents market in Malaysia is the tightening of environmental regulations concerning the use and disposal of chemical solvents. Government agencies such as the Department of Environment (DOE) enforce strict standards on emissions, waste handling, and solvent toxicity to minimize environmental harm. For instance, Malaysia’s solvents market has seen increased regulatory scrutiny, with manufacturers required to develop low-VOC and environmentally friendly solvents to align with sustainability objectives. As a result, solvent manufacturers and end-users must invest significantly in pollution control equipment, regulatory compliance systems, and cleaner production technologies. These compliance costs can be particularly burdensome for small and medium-sized enterprises (SMEs), limiting their ability to compete or expand. Furthermore, the increased scrutiny on solvents with high volatile organic compound (VOC) content has prompted businesses to reformulate or phase out widely used products, often requiring substantial R&D investments and reformulation cycles.
Fluctuating Raw Material Prices and Supply Chain Disruptions
Volatility in the prices of petrochemical-based raw materials poses a significant risk to the profitability and planning of solvent manufacturers in Malaysia. Industrial solvents are largely derived from crude oil derivatives, making them highly susceptible to fluctuations in global oil prices. Any disruptions whether geopolitical conflicts, supply shortages, or OPEC production decisions can directly impact the cost structure of solvent production. Additionally, Malaysia’s reliance on imported raw materials for certain solvent types makes the sector vulnerable to global supply chain disruptions. The COVID-19 pandemic and ongoing geopolitical tensions have already exposed weaknesses in global logistics networks, leading to delivery delays and cost inflation. These challenges complicate procurement planning, inventory management, and pricing strategies for stakeholders across the value chain.
Market Opportunities
The Malaysia industrial solvents market presents strong growth opportunities driven by the country’s ongoing industrial diversification and expansion into high-value manufacturing segments. As Malaysia continues to position itself as a competitive hub in sectors such as electronics, automotive, pharmaceuticals, and specialty chemicals, the demand for a wide range of industrial solvents is expected to rise. These sectors require solvents not only for cleaning and processing but also as critical components in formulations and production workflows. With the increasing shift toward precision manufacturing and cleanroom environments, especially in electronics and medical devices, there is a growing market for high-purity and specialty solvents. This trend opens the door for manufacturers to introduce differentiated solvent solutions that meet the stringent standards of these industries. Moreover, the government’s support for industrial innovation and its emphasis on technology-driven manufacturing under the National Industry 4.0 Policy further create a conducive environment for the adoption of advanced solvent technologies.
In parallel, Malaysia’s commitment to sustainability and green industry practices creates promising avenues for the development and adoption of eco-friendly and bio-based solvents. With increasing pressure on industries to reduce carbon footprints and adhere to environmental regulations, demand is shifting toward low-VOC and biodegradable solvent alternatives. This transition provides an opportunity for both domestic and international players to invest in R&D and introduce innovative, sustainable solvent products tailored to regional needs. Additionally, the establishment of circular economy frameworks and incentives for green manufacturing offer long-term potential for solvent recycling and recovery solutions. Companies that align their product portfolios with these sustainability goals stand to gain early mover advantages and long-term market relevance. Overall, Malaysia's blend of economic growth, regulatory evolution, and industrial modernization positions its industrial solvents market as an attractive space for innovation, investment, and expansion.
Market Segmentation Analysis:
By Type:
The Malaysia industrial solvents market is segmented by type into alcohols, ketones, esters, glycols, and others. Among these, alcohols hold a significant share due to their widespread use as cleaning and dissolving agents in multiple industrial processes, particularly in paints, pharmaceuticals, and personal care products. Ketones, such as acetone and methyl ethyl ketone, are also widely used for their strong solvency properties in coatings, adhesives, and plastics. Esters find applications in formulations where a balance of solubility and evaporation rate is essential, such as in printing inks and coatings. Glycols, including ethylene and propylene glycols, are gaining traction due to their utility in antifreeze formulations and as solvents in the pharmaceutical and cosmetic sectors. The “others” category includes hydrocarbons and chlorinated solvents, which, despite declining demand due to environmental concerns, still serve niche applications in metal cleaning and degreasing. This type-based segmentation reflects both functional diversity and the evolving preference for safer, more environmentally compliant solvents.
By Application:
By application, the industrial solvents market in Malaysia is categorized into paints & coatings, pharmaceuticals, printing inks, adhesives & sealants, and others. The paints and coatings segment dominates due to Malaysia’s growing construction and infrastructure sectors, which rely heavily on solvent-based coatings for durability and finish. The pharmaceutical industry is a key emerging consumer of high-purity solvents, driven by stringent regulatory requirements and the rise of biopharmaceutical manufacturing. Printing inks also constitute a notable segment, supported by Malaysia’s expanding packaging and labeling industry. The adhesives and sealants segment is growing steadily, particularly in construction and automotive manufacturing, where solvent-based formulations offer enhanced bonding and flexibility. The “others” category includes personal care, cleaning agents, and agrochemicals, which also contribute steadily to overall demand. Across all applications, there is a notable shift toward low-VOC and green solvents, influenced by tightening regulations and rising environmental awareness. This application-based segmentation highlights the diversity of end-use sectors and the scope for product specialization.
Segments:
Based on Type:
- Alcohols
- Ketones
- Esters
- Glycols
- Others
Based on Application:
- Paints & Coatings
- Pharmaceuticals
- Printing Inks
- Adhesives & Sealants
- Others
Based on End- Use:
- Construction
- Automotive
- Electronics
- Agriculture
- Others
Based on Source:
- Petrochemical-Based Solvents
- Bio-Based Solvents
Based on the Geography:
- Northern Peninsula
- Southern Peninsula
- Central
- East Coast
- East Malaysia
Regional Analysis
Central Region The Central region of Malaysia, including Selangor and Kuala Lumpur, commands the largest share of the industrial solvents market at approximately 38%. This dominance is primarily driven by the region's status as Malaysia’s industrial and commercial hub. With a high concentration of manufacturing facilities, especially in sectors such as electronics, automotive, pharmaceuticals, and consumer goods, the Central region maintains strong and consistent demand for a wide range of industrial solvents. The proximity to key infrastructure-including ports, highways, and logistics centers further supports seamless supply chain operations. Additionally, the presence of several industrial parks and special economic zones has attracted both domestic and international chemical manufacturers, making this region the core driver of Malaysia’s solvent consumption and innovation.
Southern Peninsula The Southern Peninsula region, covering Johor and nearby states, accounts for around 25% of the total market share for industrial solvents. Its strategic location near Singapore, combined with strong cross-border trade and investment, has turned Johor into a growing industrial base. The region has experienced rapid development in petrochemicals, manufacturing, and construction sectors, all of which are major consumers of industrial solvents. The Iskandar Malaysia development corridor further stimulates industrial growth, attracting solvent-intensive sectors such as paints and coatings, adhesives, and specialty chemicals. The availability of industrial land, tax incentives, and growing infrastructure make the Southern Peninsula a key area of solvent demand and potential expansion for manufacturers.
Northern Peninsula The Northern Peninsula, which includes Penang, Kedah, and Perak, contributes approximately 20% to Malaysia’s industrial solvents market. This region is renowned for its strong presence in the electrical and electronics (E&E) sector, particularly in Penang, which is often referred to as the "Silicon Valley of the East." Industrial solvents are extensively used in semiconductor manufacturing, precision cleaning, and printed circuit board (PCB) production. Additionally, the pharmaceutical and packaging sectors in this region are gaining momentum, further supporting solvent demand. Ongoing investments in high-tech manufacturing and export-oriented industries reinforce the Northern region’s role in the solvent value chain.
East Malaysia and East Coast Combined, East Malaysia (Sabah and Sarawak) and the East Coast (Kelantan, Terengganu, and Pahang) represent about 17% of the national industrial solvents market. Though traditionally less industrialized than the Peninsula regions, these areas are experiencing gradual growth in petrochemical, palm oil processing, and agro-based industries, all of which use solvents in extraction, processing, and maintenance operations. Government efforts to spur development in these regions through infrastructure upgrades, rural industrial programs, and special economic zones are creating new opportunities for solvent suppliers. As these regions continue to industrialize, they are expected to contribute more actively to national solvent demand in the coming years.
Key Player Analysis
- Malaysia National Petroleum Corporation (CNPC)
- Formosa Plastics Corporation
- Reliance Industries Limited
- Sinopec Group
- Mitsubishi Chemical Holdings Corporation
- Sumitomo Chemical Co., Ltd.
- Toray Industries, Inc.
- LG Chem Ltd.
- Tata Chemicals Ltd.
- SK Innovation Co., Ltd.
Competitive Analysis
The competitive landscape of Malaysia's industrial solvents market is characterized by the presence of both global and regional players who are continuously innovating and expanding to meet growing demand across various sectors. Leading companies such as Malaysia National Petroleum Corporation (CNPC), Formosa Plastics Corporation, Reliance Industries Limited, Sinopec Group, Mitsubishi Chemical Holdings Corporation, Sumitomo Chemical Co., Ltd., Toray Industries, Inc., LG Chem Ltd., Tata Chemicals Ltd., and SK Innovation Co., Ltd. dominate the market with diverse product portfolios and strong regional presence.
These key players focus on technological innovation, offering high-performance, sustainable, and eco-friendly solvents to cater to industries like paints & coatings, pharmaceuticals, and electronics. They are also heavily investing in R&D to develop green solvents and improve solvent recovery and recycling processes, responding to increasing environmental concerns and regulations. Strategic partnerships, joint ventures, and expansions in emerging markets such as East Malaysia and the East Coast are vital strategies for these companies to maintain competitiveness. Additionally, market leaders are enhancing their regional supply chains to ensure efficiency and reduce costs, all while meeting the growing demand for industrial solvents in the manufacturing, automotive, and construction sectors. The ongoing emphasis on product differentiation and sustainability will continue to shape competition in the Malaysian industrial solvents market.
Recent Developments
- In April 2025, Eastman announced off-list price increases for several EOD (Ethylene Oxide Derivatives) solvents, including Eastman™ DB Solvent, effective April 7, 2025, reflecting ongoing cost and market pressures.
- In March 2025, BASF reported generating approximately €11 billion in 2024 sales from products launched in the past five years, driven by R&D focused on sustainability, biodegradable materials, and digital transformation. The company filed 1,159 new patents in 2024, with 45% targeting sustainability. R&D investment in 2024 was €2.1 billion, with a similar budget planned for 2025.
- In March and April 2025, Shell is restructuring its global chemicals business to boost profitability and reduce capital spending by 2030. This includes exploring strategic partnerships in the U.S., potentially closing some European assets, and selling existing assets like the Singapore refinery and chemical complex. The company aims to streamline operations, focus on core businesses, and improve returns for shareholders.
- In March 2025, BASF is expanding its production capacity for aminic antioxidants at its Puebla, Mexico site, targeting the growing demand for long-life lubricants. The project is set for completion in 2026.
- In March 2025, ExxonMobil announced a $100 million upgrade to its Baton Rouge, Louisiana plant to produce ultra-high-purity (99.999%) isopropyl alcohol (IPA) for the semiconductor industry by 2027.
- In March 2024, Dow announced plans to invest in new ethylene derivatives capacity-including carbonate solvents-on the U.S. Gulf Coast. This investment, supported by the U.S. Department of Energy, aims to supply carbonate solvents for lithium-ion batteries, supporting the domestic EV and energy storage market. The facility will capture over 90% of CO₂ from ethylene oxide production, aligning with sustainability goals.
Market Concentration & Characteristics
The Malaysia industrial solvents market exhibits moderate concentration, with a mix of multinational corporations and regional players dominating the sector. While global giants like CNPC, Formosa Plastics, Reliance Industries, and Sinopec hold significant market shares due to their extensive product portfolios and established supply chains, regional players also maintain a strong presence, offering localized solutions tailored to Malaysian industry needs. The market is characterized by a high degree of innovation, with key players focusing on the development of sustainable and eco-friendly solvent alternatives to meet growing environmental regulations. Additionally, the market's growth is fueled by demand from diverse sectors, including automotive, pharmaceuticals, paints & coatings, and electronics. The competitive environment is increasingly shaped by technological advancements in solvent recovery, product differentiation, and strategic partnerships, making it dynamic and highly responsive to evolving industrial demands. Manufacturers must balance cost efficiency, environmental compliance, and innovation to sustain their market positions.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End-Use, Source and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Malaysia industrial solvents market is expected to continue its steady growth trajectory, driven by increasing demand from key sectors such as automotive, electronics, pharmaceuticals, and paints & coatings.
- The shift towards sustainable and eco-friendly solvents is anticipated to gain momentum, with industries adopting bio-based and low-VOC alternatives in response to stringent environmental regulations.
- Technological advancements in solvent recovery and recycling processes are likely to enhance operational efficiencies and reduce environmental impact.
- The expansion of the pharmaceutical and biopharmaceutical industries in Malaysia is expected to drive demand for high-purity solvents, particularly in drug formulation and analytical testing applications.
- Strategic collaborations and partnerships among solvent manufacturers, raw material suppliers, and end-users are projected to foster innovation and improve market competitiveness.
- The government's commitment to sustainability and green initiatives is expected to support the adoption of eco-friendly solvents through favorable policies and incentives.
- The growing emphasis on digitalization and Industry 4.0 technologies is likely to influence solvent manufacturing processes, leading to improved product quality and production efficiency.
- Fluctuations in raw material prices and supply chain disruptions may pose challenges to solvent manufacturers, requiring agile strategies to mitigate risks.
- The increasing focus on circular economy principles is expected to promote the development of solvent recycling and reuse technologies, contributing to resource efficiency.
- As Malaysia continues to integrate into regional and global supply chains, the industrial solvents market is poised to benefit from expanded export opportunities and market diversification.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Robust Growth in Manufacturing and Industrial Activities
Malaysia's expanding manufacturing sector, particularly in electronics, automotive, and rubber industries, is driving increased consumption of industrial solvents for cleaning, degreasing, and chemical synthesis. Government incentives and infrastructure development further support this industrial expansion, boosting solvent demand.
Boom in Construction and Infrastructure Projects
Ongoing public and private investments in infrastructure, such as transport networks and urban development, are increasing the need for solvent-based paints, coatings, adhesives, and sealants. This sustained construction activity ensures a steady demand for industrial solvents across the country.
Shift Toward Eco-Friendly and Specialty Solvents
Stricter environmental regulations and growing sustainability goals are prompting industries to adopt eco-friendly, low-VOC, and bio-based solvents. This trend is fostering innovation and product diversification, as manufacturers invest in R&D to develop greener alternatives.
Favorable Trade Policies and Economic Outlook
Malaysia's strategic trade position in ASEAN, supported by free trade agreements and a stable economic environment, encourages industrial growth and export-oriented manufacturing. These factors amplify the demand for industrial solvents across diverse sectors.
Technological Advancements in Solvent Recovery and Recycling
Innovations in solvent purification, recovery, and recycling technologies are enabling industries to reduce waste and improve operational efficiency. This not only helps companies comply with environmental regulations but also creates new opportunities for high-purity and specialty solvent segments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Malaysia Industrial Solvents?
What factors are driving the growth of the Malaysia Industrial Solvents?
What are some challenges faced by the Malaysia Industrial Solvents?
Who are the major players in the Malaysia Industrial Solvents?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Alcohols
- 1.2.2 Ketones
- 1.2.3 Esters
- 1.2.4 Glycols
- 1.2.5 Others
- 1.3 By Source
- 1.3.1 Petrochemical-Based Solvents
- 1.3.2 Bio-Based Solvents
- 1.4 By End-Use
- 1.4.1 Construction
- 1.4.2 Automotive
- 1.4.3 Electronics
- 1.4.4 Agriculture
- 1.4.5 Others
- 1.5 By Application
- 1.5.1 Paints & Coatings
- 1.5.2 Pharmaceuticals
- 1.5.3 Printing Inks
- 1.5.4 Adhesives & Sealants
- 1.5.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 75.11 million → 2032: USD 131.48 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Malaysia Industrial Solvents Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Malaysia Industrial Solvents Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Malaysia Industrial Solvents Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Malaysia Industrial Solvents Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Malaysia Industrial Solvents Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Malaysia Industrial Solvents Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Malaysia Industrial Solvents Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Malaysia Industrial Solvents Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 75.11 million → 2032: USD 131.48 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Malaysia Industrial Solvents Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Alcohols
- 12.3.7.2 Ketones
- 12.3.7.3 Esters
- 12.3.7.4 Glycols
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Source - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Petrochemical-Based Solvents
- 12.4.7.2 Bio-Based Solvents
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-Use - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Construction
- 12.5.7.2 Automotive
- 12.5.7.3 Electronics
- 12.5.7.4 Agriculture
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Paints & Coatings
- 12.6.7.2 Pharmaceuticals
- 12.6.7.3 Printing Inks
- 12.6.7.4 Adhesives & Sealants
- 12.6.7.5 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Malaysia Industrial Solvents End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Malaysia Industrial Solvents Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Malaysia Industrial Solvents Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Malaysia Industrial Solvents Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Malaysia National Petroleum Corporation (CNPC)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Formosa Plastics Corporation
- 18.4 Reliance Industries Limited
- 18.5 Sinopec Group
- 18.6 Mitsubishi Chemical Holdings Corporation
- 18.7 Sumitomo Chemical Co., Ltd.
- 18.8 Toray Industries, Inc.
- 18.9 LG Chem Ltd.
- 18.10 Tata Chemicals Ltd.
- 18.11 SK Innovation Co., Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

