
Market Overview
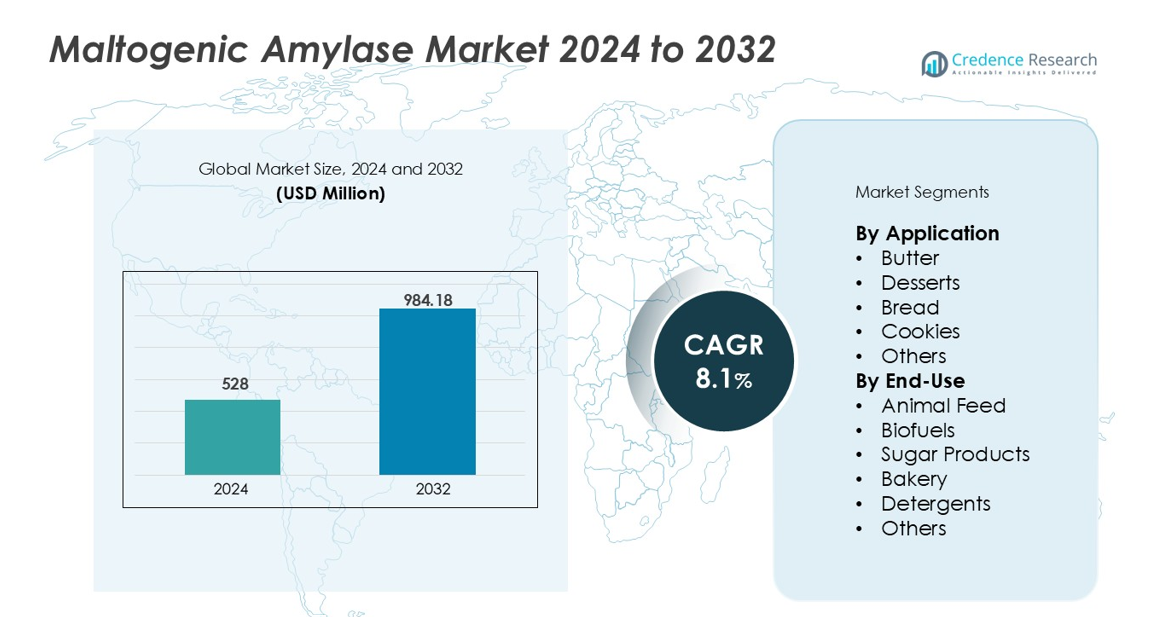
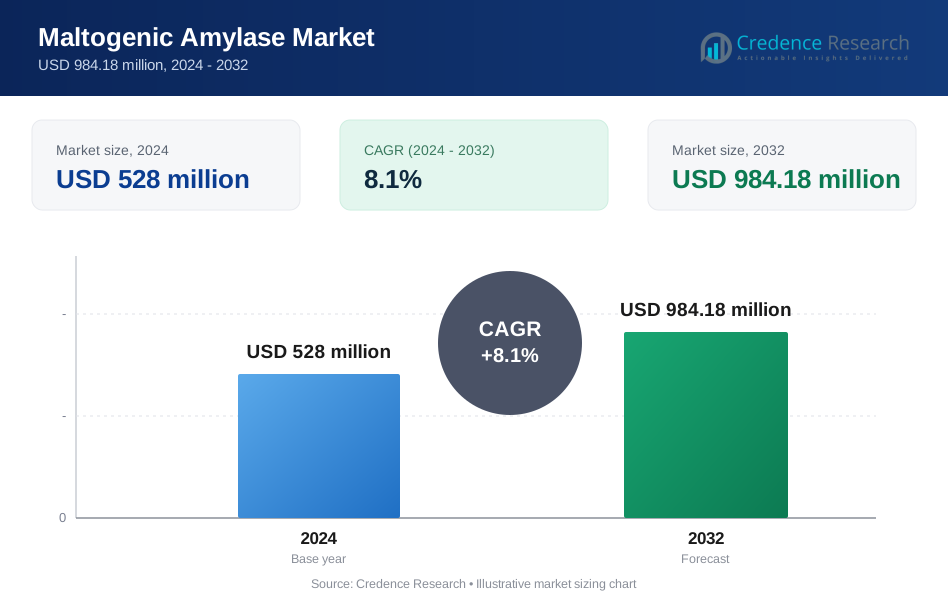
Maltogenic Amylase market size was valued USD 528 million in 2024 and is anticipated to reach USD 984.18 million by 2032, at a CAGR of 8.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Maltogenic Amylase Market Size 2024 | USD 528 million |
| Maltogenic Amylase Market, CAGR | 8.1% |
| Maltogenic Amylase Market Size 2032 | USD 984.18 million |
The Maltogenic Amylase market features strong competition among global and regional enzyme producers. Key players include Novozymes A/S, DSM, AB Enzymes, Amano Enzyme, Advanced Enzyme, Angel Yeast, and SUNSON Industry Group. These companies lead through strong formulation expertise and bakery-focused solutions. Novozymes and DSM maintain wide global reach and technical support networks. Asian players compete on cost and regional supply strength. North America leads the market with an exact share of 35%, driven by large-scale industrial bakeries and packaged food demand. Europe follows as a mature market, while Asia Pacific shows the fastest expansion. Regional leadership reflects advanced food processing infrastructure and high enzyme adoption.
Market Insights
- The Maltogenic Amylase market was valued at USD 528 million in 2024 and is projected to reach USD 984.18 million by 2032, growing at a CAGR of 8.1% during the forecast period.
- Market growth is driven by rising industrial bakery production, where bread applications hold nearly 35% segment share due to shelf-life extension needs. Packaged bakery demand supports stable enzyme adoption across large-scale processing units.
- Clean-label trends and enzyme-based processing shape market trends. Food manufacturers replace chemical improvers with maltogenic amylase to improve texture and freshness, especially in bread and cookies. Bakery end use dominates with about 40% share.
- Competition remains moderate, led by global enzyme producers focusing on formulation efficiency and technical support. Regional players compete through cost advantages and local supply strength. Product consistency and dosage efficiency drive differentiation.
- North America leads with around 35% market share, followed by Europe at 28% and Asia Pacific at 25%. Asia Pacific remains the fastest-growing region due to expanding packaged food consumption.
Market Segmentation Analysis:
By Application
The application segment shows strong demand from bakery and confectionery products. Bread remains the dominant sub-segment, accounting for nearly 35% market share. Bakeries use maltogenic amylase to improve crumb softness and extend shelf life. Consistent texture and delayed staling support large-scale bread production. Cookies and desserts follow due to rising packaged food consumption. Butter and specialty applications hold smaller shares but show steady use in premium products. Growth drivers include industrial baking expansion, clean-label enzyme adoption, and rising demand for consistent product quality across high-volume food processing.
- For instance, Novozymes’ Novamyl® 3D enzyme solution extends bread shelf life by up to 10–14 days while maintaining softness and elasticity, enabling commercial bakeries to reduce waste and optimize inventory cycles.
By End-Use
The bakery end-use segment leads the market with an estimated 40% share. Commercial bakeries rely on maltogenic amylase to maintain freshness during distribution. Sugar products represent the next major sub-segment, driven by texture control in confectionery processing. Animal feed and biofuels show moderate adoption due to starch modification needs. Detergents hold a niche share focused on specialty enzyme blends. Key drivers include rising industrial food processing, efficiency gains in starch conversion, and increased enzyme penetration across non-food applications seeking process stability and performance consistency.
- For instance, DSM’s BakeZyme® Master 4.0 is used in industrial bakeries to reduce firmness by over 25% after 7 days in packaged bread products, supporting shelf-life extension and maintaining consumer-acceptable texture.
Key Growth Drivers
Rising Demand from Industrial Bakery Processing
Industrial bakeries drive strong demand for maltogenic amylase worldwide. Manufacturers use the enzyme to delay starch retrogradation in baked goods. This function improves softness and shelf life in packaged bread. Large retail chains require longer freshness during transport and storage. Maltogenic amylase supports consistent texture across high-volume production lines. Frozen and par-baked products also rely on enzyme support. Growth in quick-service restaurants increases standardized bread usage. Urban lifestyles favor packaged bakery consumption. Enzyme solutions reduce product waste and return. Cost savings strengthen adoption among commercial bakers. This driver remains central to sustained market expansion.
- For instance, Angel Yeast markets a maltogenic amylase product, Annzyme MAM100, which is used in the baking industry to extend bread shelf life, improve elasticity, and reduce staling. In general industry trials and scientific studies, maltogenic amylase enzymes have been shown to effectively keep packaged bread soft during storage periods that can exceed 12 days.
Expansion of Processed and Convenience Food Consumption
Processed food demand continues to rise across regions. Consumers prefer ready-to-eat and long-shelf-life bakery products. Maltogenic amylase helps manufacturers meet these needs efficiently. The enzyme improves mouthfeel and freshness without recipe changes. Clean processing benefits align with modern food production goals. Food brands seek stable quality across batches and geographies. Enzyme use supports scalable manufacturing systems. Emerging economies show strong packaged food growth. Urban population growth increases demand for consistent bakery output. This trend supports long-term enzyme market growth.
- For instance, AB Enzymes’ VERON® MAXIMA was deployed by a major snack food company in Brazil to enhance the softness of pre-packed rolls for over 10 days without affecting the dough formula, improving batch consistency across 9 processing facilities.
Advancements In Enzyme Engineering and Formulation
Enzyme producers invest in improved maltogenic amylase variants. New formulations offer higher temperature and pH stability. These features suit diverse baking conditions. Improved specificity enhances starch conversion control. Manufacturers achieve better product consistency with lower dosages. Liquid and granulated formats improve handling efficiency. Longer enzyme activity extends freshness benefits. These innovations improve cost efficiency for end users. Food processors prefer reliable and predictable enzyme performance. Technology progress strengthens adoption across food and non-food applications.
Key Trends & Opportunities
Growing Adoption of Clean-Label and Enzyme-Based Solutions
Food producers shift toward clean-label processing aids. Maltogenic amylase replaces chemical dough conditioners in many recipes. Enzymes support simpler ingredient lists without sensory compromise. Regulatory acceptance of food enzymes supports this shift. Consumers favor products with familiar ingredient profiles. Bakery brands use enzymes to maintain quality claims. This trend creates strong opportunities for enzyme suppliers. Premium and health-focused bakery segments show higher adoption. Innovation in label-friendly enzyme blends expands application scope. Clean-label positioning strengthens long-term market opportunities.
- For instance, the use of maltogenic amylase is a well-established industry practice adopted by various organic bread brands to eliminate the need for chemical additives like mono- and diglycerides from their ingredient lists across numerous retail SKUs, while maintaining softness for several days post-bake.
Increasing Use Beyond Traditional Bakery Applications
The market sees rising use outside core bakery segments. Sugar processing uses maltogenic amylase for controlled hydrolysis. Animal feed producers apply enzymes to improve digestibility. Biofuel producers adopt enzymes for starch conversion efficiency. These applications diversify revenue streams. Industrial processors value process optimization benefits. Enzyme blends tailored for non-food uses gain traction. Emerging industrial markets support incremental growth. This trend reduces dependence on bakery demand alone. Broader application scope creates new growth pathways
Key Challenges
Sensitivity to Processing Conditions and Formulation Limits
Maltogenic amylase performance depends on precise conditions. Temperature and pH variations affect enzyme activity. Improper handling reduces effectiveness in baking processes. Smaller producers face formulation challenges during scale-up. Inconsistent results discourage adoption in some facilities. Storage stability also affects enzyme performance. Manufacturers must ensure correct dosing and process control. Technical support becomes critical for end users. These factors increase operational complexity. Such limitations can slow adoption among less advanced processors.
Price Pressure and Competition from Alternative Enzymes
The market faces pricing pressure from competing enzyme solutions. Amylase blends and multifunctional enzymes offer substitution options. Large food processors negotiate aggressive pricing contracts. Cost-sensitive regions favor lower-priced alternatives. Enzyme commoditization affects margin stability. Smaller suppliers struggle to differentiate offerings. Continuous innovation requires high development investment. Regulatory compliance adds further cost burden. These challenges affect profitability across the value chain. Competitive intensity remains a key restraint on market growth.
Regional Analysis
North America
North America holds the largest market share at around 35%. The region benefits from advanced industrial bakery infrastructure and high enzyme adoption. Large commercial bakeries rely on maltogenic amylase to extend shelf life. Strong demand comes from packaged bread and frozen bakery products. Clean-label reformulation remains a key focus for food brands. The United States leads regional consumption due to large-scale food processing. Canada supports steady growth through premium baked goods. Mature supply chains ensure stable enzyme availability. Continuous product innovation sustains regional leadership.
Europe
Europe accounts for nearly 28% of the global market share. The region shows strong demand from artisanal and industrial bakeries. Shelf-life improvement remains critical for cross-border distribution. Clean-label regulations favor enzyme-based processing aids. Countries such as Germany, France, and the United Kingdom lead adoption. Bakers focus on texture consistency and waste reduction. Strong regulatory clarity supports enzyme usage. Premium bread and confectionery segments drive demand. Sustainable food processing trends further support regional growth.
Asia Pacific
Asia Pacific represents about 25% of the market share and shows the fastest growth. Rising urbanization increases packaged bakery consumption. Expanding middle-class populations drive demand for convenience foods. China and India lead volume growth due to large populations. Japan and South Korea support high-value enzyme applications. Industrial bakeries expand capacity to meet retail demand. Shelf-life stability remains a major driver. Local manufacturers increase enzyme adoption to improve quality. The region offers strong long-term growth potential.
Latin America
Latin America holds approximately 7% of the global market share. Brazil and Mexico lead regional demand. Growth comes from expanding commercial bakery chains. Packaged bread consumption increases across urban centers. Cost efficiency remains a key purchase factor. Enzyme use helps reduce product losses during distribution. Local producers adopt maltogenic amylase gradually. Regulatory frameworks continue to evolve. Rising investment in food processing supports moderate growth. The region shows steady but controlled market expansion.
Middle East & Africa
The Middle East & Africa region accounts for around 5% market share. Urban population growth supports bakery demand. Gulf countries lead adoption due to modern food processing facilities. Long shelf life remains essential in hot climates. Imported bakery products increase enzyme usage. Local production capacity continues to expand slowly. Africa shows early-stage adoption in packaged foods. Cost sensitivity limits rapid penetration. Distribution infrastructure improvements support gradual growth. The region presents long-term opportunity with developing food industries.
Market Segmentations:
By Application
- Butter
- Desserts
- Bread
- Cookies
- Others
By End-Use
- Animal Feed
- Biofuels
- Sugar Products
- Bakery
- Detergents
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Maltogenic Amylase market shows a moderately consolidated competitive landscape. Leading players focus on product performance, formulation stability, and application-specific solutions. Global enzyme producers leverage strong research capabilities and established distribution networks. Companies invest in enzyme engineering to improve thermal stability and shelf-life extension effects. Strategic partnerships with industrial bakeries strengthen long-term supply contracts. Regional manufacturers compete through cost-efficient offerings and localized technical support. Product differentiation centers on dosage efficiency and consistent performance. Clean-label compliance influences product development strategies. Competitive intensity remains high due to price sensitivity among large buyers. Ongoing innovation and application expansion define long-term positioning across the market.
Key Player Analysis
- Novozymes A/S
- DSM
- AB Enzymes
- Amano Enzyme
- Advanced Enzyme
- Angel Yeast
- SUNSON Industry Group
- Infinita Biotech
- Antozyme Biotech
- Henan Chemsino Industrial
- Creative Enzymes
- LEVEKING
Recent Developments
- In June 2022, Royal DSM, a global purpose-led science-based company acquired Prodap, Brazilian animal nutrition, and technology company.
- In May 2022, BASF Enzymes launched its new brand SpartecTM for the North American bioethanol market. To provide sustainable solutions and create cutting-edge enzymes that add value for ethanol producers, BASF Bioenergy continuously works with customers and strategic partners.
Report Coverage
The research report offers an in-depth analysis based on Application, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Industrial bakeries will increase maltogenic amylase adoption to extend product freshness.
- Packaged bread and frozen bakery demand will support steady enzyme consumption.
- Clean-label product reformulation will accelerate enzyme-based processing use.
- Enzyme suppliers will focus on higher stability and lower dosage formulations.
- Application scope will expand beyond bakery into sugar processing and animal feed.
- Asia Pacific will remain the fastest-growing regional market.
- Regional producers will strengthen cost-competitive enzyme offerings.
- Technical support services will play a larger role in supplier selection.
- Competition will intensify through formulation efficiency and performance reliability.
- Long-term growth will depend on innovation and diversified end-use applications.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Maltogenic Amylase market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Maltogenic Amylase market projected to grow between 2024 and 2032?
What factors are driving the growth of the maltogenic amylase market?
Which regions are leading in the maltogenic amylase market and who are the major players?
Who are the leading companies in the Maltogenic Amylase market
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Maltogenic Amylase Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Maltogenic Amylase Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 528 million → 2032: USD 984.18 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Maltogenic Amylase Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Maltogenic Amylase Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Maltogenic Amylase Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Maltogenic Amylase Market Drivers
- 3.3 Maltogenic Amylase Market Restraints & Challenges
- 3.4 Maltogenic Amylase Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Maltogenic Amylase Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Maltogenic Amylase Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Maltogenic Amylase category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Maltogenic Amylase Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Maltogenic Amylase Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Maltogenic Amylase market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Maltogenic Amylase Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Maltogenic Amylase Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Maltogenic Amylase Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Maltogenic Amylase (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Maltogenic Amylase Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Maltogenic Amylase Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Maltogenic Amylase Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Maltogenic Amylase Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Maltogenic Amylase Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Maltogenic Amylase Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Maltogenic Amylase Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Maltogenic Amylase Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Maltogenic Amylase Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
