
Materials For Green Hydrogen Market Overview:
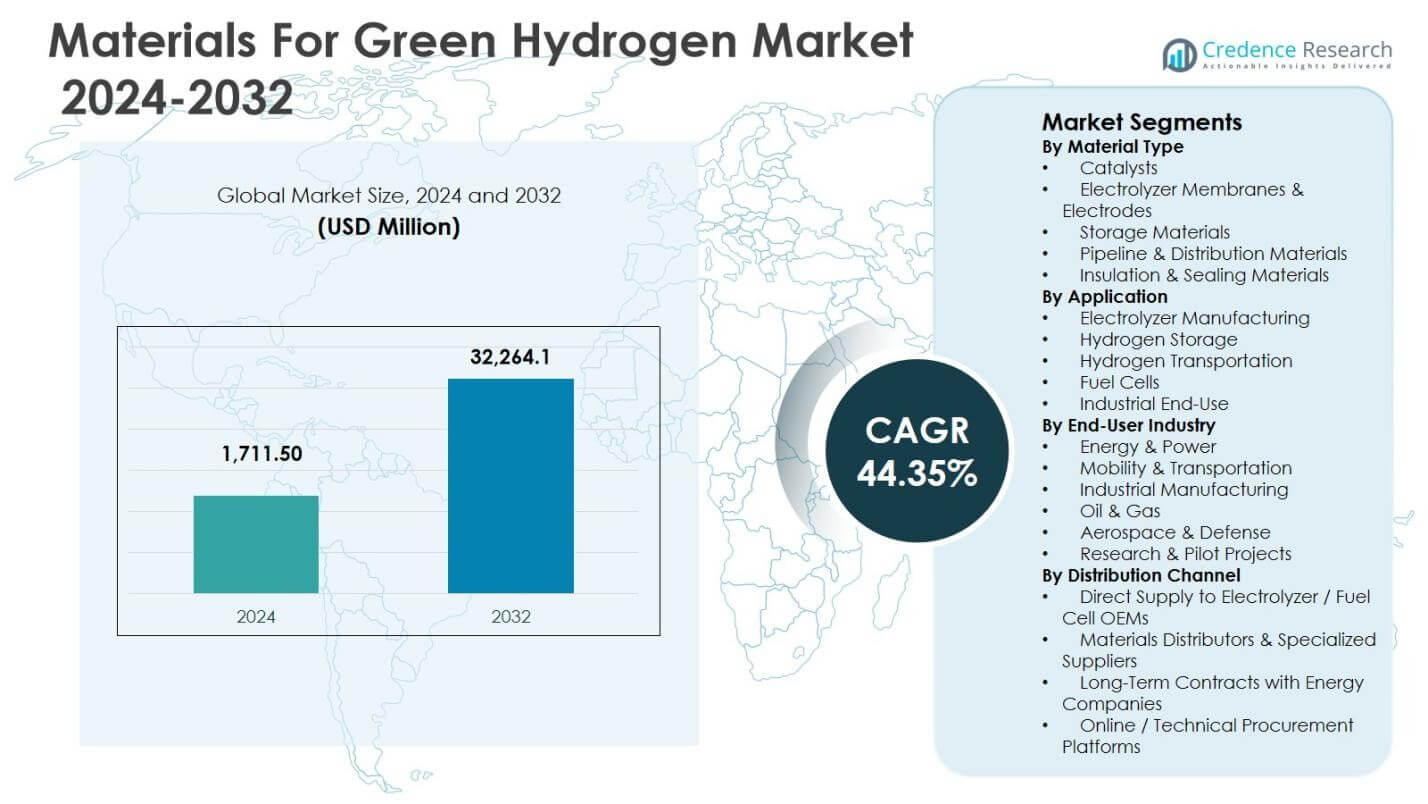
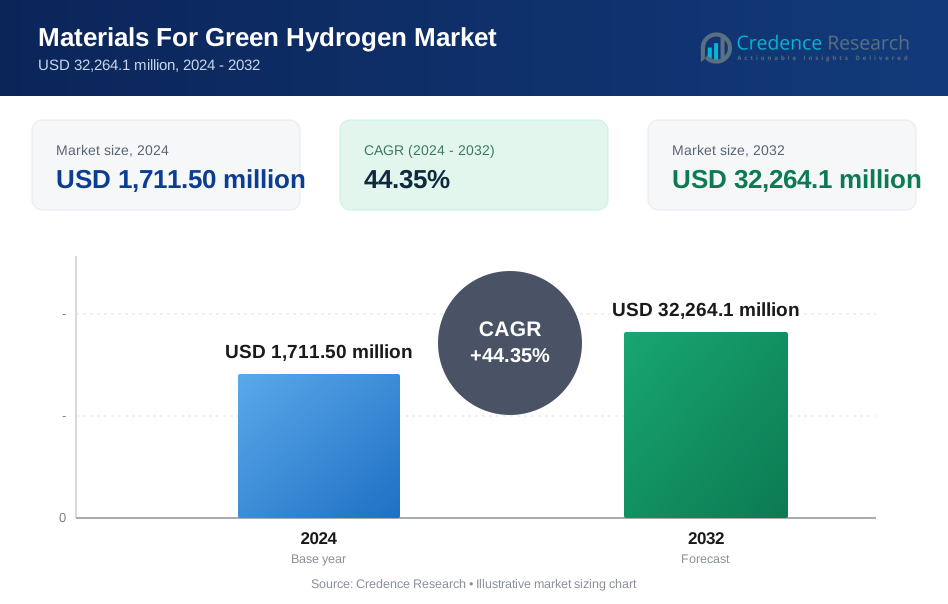
Materials For Green Hydrogen Market size was valued at USD 1,711.50 million in 2024 and is anticipated to reach USD 32,264.1 million by 2032, growing at a CAGR of 44.35% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Materials For Green Hydrogen Market Size 2024 | USD 1,711.50 million |
| Materials For Green Hydrogen Market, CAGR | 44.35% |
| Materials For Green Hydrogen Market Size 2032 | USD 32,264.1 million |
Materials For Green Hydrogen Market Insights
- Market growth is primarily driven by large-scale deployment of renewable-powered electrolyzers, strong government incentives, and rising demand for decarbonization across energy, industrial manufacturing, and mobility sectors, significantly increasing demand for membranes, electrodes, and catalysts.
- Electrolyzer membranes & electrodes dominated the market with a 42.6% share in 2024, followed by catalysts at 27.4%, while electrolyzer manufacturing led applications with a 46.8% share, reflecting high material intensity in hydrogen production systems.
- Market restraints include high costs of noble metals, supply chain constraints, and durability challenges under high-pressure and corrosive operating conditions, which impact overall material efficiency and project economics.
- Europe led the market with a 34.7% share in 2024, followed by North America at 28.4% and Asia-Pacific at 25.6%, supported by strong hydrogen policies, expanding renewable capacity, and increasing investments in green hydrogen infrastructure.
Materials For Green Hydrogen Market Segmentation Analysis:
By Material Type:
The Materials for Green Hydrogen Market by material type is led by electrolyzer membranes & electrodes, which accounted for 42.6% market share in 2024, driven by their critical role in PEM and alkaline electrolyzers used for large-scale green hydrogen production. Strong demand for high-efficiency proton exchange membranes, iridium- and platinum-based catalysts, and durable electrode coatings supports this dominance. Catalysts followed with 27.4% share, supported by ongoing R&D to reduce noble-metal loading. Storage materials, pipeline & distribution materials, and insulation & sealing materials collectively held 30.0% share, driven by infrastructure expansion and safety requirements.
- For instance, W. L. Gore & Associates reports that its advanced PEM membrane (e.g., M275 series) delivers about 5% higher cell voltage efficiency than conventional PEMs in water electrolysis, lowering the electricity required per kilogram of green hydrogen and enabling more compact stacks for large projects.
By Application:
By application, electrolyzer manufacturing dominated the Materials for Green Hydrogen Market with a 46.8% market share in 2024, supported by rapid global deployment of utility-scale electrolyzers aligned with renewable energy projects. Government incentives, capacity expansion targets, and declining electrolyzer costs significantly drive material demand in this segment. Hydrogen storage accounted for 21.9% share, driven by investments in compressed and solid-state storage technologies. Hydrogen transportation held 15.6% share, supported by pipeline retrofitting and distribution networks, while fuel cells and industrial end-use applications together represented 15.7% share, driven by mobility and industrial decarbonization initiatives.
- For instance, Linde is constructing a 35 MW PEM electrolyzer at its Niagara Falls facility, set to produce 14 tonnes of green hydrogen per day using hydroelectric power starting in 2025.
By End-User Industry:
The energy & power sector emerged as the dominant end-user industry with a 38.3% market share in 2024, driven by large-scale green hydrogen projects integrated with solar and wind power generation. National hydrogen strategies and grid-scale energy storage needs strongly support material demand from this segment. Industrial manufacturing followed with 22.7% share, supported by hydrogen use in steel, chemicals, and refining. Mobility & transportation accounted for 18.4% share, driven by fuel-cell vehicles and heavy transport. Oil & gas, aerospace & defense, and research & pilot projects collectively held 20.6% share, supported by pilot deployments and transition initiatives.
Key Growth Drivers
Rapid Expansion of Green Hydrogen Projects
The Materials for Green Hydrogen Market is strongly driven by the accelerating deployment of green hydrogen projects worldwide. Governments and private players are committing large-scale investments to develop renewable-powered electrolyzer capacity to support decarbonization goals. This expansion directly increases demand for advanced catalysts, membranes, electrodes, and balance-of-plant materials that improve electrolyzer efficiency and durability. National hydrogen strategies across Europe, Asia-Pacific, and the Middle East emphasize domestic manufacturing of electrolyzers, further strengthening material consumption. As project pipelines grow in size and complexity, material suppliers benefit from higher volumes, long-term supply contracts, and increasing performance requirements.
- For instance, Linde is constructing a 24-megawatt PEM electrolyzer at its Leuna site in Germany to supply green hydrogen via existing pipelines, capable of fueling around 600 fuel cell buses yearly.
Advancements in Electrolyzer and Material Technologies
Continuous technological innovation in electrolyzers significantly fuels market growth for green hydrogen materials. Improvements in proton exchange membrane, alkaline, and anion exchange membrane technologies are driving demand for high-performance membranes, corrosion-resistant electrodes, and low-iridium catalysts. Manufacturers are focusing on enhancing material lifetimes, reducing degradation, and improving energy efficiency to lower hydrogen production costs. These advancements enable higher operating pressures and temperatures, increasing hydrogen output per unit of material. As electrolyzer technologies mature and move toward gigawatt-scale deployment, demand for specialized, high-quality materials continues to rise steadily.
- For instance, Accelera by Cummins developed the HyLYZER PEM electrolyzer, supplying a 100 MW system of 20 PEM HyLYZER-1000 units for bp's Lingen green hydrogen project in Germany, manufactured in their Guadalajara plant for commissioning in 2027.
Strong Policy Support and Decarbonization Targets
Supportive regulatory frameworks and ambitious decarbonization targets represent a major growth driver for the Materials for Green Hydrogen Market. Governments are offering subsidies, tax credits, and funding programs to accelerate green hydrogen adoption across energy, transportation, and industrial sectors. Policies promoting clean fuels, carbon neutrality, and fossil fuel replacement increase investments in hydrogen infrastructure, directly boosting material demand. Mandates for renewable hydrogen use in refining, chemicals, and steel production further strengthen market momentum. This strong policy backing provides long-term visibility for material manufacturers and encourages capacity expansion and innovation.
Key Trends & Opportunities
Shift Toward Cost-Optimized and Scalable Materials
A key trend shaping the Materials for Green Hydrogen Market is the shift toward cost-optimized and scalable material solutions. Manufacturers are actively reducing reliance on scarce and expensive noble metals by developing alternative catalysts and thinner membrane designs without compromising performance. This trend improves supply chain resilience and supports large-scale electrolyzer deployment. Opportunities are emerging for material suppliers that can deliver high-volume, standardized products with consistent quality. As cost reduction becomes critical for green hydrogen competitiveness, companies offering innovative, scalable material solutions are well positioned to capture long-term growth.
- For instance, Hystar employs thinner PEM membranes, reduced by 90% compared to industry standards (from around 100-200 μm to 20 μm), which lowers ohmic resistance and boosts efficiency in their electrolyzers.
Growing Demand for Integrated Hydrogen Infrastructure Materials
The growing focus on end-to-end hydrogen ecosystems creates significant opportunities for materials used beyond electrolyzers. Increasing investments in hydrogen storage, transportation pipelines, compression systems, and sealing solutions are expanding demand for advanced alloys, composites, and insulation materials. This trend supports diversification of material portfolios across multiple stages of the hydrogen value chain. Suppliers capable of providing integrated material solutions for production, storage, and distribution benefit from higher customer retention and cross-segment demand. As hydrogen infrastructure networks expand, material innovation for safety, durability, and efficiency becomes a key differentiator.
- For instance, Hexagon Purus provides lightweight Type 4 composite hydrogen cylinders using carbon fiber-reinforced materials and polymer liners, capable of handling pressures from 700 to 950 bar while preventing hydrogen embrittlement for enhanced durability in fuel cell vehicles and industrial storage.
Key Challenges
High Material Costs and Supply Constraints
High costs of critical raw materials pose a significant challenge for the Materials for Green Hydrogen Market. Dependence on scarce elements such as iridium, platinum, and specialized polymers increases production costs and exposes manufacturers to supply volatility. Limited global availability and geopolitical risks further strain supply chains. These cost pressures slow the pace of electrolyzer deployment and reduce project profitability. Addressing this challenge requires accelerated development of alternative materials, recycling strategies, and improved material efficiency to reduce overall dependency on constrained resources.
Technical Durability and Performance Limitations
Ensuring long-term durability and consistent performance of materials remains a key challenge in green hydrogen applications. Electrolyzers operate under demanding conditions, including high temperatures, pressures, and corrosive environments, which accelerate material degradation. Failures in membranes, electrodes, or sealing materials can lead to downtime and higher maintenance costs. Achieving longer lifetimes while maintaining efficiency is critical for large-scale adoption. Material manufacturers must balance performance, cost, and reliability, making continuous testing, validation, and innovation essential to overcome these technical limitations.
Regional Analysis
North America
North America accounted for 28.4% market share in 2024 in the Materials for Green Hydrogen Market, supported by strong policy incentives, large-scale electrolyzer deployments, and rapid growth in renewable energy capacity. The United States leads regional demand due to federal tax credits, hydrogen hub funding, and increasing adoption of green hydrogen across power generation, refining, and mobility sectors. Demand for high-performance membranes, catalysts, and storage materials remains strong as electrolyzer manufacturing scales domestically. Canada also contributes through pilot projects and clean energy investments, reinforcing steady material consumption across the region.
Europe
Europe held the largest share of the Materials for Green Hydrogen Market with 34.7% market share in 2024, driven by aggressive decarbonization targets and well-defined hydrogen strategies. Countries such as Germany, France, the Netherlands, and Spain are investing heavily in electrolyzer capacity and hydrogen infrastructure. Strong emphasis on domestic manufacturing of electrolyzers and supply-chain localization supports high demand for advanced membranes, electrodes, and pipeline materials. The region’s focus on replacing fossil fuels in industrial processes and cross-border hydrogen networks further strengthens material demand and long-term market stability.
Asia-Pacific
Asia-Pacific captured 25.6% market share in 2024, driven by rapid industrialization, expanding renewable energy capacity, and government-led hydrogen initiatives. China dominates regional demand through large-scale electrolyzer manufacturing and cost-competitive material production. Japan and South Korea contribute significantly through fuel cell deployment, hydrogen mobility, and advanced material innovation. India is emerging as a high-growth market, supported by national green hydrogen missions and infrastructure investments. Strong manufacturing capabilities and rising domestic consumption of electrolyzer and storage materials position Asia-Pacific as a key growth engine.
Latin America
Latin America accounted for 6.1% market share in 2024, supported by abundant renewable energy resources and growing interest in green hydrogen exports. Countries such as Chile and Brazil are developing large-scale solar- and wind-powered hydrogen projects aimed at international markets. These initiatives drive demand for electrolyzer materials, storage systems, and corrosion-resistant infrastructure materials. While the regional market remains smaller in scale, increasing foreign investment, pilot projects, and export-oriented strategies continue to strengthen material demand and create long-term growth potential.
Middle East & Africa
The Middle East & Africa region held 5.2% market share in 2024, driven by strategic investments in green hydrogen as part of economic diversification and energy transition plans. Saudi Arabia, the United Arab Emirates, and Oman are developing large integrated hydrogen projects supported by renewable energy capacity. Demand for durable electrolyzer components, high-temperature materials, and pipeline solutions is increasing. In Africa, pilot projects and international partnerships are emerging, supporting gradual growth. Strong government backing and export-focused projects underpin steady material demand in the region.
Market Segmentations:
By Material Type
- Catalysts
- Electrolyzer Membranes & Electrodes
- Storage Materials
- Pipeline & Distribution Materials
- Insulation & Sealing Materials
By Application
- Electrolyzer Manufacturing
- Hydrogen Storage
- Hydrogen Transportation
- Fuel Cells
- Industrial End-Use
By End-User Industry
- Energy & Power
- Mobility & Transportation
- Industrial Manufacturing
- Oil & Gas
- Aerospace & Defense
- Research & Pilot Projects
By Distribution Channel
- Direct Supply to Electrolyzer / Fuel Cell OEMs
- Materials Distributors & Specialized Suppliers
- Long-Term Contracts with Energy Companies
- Online / Technical Procurement Platforms
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis of the Materials for Green Hydrogen Market highlights the presence of key players including Air Liquide, Linde plc, Air Products and Chemicals, Inc., Nel ASA, Siemens Energy AG, ITM Power plc, Plug Power Inc., McPhy Energy S.A., Ballard Power Systems Inc., and Enapter AG. The market is characterized by intense competition driven by technological innovation, scale expansion, and supply-chain integration across catalysts, membranes, electrodes, and infrastructure materials. Leading companies focus on improving material efficiency, reducing noble metal dependency, and enhancing durability to support gigawatt-scale electrolyzer deployment. Strategic partnerships with renewable developers, government-backed hydrogen projects, and industrial off-takers strengthen market positioning. Continuous investments in R&D, localization of manufacturing, and long-term supply agreements remain key strategies as players compete to meet rising global demand for cost-effective and high-performance green hydrogen materials.
Key Player Analysis
- Air Liquide
- Linde plc
- Air Products and Chemicals, Inc.
- Plug Power Inc.
- Nel ASA
- Siemens Energy AG
- ITM Power plc
- Ballard Power Systems Inc.
- McPhy Energy S.A.
- Enapter AG
Recent Developments
- In December 2025, AM Green and Mitsui & Co., Ltd. signed a Memorandum of Understanding (MoU) to explore a strategic collaboration in hydrogen value-chain materials and technologies.
- In September 2025, Oxford nanoSystems was acquired by new ownership under Dr. David Hodgson, with plans to pivot the UK-based company toward focused electrolyser materials testing and validation services.
- In September 2025, CATAGEN launched its ClimaHtech Compressor, a revolutionary liquid piston hydrogen compressor offering 28% average energy savings for refueling and distribution applications.
Report Coverage
The research report offers an in-depth analysis based on Material Type, Application, End User Industry, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Materials for Green Hydrogen Market will expand rapidly as global electrolyzer capacity continues to scale across utility and industrial projects.
- Demand for high-performance membranes and electrodes will rise with the adoption of advanced PEM, alkaline, and AEM electrolyzer technologies.
- Catalyst innovation will accelerate, focusing on reduced noble-metal content and improved efficiency to lower production costs.
- Materials supporting hydrogen storage and transportation will gain importance as large-scale infrastructure networks are developed.
- Manufacturers will prioritize durability and longer material lifetimes to improve electrolyzer reliability and operational efficiency.
- Supply chain localization will strengthen as countries promote domestic manufacturing of hydrogen-related materials.
- Integration of green hydrogen into steel, chemicals, and refining will drive sustained material demand from industrial end users.
- Collaboration between material suppliers and electrolyzer manufacturers will intensify to enable standardized and scalable solutions.
- Research and pilot projects will play a critical role in validating next-generation materials under real operating conditions.
- Sustainability and recyclability of hydrogen materials will become a key focus as environmental regulations tighten globally.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Materials For Green Hydrogen Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Materials For Green Hydrogen Market projected to grow between 2024 and 2032?
Which Materials For Green Hydrogen Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Materials For Green Hydrogen Market?
Who are the leading companies in the Materials For Green Hydrogen Market?
Which region commanded the largest share of the Materials For Green Hydrogen Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,711.50 million → 2032: USD 32,264.1 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Materials For Green Hydrogen Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Materials For Green Hydrogen Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Materials For Green Hydrogen Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Materials For Green Hydrogen Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Materials For Green Hydrogen Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Materials For Green Hydrogen Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Materials For Green Hydrogen Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Materials For Green Hydrogen Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,711.50 million → 2032: USD 32,264.1 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Materials For Green Hydrogen Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Materials For Green Hydrogen Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Materials For Green Hydrogen Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Materials For Green Hydrogen Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

