
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Medical Robots Market Size 2024 | USD 11427.1 million |
| Medical Robots Market, CAGR | 10.30% |
| Medical Robots Market Size 2032 | USD 27613.22 million |
Market Overview:
The Medical Robots Market is projected to grow from USD 11427.1 million in 2023 to an estimated USD 27613.22 million by 2032, with a compound annual growth rate (CAGR) of 10.30% from 2023 to 2032.
Rising demand for minimally invasive procedures drives market growth by decreasing patient trauma, shortening hospital stays, and improving clinical outcomes. Concurrently, the global surge in chronic conditions such as cardiovascular diseases, oncological disorders, and neurological impairments escalates the need for precise, repeatable interventions that robotics uniquely deliver. Technological advancements represent a second major driver: integration of AI, machine learning, and advanced sensor technologies enhances real-time imaging, haptic feedback, and error-avoidance capabilities, empowering surgeons to perform complex procedures with greater confidence and consistency. Aging populations in developed regions further bolster demand for rehabilitation robotics, as affordable exoskeletons and assistive devices support independence among elderly patients. Healthcare providers also pursue robotics to address labor shortages, reallocating skilled clinicians toward high-value tasks while robots handle repetitive or hazardous chores.
North America dominates the medical robots market, this leadership stems from advanced healthcare infrastructure, high per-capita procedure volumes, and early acceptance of robotic surgery and automation tools. The United States leads regional growth, underpinned by proactive reimbursement policies and significant R&D investments by both established and emerging robotics firms. Europe secures the second-highest market share, driven by strong demand in Germany, France, and the United Kingdom, where government funding and public-private partnerships underwrite adoption of both surgical and service robots. Asia Pacific will register the fastest CAGR over the forecast period, propelled by expanding healthcare access in China and India, rising geriatric populations, and mounting government initiatives to modernize hospital networks. Within this region, Japan’s technological prowess and South Korea’s early rollout of next-gen robotic platforms will further reinforce market momentum. Latin America and Middle East & Africa represent emerging opportunities, where improving healthcare budgets and growing private-sector involvement anticipate steady uptake of cost-effective robotic solutions by 2032.
Market Insights:
- The Medical Robots Market is projected to grow from USD 11,427.1 million in 2023 to USD 27,613.22 million by 2032, with a CAGR of 10.30%.
- Rising demand for minimally invasive procedures drives adoption by reducing patient trauma and improving recovery outcomes.
- Aging populations increase the need for rehabilitation and assistive robots that support mobility and independence in elderly patients.
- Integration of AI, machine learning, and imaging technologies enhances surgical accuracy and real-time intraoperative decision-making.
- Hospitals implement robotic automation to manage staff shortages and improve efficiency in logistics and repetitive tasks.
- High equipment costs, maintenance expenses, and complex regulatory requirements limit accessibility for smaller healthcare providers.
- North America leads the market, Asia Pacific shows the fastest growth, and Europe benefits from strong government support and R&D investment.
Report Scope
This report segments the Medical Robots Market as follows:
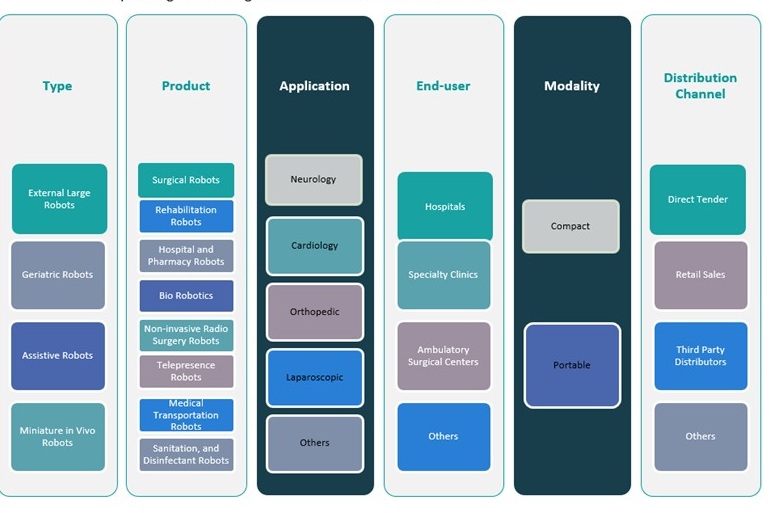
Market Drivers:
Surge in Minimally Invasive Procedures Drives Precision and Patient Safety
Medical Robots Market growth stems from physician preference for small incisions that minimize patient trauma. It cuts healing times and lowers infection rates across diverse surgical specialties. Surgeons achieve higher precision when robots execute controlled, repeatable movements. Device manufacturers enhance instrument dexterity and integrate real-time feedback systems for improved decision making. Hospitals allocate capital to platforms that deliver consistent accuracy under challenging anatomical conditions. Patients benefit from shorter hospital stays and faster returns to daily activities. Healthcare teams appreciate workflows that balance clinical efficacy with operational efficiency.
- For instance, Intuitive Surgical reported that over 1.8 million procedures were performed worldwide using the da Vinci Surgical System in 2023, with hospitals citing a 20–30% reduction in post-operative infection rates compared to traditional surgery.
Growing Geriatric Population Expands Rehabilitation and Long-Term Care Demand
It intensifies demand for robotic rehabilitation devices designed to support mobility and neurological recovery in elderly patients. Healthcare providers adopt exoskeletons and wearable robots to supplement physical therapy and reduce caregiver burden. Medical Robots Market players develop lightweight, adjustable systems that adapt to individual patient anatomy. Clinicians observe improvements in muscle strength and gait stability when robots assist repetitive exercises. Payers recognize cost savings linked to fewer readmissions and lower long-term care needs. Rehabilitation centers integrate robotics into standard care protocols to boost treatment consistency. Patient satisfaction rises when therapy incorporates precise, motivating feedback from automated devices.
- For example, Ekso Bionics reported that patients using its EksoNR exoskeleton achieved a 32% improvement in walking speed after 12 weeks of therapy.
Advances in Artificial Intelligence and Imaging Technologies Boost Functional Capabilities
It empowers robotic solutions with enhanced situational awareness and autonomous decision support. Developers embed machine-learning algorithms that process multi-modal imaging data to guide surgical planning. Medical Robots Market participants leverage AI to map tissue boundaries and predict optimal instrument trajectories. Engineers refine sensor arrays that detect subtle force variations, enabling improved haptic feedback. Software upgrades allow systems to adapt to intra-operative changes in real time. Hospitals report higher procedural success rates when robots collaborate with navigation platforms. Research teams pursue innovations that merge deep learning with robotic control to expand application scope.
Labor Shortages and Operational Efficiency Encourage Automation Integration
Hospitals face chronic clinician shortages and elevated staff turnover that strain service delivery. It shifts routine or hazardous tasks-such as sterilization, material transport, and pharmacy dispensing-to automation. Medical Robots Market offerings include autonomous mobile robots that navigate hospital corridors and handle logistical workflows. Facility managers reduce labor costs and reallocate skilled professionals to critical patient-care roles. Quality assurance departments track performance metrics that demonstrate fewer errors and higher throughput. Stakeholders prioritize scalable robotic fleets that integrate with electronic health-care systems. Long-term planning favors modular solutions that evolve alongside institutional needs.
Market Trends:
Integration of Advanced AI Algorithms for Enhanced Surgical Autonomy
Developers embed AI modules into robotic systems to analyze real-time data. It improves decision-making during procedures. Hospitals deploy these smart platforms to reduce variability across surgeons. The Medical Robots Market relies heavily on pattern recognition that identifies critical anatomical features. Engineers train algorithms on large datasets to refine motion control. Surgeons witness higher precision when AI guides instrument positioning. Manufacturers push software updates to expand supported procedures and refine tool calibration.
- For example, Intuitive Surgical’s da Vinci platform incorporates AI-powered vision systems for enhanced depth perception and real-time instrument tracking, while Stryker’s Mako system uses AI algorithms and advanced imaging to create patient-specific surgical plans, optimizing implant positioning in orthopedic procedures.
Expansion of Telepresence Platforms Enabling Remote Surgical Interventions
Clinicians connect with patients in remote locations through secure networks. Surgical robots transmit high-definition video and haptic feedback in real time. It supports centers in underserved regions. The Medical Robots Market experiences growth in platforms that combine robotics with telemedicine. Vendors partner with network providers to ensure low-latency performance. Healthcare systems deploy these solutions to broaden access to expert care. Regulatory bodies evaluate safety standards to govern cross-border procedures.
Shift Toward Compact and Modular Systems for Ambulatory Care Environments
Clinicians seek portable robotic units that fit small operating suites. It reduces capital expenditure on large infrastructure renovations. The Medical Robots Market sees rising demand for plug-and-play attachments that support diverse tasks. Providers rotate modules quickly between surgery, diagnostics, and rehabilitation. Manufacturers design user interfaces that require minimal training. Hospitals report faster turnover when robots adapt to changing caseloads. Engineers emphasize standard connectivity to integrate with existing hospital networks.
- For instance, Brainlab’s Cirq system is a lightweight, flexible robotic assistant that integrates seamlessly with standard operating tables and offers modular end effectors for various procedures, including spine and cranial surgeries.
Convergence of Robotics With Integrated Digital Healthcare Infrastructure
Hospitals adopt platforms that link robots to electronic health records and analytics tools. It allows surgical plans to update dynamically based on patient history. The Medical Robots Market benefits from cloud-based software that enables centralized fleet management. Administrators monitor performance metrics and maintenance schedules through unified dashboards. Vendors secure data with encryption and access controls to comply with privacy laws. Healthcare leaders prioritize interoperability to avoid vendor lock-in and maximize resource utilization. Clinicians access outcome data to guide quality improvement and training programs.
Market Challenges Analysis:
High Procurement and Maintenance Costs Impede Wide-Scale Deployment
Hospitals allocate significant capital to purchase robotic suites with multiple arms, consoles, and accessories. The Medical Robots Market faces scrutiny over return on investment for procedures that already run profitably. It demands extensive staff training and certification that increase operational budgets. Providers must schedule downtime for preventive maintenance that disrupts case schedules. Vendors charge premium fees for software licenses and upgrades, which inflate lifetime costs. Smaller clinics and ambulatory centers struggle to secure financing for these advanced platforms. Clinical directors weigh value against volume metrics before approving new robotics lines.
- For instance, the da Vinci Xi Surgical System from Intuitive Surgical has a list price ranging from $1.5 million to $2.5 million per unit, with annual maintenance contracts costing approximately $100,000–$170,000 per year.
Complex Regulatory Approval and Integration Challenges Stall Growth
Manufacturers navigate divergent safety standards across regions that prolong product launches. Regulators require extensive clinical data to prove efficacy and safety for each new application. It slows approvals even when system design improvements simplify workflows. Healthcare systems report integration difficulties with legacy electronic records and imaging networks. IT teams must validate data security protocols to meet diverse privacy regulations. Training and support resources vary by vendor, which complicates large-scale rollouts. Hospital administrators coordinate cross-functional teams to align on compliance and adoption timelines.
Market Opportunities:
Healthcare systems in Latin America, Southeast Asia, and Africa plan facility upgrades that include robotic platforms. The Medical Robots Market can target these regions by offering scalable financing options. It provides training programs tailored to local clinical practices that boost adoption rates. Device makers collaborate with government bodies to secure public–private partnership grants. Hospitals invest in minimally invasive surgery suites to improve procedural volume. Manufacturers supply modular robotic units that fit diverse budget constraints. Clinicians gain access to advanced surgical care without overhauling existing infrastructure.
Robotics firms partner with AI startups to enhance image-guided surgical planning. The Medical Robots Market benefits when it supports interoperability with electronic health records and diagnostics software. Companies co-develop specialty tools for orthopedics, neurosurgery, and pediatrics to address unmet clinical needs. Distributors offer service bundles that combine maintenance, software updates, and outcome analytics. Research institutes collaborate on trials that validate new applications and accelerate regulatory approval. Healthcare networks adopt pilot programs that demonstrate value in high-volume centers. This collaborative model reduces barriers and expands clinical use cases.
Market Segmentation Analysis:
The Medical Robots Market is segmented across multiple dimensions that reflect its broad scope and clinical applications.
By type, external large robots dominate due to their advanced surgical capabilities, while assistive and geriatric robots gain traction in rehabilitation and eldercare. Miniature in vivo robots show potential in minimally invasive diagnostics and procedures.
By product, surgical robots lead the market, supported by widespread adoption in urology, gynecology, and general surgery. Rehabilitation robots see steady demand due to aging populations, while hospital and pharmacy robots streamline logistics and medication management. Segments like telepresence, sanitation, and transportation robots address operational efficiency and infection control priorities.
By modality, compact systems hold significant share in hospital settings, while portable robots cater to outpatient and home care environments.
By application, orthopedic and neurology dominate, followed by cardiology and laparoscopic use cases.
By End-users include hospitals, which account for the largest share, followed by specialty clinics and ambulatory surgical centers.
By distribution channel, direct tender leads, with retail sales and third-party distributors expanding access in developing regions.
Segmentation:
By Type
- External Large Robots
- Geriatric Robots
- Assistive Robots
- Miniature in Vivo Robots
By Product
- Surgical Robots
- Rehabilitation Robots
- Hospital and Pharmacy Robots
- Bio Robotics
- Non-invasive Radio Surgery Robots
- Telepresence Robots
- Medical Transportation Robots
- Sanitation and Disinfectant Robots
By Modality
- Compact
- Portable
By Application
- Neurology
- Cardiology
- Orthopedic
- Laparoscopic
- Others
By End-user
- Hospitals
- Specialty Clinics
- Ambulatory Surgical Centers
- Others
By Distribution Channel
- Direct Tender
- Retail Sales
- Third Party Distributors
- Others
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Dominance of North America Through Early Technology Adoption Hospitals in the United States and Canada invest heavily in robotic surgery platforms, securing a 38 percent share of the global medical robots market in 2024. Healthcare systems there benefit from established reimbursement policies that support high-cost equipment. It drives widespread deployment of surgical robots in leading academic and community hospitals. Clinicians gain consistent precision when they perform procedures with robotic assistance. Manufacturers release regular software updates and training modules to sustain clinical confidence. Research partnerships with universities accelerate next-generation innovations. Regional leaders plan incremental expansions of robotic fleets to meet growing procedural volumes.
Steady Growth in Europe Fueled by Public–Private Initiatives European nations command roughly 25 percent of the global medical robots market, reflecting strong government funding for healthcare modernization. National health services adopt robots for surgery, rehabilitation, and hospital automation to optimize resource use. It encourages collaboration between domestic robotics firms and academic research centers. Regulatory bodies streamline device approvals to maintain patient safety while reducing time to market. Hospitals deploy modular systems that fit existing operating suites without major renovations. Insurers recognize long-term cost savings tied to shorter hospital stays and lower complication rates. Leading economies such as Germany, France, and the United Kingdom drive regional demand and cultivate export opportunities.
Rapid Expansion in Asia Pacific and Emerging Regions Asia Pacific holds 20 percent of the market, propelled by government schemes in China, India, and Japan that upgrade hospital infrastructure. It targets minimally invasive surgery and aging-population care through scalable, lower-cost robotic solutions. Latin America captures 10 percent, driven by private-sector investments in Brazil and Mexico. Health systems there integrate telepresence robots to extend specialist reach. Middle East and Africa account for 7 percent, supported by new hospital projects in the Gulf Cooperation Council and South Africa. It taps public–private partnerships to introduce robotic rehabilitation and pharmacy automation. Emerging-market stakeholders plan phased rollouts aligned with local clinical training and service networks.
Key Player Analysis:
- Medtronic
- Titan Medical Inc.
- Accuray Incorporated
- Stryker
- Stereotaxis, Inc.
Competitive Analysis:
The Medical Robots Market features strong competition among global leaders and emerging innovators focused on specialized applications. Intuitive Surgical holds a dominant position with its da Vinci robotic systems, supported by a broad procedural base and established training ecosystem. Medtronic advances its Hugo robotic platform to expand global surgical access. Stryker strengthens its foothold in orthopedic robotics with the Mako system, delivering consistent growth in joint replacement procedures. Siemens Healthineers and Zimmer Biomet invest in smart navigation and AI-integrated solutions to enhance surgical accuracy. Emerging players such as CMR Surgical and Asensus Surgical introduce compact, cost-effective platforms tailored to mid-tier hospitals. It encourages partnerships with research institutes, software developers, and health systems to co-develop application-specific solutions. Competitive strategies focus on modular designs, AI-driven analytics, and post-sale service models to build customer loyalty and drive recurring revenue. Players prioritize global expansion, clinical validation, and regulatory approvals to secure long-term market presence.
Recent Developments:
- In April 2024, Intuitive Surgical announced the launch of its next-generation da Vinci 5 surgical system. This advanced robotic platform features enhanced imaging, improved ergonomics, and new AI-powered assistance tools, aiming to further improve precision and patient outcomes in minimally invasive surgery. The launch underscores Intuitive’s commitment to maintaining its leadership in the surgical robotics space.
- In January 2024, Zimmer Biomet introduced the ROSA Hip System, expanding its ROSA Robotics portfolio. The new system is designed to assist surgeons during hip replacement procedures, offering real-time data and enhanced precision. This launch reflects Zimmer Biomet’s ongoing investment in robotic solutions for orthopedic surgery.
- In March 2023, Medtronic entered into a strategic partnership with NVIDIA to accelerate the development of AI-powered medical robotics. The collaboration focuses on leveraging NVIDIA’s advanced computing and AI capabilities to improve Medtronic’s Hugo robotic-assisted surgery system, aiming for faster, smarter surgical workflows and improved clinical outcomes.
Market Concentration & Characteristics:
The Medical Robots Market exhibits moderate to high market concentration, with a few dominant players controlling a significant share of global revenues. Intuitive Surgical leads in surgical robotics, supported by an extensive installed base and proprietary technology. It features high entry barriers due to capital intensity, regulatory compliance, and clinical validation requirements. Market participants differentiate through innovation in AI integration, multi-specialty compatibility, and compact system design. Product lifecycles extend through service contracts, software updates, and consumable sales, creating strong aftermarket dynamics. Buyers prioritize clinical outcomes, ease of use, and long-term value, which places pressure on suppliers to demonstrate continuous performance improvements. The market evolves rapidly, shaped by ongoing R&D, strategic partnerships, and growing adoption across hospitals, ambulatory centers, and rehabilitation facilities.
Report Coverage:
The research report offers an in-depth analysis based on Type, Product, Modality, Application, End-user and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising demand for minimally invasive procedures will continue to drive robotic surgery adoption across specialties.
- Integration of AI and machine learning will enhance surgical precision, autonomy, and real-time decision support.
- Expansion into emerging markets will gain momentum through localized manufacturing and cost-effective system models.
- Telepresence robotics will increase global access to expert care, especially in underserved and rural regions.
- Rehabilitation robotics will see growth due to aging populations and rising demand for post-acute care solutions.
- Compact and modular robot designs will enable deployment in outpatient and ambulatory surgical centers.
- Strategic partnerships between robotics firms and healthcare providers will accelerate clinical validation and adoption.
- Governments and insurers will develop supportive reimbursement frameworks for robotic-assisted procedures.
- Cloud connectivity and analytics will improve fleet management, performance tracking, and predictive maintenance.
- Growing emphasis on surgical training and simulation will strengthen clinician confidence and optimize patient outcomes.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Surge in Minimally Invasive Procedures
Physician and patient preference for minimally invasive surgeries is driving adoption of medical robots, as these systems enable smaller incisions, reduced trauma, and faster recovery, leading to better clinical outcomes and higher patient satisfaction.
Aging Population and Rehabilitation Needs
The growing elderly demographic is increasing demand for rehabilitation and assistive robots that support mobility, independence, and post-acute care, particularly in developed regions with rising chronic disease prevalence.
Technological Advancements in AI and Imaging
Integration of artificial intelligence, machine learning, and advanced imaging technologies into medical robots is enhancing surgical precision, real-time decision-making, and expanding the scope of complex procedures that can be performed robotically.
Healthcare Labor Shortages and Efficiency Demands
Hospitals are turning to robotic automation to address clinician shortages and improve operational efficiency, using robots for repetitive, hazardous, or logistical tasks to free up skilled staff for higher-value patient care.
Expansion of Telepresence and Remote Surgery
The development of telepresence-enabled robotic platforms is broadening access to expert surgical care in remote and underserved regions, supporting global healthcare equity and driving market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Medical Robots Market?
What factors are driving the growth of the Medical Robots Market?
What are the key segments within the Medical Robots Market?
What are some challenges faced by the Medical Robots Market?
Who are the major players in the Medical Robots Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 External Large Robots
- 1.2.2 Geriatric Robots
- 1.2.3 Assistive Robots
- 1.2.4 Miniature in Vivo Robots
- 1.3 By Product
- 1.3.1 Surgical Robots
- 1.3.2 Rehabilitation Robots
- 1.3.3 Hospital and Pharmacy Robots
- 1.3.4 Telepresence Robots
- 1.3.5 Sanitation and Disinfectant Robots
- 1.4 By End-user
- 1.4.1 Hospitals
- 1.4.2 Specialty Clinics
- 1.4.3 Ambulatory Surgical Centers
- 1.4.4 Others
- 1.5 By Application
- 1.5.1 Neurology
- 1.5.2 Cardiology
- 1.5.3 Orthopedic
- 1.5.4 Laparoscopic
- 1.5.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 11,427.1 million → 2032: USD 27,613.22 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Medical Robots Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Medical Robots Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Medical Robots Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Medical Robots Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Medical Robots Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Medical Robots Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Medical Robots Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Medical Robots Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 11,427.1 million → 2032: USD 27,613.22 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Medical Robots Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 External Large Robots
- 12.3.7.2 Geriatric Robots
- 12.3.7.3 Assistive Robots
- 12.3.7.4 Miniature in Vivo Robots
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Surgical Robots
- 12.4.7.2 Rehabilitation Robots
- 12.4.7.3 Hospital and Pharmacy Robots
- 12.4.7.4 Telepresence Robots
- 12.4.7.5 Sanitation and Disinfectant Robots
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-user - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Hospitals
- 12.5.7.2 Specialty Clinics
- 12.5.7.3 Ambulatory Surgical Centers
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Neurology
- 12.6.7.2 Cardiology
- 12.6.7.3 Orthopedic
- 12.6.7.4 Laparoscopic
- 12.6.7.5 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Medical Robots End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Medical Robots Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Medical Robots Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Medical Robots Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Intuitive Surgical
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Medtronic
- 18.4 Stryker
- 18.5 Zimmer Biomet
- 18.6 Siemens Healthineers
- 18.7 Accuray Incorporated
- 18.8 Titan Medical Inc.
- 18.9 Stereotaxis, Inc.
- 18.10 CMR Surgical
- 18.11 Asensus Surgical
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

