
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
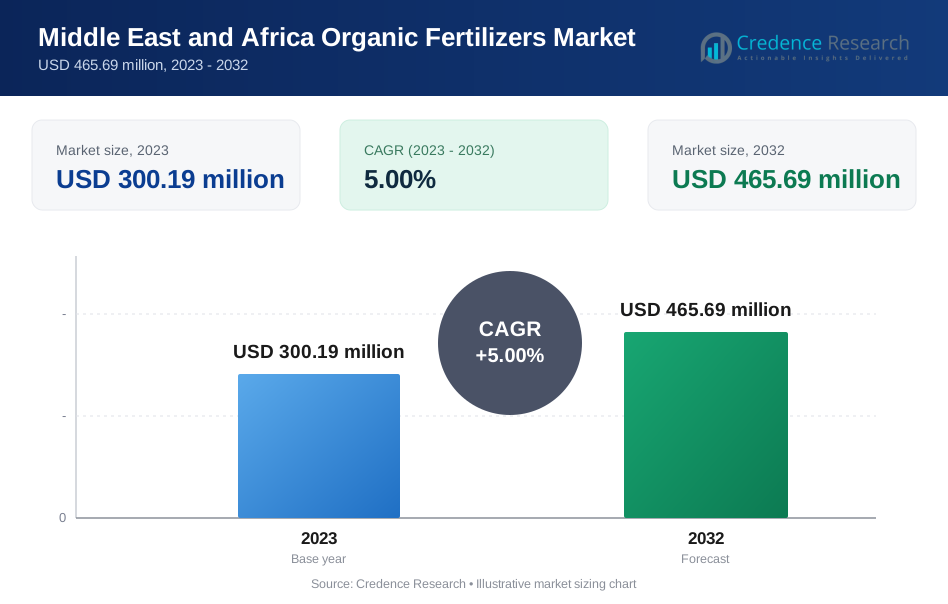
| Middle East and Africa Organic Fertilizers Market Size 2023 | USD 300.19 million |
| Middle East and Africa Organic Fertilizers Market, CAGR | 5.00% |
| Middle East and Africa Organic Fertilizers Market Size 2032 | USD 465.69 million |
Market Overview
The Middle East and Africa Organic Fertilizers Market is projected to grow from USD 300.19 million in 2023 to an estimated USD 465.69 million by 2032, with a compound annual growth rate (CAGR) of 5.00% from 2024 to 2032. This growth trajectory highlights the increasing adoption of organic farming practices in the region, driven by the rising awareness of the benefits of organic fertilizers over synthetic counterparts. Organic fertilizers, derived from natural sources such as compost, manure, and bone meal, are gaining popularity due to their environmental sustainability and ability to improve soil health. As a result, the market is experiencing substantial growth, supported by government initiatives and policies promoting organic agriculture.
Several factors drive the growth of the organic fertilizers market in the Middle East and Africa. Key among these is the increasing consumer demand for organic food products, driven by health consciousness and environmental concerns. Additionally, the detrimental effects of chemical fertilizers on soil fertility and the ecosystem have prompted a shift towards organic alternatives. Technological advancements in organic fertilizer production, including the development of more efficient and nutrient-rich formulations, are also contributing to market expansion. Moreover, the region's favorable climatic conditions for organic farming and the availability of raw materials further bolster the market's growth.
Geographically, the market analysis indicates significant growth potential across various countries in the Middle East and Africa. South Africa, Nigeria, and Kenya are emerging as key markets due to their robust agricultural sectors and growing organic farming communities. The GCC countries, particularly the UAE and Saudi Arabia, are also witnessing increased adoption of organic fertilizers, driven by government support and investment in sustainable agricultural practices. Key players in the market, such as Tata Chemicals Ltd., BioStar Organics, and Italpollina SpA, are actively expanding their presence and product offerings in the region. These companies are focusing on strategic partnerships, mergers, and acquisitions to enhance their market share and cater to the rising demand for organic fertilizers in the Middle East and Africa.
Market Drivers
Increasing Consumer Demand for Organic Food Products
The surge in consumer demand for organic food products significantly drives the Middle East and Africa organic fertilizers market. For instance, in recent years, there has been a noticeable increase in the number of farmers’ markets and organic food stores in cities like Cape Town and Dubai. Consumers are becoming increasingly aware of the health benefits associated with organic food, which is perceived to be free from synthetic chemicals and pesticides. This growing preference is evident in both urban and rural areas, where organic produce is gaining traction in local markets and retail chains. The health-conscious population seeks food that is safer, more nutritious, and environmentally friendly, which aligns with the principles of organic farming. Consequently, this demand stimulates the need for organic fertilizers, as farmers strive to meet consumer expectations and adhere to organic certification standards. The organic food market's expansion creates a ripple effect, boosting the organic fertilizers market as farmers adopt sustainable practices to cater to the rising demand.
Environmental Sustainability and Soil Health Improvement
The shift towards sustainable agricultural practices is a pivotal driver of the organic fertilizers market in the Middle East and Africa. For instance, in countries like Kenya and Ethiopia, there has been a growing trend of farmers transitioning from conventional to organic farming practices. Traditional chemical fertilizers have long been associated with adverse environmental impacts, including soil degradation, water pollution, and loss of biodiversity. In contrast, organic fertilizers offer a more sustainable solution by enhancing soil health and fertility. They improve soil structure, increase microbial activity, and promote the natural nutrient cycle, leading to long-term soil sustainability. Farmers in the region are increasingly recognizing the importance of maintaining soil health for future agricultural productivity. Organic fertilizers, derived from natural sources such as compost, manure, and plant residues, provide essential nutrients without the harmful side effects of synthetic chemicals. This shift towards environmentally friendly farming practices is gaining momentum, supported by government policies and incentives promoting organic agriculture. The focus on sustainability not only benefits the environment but also ensures the longevity and productivity of agricultural lands, driving the demand for organic fertilizers.
Technological Advancements and Innovative Product Development
Technological advancements and innovation in the production and formulation of organic fertilizers are key drivers of market growth. For instance, the development of bio-fertilizers that utilize beneficial microorganisms to improve soil fertility and plant health is an emerging trend in the region. The organic fertilizers market is witnessing significant research and development efforts aimed at improving the efficiency and effectiveness of organic fertilizers. Innovations such as the development of bio-fertilizers, microbial inoculants, and nutrient-enriched organic formulations are enhancing the nutrient availability and uptake by plants. These advancements are making organic fertilizers more competitive with synthetic alternatives, offering farmers better yield outcomes and crop quality. Additionally, the integration of technology in organic farming practices, such as precision agriculture and smart farming techniques, is further driving the adoption of organic fertilizers. These technologies enable farmers to optimize fertilizer application, reduce waste, and enhance crop productivity. The continuous evolution of organic fertilizer products, driven by technological innovation, is a significant factor propelling market growth in the Middle East and Africa.
Government Support and Regulatory Frameworks
Government support and favorable regulatory frameworks play a crucial role in driving the organic fertilizers market in the Middle East and Africa. Various governments in the region are actively promoting organic farming through policies, subsidies, and certification programs. These initiatives aim to encourage farmers to transition from conventional to organic farming practices by providing financial incentives, technical assistance, and market access for organic produce. For instance, government programs that offer subsidies for organic fertilizers and support for organic certification processes help reduce the financial burden on farmers and promote the adoption of organic fertilizers. Additionally, the establishment of regulatory frameworks and standards for organic agriculture ensures the credibility and authenticity of organic products in the market. This regulatory support fosters consumer confidence in organic produce, further driving demand. The commitment of governments to sustainable agriculture and environmental conservation is a significant driver of the organic fertilizers market, as it creates a conducive environment for the growth and development of the organic farming sector.
Market Trend
Rising Adoption of Bio-fertilizers
The Middle East and Africa organic fertilizers market is witnessing a significant shift towards bio-fertilizers. For instance, the use of Rhizobium bacteria as a bio-fertilizer to enhance nitrogen availability in legume crops is becoming increasingly common. Bio-fertilizers, which include microbial inoculants and natural growth promoters, are gaining popularity due to their ability to enhance soil fertility and plant growth sustainably. Farmers are increasingly adopting bio-fertilizers as they help improve nutrient uptake, enhance soil health, and reduce dependency on chemical inputs. This trend is supported by ongoing research and development efforts focused on creating more effective and diverse bio-fertilizer products.
Integration of Precision Agriculture
Precision agriculture is becoming a prominent trend in the region, influencing the organic fertilizers market. For instance, the use of GPS technology to map fields and apply fertilizers at precise locations is becoming more prevalent. The use of advanced technologies such as GPS, drones, and IoT-enabled devices allows farmers to optimize fertilizer application, monitor crop health, and manage resources efficiently. By integrating precision agriculture with organic farming practices, farmers can achieve higher yields and better crop quality while minimizing environmental impact. This trend is driving the demand for specialized organic fertilizers that can be precisely applied based on real-time data.
Expansion of Organic Farming Acreage
There is a noticeable increase in the acreage dedicated to organic farming in the Middle East and Africa. For instance, in countries like Egypt and Kenya, there has been a significant increase in the land area dedicated to organic farming over the past few years. As consumer demand for organic products grows, more farmers are transitioning from conventional to organic farming methods. This expansion is supported by government initiatives, subsidies, and educational programs that promote the benefits of organic agriculture. The increase in organic farming acreage directly boosts the demand for organic fertilizers, creating new opportunities for market growth.
Growing Focus on Sustainable Agriculture Practices
Sustainable agriculture practices are gaining momentum in the region, driven by environmental concerns and the need for long-term agricultural productivity. For instance, the practice of crop rotation to maintain soil health and prevent pest infestations is becoming more common among farmers in the region. Farmers are adopting crop rotation, intercropping, and the use of cover crops to maintain soil health and biodiversity. Organic fertilizers, which are integral to these practices, are increasingly being used to enhance soil fertility and structure. The growing emphasis on sustainability is propelling the demand for organic fertilizers that support these environmentally friendly farming methods.
Increased Investment in Research and Development
Investment in research and development (R&D) is on the rise, leading to the introduction of innovative organic fertilizer products. Companies and research institutions are focusing on developing fertilizers that are more efficient, nutrient-rich, and tailored to specific crop needs. Innovations such as slow-release organic fertilizers, liquid organic fertilizers, and fortified composts are gaining traction in the market. This trend reflects the ongoing efforts to improve the performance and competitiveness of organic fertilizers compared to synthetic alternatives.
Collaborations and Strategic Partnerships
Collaborations and strategic partnerships among key market players are becoming more prevalent. Companies are forming alliances to leverage each other’s strengths, expand their product portfolios, and enter new markets. These collaborations often involve joint R&D projects, distribution agreements, and knowledge-sharing initiatives. By working together, companies can accelerate the development and commercialization of advanced organic fertilizers, thereby driving market growth.
Government Initiatives and Policy Support
Governments across the Middle East and Africa are playing a crucial role in promoting the use of organic fertilizers through various initiatives and policies. Subsidies for organic farming inputs, training programs for farmers, and the establishment of organic certification standards are some of the measures being implemented. These initiatives are aimed at encouraging farmers to adopt organic fertilizers and sustainable farming practices, thereby enhancing agricultural productivity and environmental sustainability. The supportive policy environment is a key trend driving the organic fertilizers market in the region.
Market Restraints and Challenges
Limited Awareness and Knowledge Among Farmers
A significant restraint in the Middle East and Africa organic fertilizers market is the limited awareness and knowledge among farmers regarding the benefits and application of organic fertilizers. Many farmers in the region are accustomed to conventional farming practices and may be hesitant to transition to organic methods due to a lack of information and training. This knowledge gap hinders the widespread adoption of organic fertilizers, as farmers may not fully understand how to effectively use these products or appreciate their long-term benefits for soil health and sustainability. Overcoming this challenge requires extensive educational and training programs to enlighten farmers on the advantages and techniques of organic farming.
High Cost of Organic Fertilizers
The relatively high cost of organic fertilizers compared to synthetic alternatives poses a significant challenge for market growth. Organic fertilizers often involve more complex production processes and raw material sourcing, leading to higher prices. For many small-scale and subsistence farmers in the region, the cost of organic fertilizers can be prohibitive, limiting their ability to adopt these products. Financial constraints and limited access to credit further exacerbate this issue, making it difficult for farmers to invest in organic inputs. Addressing this challenge requires innovative financing solutions and subsidies to make organic fertilizers more affordable and accessible to a broader range of farmers.
Inconsistent Quality and Availability
The inconsistent quality and availability of organic fertilizers in the market is another critical restraint. Due to the fragmented nature of the organic fertilizer industry in the Middle East and Africa, there are variations in product quality, which can affect the effectiveness of these fertilizers. Inadequate regulation and quality control measures contribute to this inconsistency, leading to a lack of trust among farmers. Moreover, the sporadic availability of organic fertilizers, especially in remote and rural areas, hampers their adoption. Ensuring consistent quality and reliable supply chains for organic fertilizers is essential to build farmer confidence and support market growth
Challenges in Certification and Market Access
Organic certification and market access present significant challenges for the organic fertilizers market. The certification process for organic farming is often complex, time-consuming, and costly, deterring many farmers from seeking organic certification. Additionally, the lack of harmonized standards and regulations across different countries in the region complicates the certification process and limits the marketability of organic products. Farmers also face difficulties in accessing lucrative markets for organic produce due to inadequate infrastructure, limited market linkages, and competition from conventionally grown products. Streamlining certification processes and improving market access for organic products are crucial to overcoming these barriers and fostering market growth.
Climatic and Environmental Challenges
The Middle East and Africa face unique climatic and environmental challenges that impact the adoption of organic fertilizers. The region's arid and semi-arid conditions, water scarcity, and soil degradation pose significant obstacles to organic farming. Organic fertilizers require specific environmental conditions to be effective, and extreme weather events such as droughts and floods can disrupt their application and efficacy. Developing organic fertilizers that are resilient to these climatic challenges and promoting sustainable water management practices are essential to address this restraint.
Market Segmentation Analysis
By Source
Plant-based organic fertilizers, derived from compost, green manure, and plant residues, are gaining popularity due to their high nutrient content and ability to enhance soil structure and microbial activity, leading to improved soil fertility and crop productivity. Animal-based fertilizers, including manure, bone meal, and blood meal, are favored for their rich nitrogen content and essential nutrients that enhance soil organic matter and water retention capabilities. Mineral-based organic fertilizers, such as rock phosphate and gypsum, provide crucial trace minerals for plant growth and help correct soil deficiencies, often used alongside other organic fertilizers to achieve balanced nutrient profiles.
By Crop Type
The application of organic fertilizers spans various crop types, each benefiting uniquely from their use. In cereals and grains like wheat, maize, and rice, organic fertilizers enhance nutrient availability and support long-term soil fertility, ensuring sustainable crop yields. Oilseeds and pulses, including soybeans, sunflower, and lentils, see improved crop quality and yield due to the essential nutrients provided by organic fertilizers, leading to healthier and more productive plants. The fruits and vegetables segment, encompassing tomatoes, cucumbers, and citrus fruits, relies heavily on organic fertilizers for producing high-quality, nutrient-rich produce by enhancing soil fertility and supporting healthy plant growth. Additionally, other crops such as herbs, spices, and ornamentals benefit from organic fertilizers, driven by the demand for high-quality produce and sustainable farming practices.
By Nutrition Content
Organic fertilizers with up to 60% organic matter are highly effective in improving soil structure and fertility, making them suitable for a wide range of crops. Those containing 40% to 60% organic content provide a moderate nutrient supply, enhancing soil health and nutrient availability, and are often combined with other fertilizers to meet specific crop needs. Fertilizers with 20% to 40% organic content are used to address particular nutrient deficiencies and improve soil conditions, offering moderate organic enrichment in targeted applications.
By Form
Dry organic fertilizers, including pellets, powders, and granules, are popular due to their ease of application and long-lasting effects, making them suitable for both large-scale and small-scale farming operations to enhance soil fertility and ensure sustained nutrient release. Liquid organic fertilizers, on the other hand, are preferred for their rapid nutrient delivery and compatibility with modern irrigation systems, effectively addressing immediate nutrient deficiencies, and are widely utilized in horticulture and intensive farming practices.
Segments
Based on Source
- Plant-Based Organic Fertilizers
- Animal-Based Organic Fertilizers
- Mineral-Based Organic Fertilizers
Based on Crop Type
- Cereals and Grains
- Oilseeds and Pulses
- Fruits and Vegetables
- Others
Based on Nutrition Content
- Presence of Organic Substance up to 60%
- Presence of Organic Substance from 40% to 60%
- Presence of Organic Substance from 20% to 40%
Based on Form
- Dry Organic Fertilizers
- Liquid Organic Fertilizers
Regional Analysis
Gulf Cooperation Council (GCC) Countries (25%):
The GCC countries, including Saudi Arabia, the United Arab Emirates, Qatar, Kuwait, Oman, and Bahrain, collectively account for approximately 25% of the Middle East and Africa organic fertilizers market. This region's market growth is primarily driven by strong government support for sustainable agriculture and significant investments in organic farming initiatives. The UAE and Saudi Arabia are at the forefront, implementing policies to reduce dependency on food imports and enhance local agricultural productivity through organic farming. The availability of financial incentives, subsidies for organic fertilizers, and efforts to establish a sustainable food supply chain contribute to the market's expansion in the GCC.
North Africa (30%):
North Africa, comprising countries such as Egypt, Morocco, Algeria, and Tunisia, holds around 30% of the regional market share. This region benefits from a long-standing tradition of agriculture and a growing shift towards organic farming practices. Morocco and Egypt are key contributors, with significant government initiatives promoting organic agriculture and the adoption of sustainable farming practices. The region's favorable climatic conditions, coupled with increasing consumer awareness of the health benefits of organic products, drive the demand for organic fertilizers. Additionally, North Africa's strategic position as a bridge between Europe and Africa facilitates access to larger markets, further boosting the organic fertilizers market.
Key players
- Gavilon South Africa (MacroSource, LLC)
- Golden Fertilizer Company Limited
- ICL Group Ltd
- K+S Aktiengesellschaft
- Kynoch Fertilizer
- SABIC Agri-Nutrients Co.
- Safsulphur
- Unikeyterra Chemical
- Yara International ASA
Competitive Analysis
The Middle East and Africa organic fertilizers market is highly competitive, with several key players striving to expand their market share through strategic initiatives. Gavilon South Africa (MacroSource, LLC) and Golden Fertilizer Company Limited leverage their strong regional presence and extensive distribution networks to reach a broad customer base. ICL Group Ltd and K+S Aktiengesellschaft emphasize innovative product development and sustainability to differentiate themselves in the market. Kynoch Fertilizer and SABIC Agri-Nutrients Co. focus on enhancing their product portfolios and investing in R&D to meet diverse agricultural needs. Safsulphur and Unikeyterra Chemical capitalize on their specialized products to cater to specific market segments. Yara International ASA, a global leader, utilizes its extensive resources and advanced technologies to maintain a competitive edge. These companies compete on factors such as product quality, innovation, and strategic partnerships, driving the market's dynamic growth.
Recent Developments
In April 2023, SABIC Agri-Nutrients Company acquired a 49% stake in ETC Group (ETG) through a transaction valued at USD 320 million. This acquisition includes ETG Inputs Holdco Limited and aligns with SABIC's strategic goal of integrating the agri-nutrients value chain and enhancing distribution capabilities. By securing this significant stake, SABIC aims to bolster its market presence and improve its overall supply chain efficiency, ensuring a more robust and streamlined approach to meeting the demands of the agri-nutrients market.
In April 2023, K+S acquired a 75% share in the fertilizer business of South African trading company Industrial Commodities Holdings (Pty) Ltd (ICH). This strategic acquisition is intended to expand K+S's core business while strengthening its presence in southern and eastern Africa. The newly acquired business will operate as a joint venture named FertivPty Ltd. This move underscores K+S's commitment to growing its operations in key African markets and enhancing its capabilities in the region’s agricultural sector.
In January 2023, ICL entered a strategic partnership with General Mills to supply specialty phosphate solutions. This long-term agreement will not only position ICL as a key supplier but also focus on supporting General Mills' international expansion efforts. The collaboration highlights ICL's expertise in specialty phosphates and reinforces its role in providing high-quality solutions to prominent global food companies, thereby strengthening its market position and fostering global growth.
In September 2022, Agri Digitale highlighted the theme "Agriculture in Africa and surge in fertilizer prices" during an international webinar held in July 2022. The discussion aimed to promote and accelerate the local production of organic fertilizers across African states. By addressing the challenges of rising fertilizer prices and advocating for increased local production, Agri Digitale seeks to enhance agricultural sustainability and food security in Africa, fostering greater self-reliance and resilience in the continent's agricultural sector.
Market Concentration and Characteristics
The Middle East and Africa organic fertilizers market is characterized by moderate market concentration, with a mix of established global players and numerous regional and local manufacturers. Key characteristics of this market include a strong emphasis on sustainability, innovation in organic fertilizer formulations, and the adoption of advanced agricultural practices. The market is driven by increasing consumer demand for organic food, government initiatives promoting organic farming, and the environmental benefits of organic fertilizers. Despite challenges such as high costs and inconsistent product quality, the market is poised for growth, supported by ongoing technological advancements and strategic collaborations among industry players.
Report Coverage
The research report offers an in-depth analysis based on Source, Crop Type, Nutrition Content and Form. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The adoption of organic farming practices is expected to rise, driven by growing consumer demand for organic produce and government support for sustainable agriculture.
- Ongoing technological advancements in organic fertilizer formulations and precision agriculture will enhance the efficiency and effectiveness of organic fertilizers, promoting wider adoption.
- The acreage dedicated to organic farming is anticipated to expand, supported by favorable climatic conditions and the increasing profitability of organic crops.
- Governments in the region are likely to introduce more initiatives and subsidies to promote organic farming, further boosting the demand for organic fertilizers.
- Local production capabilities for organic fertilizers are expected to improve, reducing reliance on imports and ensuring consistent supply to meet growing demand.
- Investment in research and development will continue to grow, leading to the introduction of innovative organic fertilizer products tailored to specific regional needs.
- Enhanced regulatory frameworks and certification standards will ensure the quality and authenticity of organic fertilizers, fostering consumer trust and market growth.
- Increased awareness and education programs for farmers about the benefits and application of organic fertilizers will drive market penetration and adoption rates.
- Strategic collaborations and partnerships among key players will facilitate knowledge sharing, innovation, and market expansion, strengthening the overall market landscape.
- The development of climate-resilient organic fertilizers will address regional climatic challenges, ensuring sustainable agricultural practices and improved crop yields.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Middle East and Africa organic fertilizers market?
What factors are driving the growth of the organic fertilizers market in this region?
Which countries are key markets for organic fertilizers in the Middle East and Africa?
What are the main types of organic fertilizers used in this market?
How are technological advancements influencing the organic fertilizers market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Middle East and Africa Organic Fertilizers Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Middle East and Africa Organic Fertilizers Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 300.19 million → 2032: USD 465.69 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Middle East and Africa Organic Fertilizers Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Middle East and Africa Organic Fertilizers Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Middle East and Africa Organic Fertilizers Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Middle East and Africa Organic Fertilizers Market Drivers
- 3.3 Middle East and Africa Organic Fertilizers Market Restraints & Challenges
- 3.4 Middle East and Africa Organic Fertilizers Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Middle East and Africa Organic Fertilizers Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Middle East and Africa Organic Fertilizers Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Middle East and Africa Organic Fertilizers category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Middle East and Africa Organic Fertilizers Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Middle East and Africa Organic Fertilizers Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Middle East and Africa Organic Fertilizers market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Middle East and Africa Organic Fertilizers Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Middle East and Africa Organic Fertilizers Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Middle East and Africa Organic Fertilizers Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Middle East and Africa Organic Fertilizers (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Middle East and Africa Organic Fertilizers Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Middle East and Africa Organic Fertilizers Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Middle East and Africa Organic Fertilizers Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Middle East and Africa Organic Fertilizers Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Middle East and Africa Organic Fertilizers Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Middle East and Africa Organic Fertilizers Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Middle East and Africa Organic Fertilizers Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Middle East and Africa Organic Fertilizers Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Middle East and Africa Organic Fertilizers Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
