
Market Overview
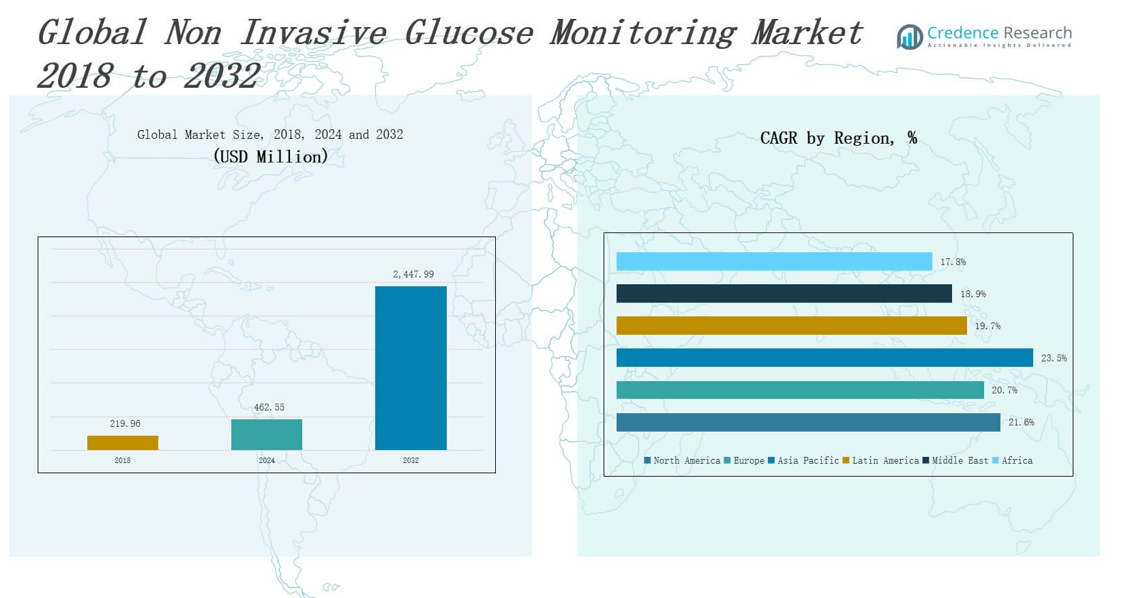
The Non Invasive Glucose Monitoring Market size was valued at USD 219.96 million in 2018 to USD 462.55 million in 2024 and is anticipated to reach USD 2,447.99 million by 2032, at a CAGR of 21.60% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Non Invasive Glucose Monitoring Market Size 2024 | USD 462.55 million |
| Non Invasive Glucose Monitoring Market CAGR | 21.60% |
| Non Invasive Glucose Monitoring Market Size 2032 | USD 2,447.99 million |
The Non-Invasive Glucose Monitoring Market is driven by the growing prevalence of diabetes, increasing demand for painless glucose monitoring, and rising awareness of continuous health tracking. Technological advancements in biosensors, wearable devices, and optical sensing techniques are accelerating product development and adoption. Trends include the integration of AI and IoT for real-time data analytics, expansion of remote patient monitoring solutions, and a shift toward user-friendly, smartphone-compatible devices. Supportive regulatory initiatives and investments in digital health further enhance market growth, while consumer preference for non-invasive, convenient, and cost-effective alternatives to traditional blood-based methods continues to rise.
The Non Invasive Glucose Monitoring Market spans key regions including North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa. North America leads in adoption, while Asia Pacific shows the fastest growth. Europe maintains strong healthcare integration, and Latin America, the Middle East, and Africa present emerging opportunities. Leading companies include Abbott Laboratories, Dexcom, Medtronic, Apple Inc., Fitbit (Google), Hoffmann-La Roche, DiaMonTech, Know Labs, Sanofi, DarioHealth, PHC Holdings, and WellDoc. It reflects a competitive landscape shaped by innovation, partnerships, and regional healthcare advancements.
Market Insights
- The Non Invasive Glucose Monitoring Market was valued at USD 219.96 million in 2018, reached USD 462.55 million in 2024, and is projected to hit USD 2,447.99 million by 2032, growing at a CAGR of 21.60%.
- Rising global diabetes prevalence and demand for painless, real-time monitoring are key drivers boosting adoption of non-invasive solutions.
- Technological advancements in biosensors, optical sensing, and AI integration are transforming wearable devices into smart, user-friendly tools.
- North America leads the market with strong infrastructure, early tech adoption, and favorable reimbursement; Asia Pacific records the fastest growth.
- Regulatory support, government health digitization programs, and investment in preventive care enhance global market expansion.
- Major players include Abbott, Dexcom, Apple, Medtronic, Sanofi, Roche, Know Labs, and DiaMonTech, shaping the competitive landscape with innovation and partnerships.
- Challenges include accuracy limitations across diverse populations, high development costs, and complex regulatory frameworks, especially for new entrants.
Market Drivers
Rising Diabetes Prevalence and Demand for Painless Monitoring
The Non Invasive Glucose Monitoring Market benefits significantly from the global rise in diabetes cases. With millions of individuals seeking alternatives to painful finger-prick testing, demand for non-invasive solutions is surging. The growing burden of type 1 and type 2 diabetes across all age groups reinforces the urgency for comfortable, real-time monitoring tools. It enables users to track glucose levels frequently without blood sampling. This improves compliance and enhances disease management. The increasing focus on preventive care also fuels the market’s momentum.
- For instance, the Simplera system, approved by FDA, CE, and TGA in early 2025, pairs a compact glucose sensor with a mobile app for six-day continuous monitoring, representing an accessible non-invasive adjunct device for diabetes management.
Technological Advancements in Sensor and Optical Systems
Continuous innovation in biosensors, spectroscopy, and wearable electronics strengthens the Non Invasive Glucose Monitoring Market. Emerging technologies such as Raman spectroscopy, near-infrared (NIR) sensing, and electromagnetic wave-based systems offer accurate glucose detection without penetrating the skin. It supports the development of compact, user-friendly devices with real-time analytics capabilities. These innovations improve accuracy, reliability, and convenience, attracting investment from medtech firms. Research institutions and startups are also expanding the technology pipeline. The evolving technology landscape ensures sustained product innovation.
- For instance, Rockley Photonics announced in its 2023 white paper that its infrared spectroscopy-based biosensing platform can monitor glucose trends through a compact wristband device.
Integration with Smart Health Ecosystems
The Non Invasive Glucose Monitoring Market gains traction from the integration of glucose monitoring with digital health ecosystems. Smartwatches, smartphones, and health apps now support synchronized data exchange and patient-specific alerts. It enhances decision-making for users and healthcare providers alike. The growing adoption of AI-powered analytics and cloud-based platforms enables predictive insights and trend analysis. Remote monitoring solutions become more viable and scalable. This digital integration improves patient engagement and long-term disease control.
Government Support and Regulatory Advancements
Government initiatives promoting early diabetes detection and digital health accelerate the Non Invasive Glucose Monitoring Market. Policies supporting non-invasive diagnostic tools improve funding and streamline regulatory pathways. It encourages manufacturers to invest in clinical trials and commercialization efforts. Favorable reimbursement structures and healthcare subsidies further stimulate adoption. International health agencies emphasize glucose control to reduce complications. Regulatory bodies are gradually adapting frameworks to accommodate new non-invasive technologies, improving market entry timelines.
Market Trends
Growing Adoption of Wearable and User-Centric Monitoring Devices
The Non Invasive Glucose Monitoring Market is witnessing a shift toward wearable, skin-friendly, and easy-to-use devices. Smartwatches, skin patches, and optical sensors embedded in fitness bands are becoming common. These innovations offer continuous monitoring without disrupting the user’s routine. It enables users to stay informed about their glucose trends in real time. Market players focus on comfort, battery life, and seamless integration with smartphones. This trend aligns with increasing consumer expectations for health and lifestyle convergence.
- For instance, Nemaura Medical's SugarBEAT is a skin patch that noninvasively measures glucose by drawing interstitial fluid through the skin using a low-level electric current, offering a convenient alternative for type 1, type 2, and pre-diabetes patients.
Integration of AI and Predictive Analytics for Personalized Insights
Artificial intelligence and machine learning play a growing role in the Non Invasive Glucose Monitoring Market. AI-powered algorithms can analyze trends, detect anomalies, and deliver personalized alerts. It supports better clinical decision-making and user engagement. Companies are embedding predictive analytics into cloud-based platforms for physicians and patients. This trend enhances patient self-management and improves long-term glycemic control. AI integration also strengthens product differentiation and improves patient satisfaction in a competitive landscape.
- For instance, Medtronic incorporates predictive analytics in its cloud-based ecosystem to enable continuous remote monitoring and personalized alerts for glycemic excursions, enhancing patient self-management and adherence.
Advancement in Optical and Spectroscopy-Based Sensing Technologies
Rapid progress in optical detection methods is shaping innovation across the Non Invasive Glucose Monitoring Market. Raman spectroscopy, fluorescence, and near-infrared techniques are enhancing measurement accuracy and device sensitivity. It allows precise glucose analysis through skin without invasive methods. These systems are now being miniaturized for consumer-grade applications. Startups and research institutions are refining algorithms for real-time calibration. The focus remains on reducing noise, improving signal strength, and ensuring consistent performance across diverse skin types.
Rising Strategic Collaborations and Digital Health Partnerships
Key players in the Non Invasive Glucose Monitoring Market are forming alliances with tech companies and healthcare providers. Strategic partnerships help accelerate R&D, regulatory approvals, and product commercialization. It facilitates integration with telehealth platforms and electronic health records. Joint ventures enable access to advanced sensor technologies and digital infrastructure. Global medtech firms seek to co-develop AI-enhanced solutions and wearable ecosystems. These collaborations are driving faster product rollouts and broader market penetration.
Market Challenges Analysis
Accuracy Limitations and Technological Constraints
The Non Invasive Glucose Monitoring Market faces challenges in achieving clinically reliable accuracy across diverse populations. Factors such as skin type, hydration levels, and external temperature can affect sensor performance. It becomes difficult to ensure consistency in glucose readings compared to traditional invasive methods. Despite progress, many non-invasive devices still face scrutiny from regulatory bodies due to variability in results. Manufacturers must overcome these barriers through rigorous clinical validation and advanced calibration techniques. Ensuring real-time, reproducible accuracy remains a critical hurdle.
Regulatory Complexities and High Development Costs
Bringing non-invasive glucose monitoring products to market involves navigating complex regulatory frameworks. Approval processes require extensive clinical data to demonstrate safety, precision, and long-term reliability. It often leads to delays in product launches and increases operational costs. High R&D investment, combined with uncertain reimbursement policies, limits participation by smaller firms. Market entrants must balance innovation with compliance and financial viability. These regulatory and cost-related pressures can slow widespread adoption and limit market competitiveness.
Market Opportunities
Expanding Demand in Emerging Economies and Home Healthcare
The Non Invasive Glucose Monitoring Market holds significant potential in emerging economies with rising diabetes prevalence and limited access to clinical diagnostics. Countries in Asia-Pacific, Latin America, and the Middle East are experiencing increased demand for affordable, user-friendly health technologies. It provides an opportunity to deploy compact, non-invasive devices tailored for remote and underserved populations. Growth in home healthcare and self-monitoring further strengthens this opportunity. Local manufacturing and government-backed health programs can accelerate regional adoption. Companies that offer cost-effective and scalable solutions stand to benefit the most.
Innovation in Multi-Parameter Health Monitoring Platforms
There is a growing opportunity to integrate glucose monitoring with broader digital health platforms offering multi-parameter tracking. Consumers seek all-in-one devices that monitor glucose, heart rate, blood pressure, and physical activity. The Non Invasive Glucose Monitoring Market can tap into this demand by collaborating with wearable tech and software developers. It opens pathways for subscription models, personalized wellness solutions, and real-time physician connectivity. This convergence supports preventive care and chronic disease management. Offering integrated, data-rich ecosystems will create long-term competitive advantages.
Market Segmentation Analysis:
By Device Type
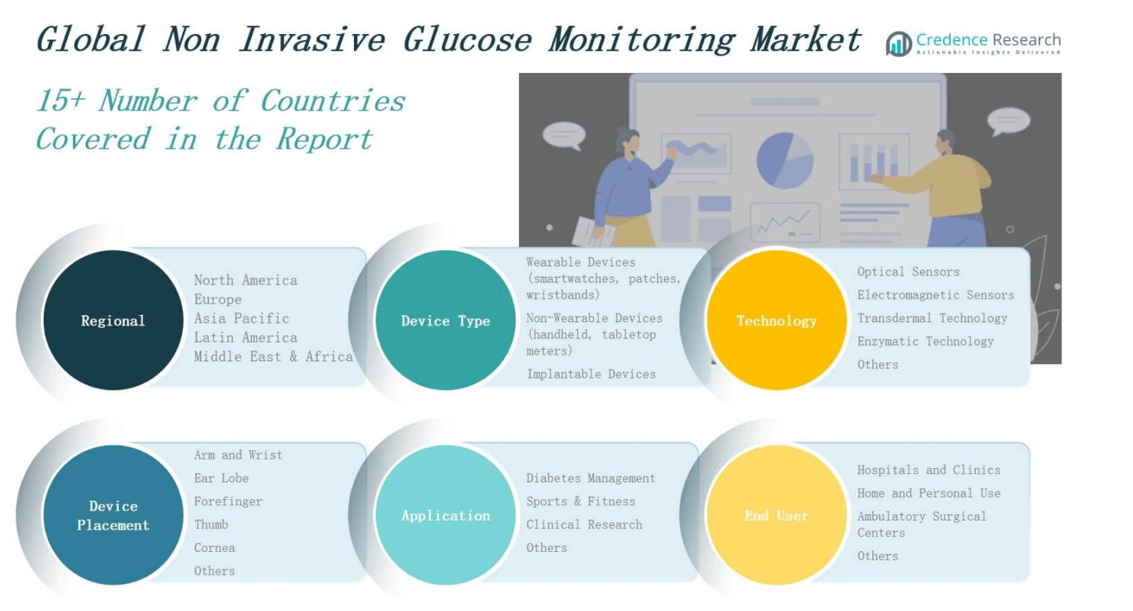
The Non Invasive Glucose Monitoring Market is segmented into wearable, non-wearable, and implantable devices. Wearable devices, such as smartwatches, patches, and wristbands, dominate the market due to their comfort, portability, and integration with mobile health apps. Non-wearable devices, including handheld and tabletop meters, are used in clinical and home settings but are gradually losing preference to compact alternatives. Implantable devices are emerging with continuous sensing capability and minimal maintenance. It reflects a trend toward continuous, passive glucose tracking.
- For instance, Senseonics’ Eversense implantable sensor lasts up to three months under the skin, providing real-time glucose monitoring via a polymer that fluoresces according to glucose levels, and it has FDA approval for use in the U.S.
By Technology
Based on technology, the Non Invasive Glucose Monitoring Market includes optical sensors, electromagnetic sensors, transdermal technology, enzymatic technology, and others. Optical sensors lead due to their accuracy and integration in wearables using near-infrared or Raman spectroscopy. Electromagnetic sensors offer contactless monitoring but face limitations in signal interference. Transdermal technology uses chemical markers through skin diffusion, appealing for its non-contact approach. Enzymatic methods, while precise, are less adopted due to invasive tendencies. It highlights innovation efforts to balance precision with comfort.
- For instance, DiaMonTech employs molecular spectroscopy to detect glucose noninvasively through the skin with devices including a fingertip reader and smartwatch sensor, showing accuracy comparable to Abbott's FreeStyle Libre in clinical research.
By Device Placement
The Non Invasive Glucose Monitoring Market categorizes device placement into arm and wrist, ear lobe, forefinger, thumb, cornea, and others. Arm and wrist placements lead due to compatibility with smartwatches and patches, providing ease of use and consistent readings. Devices placed on the ear lobe and cornea are under development but raise concerns related to comfort and sensitivity. It demonstrates user preference for accessible and unobtrusive placement that supports everyday wear. Placement flexibility remains key for adoption and user compliance.
Segments
Based on Device Type:
- Wearable Devices (smartwatches, patches, wristbands)
- Non-Wearable Devices (handheld, tabletop meters)
- Implantable Devices
Based on Technology:
- Optical Sensors
- Electromagnetic Sensors
- Transdermal Technology
- Enzymatic Technology
- Others
Based on Device Placement:
- Arm and Wrist
- Ear Lobe
- Forefinger
- Thumb
- Cornea
- Others
Based on Application:
- Diabetes Management
- Sports & Fitness
- Clinical Research
- Others
Based on End User
- Hospitals and Clinics
- Home and Personal Use
- Ambulatory Surgical Centers
- Others
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
The North America Non Invasive Glucose Monitoring Market size was valued at USD 94.85 million in 2018 to USD 197.37 million in 2024 and is anticipated to reach USD 1,047.48 million by 2032, at a CAGR of 21.6% during the forecast period. North America holds the largest market share, driven by a high prevalence of diabetes, strong healthcare infrastructure, and favorable reimbursement policies. The U.S. leads regional growth with robust R&D investments and regulatory support for digital health devices. It benefits from early adoption of wearable glucose monitoring technologies and a mature consumer base. Key market players operate extensive clinical trial networks and distribution systems in the region. Demand for non-invasive, real-time tracking is growing in home healthcare and outpatient settings.
Europe
The Europe Non Invasive Glucose Monitoring Market size was valued at USD 62.96 million in 2018 to USD 127.66 million in 2024 and is anticipated to reach USD 636.48 million by 2032, at a CAGR of 20.7% during the forecast period. Europe holds a significant share due to supportive government initiatives and strong public awareness of diabetes management. Germany, the UK, and France drive regional demand through advanced healthcare systems and increasing adoption of digital therapeutics. It shows steady growth in wearable device usage and clinical integration. Regulatory bodies in Europe encourage the development of non-invasive diagnostics through innovation funding and clear approval pathways. The region supports continuous monitoring adoption in elderly care and chronic disease programs.
Asia Pacific
The Asia Pacific Non Invasive Glucose Monitoring Market size was valued at USD 42.70 million in 2018 to USD 97.25 million in 2024 and is anticipated to reach USD 582.36 million by 2032, at a CAGR of 23.5% during the forecast period. Asia Pacific is the fastest-growing region, driven by large diabetic populations, rising disposable incomes, and rapid urbanization. China, India, and Japan are leading contributors with growing health tech investments. It benefits from increasing smartphone penetration and digital health awareness among younger demographics. Governments are expanding access to wearable diagnostics through public health schemes. Local manufacturing and technology partnerships support affordability and scalability across emerging markets.
Latin America
The Latin America Non Invasive Glucose Monitoring Market size was valued at USD 10.39 million in 2018 to USD 21.58 million in 2024 and is anticipated to reach USD 101.07 million by 2032, at a CAGR of 19.7% during the forecast period. Latin America is experiencing steady growth supported by increasing diabetes prevalence and gradual improvement in healthcare infrastructure. Brazil and Mexico account for the majority of the regional market. It gains momentum from rising awareness campaigns and collaborations between local clinics and medtech firms. Economic development is improving access to personal health devices in urban centers. Cross-border investments and mobile health applications are expanding adoption across middle-income populations.
Middle East
The Middle East Non Invasive Glucose Monitoring Market size was valued at USD 5.97 million in 2018 to USD 11.43 million in 2024 and is anticipated to reach USD 50.71 million by 2032, at a CAGR of 18.9% during the forecast period. The Middle East market is expanding due to increasing lifestyle-related diabetes cases and high demand for preventive healthcare. Gulf Cooperation Council (GCC) countries lead the adoption of digital monitoring devices. It benefits from government-backed healthcare digitization programs and rising consumer interest in wellness technologies. Hospitals and specialty clinics across the region are incorporating non-invasive solutions into chronic disease management protocols. Strategic partnerships with global tech firms are also supporting innovation and access.
Africa
The Africa Non Invasive Glucose Monitoring Market size was valued at USD 3.09 million in 2018 to USD 7.25 million in 2024 and is anticipated to reach USD 29.88 million by 2032, at a CAGR of 17.8% during the forecast period. Africa represents an emerging opportunity as diabetes rates increase across urban and semi-urban populations. South Africa leads regional adoption, supported by growing private healthcare infrastructure and NGO health initiatives. It faces challenges in affordability and distribution but benefits from rising awareness and mobile health expansion. Pilot programs are deploying wearable solutions for remote and rural monitoring. Local innovation and donor-funded programs will shape long-term growth in the region.
Key Player Analysis
- Know Labs
- Dexcom, Inc.
- DarioHealth Corp.
- Fitbit (Google)
- Sanofi
- Medtronic plc
- WellDoc Inc.
- Hoffmann-La Roche Ltd.
- PHC Holdings Corporation
- DiaMonTech GmbH
- Apple Inc.
- Abbott Laboratories
Competitive Analysis
The Non Invasive Glucose Monitoring Market features intense competition driven by rapid technological innovation and rising consumer demand. Major players such as Abbott Laboratories, Dexcom, Medtronic, and Apple focus on expanding their wearable portfolios and integrating AI for real-time analytics. Startups like DiaMonTech and Know Labs are disrupting the space with novel sensing technologies. It reflects a strong emphasis on accuracy, ease of use, and continuous monitoring. Companies invest in clinical trials, strategic partnerships, and regulatory approvals to strengthen market position. The market also sees increased collaboration between tech firms and healthcare providers to enhance device functionality and user experience. Competitive advantage depends on miniaturization, battery efficiency, and seamless app connectivity. With growing emphasis on home healthcare, firms aim to differentiate through personalized, data-driven solutions. The Non Invasive Glucose Monitoring Market continues to evolve with a dynamic mix of established medtech leaders and agile innovators targeting global adoption.
Recent Developments
- On April 24, 2025, Medtronic submitted an FDA application for an interoperable continuous glucose monitor supplied by Abbott, aimed at integration with its automated insulin pump systems.
- On April 29, 2025, Sequel Med Tech and Senseonics revealed details for developing an automated insulin delivery system featuring one-year continuous glucose monitoring capacity.
- On November 19, 2024, Dexcomannounced a $75 million strategic partnership with ŌURAto integrate its glucose sensing technology with smart rings, aiming for a 2025 launch.
- On April 29, 2025, Abbott partnered with Epic Systems to integrate FreeStyle Libre CGM data into Epic’s electronic health records, enabling real-time glucose insights for healthcare providers.
Market Concentration & Characteristics
The Non Invasive Glucose Monitoring Market exhibits moderate to high market concentration, with a few global players holding significant revenue shares due to strong technological capabilities and established distribution networks. Companies such as Abbott, Dexcom, Medtronic, and Apple dominate with advanced wearable technologies and integrated digital health solutions. It features a mix of established medtech firms and emerging innovators introducing novel sensing platforms. The market is characterized by high R&D intensity, regulatory scrutiny, and rapid product innovation cycles. Strategic partnerships, intellectual property strength, and clinical validation remain key differentiators. It reflects strong demand for user-friendly, non-invasive, and connected monitoring systems, especially in homecare and outpatient settings. Market dynamics favor companies that can balance accuracy, usability, and affordability. While North America and Europe remain innovation hubs, Asia Pacific’s fast growth rate creates opportunities for local manufacturing and scalable solutions. The market continues to evolve, driven by personalization, preventive care trends, and real-time data integration.
Report Coverage
The research report offers an in-depth analysis based on Device Type, Technology, Device Placemnet, Application, End-Use and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for non-invasive glucose monitoring devices will rise due to increasing global diabetes cases.
- Wearable technologies will dominate product development with improved accuracy and comfort.
- Integration with smartphones and cloud-based health platforms will enhance real-time monitoring.
- AI and predictive analytics will support personalized glucose trend analysis and alerts.
- Regulatory approvals will become more streamlined as clinical evidence strengthens.
- Home healthcare adoption will accelerate, especially in aging populations.
- Asia Pacific will emerge as a key manufacturing and adoption hub.
- Strategic partnerships between medtech firms and digital health companies will expand.
- Pricing pressure will increase the focus on affordability and scalable solutions.
- Innovation in multi-parameter health devices will drive competition and differentiation.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Diabetes Prevalence and Demand for Painless Monitoring
The global increase in diabetes cases is fueling demand for non-invasive glucose monitoring solutions, as patients seek alternatives to traditional finger-prick methods. This shift improves compliance and disease management by enabling frequent, comfortable monitoring.
Technological Advancements in Biosensors and Optical Sensing
Continuous innovation in biosensors, spectroscopy, and wearable electronics is enhancing the accuracy, reliability, and convenience of non-invasive glucose monitoring devices. These advancements attract investment and accelerate product development and adoption.
Integration with Digital Health Ecosystems
The ability to sync glucose monitoring devices with smartphones, smartwatches, and cloud-based health platforms is driving market growth. This integration enables real-time analytics, personalized alerts, and remote patient monitoring, improving user engagement and clinical outcomes.
Supportive Regulatory Initiatives and Government Health Programs
Government policies promoting early diabetes detection and digital health, along with streamlined regulatory pathways and favorable reimbursement structures, are encouraging manufacturers to invest in non-invasive technologies and expand market reach.
Expansion of Home Healthcare and Preventive Care
The trend toward home-based health management and preventive care is increasing demand for user-friendly, non-invasive glucose monitoring devices. This is especially significant in aging populations and regions with limited access to clinical diagnostics.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Non Invasive Glucose Monitoring Market?
What are the key segments within the Non Invasive Glucose Monitoring Market?
What are some challenges faced by the Non Invasive Glucose Monitoring Market?
Who are the major players in the Non Invasive Glucose Monitoring Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Hospitals and Clinics
- 1.2.2 Home and Personal Use
- 1.2.3 Ambulatory Surgical Centers
- 1.2.4 Others
- 1.3 By Technology
- 1.3.1 Optical Sensors
- 1.3.2 Electromagnetic Sensors
- 1.3.3 Transdermal Technology
- 1.3.4 Enzymatic Technology
- 1.3.5 Others
- 1.4 By Application
- 1.4.1 Diabetes Management
- 1.4.2 Sports & Fitness
- 1.4.3 Clinical Research
- 1.4.4 Others
- 1.5 By Device Type
- 1.5.1 Wearable Devices (smartwatches, patches, wristbands)
- 1.5.2 Non-Wearable Devices (handheld, tabletop meters)
- 1.5.3 Implantable Devices
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 462.55 million → 2032: USD 2,447.99 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Non-Invasive Glucose Monitoring Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Non-Invasive Glucose Monitoring Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Non-Invasive Glucose Monitoring Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Non-Invasive Glucose Monitoring Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Non-Invasive Glucose Monitoring Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Non-Invasive Glucose Monitoring Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Non-Invasive Glucose Monitoring Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Non-Invasive Glucose Monitoring Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 462.55 million → 2032: USD 2,447.99 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Non-Invasive Glucose Monitoring Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals and Clinics
- 12.3.7.2 Home and Personal Use
- 12.3.7.3 Ambulatory Surgical Centers
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Optical Sensors
- 12.4.7.2 Electromagnetic Sensors
- 12.4.7.3 Transdermal Technology
- 12.4.7.4 Enzymatic Technology
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Diabetes Management
- 12.5.7.2 Sports & Fitness
- 12.5.7.3 Clinical Research
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Device Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Wearable Devices (smartwatches, patches, wristbands)
- 12.6.7.2 Non-Wearable Devices (handheld, tabletop meters)
- 12.6.7.3 Implantable Devices
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Non-Invasive Glucose Monitoring End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Non-Invasive Glucose Monitoring Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Non-Invasive Glucose Monitoring Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Non-Invasive Glucose Monitoring Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Abbott Laboratories
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Dexcom, Inc.
- 18.4 Medtronic plc
- 18.5 Apple Inc.
- 18.6 Fitbit (Google)
- 18.7 Hoffmann-La Roche Ltd.
- 18.8 DiaMonTech GmbH
- 18.9 Know Labs
- 18.10 Sanofi
- 18.11 DarioHealth Corp.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

