
Market Overview:
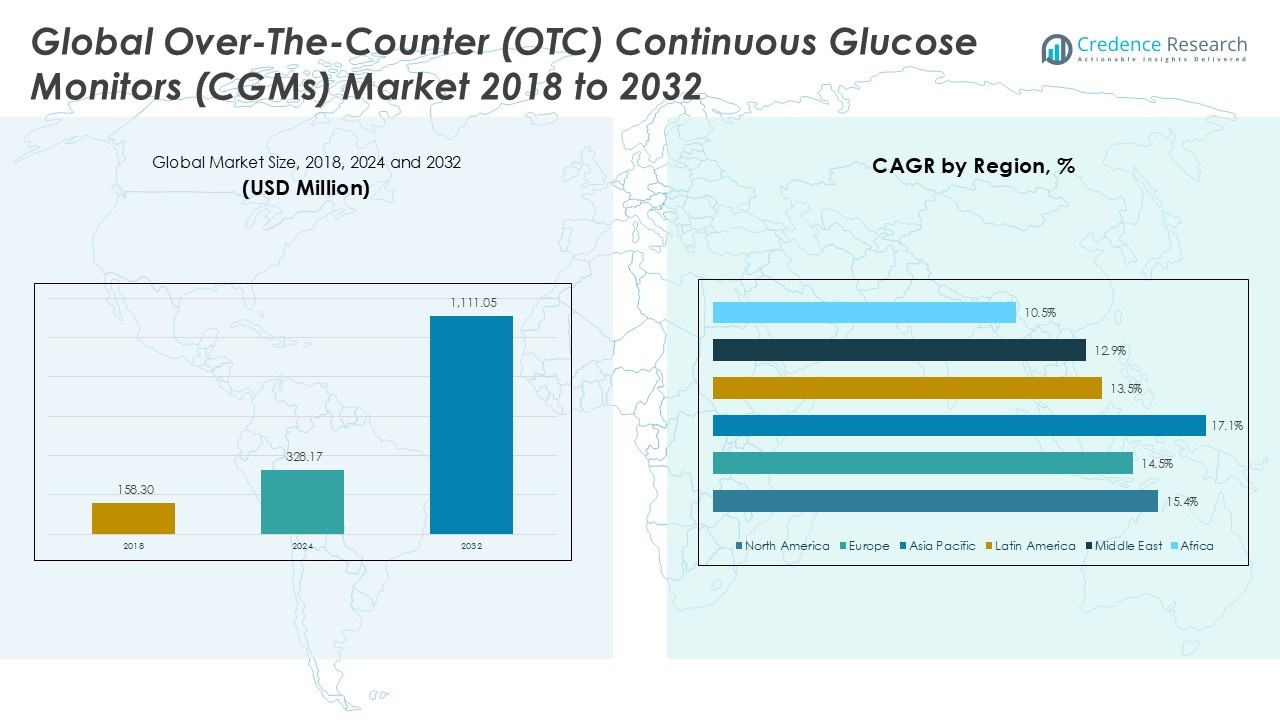
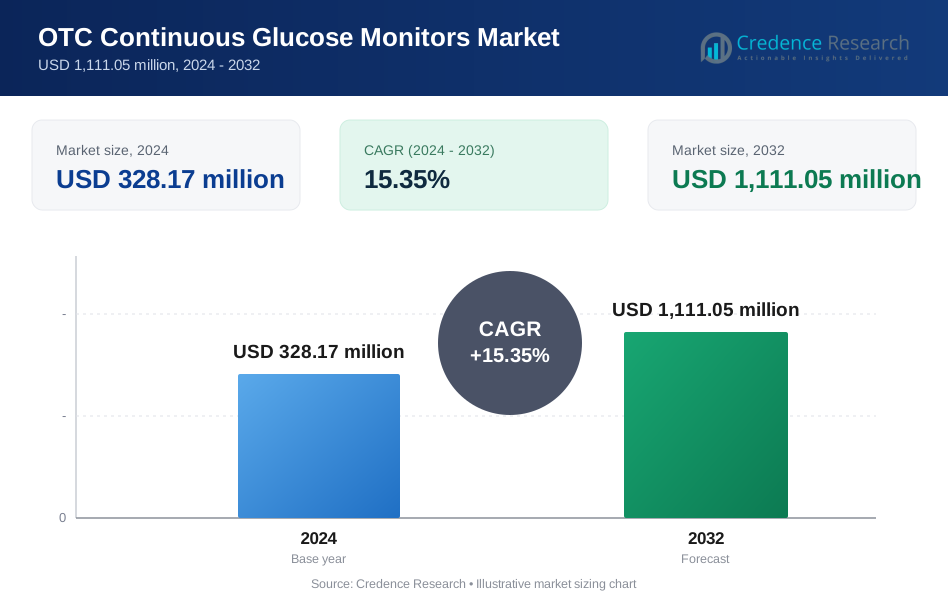
The Global Over-The-Counter (OTC) Continuous Glucose Monitors (CGMs) Market size was valued at USD 158.30 million in 2018 to USD 328.17 million in 2024 and is anticipated to reach USD 1,111.05 million by 2032, at a CAGR of 15.35% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Over-The-Counter (OTC) Continuous Glucose Monitors (CGMs) Market Size 2024 | USD 328.17 Million |
| Over-The-Counter (OTC) Continuous Glucose Monitors (CGMs) Market, CAGR | 15.35% |
| Over-The-Counter (OTC) Continuous Glucose Monitors (CGMs) Market Size 2032 | USD 1,111.05 Million |
Key drivers fueling the OTC CGM market include the rising prevalence of diabetes and prediabetes, the increasing adoption of digital health tools, and ongoing innovations in sensor technology that deliver improved accuracy, comfort, and longer wear times. The market also benefits from heightened awareness about proactive health management and the integration of CGMs with mobile health applications, empowering patients to make informed decisions and improve glycemic control independently. Additionally, increased availability of OTC CGMs in retail pharmacies and online platforms is making these devices more accessible to a wider population.
Regionally, North America holds the dominant market share, underpinned by strong healthcare infrastructure and rapid adoption of consumer health technologies. Strategic collaborations between device manufacturers and retail pharmacy chains are further boosting product visibility and distribution in the region. Europe follows closely, driven by increasing diabetes incidence and supportive regulatory frameworks for non-prescription CGMs. The Asia-Pacific region is projected to witness the fastest growth, attributed to the expanding diabetic population, rising healthcare expenditure, and increasing acceptance of digital health solutions.
Market Insights:
- The Global Over-The-Counter (OTC) Continuous Glucose Monitors (CGMs) Market is expected to grow from USD 158.30 million in 2018 to USD 1,111.05 million by 2032, at a CAGR of 15.35%, driven by rising diabetes and prediabetes prevalence.
- Innovations in sensor technology, improved accuracy, longer wear times, and non-invasive designs are enhancing product adoption and user comfort in the OTC CGM market.
- Growing awareness and consumer empowerment in proactive health management are significantly boosting demand for OTC CGMs through educational campaigns and digital health initiatives.
- The expansion of distribution channels, including retail pharmacies and online platforms, has increased OTC CGM accessibility and market penetration.
- North America holds the largest share of the market, benefiting from advanced healthcare infrastructure and rapid adoption of digital health technologies.
- The Asia Pacific region is experiencing the fastest growth, driven by the increasing diabetic population, rising healthcare spending, and expanding digital health solutions.
- In Latin America, improved healthcare infrastructure, rising diabetes awareness, and expanded access to OTC CGMs through retail and online channels are driving market growth.
Market Drivers:
Rising Prevalence of Diabetes and Prediabetes Fuels Market Demand
The Global Over-The-Counter (OTC) Continuous Glucose Monitors (CGMs) Market experiences significant growth due to the surging rates of diabetes and prediabetes worldwide. Health authorities report escalating incidences across both developed and developing regions, driving demand for convenient self-monitoring solutions. Patients require accessible tools to manage their conditions outside clinical settings, and OTC CGMs directly address this necessity. It provides real-time data and removes the barriers of prescription-only models, making continuous monitoring feasible for millions. This trend supports a larger movement toward self-managed healthcare. Stakeholders across the healthcare ecosystem recognize the impact of widespread diabetes, prioritizing solutions that improve daily glucose management.
- For instance, the FDA approved the Dexcom Stelo Glucose Biosensor System in March 2024 as the first OTC CGM specifically for adults 18 and older with prediabetes or type 2 diabetes not using insulin, allowing direct purchase without a prescription.
Technological Advancements Drive Product Innovation and User Comfort
Ongoing advancements in biosensor technology, wireless connectivity, and device miniaturization support the expansion of the Global Over-The-Counter (OTC) Continuous Glucose Monitors (CGMs) Market. It now features sensors with higher accuracy, longer lifespans, and increased comfort for users, resulting in broader adoption. Developers focus on improving calibration-free technology and non-invasive designs, meeting consumer expectations for ease of use. Integration with smartphones and digital platforms enhances usability, providing seamless access to glucose data. These innovations make daily glucose management more efficient and less intrusive. The rapid pace of R&D ensures the market remains highly dynamic and competitive.
- For instance, the Abbott Free Style Libre 2 CGM sensor is designed to deliver accurate glucose readings for up to 14 days of continuous wear.
Increasing Health Awareness and Patient Empowerment Shape Market Growth
Growing awareness about the importance of proactive diabetes management significantly influences the Global Over-The-Counter (OTC) Continuous Glucose Monitors (CGMs) Market. Educational campaigns and digital health initiatives inform consumers about the risks of uncontrolled blood sugar. People are more likely to seek real-time monitoring solutions to avoid complications and improve their quality of life. The market capitalizes on this shift, offering devices that empower users to make informed health decisions. It helps bridge the gap between routine care and clinical intervention. This heightened awareness translates to stronger product demand across all age groups.
Expanding Access Through Retail Pharmacies and Online Distribution Channels
The availability of OTC CGMs in retail pharmacies and e-commerce platforms increases accessibility and accelerates market penetration. Consumers can now purchase these devices directly, bypassing traditional healthcare channels. This model enhances convenience and allows greater reach, particularly in regions with limited healthcare infrastructure. The Global Over-The-Counter (OTC) Continuous Glucose Monitors (CGMs) Market benefits from the rise of digital retail and pharmacy partnerships. It leverages widespread distribution networks to ensure timely product availability. Expanded access not only drives sales but also supports ongoing education about self-monitoring and disease prevention.
Market Trends:
Integration with Digital Health Ecosystems and Mobile Applications is Transforming User Experience
The integration of OTC continuous glucose monitors with digital health ecosystems and mobile applications is reshaping the landscape of diabetes management. Users now connect their CGM devices to smartphones and health platforms, enabling real-time tracking and seamless sharing of glucose data with healthcare providers or family members. It improves adherence to care plans and enhances personalized interventions. Remote monitoring capabilities foster stronger patient engagement and promote timely clinical decisions. Many devices now offer predictive alerts, data analytics, and actionable health insights through user-friendly interfaces. The Global Over-The-Counter (OTC) Continuous Glucose Monitors (CGMs) Market responds to these trends by supporting greater connectivity, interactivity, and convenience for end-users.
- For instance, the Dexcom Follow app allows users to share real-time glucose data with up to 10 people, improving care coordination and support structures.
Shift Toward Non-Invasive and Wearable Technologies is Expanding Market Reach
The market is witnessing a clear shift toward non-invasive, discreet, and wearable CGM technologies, driven by consumer demand for comfort and ease of use. Leading manufacturers prioritize thin, flexible sensors and patch-style monitors that reduce discomfort and encourage consistent usage. It addresses consumer preferences for minimal disruption to daily routines, supporting broad adoption across diverse age groups. Companies invest in research to improve sensor longevity, calibration-free designs, and waterproof features. These trends increase device accessibility for those managing diabetes and appeal to health-conscious individuals focused on preventive care. The Global Over-The-Counter (OTC) Continuous Glucose Monitors (CGMs) Market evolves rapidly as innovation continues to blur the lines between medical devices and everyday wellness technology.
- For instance, Abbott’s FreeStyle Libre portfolio incorporates a factory-calibrated sensor that allows for 14 consecutive days of wear, supporting longer continuous glucose measurement without routine calibrations.
Market Challenges Analysis:
Regulatory Hurdles and Product Reliability Concerns Hamper Market Growth
The Global Over-The-Counter (OTC) Continuous Glucose Monitors (CGMs) Market faces significant challenges from complex regulatory pathways and evolving compliance requirements. Many markets enforce stringent standards for safety, accuracy, and data security. It must address concerns regarding product reliability and calibration errors, which can undermine user trust and adoption rates. Uncertainties in regulatory approval timelines can slow new product launches and hinder innovation. Ensuring devices meet diverse regional guidelines presents further complexity. Stakeholders must invest in ongoing quality assurance and transparency to maintain credibility and market access.
High Costs and Limited Awareness Restrict Wider Adoption
Despite recent advancements, high upfront costs and limited reimbursement policies restrict access for many consumers. It creates a barrier, especially in emerging economies and among underinsured populations. Some users remain unaware of the benefits and availability of OTC CGMs, reducing potential market penetration. Effective education and outreach programs are essential to expand understanding and drive demand. The Global Over-The-Counter (OTC) Continuous Glucose Monitors (CGMs) Market requires strategies to address affordability and promote broader acceptance. Industry leaders must focus on cost optimization and awareness campaigns to support sustainable growth.
Market Opportunities:
Expansion into Untapped Emerging Markets Offers Strong Growth Potential
Expanding into emerging markets presents a significant growth opportunity for the Global Over-The-Counter (OTC) Continuous Glucose Monitors (CGMs) Market. Rapid urbanization, rising disposable incomes, and increasing rates of diabetes in countries across Asia-Pacific, Latin America, and Africa create fertile ground for adoption. It can leverage partnerships with local distributors and healthcare providers to enhance market penetration. Customized awareness campaigns and affordable product offerings will help address region-specific needs. Governments and NGOs increasingly prioritize diabetes prevention and management, further supporting market access. The ability to reach new demographics positions the market for robust long-term expansion.
Advancements in Product Innovation and Digital Integration Accelerate Market Growth
Continued investment in product innovation and digital integration creates compelling opportunities for the Global Over-The-Counter (OTC) Continuous Glucose Monitors (CGMs) Market. It can benefit from developing next-generation sensors, improved data analytics, and user-friendly mobile interfaces. Collaborations with technology firms and app developers will strengthen connectivity and enhance the user experience. The integration of artificial intelligence and machine learning holds promise for more personalized diabetes management. Emphasizing convenience, accuracy, and seamless data sharing will attract a broader user base. Strategic innovation supports the market’s evolution into a mainstream healthcare solution.
Market Segmentation Analysis:
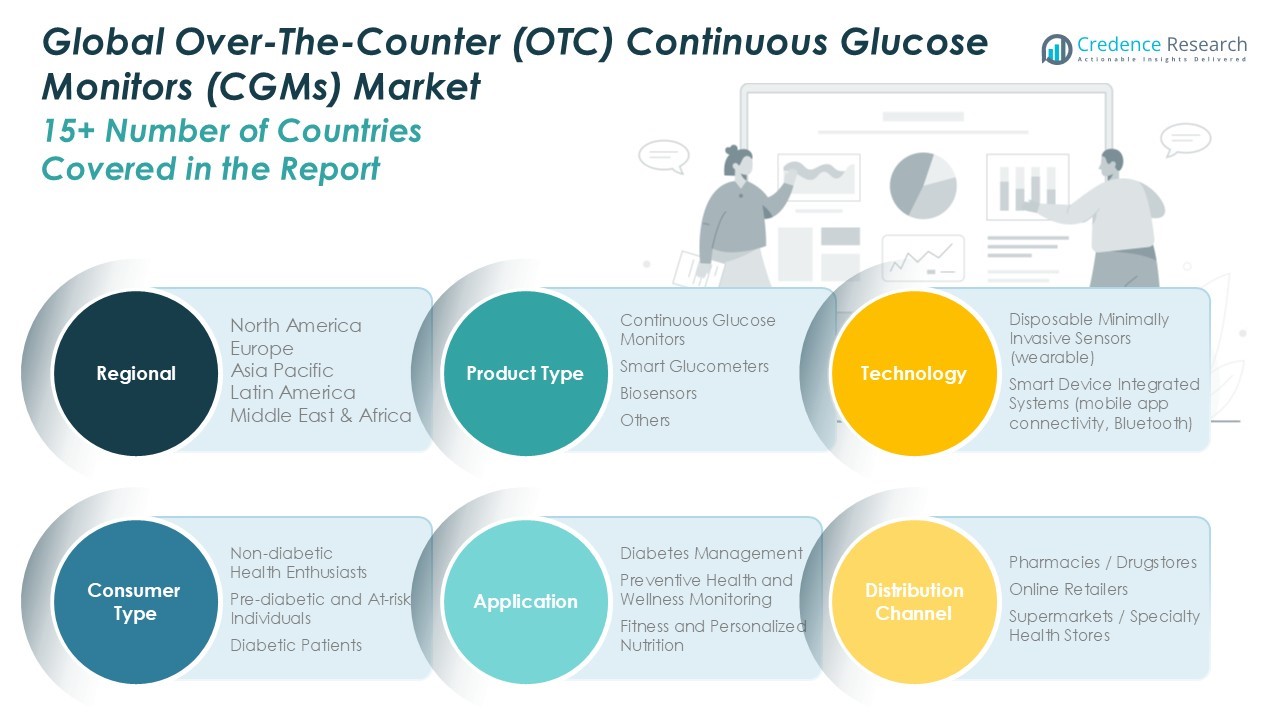
By Product Type
The Global Over-The-Counter (OTC) Continuous Glucose Monitors (CGMs) Market is segmented into continuous glucose monitors, smart glucometers, biosensors, and others. Continuous glucose monitors dominate this segment, valued for real-time glucose readings and actionable insights. Smart glucometers and biosensors follow, attracting tech-savvy users seeking connected, convenient solutions. It benefits from strong demand for biosensors, which support discreet and non-invasive glucose tracking.
- For instance, Dexcom Stelo delivers continuous glucose monitoring for 15 days per sensor, available OTC since March 2024.
By Technology
Disposable minimally invasive sensors hold the largest market share, supported by advancements in accuracy, comfort, and extended wear time. Smart device integrated systems, featuring mobile app connectivity and Bluetooth, are rapidly gaining momentum. It appeals to consumers who value seamless data transfer and integration with broader digital health ecosystems.
By Consumer Type
Diabetic patients account for the largest share in this segment, reflecting the market’s focus on supporting chronic disease management. Pre-diabetic and at-risk individuals are increasingly adopting OTC CGMs to monitor glucose trends and enable early intervention. Non-diabetic health enthusiasts also represent a rising segment, interested in using these solutions for fitness, nutrition, and general wellness monitoring.
- For instance, Medtronic’s Guardian Sensor 3 is FDA approved for use on the upper arm and is incorporated
-
Segmentations:
By Product Type- Continuous Glucose Monitors
- Smart Glucometers
- Biosensors
- Others
- Disposable Minimally Invasive Sensors (wearable)
- Smart Device Integrated Systems (mobile app connectivity, Bluetooth)
- Non-diabetic Health Enthusiasts
- Pre-diabetic and At-risk Individuals
- Diabetic Patients
- Diabetes Management
- Preventive Health and Wellness Monitoring
- Fitness and Personalized Nutrition
- Pharmacies / Drugstores
- Online Retailers
- Supermarkets / Specialty Health Stores
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East
- Africa
Regional Analysis:
North America: Leading Market Share with Advanced Infrastructure
The North America Global Over-The-Counter (OTC) Continuous Glucose Monitors (CGMs) Market size was valued at USD 66.05 million in 2018 to USD 135.44 million in 2024 and is anticipated to reach USD 459.86 million by 2032, at a CAGR of 15.4% during the forecast period. North America holds the largest share, comprising 34.5% of the global market in 2024. It benefits from robust healthcare infrastructure, high consumer awareness, and rapid adoption of digital health solutions. Favorable reimbursement policies, strong distribution networks, and frequent product launches by key manufacturers fuel market leadership. Major players collaborate with pharmacy chains, boosting product accessibility. The region’s emphasis on preventive health and advanced regulatory standards supports ongoing demand and continuous innovation.
Europe: Expanding Access with Regulatory Support
The Europe Global Over-The-Counter (OTC) Continuous Glucose Monitors (CGMs) Market size was valued at USD 46.75 million in 2018 to USD 93.57 million in 2024 and is anticipated to reach USD 299.00 million by 2032, at a CAGR of 14.5% during the forecast period. Europe accounts for 23.8% of the global market in 2024, propelled by rising diabetes incidence, supportive healthcare systems, and favorable regulatory frameworks for non-prescription devices. Public health campaigns and cross-border partnerships stimulate market growth. Consumers value comfort and convenience, fueling the adoption of new CGM technologies. Global and regional manufacturers maintain a competitive environment through continuous innovation and tailored service models.
Asia Pacific: Rapid Growth Driven by Large Diabetic Population
The Asia Pacific Global Over-The-Counter (OTC) Continuous Glucose Monitors (CGMs) Market size was valued at USD 32.40 million in 2018 to USD 72.46 million in 2024 and is anticipated to reach USD 276.03 million by 2032, at a CAGR of 17.1% during the forecast period. Asia Pacific represents 18.5% of the market in 2024 and demonstrates the fastest growth rate globally. The market is driven by a large diabetic population, rising healthcare spending, and accelerating urbanization across countries such as China, India, and Japan. Government-backed digital health initiatives and robust e-commerce infrastructure support widespread adoption. Manufacturers focus on affordability and innovation, delivering region-specific solutions and expanding access through online platforms.
Latin America: Rising Awareness and Improved Accessibility
The Latin America Global Over-The-Counter (OTC) Continuous Glucose Monitors (CGMs) Market size was valued at USD 6.98 million in 2018 to USD 14.29 million in 2024 and is anticipated to reach USD 42.42 million by 2032, at a CAGR of 13.5% during the forecast period. Latin America comprises 3.6% of the global market in 2024, with growth supported by increasing health awareness and gradual improvements in healthcare infrastructure. Partnerships between international device makers and local distributors enhance reach. Expanding retail pharmacy networks and digital sales channels boost product availability in both urban and rural areas. Government and NGO-led initiatives further promote diabetes management and market expansion.
Middle East: Emerging Demand Supported by Healthcare Modernization
The Middle East Global Over-The-Counter (OTC) Continuous Glucose Monitors (CGMs) Market size was valued at USD 4.45 million in 2018 to USD 8.44 million in 2024 and is anticipated to reach USD 24.12 million by 2032, at a CAGR of 12.9% during the forecast period. The region holds 2.2% of the global market in 2024, with demand shaped by rising diabetes prevalence and increasing investments in healthcare modernization. Urban centers see higher uptake, supported by private healthcare expansion and digital health campaigns. Manufacturers offer culturally relevant solutions, and collaborations with local providers accelerate access. The Middle East remains a promising market for sustained growth.
Africa: Incremental Progress Driven by Education and Partnerships
The Africa Global Over-The-Counter (OTC) Continuous Glucose Monitors (CGMs) Market size was valued at USD 1.66 million in 2018 to USD 3.98 million in 2024 and is anticipated to reach USD 9.62 million by 2032, at a CAGR of 10.5% during the forecast period. Africa accounts for 1.0% of the global market in 2024 and sees gradual growth driven by improved healthcare access and disease education. Limited resources and affordability remain challenges, but partnerships with NGOs and international agencies expand CGM reach. Local distributors focus on lower-cost solutions, while ongoing campaigns highlight the importance of diabetes monitoring. Africa’s market outlook remains positive as infrastructure and awareness initiatives progress.
Key Player Analysis:
- Abbott Laboratories
- Dexcom, Inc.
- Medtronic plc
- Senseonics Holdings
- Ascensia Diabetes Care
- i-SENS, Inc.
Competitive Analysis:
The Global Over-The-Counter (OTC) Continuous Glucose Monitors (CGMs) Market features intense competition among established medical device manufacturers and innovative technology firms. Leading companies such as Abbott Laboratories, Dexcom, Medtronic, and Senseonics focus on expanding product portfolios and advancing sensor technology. It encourages strategic partnerships with retail pharmacies and digital health platforms to enhance product accessibility and user engagement. Continuous investment in research and development drives improvements in accuracy, comfort, and device connectivity. New entrants and regional players compete by offering cost-effective and user-friendly solutions, targeting specific consumer segments. The market also experiences rapid product cycles and a strong emphasis on regulatory compliance. Companies differentiate through innovation, customer service, and integration with digital ecosystems, establishing a dynamic and evolving competitive environment.
Recent Developments:
- In July 2025, Medtronic secured the CE Mark in Europe for the MiniMed 780G system, expanding its indications to include children as young as two years old, pregnant women, and individuals with type 2 diabetes.
- In April 2025, Senseonics and Sequel Med Tech announced a partnership to create the first automated insulin delivery system using the one-year Eversense 365 CGM technology.
Market Concentration & Characteristics:
The Global Over-The-Counter (OTC) Continuous Glucose Monitors (CGMs) Market exhibits a moderate-to-high market concentration, with a few dominant multinational players controlling a significant share. It is characterized by rapid technological advancement, strong regulatory oversight, and a growing emphasis on digital integration. The market values innovation in sensor design, comfort, and non-invasive solutions, driving frequent product launches. Consumer demand for real-time monitoring and preventive health management shapes competitive strategies. Companies compete on brand reputation, distribution networks, and connectivity with mobile health platforms, reinforcing a dynamic and innovation-driven market landscape.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Technology, Consumer Type, Application, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Companies will expand partnerships with pharmacies and e-commerce platforms to enhance OTC CGM accessibility and consumer reach.
- Manufacturers will focus on developing non-invasive sensor technologies that enhance comfort while maintaining accuracy.
- Integration with mobile health platforms will deepen, enabling advanced data analytics and predictive health alerts.
- Regulatory frameworks will evolve to support OTC distribution, simplifying approval processes for new devices.
- Personalized health management features, including AI-driven insights, will become standard components in CGM apps.
- Entry of cost-effective regional players will increase competition and drive price optimization across markets.
- Expansion into preventive health markets will attract pre-diabetic and wellness-oriented consumers.
- Enhanced interoperability standards will enable seamless sharing between CGMs, fitness trackers, and electronic health records.
- Stakeholders will prioritize continuous patient education to build trust and enhance device adoption.
- Ongoing sensor miniaturization will support discreet monitoring and appeal to broader demographics.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Over-The-Counter (OTC) Continuous Glucose Monitors (CGMs) Market?
What factors are driving the growth of the Global Over-The-Counter (OTC) Continuous Glucose Monitors (CGMs) Market?
What are the key segments within the Global Over-The-Counter (OTC) Continuous Glucose Monitors (CGMs) Market?
What are some challenges faced by the Global Over-The-Counter (OTC) Continuous Glucose Monitors (CGMs) Market?
Who are the major players in the Global Over-The-Counter (OTC) Continuous Glucose Monitors (CGMs) Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 OTC Continuous Glucose Monitors Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global OTC Continuous Glucose Monitors Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 328.17 million → 2032: USD 1,111.05 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 OTC Continuous Glucose Monitors Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. OTC Continuous Glucose Monitors Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 OTC Continuous Glucose Monitors Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 OTC Continuous Glucose Monitors Market Drivers
- 3.3 OTC Continuous Glucose Monitors Market Restraints & Challenges
- 3.4 OTC Continuous Glucose Monitors Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 OTC Continuous Glucose Monitors Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 OTC Continuous Glucose Monitors Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, OTC Continuous Glucose Monitors category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 OTC Continuous Glucose Monitors Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. OTC Continuous Glucose Monitors Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the OTC Continuous Glucose Monitors market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 OTC Continuous Glucose Monitors Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 OTC Continuous Glucose Monitors Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 OTC Continuous Glucose Monitors Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in OTC Continuous Glucose Monitors (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New OTC Continuous Glucose Monitors Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global OTC Continuous Glucose Monitors Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America OTC Continuous Glucose Monitors Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe OTC Continuous Glucose Monitors Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific OTC Continuous Glucose Monitors Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America OTC Continuous Glucose Monitors Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East OTC Continuous Glucose Monitors Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa OTC Continuous Glucose Monitors Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. OTC Continuous Glucose Monitors Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
