
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
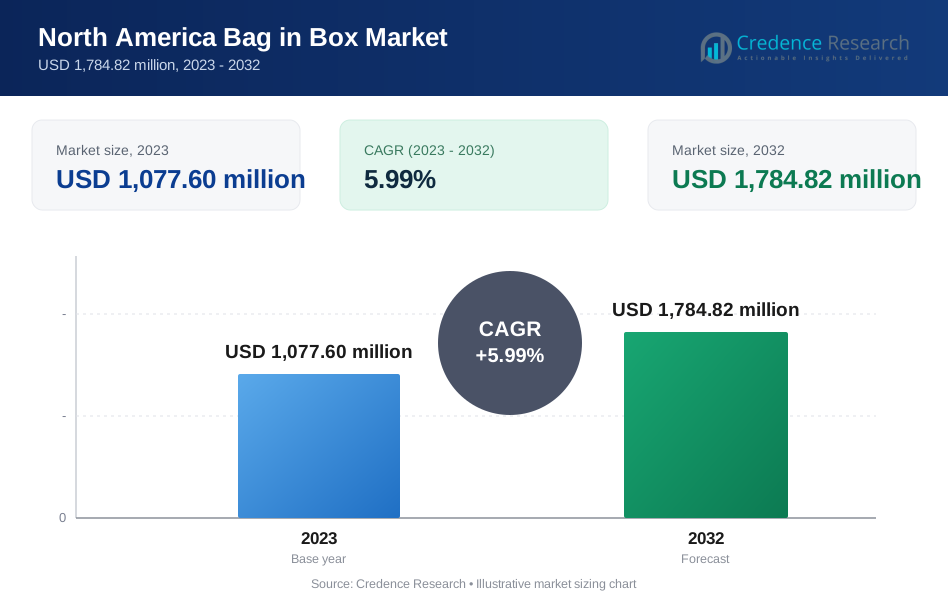
| North America Bag in Box Market Size 2023 | USD 1,077.60 Million |
| North America Bag in Box Market, CAGR | 5.99% |
| North America Bag in Box Market Size 2032 | USD 1,784.82 Million |
Market Overview
The North America Bag in Box Market is projected to grow from USD 1,077.60 million in 2023 to an estimated USD 1,784.82 million by 2032, reflecting a compound annual growth rate (CAGR) of 5.99% from 2024 to 2032. This growth trajectory is driven by the increasing demand for sustainable and cost-effective packaging solutions across various industries such as food and beverage, household, and industrial applications.
Market drivers include a growing emphasis on sustainable packaging and reduced packaging waste, which aligns with regulatory requirements and consumer expectations in North America. The demand for extended shelf life and minimal contamination, particularly in liquid packaging, further fuels adoption in sectors such as beverages and dairy. Additionally, the rising popularity of flexible packaging solutions due to their cost savings, transport efficiency, and convenience is propelling market growth. Trends such as increased focus on customizable solutions and innovative dispensing technologies are expected to foster further market development.
Geographically, the United States dominates the North America Bag in Box Market due to its robust food and beverage industry, high consumption of packaged products, and favorable regulatory environment supporting sustainable packaging. Canada also holds a significant market share, driven by increasing demand for innovative packaging solutions. Key players operating in the market include Smurfit Kappa, DS Smith Plc, Liquibox Corporation, Scholle IPN, and Amcor Plc, who are focusing on R&D and strategic partnerships to strengthen their market presence.
Market Drivers
Increasing Demand for Sustainable and Eco-Friendly Packaging Solutions
The North America Bag in Box Market has witnessed strong growth driven by increasing demand for sustainable and eco-friendly packaging solutions. Consumers and industries alike are becoming more conscious of their environmental impact, which has led to a surge in demand for packaging formats that minimize material usage, reduce waste, and are easier to recycle. Bag-in-box packaging is considered highly sustainable as it significantly reduces plastic usage compared to rigid packaging solutions, thereby offering a greener alternative. Furthermore, these packages are often lighter and more compact, contributing to lower carbon footprints associated with transportation and distribution. Regulatory bodies in North America have also set ambitious targets for waste reduction, further compelling companies to adopt greener packaging solutions. This regulatory push has bolstered demand across sectors like beverages, food service, and non-food industries, making sustainability a key growth driver in this market. For instance, several companies in North America have transitioned to bag-in-box packaging due to its environmental benefits and cost efficiency. This packaging format not only reduces plastic usage significantly but also minimizes transportation costs by being lightweight and compact. As a result, businesses can lower their carbon footprint while saving on logistics expenses.
Cost Efficiency and Convenience of Bag-in-Box Packaging
Cost efficiency is another key driver propelling the growth of the North America Bag in Box Market. Bag-in-box solutions offer substantial cost savings over traditional rigid packaging options due to their lightweight nature, minimal raw material use, and reduced logistics costs. The flat-packed design of bag-in-box packaging allows for efficient storage and transportation, significantly lowering shipping expenses for manufacturers. These savings extend to consumers as well, offering a price-competitive alternative without compromising on product safety and quality. Moreover, bag-in-box containers feature innovative dispensing mechanisms that prevent spillage, extend product shelf life, and provide ease of use. This convenience factor makes them popular among end-users across diverse sectors, such as food and beverage, cleaning agents, and liquid chemicals. The cost-benefit balance has attracted businesses looking to optimize packaging budgets without sacrificing quality, thus propelling market growth. For instance, the extended shelf life offered by bag-in-box packaging, which protects contents from oxygen and light exposure, has made it a preferred choice for industries such as beverages and liquid food products.
Rising Demand for Extended Shelf Life and Hygienic Packaging Solutions
Bag-in-box packaging has become synonymous with extended shelf life and superior product preservation, driving demand across the North American market. This type of packaging is designed to maintain product freshness by protecting its contents from oxygen, light, and contamination. The bag-in-box format ensures minimal air exposure during dispensing, making it a preferred choice for products that require prolonged freshness, such as wine, juice, dairy products, sauces, and liquid food ingredients. Additionally, this hygienic packaging solution addresses concerns over food safety and contamination risks, which are top priorities for consumers and businesses in the food and beverage industry. The increased focus on food safety, driven by stringent government regulations and growing awareness of health risks, has further bolstered the adoption of bag-in-box packaging solutions in the market. The ability of these packages to offer high-quality preservation while meeting safety standards has made them indispensable for liquid food and beverage manufacturers, thereby accelerating market growth. For instance, businesses across the beverage sector have increasingly adopted bag-in-box solutions due to their ability to preserve product quality while ensuring compliance with food safety regulations.
Growing Adoption of Flexible Packaging Solutions Across Various Industries
The growing adoption of flexible packaging solutions across various industries has been a significant driver for the North America Bag in Box Market. Flexibility in packaging not only provides versatility in terms of design and capacity but also allows for customization to meet specific requirements across different sectors. The food and beverage industry, in particular, has embraced flexible bag-in-box formats for packaging a wide array of liquid products, such as wines, sauces, syrups, and oils, due to their convenience and ability to preserve product integrity. The rising popularity of “on-the-go” consumption patterns and the increased demand for user-friendly and portable packaging solutions have further encouraged manufacturers to invest in bag-in-box systems. Beyond food and beverages, sectors such as industrial liquids, pharmaceuticals, and household chemicals are also shifting towards flexible packaging due to its resilience and space-saving characteristics. This broad-based adoption has fueled the market’s expansion, driven by companies’ and consumers’ desire for innovative, efficient, and practical packaging solutions
Market Trends
Emphasis on Innovation and Customization in Bag-in-Box Solutions
One of the prevailing trends in the North America Bag in Box Market is the growing emphasis on innovation and customization to meet diverse consumer demands. Companies are actively investing in research and development to create solutions tailored to specific product requirements, enhancing both functionality and consumer appeal. This trend includes the introduction of advanced dispensing systems that improve product flow and reduce waste, such as push-tap valves and self-closing taps that provide spill-free convenience. Customization extends to the ability to tailor bag sizes, shapes, and materials to suit different applications, such as wine, dairy products, industrial liquids, and more. Additionally, companies are leveraging innovative barrier technologies and materials to improve oxygen resistance and extend shelf life. The focus on creating eco-friendly and recyclable bag-in-box materials also aligns with environmental trends, attracting businesses seeking to minimize their environmental impact while maintaining product integrity. This push for innovation and bespoke solutions is helping companies differentiate themselves in an increasingly competitive market.For instance, companies like Smurfit Kappa have introduced bag-in-box solutions where over 75% of the packaging is made from corrugated cardboard, which is fully recyclable, renewable, and biodegradable. This innovation not only reduces the environmental impact but also provides an 8 times lower carbon footprint compared to glass bottles, making it a popular choice for businesses aiming to align with sustainability goals.
Rising Demand for Sustainable and Recyclable Packaging Materials
Sustainability continues to dominate the packaging industry, and the North America Bag in Box Market is no exception. The market has seen a significant shift toward the adoption of eco-friendly and recyclable materials, driven by heightened awareness of environmental issues and stringent government regulations. Consumers are increasingly prioritizing environmentally conscious packaging, prompting manufacturers to introduce recyclable bags, biodegradable films, and reusable outer boxes. This trend has led to partnerships and collaborations within the industry to develop packaging solutions that minimize plastic usage and improve recyclability without compromising performance. Companies are also exploring the use of plant-based and bio-derived polymers to create biodegradable alternatives that reduce the environmental footprint. The strong emphasis on sustainability has become a key differentiating factor, enabling businesses to attract environmentally conscious customers and align with corporate social responsibility (CSR) objectives. As more businesses and consumers advocate for green initiatives, this trend is expected to shape the market’s evolution for years to come.
Market Restraints and Challenges
Concerns Over the Recycling and Disposal of Multi-Layer Packaging
One of the key restraints facing the North America Bag in Box Market is the challenge associated with recycling and disposal of multi-layer packaging materials. Bag-in-box systems often comprise several layers of different materials, such as plastic films, foil barriers, and cardboard boxes, designed to protect the contents and extend shelf life. While these multi-layer constructions enhance product performance, they also pose challenges for recyclability, as separating and processing such materials can be complex and costly. Many recycling facilities in North America are not fully equipped to handle mixed-material packaging, resulting in a limited recycling rate and increased concerns over the environmental impact of these products. This has led to scrutiny from both regulators and environmentally conscious consumers, creating pressure on manufacturers to develop alternative solutions that balance high performance with improved recyclability. The complexity of addressing these challenges while maintaining product integrity and cost efficiency remains a significant barrier to growth.
Volatility in Raw Material Prices and Supply Chain Disruptions
The volatility in raw material prices, particularly those used in the production of bag-in-box packaging, presents a considerable challenge for manufacturers operating in this market. Prices of key inputs, such as plastic resins and paperboard, are subject to fluctuations due to changes in global supply and demand dynamics, trade policies, and economic conditions. These price swings can directly impact production costs, leading to increased pricing pressures that may be passed on to end-users. Additionally, the COVID-19 pandemic and other geopolitical factors have exposed vulnerabilities in global supply chains, resulting in disruptions that affect the availability and timely delivery of raw materials. Prolonged supply chain challenges and unpredictable price hikes create uncertainty, making it difficult for companies to plan long-term production strategies and maintain competitive pricing structures. Addressing these issues requires a focus on strategic procurement, supply chain diversification, and cost management strategies, all of which can present operational complexities for market participants.
Market Segmentation Analysis
By Component
The North America Bag in Box Market is segmented by component into bags, boxes, and fitments. Bags serve as the primary containment unit and are often constructed with multi-layer films for durability, barrier protection, and extended product shelf life. The boxes offer structural support and branding opportunities, making them essential for transport and display. Fitments, such as taps and valves, facilitate convenient dispensing while ensuring product safety. Among these components, bags account for a significant share due to their critical role in preserving the contents and protecting against contamination.
By Capacity
The market is segmented by capacity into 5 to 10 liters, 10 to 15 liters, 15 to 20 liters, and other sizes. The 5 to 10 liters segment is highly popular due to its suitability for consumer-sized packaging, particularly for beverages like wine and juices. Larger capacities, such as 15 to 20 liters, are often preferred for bulk packaging in industrial and commercial settings, including food service establishments and liquid chemicals. The market's versatility across different capacities demonstrates its adaptability to meet varying consumer and business needs.
Segments
Based on component
- Bags
- Boxes
- Fitments
Based on Capacity
- 5 to 10 liters
- 10 to 15 liters
- 15 to 20 liters
- Others
Based on End use
- Food
- Beverages
- Chemicals
- Industrial
- Others
Based on material state
- Semi-liquid
- Liquid
Based on tap
- With Tap
- Without Tap
Based on region
- United States
- Canada
- Other regions
Regional Analysis
North America (70%):
The North America Bag in Box Market is dominated by the United States, which holds the largest market share, accounting for approximately 70% of the regional market. The dominance of the U.S. is driven by its robust food and beverage industry, increasing demand for sustainable packaging solutions, and strong consumer preferences for convenient and efficient packaging. The country’s stringent regulations on packaging waste and sustainability initiatives have encouraged widespread adoption of eco-friendly bag-in-box solutions. The beverage sector, especially wine and liquid dairy products, plays a significant role in driving growth, with bag-in-box packaging emerging as a preferred option for its ability to preserve freshness and extend product shelf life. Moreover, the presence of leading market players such as Smurfit Kappa, Liquibox Corporation, and DS Smith further strengthens the market position of the U.S., as they continue to invest in research and innovation.
Canada (20%):
Canada holds a substantial share of the market, representing approximately 20% of the North America Bag in Box Market. The growth in Canada is primarily fueled by the increasing adoption of flexible packaging solutions across diverse industries, including food and beverage, industrial liquids, and household chemicals. The country's focus on sustainable and recyclable packaging materials aligns with the global shift toward environmentally friendly packaging. Canadian consumers are increasingly drawn to innovative, user-friendly dispensing solutions, which has spurred market expansion. Furthermore, collaborative efforts among key players to develop packaging that meets the unique needs of Canadian consumers have strengthened the market’s foothold in the region.
Key players
- Smurfit Kappa
- DS Smith Plc
- Scholle IPN Corporation
- Liqui-Box Corporation
- Aran Group
- Goglio S.p.A.
- CDF Corporation
- Vine Valley Ventures LLC
- TPS Rental Systems Ltd
- ABCO Automation, Inc.
- International Paper Company
- Mondi plc
- Pack Logix
- TriMas Company (Rapak)
- Great Northern Packaging
- Tote Solutions Ltd
- Pacmoore Products Inc.
- Betco Inc.
Competitive Analysis
The North America Bag in Box Market is highly competitive, with key players focusing on product innovation, sustainability, and strategic partnerships to strengthen their market presence. Companies like Smurfit Kappa, DS Smith Plc, and Scholle IPN lead the market due to their extensive product portfolios, strong distribution networks, and commitment to developing eco-friendly packaging solutions. Liqui-Box Corporation and Aran Group emphasize customization and advanced dispensing technologies, offering competitive differentiation. Meanwhile, smaller players, including CDF Corporation and Vine Valley Ventures, focus on niche markets, providing tailored solutions that cater to specific industry needs. The market's competitive landscape is shaped by ongoing innovation, cost management, and efforts to enhance recyclability, meeting growing consumer and regulatory demand for sustainable packaging.
Recent Developments
- In **October 2024**, Mondi acquired Western Europe Packaging Assets of Schumacher Packaging. Mondi also showcased its sustainable product portfolio at Scanpack 2024.
- In September 2024**, CDF Corporation announced Iris Thomas as the new President of the Petroleum Packaging Council.
- In **March 2024**, Liqui-Box Corporation launched Liquipure ultra, a sustainably simple mono-material bag-in-box solution for beverages.
- In May 2023**, Goglio S.p.A. showcased its solutions at INTERPACK, Düsseldorf.
Market Concentration and Characteristics
The North America Bag in Box Market exhibits a moderately fragmented market concentration, characterized by the presence of both established players and smaller, specialized firms. Leading companies such as Smurfit Kappa, DS Smith Plc, and Scholle IPN hold a significant share due to their extensive product portfolios, strong distribution channels, and focus on sustainable innovation. The market is driven by evolving consumer demand for eco-friendly and customizable packaging solutions, creating opportunities for differentiation through advanced technologies and unique designs. Smaller players maintain a competitive edge by catering to niche applications, offering highly tailored solutions that align with specific industry needs. Market dynamics are shaped by regulatory trends, sustainability initiatives, and continuous advancements in material and dispensing technologies.
Report Coverage
The research report offers an in-depth analysis based on Component, Capacity, End use, Material, Tap and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to grow steadily due to the increasing emphasis on eco-friendly and recyclable packaging solutions, aligning with environmental regulations and consumer preferences.
- Future growth will be fueled by heightened demand for customizable bag-in-box solutions that cater to specific industry needs, enabling companies to offer innovative and tailored packaging.
- The beverage and liquid food sectors will continue to dominate market share, driven by the growing popularity of extended shelf life and convenient dispensing solutions for liquid products.
- Innovations in barrier and film technologies to improve product protection, reduce contamination, and extend shelf life are likely to attract further industry adoption.
- The use of bag-in-box packaging is anticipated to grow in non-food sectors, including chemicals and household products, due to its convenience, safety, and efficient transportability.
- Market participants will prioritize developing lightweight and cost-effective designs that offer improved storage, transportation efficiency, and overall cost savings.
- Companies will focus on strategic partnerships, mergers, and acquisitions to strengthen their market position, enhance R&D capabilities, and drive innovation.
- The development and adoption of biodegradable and plant-based materials will gain momentum, further solidifying the market’s alignment with sustainability goals.
- Efforts to improve the recyclability of multi-layer bag-in-box solutions will continue, addressing a key market restraint and supporting circular economy initiatives.
- The rise of e-commerce and changing consumer preferences for convenient and efficient packaging will drive the adoption of bag-in-box solutions, further expanding market reach.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the North America Bag in Box Market in 2023 and 2032, and what is the CAGR?
What is driving the growth of the North America Bag in Box Market?
Which industries are major users of bag-in-box packaging solutions?
Why is the United States a dominant player in this market?
What trends are shaping the North America Bag in Box Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 North America Bag in Box Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global North America Bag in Box Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 1,077.60 million → 2032: USD 1,784.82 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 North America Bag in Box Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. North America Bag in Box Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 North America Bag in Box Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 North America Bag in Box Market Drivers
- 3.3 North America Bag in Box Market Restraints & Challenges
- 3.4 North America Bag in Box Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 North America Bag in Box Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 North America Bag in Box Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, North America Bag in Box category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 North America Bag in Box Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. North America Bag in Box Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the North America Bag in Box market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 North America Bag in Box Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 North America Bag in Box Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 North America Bag in Box Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in North America Bag in Box (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New North America Bag in Box Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global North America Bag in Box Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America North America Bag in Box Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe North America Bag in Box Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific North America Bag in Box Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America North America Bag in Box Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East North America Bag in Box Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa North America Bag in Box Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. North America Bag in Box Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
