
Market Overview:
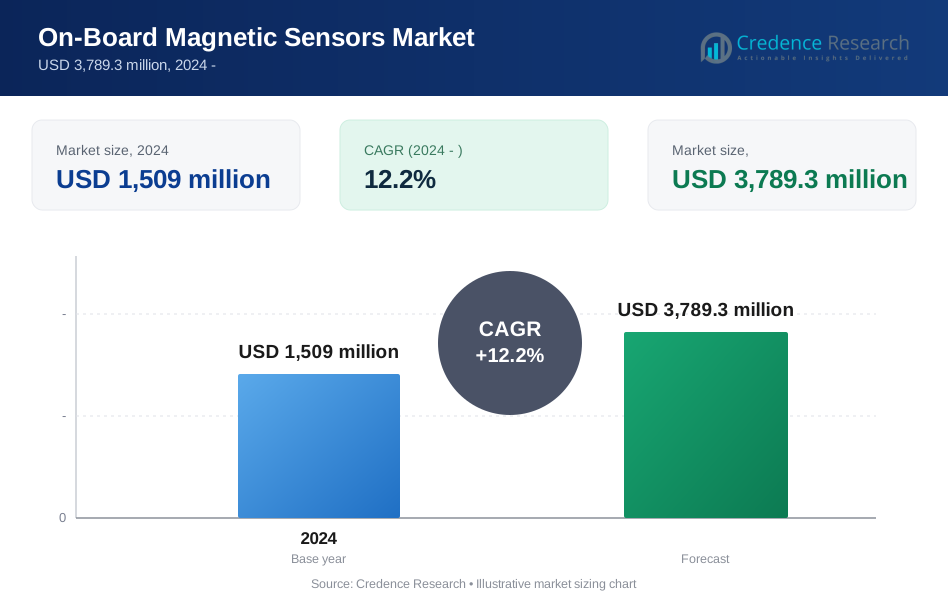
The On board magnetic sensors market is projected to grow from USD 1,509 million in 2024 to USD 3,789.3 million by 2032. The market is expected to expand at a compound annual growth rate of 12.2% from 2024 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| On-Board Magnetic Sensors Market Size 2024 | USD 1,509 million |
| On-Board Magnetic Sensors Market, CAGR | 12.2% |
| On-Board Magnetic Sensors Market Size 2032 | USD 3,789.3 million |
The market grows due to rising vehicle electrification and advanced driver assistance systems adoption. Automakers integrate magnetic sensors for position sensing, speed detection, and current measurement. Electric power steering and battery management systems rely on accurate magnetic sensing. Consumer electronics manufacturers use these sensors for motion tracking and navigation. Industrial automation increases demand for precise motor control and robotics. Improved sensor accuracy and lower power use enhance reliability. Cost-effective manufacturing also supports large-scale deployment.
Asia Pacific leads the market due to strong electronics manufacturing and automotive production hubs. Countries like China, Japan, and South Korea invest heavily in electric vehicles and smart factories. North America follows with high adoption of advanced automotive technologies and aerospace systems. Europe shows steady growth driven by vehicle safety regulations and industrial automation focus. Emerging markets in Southeast Asia gain traction due to expanding electronics assembly bases. Local manufacturing incentives further improve regional demand.

Market Insights:
- The market reached USD 1,509 million in 2024 and is projected to reach USD 3,789.3 million by 2032, expanding at a CAGR of 12.2% during the forecast period.
- Asia-Pacific leads with about 42% share due to strong electronics and automotive manufacturing, followed by North America at 28% driven by advanced vehicle systems, and Europe at 22% supported by automotive safety and industrial automation demand.
- Asia-Pacific is also the fastest-growing region, holding the largest share, driven by electric vehicle expansion, rising consumer electronics output, and strong industrial automation investments.
- By application, automotive accounts for nearly 45% share due to high sensor integration in powertrain, safety, and electric vehicle systems, while consumer electronics hold around 30% supported by high device volumes.
- By type, Hall Effect sensors dominate with approximately 60% share due to cost efficiency and broad usage, while magnetoresistive sensors account for about 40% supported by high-precision applications.
Market Drivers:
Rising Integration Of Sensors Across Automotive Electronic Architectures
The On board magnetic sensors market gains momentum from deeper sensor integration in modern vehicles. Automakers deploy these sensors across steering, braking, and transmission systems. They support accurate position, speed, and current detection. Vehicle safety systems depend on stable sensor feedback. Electrified powertrains increase reliance on magnetic sensing functions. Compact sensor designs fit dense electronic layouts. Reliability under harsh conditions improves OEM confidence. This integration sustains steady demand across vehicle platforms.
- For instance, Infineon Technologies AG states its automotive Hall sensors operate reliably from –40°C to 150°C and meet ISO 26262 functional safety requirements.
Growing Use In Consumer Electronics And Smart Portable Devices
Consumer electronics continue to drive magnetic sensor adoption. Smartphones use sensors for navigation and orientation functions. Wearables rely on precise motion and position detection. Tablets and laptops integrate sensors for hinge and lid sensing. Gaming devices require accurate movement response. Slim device designs favor non-contact sensing solutions. Energy-efficient sensors support longer battery life. High shipment volumes reinforce consistent demand.
- For instance, Apple integrates magnetometers into its iPhone models to enable digital compass functionality, though the company explicitly states that accuracy can be significantly affected by environmental interference and should only be used for basic navigation assistance rather than precise orientation.
Expansion Of Industrial Automation And Motion Control Systems
Industrial automation increases demand for magnetic sensors. These sensors enable precise motor position feedback. Robotics systems rely on stable motion tracking. Conveyor and handling systems use speed and direction sensing. Contactless designs improve durability in harsh environments. Factories value reduced downtime and maintenance needs. Predictive maintenance systems also depend on sensor data. Automation investment supports long-term growth.
Rising Adoption In Renewable Energy And Power Management Systems
Energy infrastructure adopts magnetic sensors for power monitoring. Wind turbines use sensors for rotor position tracking. Solar inverters rely on accurate current measurement. Smart grids require stable sensing for load control. Energy storage systems depend on battery current feedback. Non-intrusive sensing improves system safety. Long service life suits infrastructure assets. Clean energy expansion strengthens demand.
Market Trends:
Shift Toward Miniaturized And High-Sensitivity Sensor Designs
Manufacturers focus on smaller and more sensitive sensor designs. Compact packages support dense circuit layouts. Higher sensitivity improves signal accuracy. Advanced materials enhance magnetic response. Reduced size lowers overall system weight. Consumer devices favor low-profile components. Automotive platforms adopt space-efficient electronics. Miniaturization shapes current product development strategies.
- For instance, Melexis NV introduced magnetoresistive sensors with resolution below 0.1 mT in compact SOIC packages.
Increasing Preference For Contactless Sensing Technologies
Industries show strong preference for contactless sensing. Magnetic sensors reduce mechanical wear. Non-contact operation extends system life. Automotive applications value maintenance-free components. Industrial equipment benefits from improved reliability. Reduced friction improves measurement consistency. Harsh environment tolerance supports wider adoption. This trend influences sensor selection decisions.
- For instance, Allegro MicroSystems, Inc. highlights that its contactless current sensors exceed 20 years of operational life under automotive duty cycles.
Integration Of Sensors With Digital Signal Processing Capabilities
Sensor suppliers integrate processing features on-chip. Digital outputs simplify system integration. Noise reduction improves measurement quality. Built-in calibration enhances performance stability. Embedded diagnostics support fault detection. Automotive electronics favor smart sensor modules. Industrial systems gain faster data response. Integrated intelligence increases overall sensor value.
Rising Demand For Multi-Axis Magnetic Sensing Solutions
Applications increasingly require multi-axis sensing. Robotics systems track motion across multiple directions. Automotive navigation uses three-axis measurement. Consumer devices demand accurate orientation detection. Multi-axis sensors reduce component count. Simplified assembly lowers production complexity. Compact modules enable advanced functions. This trend supports portfolio expansion.
Market Challenges Analysis:
Performance Stability Issues Under Extreme Temperature Conditions
The On board magnetic sensors market faces challenges related to temperature stability. Extreme heat affects sensor accuracy. Automotive environments expose components to thermal cycles. Industrial machinery generates sustained heat stress. Calibration drift impacts measurement reliability. Compensation techniques increase design complexity. Material limits restrict operating ranges. Ensuring stability remains a key challenge.
Cost Pressure And Design Complexity In High-Volume Applications
Manufacturers face strong cost pressure in large-scale production. Automotive suppliers demand competitive pricing. Advanced sensor features increase design complexity. System integration raises development timelines. Testing requirements extend validation cycles. Supply chain disruptions affect component availability. Margin pressure limits innovation flexibility. Balancing cost and performance remains difficult.
Market Opportunities:
Growing Deployment In Electric Mobility And Charging Infrastructure
Electric mobility creates strong growth opportunities. Electric vehicles rely on accurate current sensing. Charging stations use sensors for power regulation. Battery management systems depend on magnetic feedback. Fleet electrification increases sensor volumes. Infrastructure investment supports long-term demand. Non-contact sensing suits high-current applications. This shift opens new revenue streams.
Emerging Applications In Aerospace, Medical, And Smart Infrastructure
Advanced sectors adopt magnetic sensing solutions. Aerospace systems use sensors for actuator control. Medical devices require precise motion detection. Smart buildings integrate sensors for automation. Infrastructure monitoring relies on stable sensing. High reliability standards favor advanced designs. Long lifecycle projects ensure repeat demand. These applications expand market scope.
Market Segmentation Analysis:
By Type
Hall Effect sensors hold a strong position due to cost efficiency and design simplicity. These sensors support position, speed, and current detection across many systems. Automotive and industrial users prefer Hall Effect technology for stable performance. Magnetoresistive sensors show rising adoption due to higher sensitivity and accuracy. These sensors suit applications that require precise field detection. Advanced control systems value their low noise output. Miniaturized designs support compact electronics. Type-based diversification supports broad application coverage.
- For instance, Texas Instruments Inc. offers automotive-grade (AEC-Q100 qualified) Hall-effect sensors, such as the TMAG5170-Q1, which provide high stability with a sensitivity temperature drift as low as ±2.8% and integrated offset adjustment to maintain precision over an operating range of –40°C to 150°C. Additionally, TI's zero-drift current sensors like the TMCS1100-Q1 achieve a maximum full-scale offset drift of <0.1%, effectively delivering sub-microtesla level stability for demanding automotive applications.
By Application / Vertical
The On board magnetic sensors market sees strong demand from the automotive sector. Vehicles use sensors for steering, braking, and powertrain control. Electric and hybrid platforms increase sensor deployment per vehicle. Consumer electronics form another major segment due to high device volumes. Smartphones, wearables, and gaming devices rely on motion and orientation sensing. The industrial segment benefits from automation and robotics expansion. Sensors enable motor control and equipment monitoring. Aerospace and defense applications value reliability under extreme conditions. High precision requirements support steady adoption in this segment.
- For instance, TDK Corporation (Micronas) reports its automotive magnetic sensors support rotational speed detection above 20,000 rpm in transmission systems.
Segmentation:
By Type
- Hall Effect Sensors
- Magnetoresistive Sensors
By Application / Vertical
- Automotive
- Consumer Electronics
- Industrial
- Aerospace & Defense
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia-Pacific Holds The Leading Share With Strong Manufacturing Base
Asia-Pacific accounts for the largest share of the On board magnetic sensors market, at around 42%. The region benefits from strong automotive and electronics manufacturing capacity. China, Japan, and South Korea lead due to high sensor integration rates. Electric vehicle production supports rising sensor demand. Consumer electronics assembly further strengthens regional dominance. Industrial automation investment also supports growth. Large-scale manufacturing keeps unit costs competitive.
North America Maintains A Significant Share Driven By Advanced Technologies
North America holds nearly 28% share of the global market. The region benefits from early adoption of advanced automotive systems. Electric vehicles and ADAS platforms support steady sensor demand. Aerospace and defense applications also drive usage. Strong presence of sensor and semiconductor suppliers improves innovation. Industrial automation adoption remains high. Stable regulatory frameworks support long-term deployment.
Europe And Rest Of The World Show Steady And Emerging Growth Patterns
Europe captures about 22% share due to strong automotive engineering. Germany and France lead with focus on safety and electrification. Industrial automation adoption supports sensor demand. Latin America and Middle East & Africa together account for nearly 8%. These regions show gradual growth due to infrastructure development. Expanding electronics assembly improves adoption rates. Government manufacturing initiatives support future demand.
Key Player Analysis:
- Infineon Technologies AG
- Allegro MicroSystems, Inc.
- TDK Corporation (Micronas)
- Melexis NV
- Texas Instruments Inc.
Competitive Analysis:
The On board magnetic sensors market shows strong competition among global semiconductor and sensor specialists. Leading players focus on sensor accuracy, compact form factors, and automotive-grade reliability. Product portfolios cover Hall Effect and magnetoresistive technologies. Companies invest in process optimization to improve yield and consistency. Strategic partnerships support access to automotive OEMs and Tier-1 suppliers. R&D spending targets higher temperature tolerance and lower power use. Scale advantages help established firms defend margins. Competitive positioning depends on design wins and long-term supply agreements.
Recent Developments:
- In September 2025, Texas Instruments Inc. introduced the TMAG5134, described as the industry’s most sensitive in-plane Hall-effect switch. This new device features an integrated magnetic concentrator that allows it to detect magnetic fields as weak as 1 mT, providing a cost-effective alternative to magnetoresistive technologies like TMR or AMR for high-sensitivity applications. The sensor is designed to offer greater design flexibility by enabling the detection of magnetic fields parallel to the circuit board surface, making it suitable for compact, battery-operated position sensing in industrial and personal electronics.
- In January 2025, Infineon Technologies AG officially formed a new business unit named "SURF" (Sensor Units & Radio Frequency) to consolidate and drive its growth in the sensor market. This strategic reorganization, effective from the start of the year, combines the company's existing sensor and radio frequency businesses into a single dedicated organization within the Power & Sensor Systems division. The move is designed to leverage synergies in research and development to address the growing demand for precision motion control and energy efficiency in automotive and industrial applications, where Infineon’s magnetic sensors play a key enabling role.
- In November 2024, Allegro MicroSystems, Inc. showcased its expanded portfolio of magnetic and inductive sensing solutions at the Electronica trade fair in Munich. The company introduced a new series of micropower magnetic switches and latches designed to reduce system costs and extend battery life for automotive, industrial, and consumer applications. This followed their September 2024 launch of the CT455 and CT456, the first current sensors to utilize the XtremeSense™ Tunnel Magneto-Resistance (TMR) technology acquired from Crocus Technology, offering high bandwidth and improved signal-to-noise ratios for high-power density applications.
- In June 2024, TDK Corporation announced the expansion of its Micronas magnetic sensor portfolio with the launch of the HAL/R 3936, a new stray-field robust 3D-magnetic position sensor. Designed for automotive and industrial applications, this Hall-effect sensor features a defined link between the mechanical angle and the magnetic field vector, allowing for robust rotary and linear position detection even in the presence of strong external magnetic interference. The sensor is part of TDK's strategy to provide highly reliable sensing solutions for safety-critical systems like steering angles and transmission position detection.
- In November 2024, Melexis NV unveiled the MLX90382, a compact absolute magnetic encoder IC designed to provide versatile motion sensing for robotics and industrial automation. This new sensor utilizes Melexis’s proprietary Triaxis® Hall technology to deliver 14-bit resolution and support for both on-axis and off-axis sensing with high stray-field immunity. Earlier in the same month, the company also introduced the MLX90384, the first product featuring its new Arcminaxis® technology, which offers a cost-effective alternative to optical sensors for precise position sensing in robotic joints.
Report Coverage:
The research report offers an in-depth analysis based on By Type and By Application / Vertical. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Vehicle electrification will increase magnetic sensor integration across powertrain and battery systems.
- Compact and lightweight sensor designs will support tighter electronic packaging.
- Multi-axis sensing capability will expand across automotive and industrial platforms.
- Contactless sensing adoption will rise due to durability and low maintenance needs.
- Industrial automation will continue to drive demand for motion and position sensing.
- Consumer electronics will adopt more sensors to support navigation and motion features.
- Aerospace applications will favor sensors with high reliability under extreme conditions.
- Digital output sensors will gain preference for simplified system integration.
- Regional manufacturing localization will strengthen supply chain stability.
- Long-term OEM partnerships will shape competitive positioning.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for On board magnetic sensors market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the On board magnetic sensors market projected to grow between 2025 and 2032?
Which On board magnetic sensors market segment held the largest share in 2024?
What are the primary factors fueling the growth of the On board magnetic sensors market?
Who are the leading companies in the On board magnetic sensors market?
Which region commanded the largest share of the On board magnetic sensors market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 On-Board Magnetic Sensors Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global On-Board Magnetic Sensors Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 1,509 million → forecast year: USD 3,789.3 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 On-Board Magnetic Sensors Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. On-Board Magnetic Sensors Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 On-Board Magnetic Sensors Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 On-Board Magnetic Sensors Market Drivers
- 3.3 On-Board Magnetic Sensors Market Restraints & Challenges
- 3.4 On-Board Magnetic Sensors Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 On-Board Magnetic Sensors Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 On-Board Magnetic Sensors Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, On-Board Magnetic Sensors category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 On-Board Magnetic Sensors Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. On-Board Magnetic Sensors Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the On-Board Magnetic Sensors market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 On-Board Magnetic Sensors Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 On-Board Magnetic Sensors Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 On-Board Magnetic Sensors Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in On-Board Magnetic Sensors (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New On-Board Magnetic Sensors Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global On-Board Magnetic Sensors Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America On-Board Magnetic Sensors Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe On-Board Magnetic Sensors Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific On-Board Magnetic Sensors Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America On-Board Magnetic Sensors Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East On-Board Magnetic Sensors Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa On-Board Magnetic Sensors Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. On-Board Magnetic Sensors Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
