
Market Overview
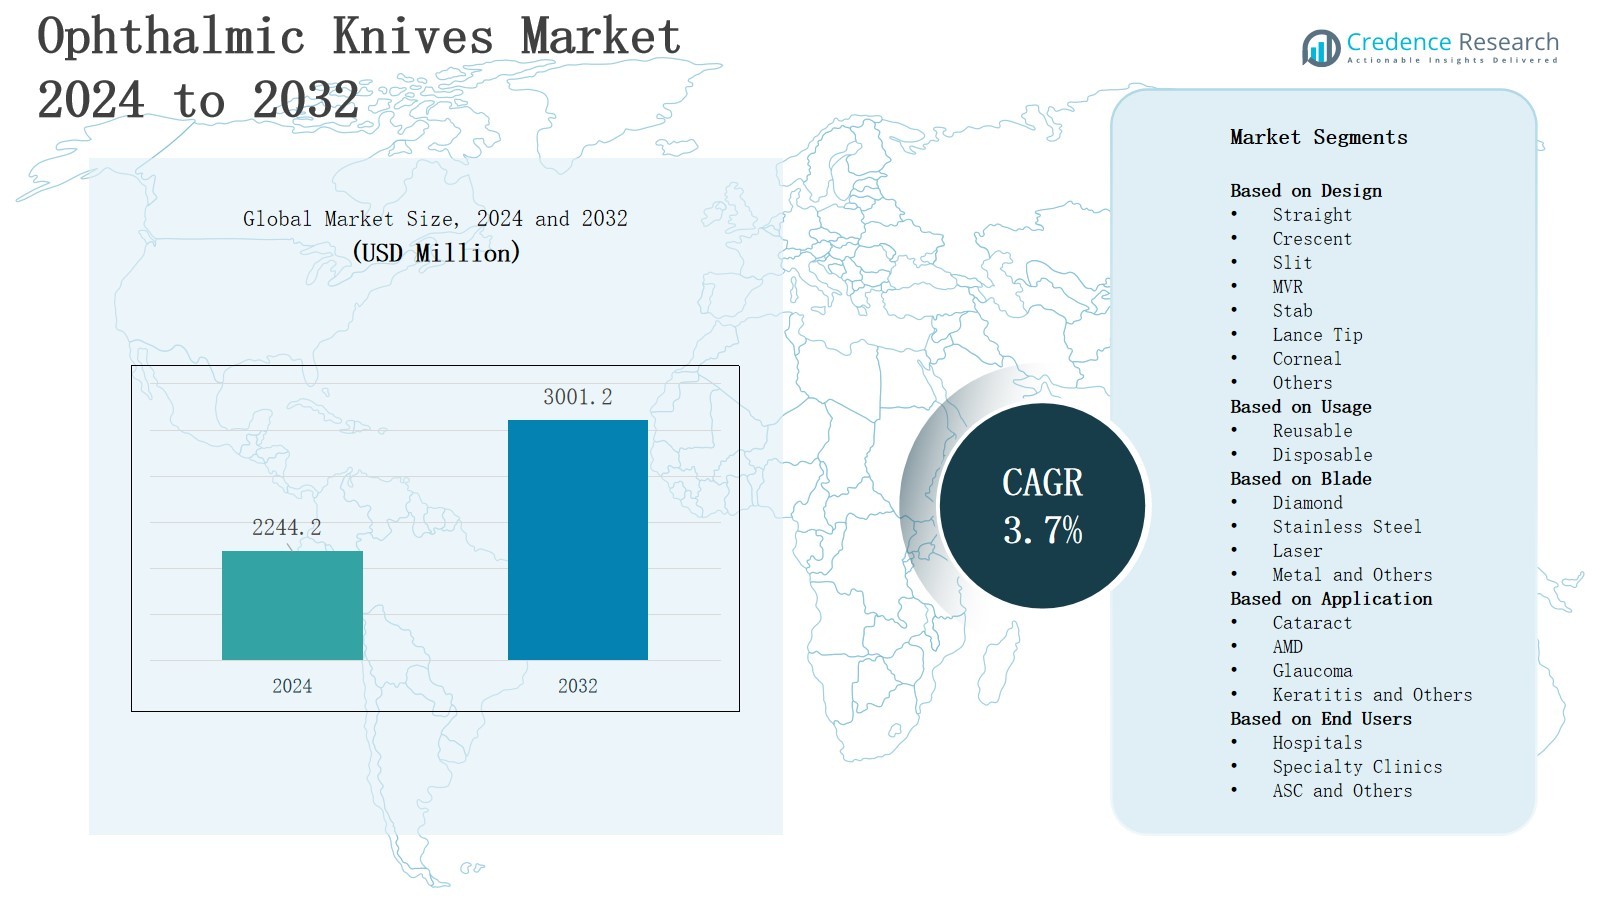
The ophthalmic knives market is projected to grow from USD 2244.2 million in 2024 to USD 3001.2 million by 2032, registering a CAGR of 3.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Ophthalmic Knives Market Size 2024 | USD 2244.2 Million |
| Ophthalmic Knives Market, CAGR | 3.7% |
| Ophthalmic Knives Market Size 2032 | USD 3001.2 Million |
The ophthalmic knives market is driven by the rising prevalence of cataracts, glaucoma, and other eye disorders requiring surgical intervention. Growing demand for minimally invasive procedures and precision surgical tools supports wider adoption across hospitals and specialty clinics. Increasing geriatric populations and improved access to advanced ophthalmic care further strengthen market growth. Technological advancements, including disposable and customizable blades, enhance safety, accuracy, and patient outcomes. Trends highlight a shift toward single-use knives to reduce infection risks, alongside rising investments in advanced surgical equipment. Emerging markets in Asia-Pacific also present opportunities due to expanding healthcare infrastructure and increasing ophthalmic surgeries.
The ophthalmic knives market shows diverse regional dynamics, with North America holding the largest share, followed by Europe and Asia-Pacific as a fast-growing region. Latin America and the Middle East & Africa contribute smaller shares but are expanding with improving healthcare access. Key players driving competition include Alcon, Novartis AG, MANI, INC., Surgical Specialties Corporation, pfm medical ag, Surgistar, Surgi Edge, Eagle Labs, ParamountBlades, Optiedge, Sidapharm, and Shah Eye Care Pvt. Ltd, each focusing on innovation, affordability, and global distribution networks.
Market Insights
- The ophthalmic knives market will grow from USD 2244.2 million in 2024 to USD 3001.2 million by 2032, registering a CAGR of 7%, driven by rising surgical demand.
- Slit knives lead design share at 28%, followed by crescent at 20%, straight and stab at 25%, MVR and lance tip at 15%, and others at 12%.
- Disposable knives dominate usage with 65% share, supported by infection control and efficiency, while reusable knives account for 35%, mainly in cost-sensitive markets with limited hospital budgets.
- By blade type, diamond knives hold 40%, stainless steel follows with 35%, laser-based knives at 15%, and metal or other variants at 10%, showing diverse adoption patterns globally.
- Regionally, North America holds 34%, Europe 27%, Asia-Pacific 25%, Latin America 8%, and Middle East & Africa 6%, reflecting both mature markets and fast-growing emerging economies.
Market Drivers
Rising Prevalence of Eye Disorders
The ophthalmic knives market is primarily driven by the increasing number of patients suffering from cataracts, glaucoma, and refractive errors. These conditions often require surgical intervention, which raises demand for precision surgical tools. The rising incidence of diabetes also contributes to diabetic retinopathy cases, further driving surgical volumes. With growing global awareness about vision health, early diagnosis and timely treatment have become a priority. It strengthens market adoption across hospitals and specialty ophthalmic centers worldwide.
- For instance, a U.S. Centers for Disease Control and Prevention (CDC) study noted that around 1 in 3 diabetics aged 40 or older has signs of diabetic retinopathy, directly fueling the need for advanced ophthalmic surgical care.
Advancements in Surgical Technologies
Theophthalmic knives market benefits from continuous advancements in blade materials, designs, and manufacturing technologies. Manufacturers are developing disposable, customizable, and sharper blades that ensure higher accuracy and reduce surgical complications. Surgeons prefer innovative knives that improve efficiency in delicate eye procedures. It supports adoption in modern surgical practices where precision is critical. Increasing investments in R&D are accelerating product innovation, reinforcing the reliability of advanced ophthalmic surgical instruments in critical eye care.
- For instance, Bausch + Lomb introduced single-use Stellaris Elite knife systems, which provide micro-thin, consistently sharp blades aimed at reducing tissue trauma during phacoemulsification.
Growing Geriatric Population Worldwide
Theophthalmic knives market experiences strong growth due to the expanding aging population, which faces higher risks of cataracts and age-related macular degeneration. Older patients are more likely to undergo ophthalmic surgeries, driving sustained demand for surgical knives. Healthcare systems worldwide are prioritizing elderly care by expanding ophthalmic facilities and services. It fuels higher adoption of advanced surgical instruments. Rising life expectancy continues to widen the patient base, strengthening the long-term market outlook globally.
Increasing Adoption of Minimally Invasive Procedures
Theophthalmic knives market is expanding due to rising demand for minimally invasive eye surgeries that offer quicker recovery and reduced risks. Surgeons are shifting toward advanced microsurgical techniques requiring precision instruments. It drives demand for knives that deliver consistent accuracy in corneal and refractive procedures. Hospitals and clinics are adopting advanced ophthalmic tools to improve patient outcomes. Growing preference for outpatient surgeries supports higher procedural volumes, strengthening market penetration in both developed and emerging economies.
Market Trends
Shift Toward Disposable and Single-Use Knives
Theophthalmic knives market is witnessing a strong shift toward disposable and single-use products due to rising concerns about infection control and patient safety. Hospitals and surgical centers prefer single-use knives as they minimize risks of cross-contamination and reduce sterilization costs. It helps ensure consistent blade sharpness, which is critical in high-precision surgeries. Manufacturers are responding with cost-effective disposable solutions. Growing awareness of hygiene standards worldwide continues to reinforce the demand for single-use ophthalmic knives.
- For instance, the Centers for Disease Control and Prevention (CDC) strongly recommends single-use sterile surgical instruments to eliminate patient-to-patient transmission risks, highlighting that reusable instruments remain a challenge for complete sterilization.
Integration of Advanced Materials and Designs
Theophthalmic knives market is evolving with the use of advanced materials such as diamond, stainless steel, and high-grade alloys to improve sharpness, durability, and precision. Manufacturers are designing innovative blade geometries tailored for specific ophthalmic procedures. It enhances surgical accuracy while reducing tissue trauma and recovery times. Technological developments also focus on ergonomic handles and lightweight structures for surgeon comfort. The trend highlights a commitment to delivering precision-driven tools for complex ophthalmic surgeries.
- For instance, Alcon has developed ultrasonic ophthalmic knives featuring adjustable power settings and vibrating blade tips that reduce tissue trauma during eye surgeries.
Adoption of Minimally Invasive and Outpatient Surgeries
Theophthalmic knives market is expanding due to the rising preference for minimally invasive surgeries that reduce hospital stays and recovery periods. Patients and healthcare providers favor procedures performed in outpatient settings, which require efficient and precise tools. It drives consistent demand for microsurgical knives designed for corneal and refractive operations. Clinics are investing in advanced instruments to meet patient expectations. The trend supports cost efficiency and greater accessibility in both developed and emerging healthcare systems.
Growth in Emerging Economies and Healthcare Access
Theophthalmic knives market is gaining traction in emerging economies where expanding healthcare infrastructure and increasing government initiatives are improving access to eye care. Rising disposable incomes and awareness about ophthalmic health are driving demand for advanced surgical solutions. It encourages global players to strengthen distribution networks and partnerships in these regions. Emerging markets such as India, China, and Brazil are witnessing higher surgical volumes. The trend highlights strong opportunities for growth outside traditional markets.
Market Challenges Analysis
High Cost of Advanced Ophthalmic Knives
Theophthalmic knives market faces a key challenge due to the high cost of advanced surgical instruments, particularly diamond-tipped and premium disposable variants. Many hospitals and clinics in developing regions struggle to afford these tools, limiting adoption rates. It creates a significant gap in access to high-quality eye care. Cost pressures also affect procurement decisions, with some providers relying on reusable knives despite higher maintenance requirements. Price sensitivity in emerging economies remains a barrier to widespread adoption.
Limited Skilled Professionals and Training Requirements
Theophthalmic knives market is challenged by the shortage of skilled ophthalmic surgeons capable of performing complex procedures. Advanced knives require proper handling and training to achieve desired outcomes, which is often lacking in underdeveloped healthcare systems. It leads to inconsistent surgical performance and raises the risk of complications. Training programs and workshops remain limited in many regions, slowing adoption of modern surgical tools. Expanding professional expertise is critical for ensuring consistent global market growth.
Market Opportunities
Rising Demand in Emerging Economies
The ophthalmic knives market holds significant opportunity in emerging economies where healthcare infrastructure is expanding rapidly. Rising disposable incomes, government initiatives, and awareness campaigns on vision health are creating strong demand for advanced surgical tools. It opens pathways for manufacturers to penetrate underserved regions with affordable and high-quality solutions. Strategic partnerships with local distributors enhance product availability. Growing numbers of ophthalmic surgeries in Asia-Pacific, Latin America, and Africa highlight untapped potential for long-term market expansion.
Technological Advancements and Product Innovation
The ophthalmic knives market benefits from growing opportunities driven by advancements in blade design, material innovation, and ergonomic features. Development of disposable and customizable products enhances patient safety and surgical precision. It supports the increasing demand for minimally invasive procedures requiring consistent accuracy. Manufacturers investing in R&D can capture competitive advantages through differentiated product portfolios. Rising adoption of digital platforms for training and global collaborations further strengthen opportunities for sustained growth in this market.
Market Segmentation Analysis:
By Design
In the ophthalmic knives market, slit knives hold the dominant share of around 28% due to their precision and versatility in cataract and refractive surgeries. Crescent knives account for nearly 20%, supported by demand in corneal tunnel creation. Straight and stab designs together represent about 25%, preferred for general incisions. MVR and lance tip knives capture around 15%, while corneal and other specialty designs make up the remaining 12%. Rising surgical volumes and need for specialized blades drive this segment.
- For instance, Beaver-Visitec International’s crescent knives are specifically designed for scleral tunnel and limbal relaxing incisions, making them common in corneal graft surgeries.
By Usage
Disposable knives dominate the ophthalmic knives market with a share of nearly 65%, driven by infection control, cost-efficiency in sterilization, and consistent sharpness in high-volume surgeries. Reusable knives hold the remaining 35%, largely preferred in cost-sensitive markets where hospitals balance affordability with longevity. It reflects a clear shift toward single-use instruments, supported by global hygiene regulations and patient safety concerns. Growing adoption in both developed and emerging regions continues to strengthen disposable knife demand.
- For instance, Bausch & Lomb offers Storz Ophthalmic single-use knives, designed to minimize cross-contamination and reduce the burden of sterilization in surgical centers.
By Blade
Diamond blades lead the ophthalmic knives market with a share of about 40%, valued for exceptional sharpness, durability, and precision in delicate eye surgeries. Stainless steel accounts for nearly 35%, favored for affordability and widespread availability. Laser-based knives hold close to 15%, gaining traction with advanced technology adoption. Metal and other variants represent the remaining 10%, catering to specific surgical requirements. It highlights a balance between premium precision tools and cost-effective alternatives across healthcare systems.
Segments:
Based on Design
- Straight
- Crescent
- Slit
- MVR
- Stab
- Lance Tip
- Corneal
- Others
Based on Usage
- Reusable
- Disposable
Based on Blade
- Diamond
- Stainless Steel
- Laser
- Metal and Others
Based on Application
- Cataract
- AMD
- Glaucoma
- Keratitis and Others
Based on End Users
- Hospitals
- Specialty Clinics
- ASC and Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds the largest share of the ophthalmic knives market at 34%, supported by advanced healthcare infrastructure and high adoption of innovative surgical tools. The region benefits from a growing elderly population and rising prevalence of cataracts and glaucoma. It is further strengthened by significant investments in ophthalmic research and clinical advancements. Strong presence of leading manufacturers ensures steady supply and product innovation. Favorable reimbursement policies and specialized surgical centers continue to expand market growth.
Europe
Europe accounts for 27% of the ophthalmic knives market, driven by strong demand for advanced eye care solutions and strict regulatory frameworks supporting patient safety. The region’s aging population fuels higher incidences of eye disorders requiring surgical intervention. It is supported by extensive healthcare coverage and investments in ophthalmic technologies. Increasing adoption of disposable knives for infection control enhances growth. Collaboration between research institutions and medical device manufacturers reinforces innovation in precision surgical tools.
Asia-Pacific
Asia-Pacific captures 25% of the ophthalmic knives market, making it the fastest-growing region due to expanding healthcare access and rising awareness about vision health. Large populations in China and India contribute significantly to surgical volumes, especially in cataract treatments. It benefits from government initiatives aimed at reducing blindness and improving ophthalmic infrastructure. Growing middle-class income levels increase affordability of advanced surgical instruments. Global manufacturers are strengthening distribution networks to meet rising demand in this region.
Latin America
Latin America represents 8% of the ophthalmic knives market, supported by improving healthcare facilities and expanding medical tourism. Countries such as Brazil and Mexico are leading contributors due to increasing cataract surgeries. It faces challenges with limited healthcare budgets but benefits from rising awareness about eye care. Disposable surgical knives are gaining preference for cost-effective safety. International partnerships and local investments are helping enhance accessibility to advanced ophthalmic surgical instruments in the region.
Middle East & Africa
The Middle East & Africa holds 6% of the ophthalmic knives market, characterized by gradual improvements in healthcare systems and rising demand for specialized surgeries. GCC countries contribute strongly due to higher investments in advanced medical facilities. It faces constraints in terms of affordability and availability of trained professionals. International players are expanding presence to meet growing demand. Government health initiatives and nonprofit programs further support access to ophthalmic surgical care across developing areas.
Key Player Analysis
- Surgical Specialties Corporation (U.S.)
- Optiedge (India)
- MANI, INC. (Japan)
- Alcon (Switzerland)
- Sidapharm (India)
- Eagle Labs (U.S.)
- Novartis AG (Switzerland)
- ParamountBlades (India)
- Shah Eye Care Pvt. Ltd (India)
- Surgistar (U.S.)
- pfm medical ag (Germany)
- Surgi Edge (U.S.)
Competitive Analysis
The ophthalmic knives market is highly competitive, with global and regional players focusing on product innovation, cost efficiency, and distribution strength to secure market share. It is shaped by strong participation from companies such as Alcon, Novartis AG, MANI, INC., Surgical Specialties Corporation, and pfm medical ag, which emphasize advanced blade technologies and precision tools. U.S.-based players like Surgistar, Surgi Edge, and Eagle Labs drive growth through high-quality disposable products tailored for infection control. Indian companies including ParamountBlades, Optiedge, Sidapharm, and Shah Eye Care Pvt. Ltd strengthen their presence by offering affordable solutions for developing markets. It reflects a balance between established multinationals with advanced portfolios and regional firms leveraging cost advantages. Competitive strategies focus on expanding into emerging economies, securing hospital partnerships, and developing customized surgical solutions. Growing demand for minimally invasive eye procedures drives innovation, with manufacturers investing in disposable, diamond, and stainless steel blade variants to address diverse surgical needs while maintaining precision and safety standards in ophthalmic care.
Recent Developments
- In March 2025, Alcon completed the acquisition of LENSAR, developer of the ALLY Robotic Cataract Laser Treatment System, in a transaction valued at USD 356 million.
- In April 2025, Microsurgical Technology (MST) entered a strategic partnership with MANI, Inc. to distribute MANI’s ophthalmic surgical blades, cannulas, and other disposable instruments in the U.S. market.
- In 2024, HumanOptics introduced a refreshed brand identity during the DOC Congress in Nuremberg, unveiling a new line of disposable ophthalmic surgical knives
- In 2023, BVI acquired Medical Mix in Europe, expanding its product portfolio of ophthalmic surgical instruments and strengthening its regional market presence.
Report Coverage
The research report offers an in-depth analysis based on Design, Usage, Blade, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Rising demand for precision surgical tools will continue to drive adoption in ophthalmic surgeries globally.
- Disposable knives will witness stronger acceptance due to growing emphasis on infection prevention and patient safety.
- Diamond blades will maintain dominance, supported by their durability, sharpness, and preference in delicate surgeries.
- Technological advancements in blade design will improve accuracy, surgeon comfort, and surgical outcomes in complex procedures.
- Increasing geriatric population will create higher demand for cataract and glaucoma surgeries using advanced knives.
- Emerging economies will offer strong growth opportunities with improving healthcare infrastructure and growing surgical volumes.
- Training initiatives for ophthalmic surgeons will expand, improving safe adoption of advanced surgical instruments worldwide.
- Strategic collaborations among global and regional manufacturers will enhance product availability and strengthen market presence.
- Shift toward minimally invasive procedures will boost demand for precision-driven, single-use ophthalmic surgical knives.
- Regulatory support for safety standards will encourage innovation in reusable and disposable ophthalmic knife solutions.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Eye Disorders
Increasing cases of cataracts, glaucoma, and diabetic retinopathy are driving the need for ophthalmic surgeries, directly boosting demand for precision surgical knives.
Shift Toward Minimally Invasive Procedures
Surgeons and healthcare facilities are increasingly adopting minimally invasive eye surgeries, which require advanced, precision knives for better outcomes and faster patient recovery.
Technological Advancements in Blade Materials and Design
Continuous innovation in blade materials such as diamond and stainless steel, along with ergonomic and customizable designs, is enhancing surgical accuracy and safety, encouraging wider adoption.
Growing Geriatric Population
The expanding elderly demographic is more susceptible to age-related eye conditions, resulting in higher surgical volumes and sustained demand for ophthalmic knives.
Increased Adoption of Disposable and Single-Use Knives
Heightened focus on infection control and patient safety is accelerating the shift toward disposable knives, especially in high-volume surgical centers and regions with strict hygiene regulations.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for ophthalmic knives market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the ophthalmic knives market projected to grow between 2025 and 2032?
Which ophthalmic knives market segment held the largest share in 2024?
What are the primary factors fueling the growth of the ophthalmic knives market?
Who are the leading companies in the ophthalmic knives market?
Which region commanded the largest share of the ophthalmic knives market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Blade
- 1.2.1 Diamond
- 1.2.2 Stainless Steel
- 1.2.3 Laser
- 1.2.4 Metal and Others
- 1.3 By Usage
- 1.3.1 Disposable
- 1.3.2 Reusable
- 1.4 By Design
- 1.4.1 Slit
- 1.4.2 Crescent
- 1.4.3 Straight & Stab
- 1.4.4 MVR & Lance Tip
- 1.4.5 Corneal & Others
- 1.5 By Application
- 1.5.1 Cataract
- 1.5.2 AMD
- 1.5.3 Glaucoma
- 1.5.4 Keratitis and Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2244.2 million → 2032: USD 3,001.2 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Ophthalmic Knives Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Ophthalmic Knives Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Ophthalmic Knives Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Ophthalmic Knives Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Ophthalmic Knives Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Ophthalmic Knives Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Ophthalmic Knives Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Ophthalmic Knives Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2244.2 million → 2032: USD 3,001.2 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Ophthalmic Knives Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Blade - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Diamond
- 12.3.7.2 Stainless Steel
- 12.3.7.3 Laser
- 12.3.7.4 Metal and Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Usage - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Disposable
- 12.4.7.2 Reusable
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Design - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Slit
- 12.5.7.2 Crescent
- 12.5.7.3 Straight & Stab
- 12.5.7.4 MVR & Lance Tip
- 12.5.7.5 Corneal & Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Cataract
- 12.6.7.2 AMD
- 12.6.7.3 Glaucoma
- 12.6.7.4 Keratitis and Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Ophthalmic Knives End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Ophthalmic Knives Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Ophthalmic Knives Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Ophthalmic Knives Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Alcon
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Novartis AG
- 18.4 MANI, INC.
- 18.5 Surgical Specialties Corporation
- 18.6 pfm medical ag
- 18.7 Surgistar
- 18.8 Surgi Edge
- 18.9 Eagle Labs
- 18.10 Optiedge
- 18.11 Sidapharm
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

