
Airway Clearance System Market Overview:
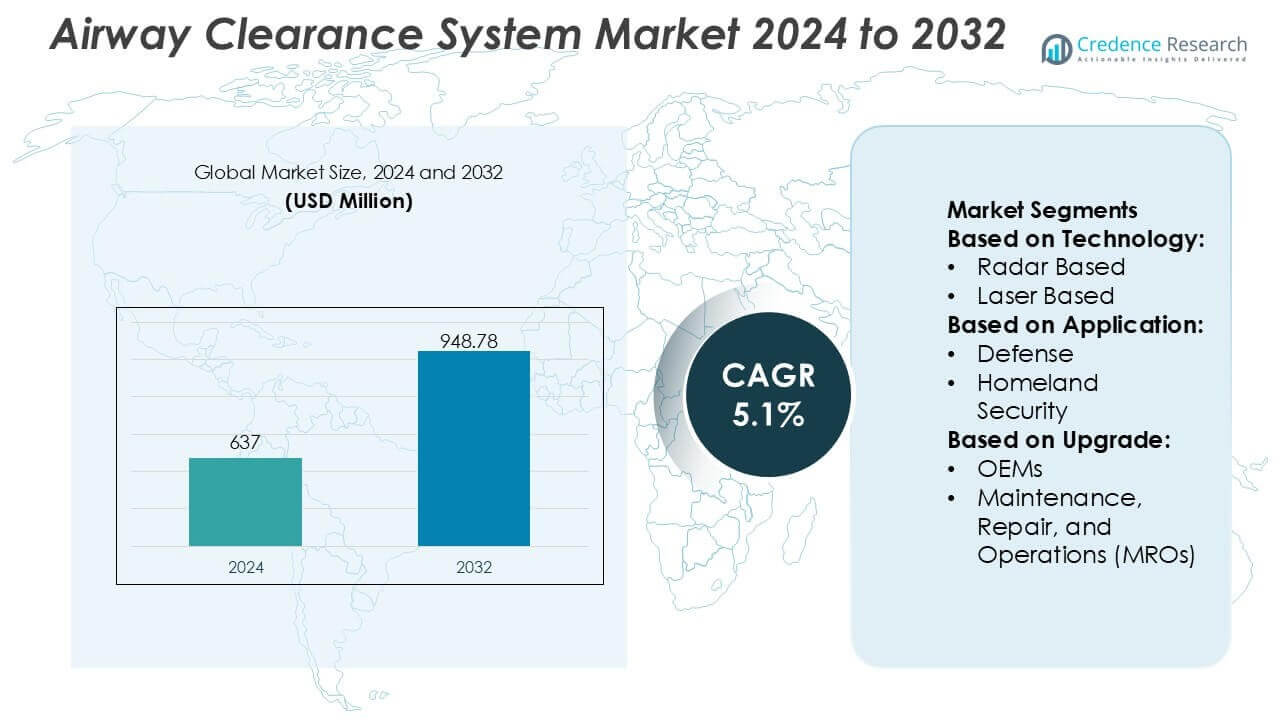
Airway Clearance System Market size was valued USD 637 million in 2024 and is anticipated to reach USD 948.78 million by 2032, at a CAGR of 5.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Airway Clearance System Market Size 2024 | USD 637 million |
| Airway Clearance System Market , CAGR | 5.1% |
| Airway Clearance System Market Size 2032 | USD 948.78 million |
Airway Clearance System Market Insights
- Market growth is primarily driven by increasing prevalence of COPD, cystic fibrosis, and bronchiectasis, alongside expanding adoption of homecare-based airway clearance devices that reduce hospital dependency.
- Key market trends include growing use of high-frequency chest wall oscillation systems, which represent the dominant technology segment due to superior mucus mobilization efficiency and high patient compliance.
- Competitive intensity remains moderate, with established medical device manufacturers and specialized respiratory care companies competing on clinical performance, portability, and integration with respiratory therapy workflows, while pricing pressure remains a restraint in cost-sensitive markets.
- Regionally, North America leads with an exact 38% market share, driven by advanced healthcare infrastructure and reimbursement support, while Asia-Pacific shows faster growth due to improving respiratory care access and rising chronic disease awareness.
Airway Clearance System Market Segmentation Analysis:
By Technology
By technology, radar-based airway clearance systems dominate the market with an estimated 46% market share, driven by their long-range detection capability, all-weather performance, and high reliability in real-time obstacle identification. Radar systems effectively detect aircraft, drones, terrain obstructions, and foreign objects during takeoff, landing, and taxiing operations, making them essential for continuous airport surveillance. Laser-based systems follow, supported by high-resolution spatial mapping and precise object discrimination in controlled environments, while sonar-based technologies remain niche, primarily used in specialized low-visibility or enclosed operational settings.
- For instance, PARI’s airway clearance technology operates across oscillation frequencies from 5 Hz to 20 Hz to mobilize secretions, while its eFlow® rapid nebulizer system delivers aerosol with a mass median aerodynamic diameter (MMAD) of approximately 4.1 µm and an aerosol output rate exceeding 0.5 g/min.
By Application
By application, the defense segment leads the Airway Clearance System Market, accounting for approximately 52% market share, supported by rising investments in military airbase safety, tactical airspace monitoring, and unmanned aerial system detection. Defense forces prioritize advanced airway clearance technologies to ensure uninterrupted flight operations in contested and high-risk environments. Homeland security applications are expanding steadily, driven by increasing airport security mandates, border surveillance requirements, and the need to mitigate airborne threats near critical infrastructure, including civilian airports and government aviation facilities.
- For instance, Smiths Group plc, through its Smiths Detection division, has deployed advanced aviation and airspace security technologies such as the HI-SCAN 10080 XCT, which operates at X-ray energies up to 180 keV, processes up to 1,800 bags per hour, and achieves spatial resolution down to 0.2 mm, while its SDX 6040 X-ray inspection systems deliver penetration capability exceeding 35 mm of steel, demonstrating verified, high-performance detection metrics aligned with defense and homeland security aviation safety requirements.
By Upgrade
By upgrade, Maintenance, Repair, and Operations (MROs) represent the dominant sub-segment with around 58% market share, driven by the growing emphasis on upgrading existing airport and airbase infrastructure rather than full system replacement. MRO upgrades enable integration of advanced sensors, improved data processing modules, and enhanced software analytics into legacy systems at lower cost and reduced downtime. OEM-led upgrades continue to grow, supported by next-generation system deployments at new airports and military installations, but retrofit-focused MRO solutions remain the primary driver of market demand.
Key Growth Drivers
Rising Prevalence of Chronic Respiratory Diseases
The growing global burden of chronic respiratory conditions, including chronic obstructive pulmonary disease (COPD), cystic fibrosis, bronchiectasis, and neuromuscular disorders, is a primary growth driver for the airway clearance system market. Increasing exposure to air pollution, smoking, occupational hazards, and aging populations significantly elevate mucus retention risks, necessitating effective airway management. Healthcare systems increasingly emphasize long-term disease management rather than acute intervention, driving consistent demand for airway clearance devices across hospitals, clinics, and homecare settings, particularly for patients requiring regular, non-invasive respiratory support.
- For instance, Baxter following its integration of Hillrom supports airway clearance therapy through The Vest® Airway Clearance System, which delivers high-frequency chest wall oscillation across programmable frequencies from 5 Hz to 25 Hz with calibrated pressure control reaching up to 50 cmH₂O, and therapy sessions configurable in cycle durations as short as 1 minute, reflecting documented engineering parameters designed for chronic respiratory disease management backed by Baxter and Hillrom product specifications.
Technological Advancements in Airway Clearance Devices
Continuous innovation in device design and therapy delivery significantly accelerates market growth. Manufacturers are integrating programmable pressure settings, oscillation frequency control, digital monitoring, and portable designs to enhance treatment efficacy and patient comfort. Advances in high-frequency chest wall oscillation and positive expiratory pressure technologies improve mucus mobilization while reducing therapy time. These improvements support broader clinical adoption across pediatric, adult, and geriatric populations and strengthen physician confidence in prescribing airway clearance systems as part of standardized respiratory care protocols.
- For instance, Dymedso’s Frequencer® platform is engineered to deliver targeted Digital Acoustic Pulse (DAP) therapy at oscillation frequencies adjustable between 20 Hz and 65 Hz, with a clinical optimum typically set at 40 Hz.
Shift Toward Homecare and Outpatient Respiratory Management
The increasing preference for home-based respiratory therapy is a major driver shaping the airway clearance system market. Healthcare providers aim to reduce hospital stays and associated costs while improving patient quality of life. Compact, user-friendly airway clearance systems enable self-administered therapy, supporting adherence and long-term disease control. This shift is reinforced by rising healthcare expenditures, limited hospital capacity, and reimbursement support for durable medical equipment, positioning homecare-focused airway clearance solutions as a critical component of modern respiratory care delivery.
Key Trends & Opportunities
Integration of Digital Health and Remote Monitoring
A key trend in the airway clearance system market is the integration of digital health capabilities, including connectivity, therapy tracking, and remote monitoring. Smart airway clearance devices allow clinicians to assess patient adherence, therapy effectiveness, and usage patterns in real time. This data-driven approach enhances clinical outcomes and supports personalized treatment plans. The trend creates opportunities for manufacturers to differentiate offerings through software-enabled platforms, subscription-based services, and data analytics, aligning airway clearance therapy with broader telehealth and remote patient management ecosystems.
- For instance, Electromed’s SmartVest® Connect system incorporates integrated Bluetooth and cellular connectivity to transmit therapy data, capturing parameters such as oscillation frequency ranges from 5 Hz to 20 Hz, session durations measured in one-minute increments, and applied pressure levels consistent with HFCWO therapeutic standards.
Expanding Pediatric and Geriatric Applications
Growing focus on age-specific respiratory care represents a significant opportunity for market expansion. Pediatric patients with cystic fibrosis and congenital respiratory disorders require tailored airway clearance solutions with adjustable pressure and safety controls. Similarly, the aging population increasingly faces reduced lung function and mobility limitations. Manufacturers are developing ergonomically designed, low-noise, and easy-to-use systems to address these demographics. Targeted product development for pediatric and geriatric segments supports higher adoption rates and long-term therapy continuity across diverse patient populations.
- For instance, Med Systems’ Electro Flo® 5000 Airway Clearance System delivers rhythmic percussive therapy with calibrated airflow patterns optimized for secretion mobilization and weighs just 6 pounds.
Emerging Markets and Improved Healthcare Access
Improving healthcare infrastructure and rising respiratory disease awareness in emerging economies present strong growth opportunities. Expanding access to diagnostic services and respiratory specialists increases identification of conditions requiring airway clearance therapy. Government initiatives aimed at strengthening chronic disease management and homecare services further support market penetration. As affordability improves and localized manufacturing expands, airway clearance systems are increasingly adopted beyond developed regions, enabling manufacturers to diversify revenue streams and strengthen global market presence.
Key Challenges
High Device Costs and Reimbursement Limitations
The relatively high cost of advanced airway clearance systems poses a significant challenge, particularly in price-sensitive markets. Limited or inconsistent reimbursement policies across regions restrict patient access and delay therapy adoption. In some healthcare systems, airway clearance devices are categorized as non-essential or face lengthy approval processes for coverage. These financial barriers impact purchasing decisions by hospitals and homecare providers, compelling manufacturers to balance innovation with cost optimization while navigating complex reimbursement landscapes.
Patient Compliance and Therapy Adherence Issues
Ensuring consistent patient adherence remains a critical challenge for the airway clearance system market. Some patients experience discomfort, fatigue, or inconvenience during therapy sessions, leading to irregular usage and reduced clinical effectiveness. Elderly patients and children often require caregiver support, further complicating adherence. Inadequate training and limited follow-up can also hinder proper device usage. Addressing these challenges requires simplified device designs, enhanced patient education, and clinician engagement to ensure sustained therapy compliance and optimal treatment outcomes.
Regional Analysis
North America
North America dominates the airway clearance system market with an estimated 38% market share, supported by advanced respiratory care infrastructure, high prevalence of chronic obstructive pulmonary disease (COPD), cystic fibrosis, and neuromuscular disorders, and strong reimbursement coverage. The United States leads regional demand due to widespread adoption of high-frequency chest wall oscillation (HFCWO) devices, positive expiratory pressure systems, and integrated digital monitoring solutions. Continuous product innovation, rapid uptake of homecare-based airway clearance therapies, and strong presence of established manufacturers further reinforce market leadership. Canada contributes steadily, supported by public healthcare funding and rising focus on long-term respiratory disease management.
Europe
Europe accounts for approximately 29% of the global airway clearance system market, driven by a high burden of chronic respiratory diseases, aging populations, and well-established pulmonary rehabilitation programs. Countries such as Germany, the UK, France, and Italy lead adoption due to strong hospital networks and increasing use of home-based airway clearance devices. Favorable regulatory frameworks, emphasis on evidence-based respiratory therapies, and growing integration of physiotherapy-led airway management support market growth. Eastern European countries show gradual expansion as healthcare spending improves. The region also benefits from strong clinical guidelines promoting non-invasive airway clearance techniques across pediatric and adult patient populations.
Asia-Pacific
Asia-Pacific holds around 21% market share and represents the fastest-growing regional market for airway clearance systems. Rising prevalence of asthma, bronchiectasis, and post-tuberculosis lung disease, particularly in China and India, significantly drives demand. Expanding healthcare infrastructure, increasing awareness of advanced respiratory therapies, and rapid growth of homecare services support market expansion. Japan and South Korea contribute through early adoption of technologically advanced airway clearance devices, while Southeast Asia shows growing uptake due to improving access to respiratory care. Government initiatives to strengthen chronic disease management and rising healthcare expenditure further accelerate regional growth.
Latin America
Latin America represents nearly 7% of the airway clearance system market, supported by increasing diagnosis rates of chronic respiratory conditions and gradual modernization of healthcare systems. Brazil and Mexico lead regional demand due to expanding hospital capacity and growing awareness of non-invasive airway clearance therapies. Adoption remains concentrated in urban centers, where access to pulmonology services and respiratory physiotherapy is stronger. Although reimbursement limitations and cost sensitivity restrict rapid penetration, rising private healthcare investments and increasing homecare adoption are improving market prospects. Regional growth is further supported by training initiatives focused on respiratory disease management.
Middle East & Africa
The Middle East & Africa region accounts for approximately 5% market share, reflecting early-stage but steadily improving adoption of airway clearance systems. Gulf Cooperation Council countries drive demand through advanced hospital infrastructure, rising prevalence of chronic respiratory diseases, and increasing investment in specialized respiratory care. In contrast, adoption across Africa remains limited due to constrained healthcare budgets and uneven access to pulmonary specialists. However, growing awareness of non-invasive respiratory therapies, expanding private healthcare facilities, and international support programs for chronic lung disease management are gradually improving market penetration and long-term growth potential across the region.
Airway Clearance System Market Segmentations:
By Technology:
- Radar Based
- Laser Based
By Application:
- Defense
- Homeland Security
By Upgrade:
- OEMs
- Maintenance, Repair, and Operations (MROs)
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The airway clearance system market players such as PARI GmbH, Smiths Group plc, Baxter, Dymedso, VYAIRE, AbbVie Inc., Med Systems, Inc., Koninklijke Philips N.V., Electromed, Inc., General Physiotherapy II LLC. The airway clearance system market is characterized by moderate consolidation and strong competition centered on clinical performance, therapy effectiveness, and usability across hospital and homecare settings.
Market participants prioritize the development of non-invasive airway clearance technologies, including high-frequency chest wall oscillation and positive expiratory pressure systems, to address chronic respiratory disorders such as COPD, cystic fibrosis, and bronchiectasis. Competitive differentiation increasingly depends on device portability, noise reduction, patient adherence features, and integration with respiratory therapy workflows.
Companies also compete through regulatory approvals, reimbursement alignment, and expansion of homecare distribution channels. Ongoing investments in R&D, clinician training, and post-sales support strengthen brand positioning, while partnerships with healthcare providers and respiratory therapists support sustained adoption and long-term market growth.
Key Player Analysis
- PARI GmbH
- Smiths Group plc
- Baxter
- Dymedso
- VYAIRE
- AbbVie Inc
- Med Systems, Inc.
- Koninklijke Philips N.V.
- Electromed, Inc
- General Physiotherapy II LLC
Recent Developments
- In September 2024, KUBRA and Advanced Utility Systems (AUS) announced a strategic partnership integrate KUBRA's CX solutions with AUS's Infinity CIS, aiming to provide utilities with a unified, seamless platform for billing, payments, communications, and overall customer engagement, enhancing efficiency and meeting evolving customer expectations.
- In April 2024, Hansen Technologies and AWS have a long-standing partnership, with Hansen using the AWS cloud infrastructure to deliver its cloud-native applications to customers in the communications, energy, and utilities industries.
- In March 2024, Kaleris, a provider of cloud-based supply chain software solutions launched new capabilities in its yard management system (YMS) to enhance efficiency and safety in yard operations.
Report Coverage
The research report offers an in-depth analysis based on Technology, Application, Upgrade and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Adoption of home-based airway clearance therapies will accelerate as healthcare systems shift toward outpatient and long-term chronic disease management.
- Technological innovation will focus on improving therapy personalization through adjustable oscillation frequencies and pressure control mechanisms.
- Integration of digital monitoring and data connectivity will enhance treatment adherence and clinician oversight.
- Demand for non-invasive airway clearance solutions will rise due to growing prevalence of chronic respiratory and neuromuscular disorders.
- Manufacturers will emphasize compact, lightweight, and portable device designs to improve patient comfort and mobility.
- Expanding geriatric populations will increase the need for effective mucus clearance solutions in long-term care settings.
- Regulatory support and updated clinical guidelines will strengthen adoption of evidence-based airway clearance therapies.
- Emerging markets will witness faster uptake driven by improving respiratory care infrastructure and awareness.
- Strategic collaborations with homecare providers and respiratory therapists will strengthen market penetration.
- Sustainability considerations and durable device designs will gain importance in procurement decisions across healthcare facilities.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Chronic Respiratory Diseases
The increasing incidence of chronic respiratory conditions such as COPD, cystic fibrosis, and bronchiectasis is driving demand for airway clearance systems, as these devices are essential for effective long-term disease management and reducing hospitalizations.
Technological Advancements in Airway Clearance Devices
Continuous innovation, including programmable pressure settings, digital monitoring, and portable designs, is enhancing therapy efficacy and patient comfort, leading to broader adoption across diverse patient populations and care settings.
Shift Toward Homecare and Outpatient Respiratory Management
Healthcare systems are prioritizing home-based and outpatient respiratory therapies to reduce hospital dependency and costs, fueling demand for compact, user-friendly airway clearance systems that support self-administered treatment.
Integration of Digital Health and Remote Monitoring
The adoption of smart airway clearance devices with connectivity and real-time therapy tracking is improving patient adherence and enabling clinicians to personalize treatment, which supports better clinical outcomes and market growth.
Expanding Access in Emerging Markets
Improved healthcare infrastructure, rising awareness of respiratory diseases, and government initiatives in emerging economies are increasing the adoption of airway clearance systems, contributing to faster market growth outside traditional developed regions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Airway Clearance System Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Airway Clearance System Market projected to grow between 2024 and 2032?
Which Airway Clearance System Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Airway Clearance System Market?
Who are the leading companies in the Airway Clearance System Market?
Which region commanded the largest share of the Airway Clearance System Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Upgrade
- 1.2.1 OEMs
- 1.2.2 Maintenance, Repair, and Operations (MROs)
- 1.3 By Technology
- 1.3.1 Radar Based
- 1.3.2 Laser Based
- 1.3.3 Sonar Based
- 1.4 By Application
- 1.4.1 Defense
- 1.4.2 Homeland Security
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 637 million → 2032: USD 948.78 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Airway Clearance System Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Airway Clearance System Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Airway Clearance System Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Airway Clearance System Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Airway Clearance System Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Airway Clearance System Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Airway Clearance System Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Airway Clearance System Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 637 million → 2032: USD 948.78 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Airway Clearance System Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Upgrade - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 OEMs
- 12.3.7.2 Maintenance, Repair, and Operations (MROs)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Radar Based
- 12.4.7.2 Laser Based
- 12.4.7.3 Sonar Based
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Defense
- 12.5.7.2 Homeland Security
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Airway Clearance System End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Airway Clearance System Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Airway Clearance System Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Airway Clearance System Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 PARI GmbH
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Smiths Group plc
- 18.4 Baxter
- 18.5 Dymedso
- 18.6 VYAIRE
- 18.7 AbbVie Inc.
- 18.8 Med Systems, Inc.
- 18.9 Koninklijke Philips N.V.
- 18.10 Electromed, Inc.
- 18.11 General Physiotherapy II LLC
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

