
Self-care and wider nonprescription access lift demand
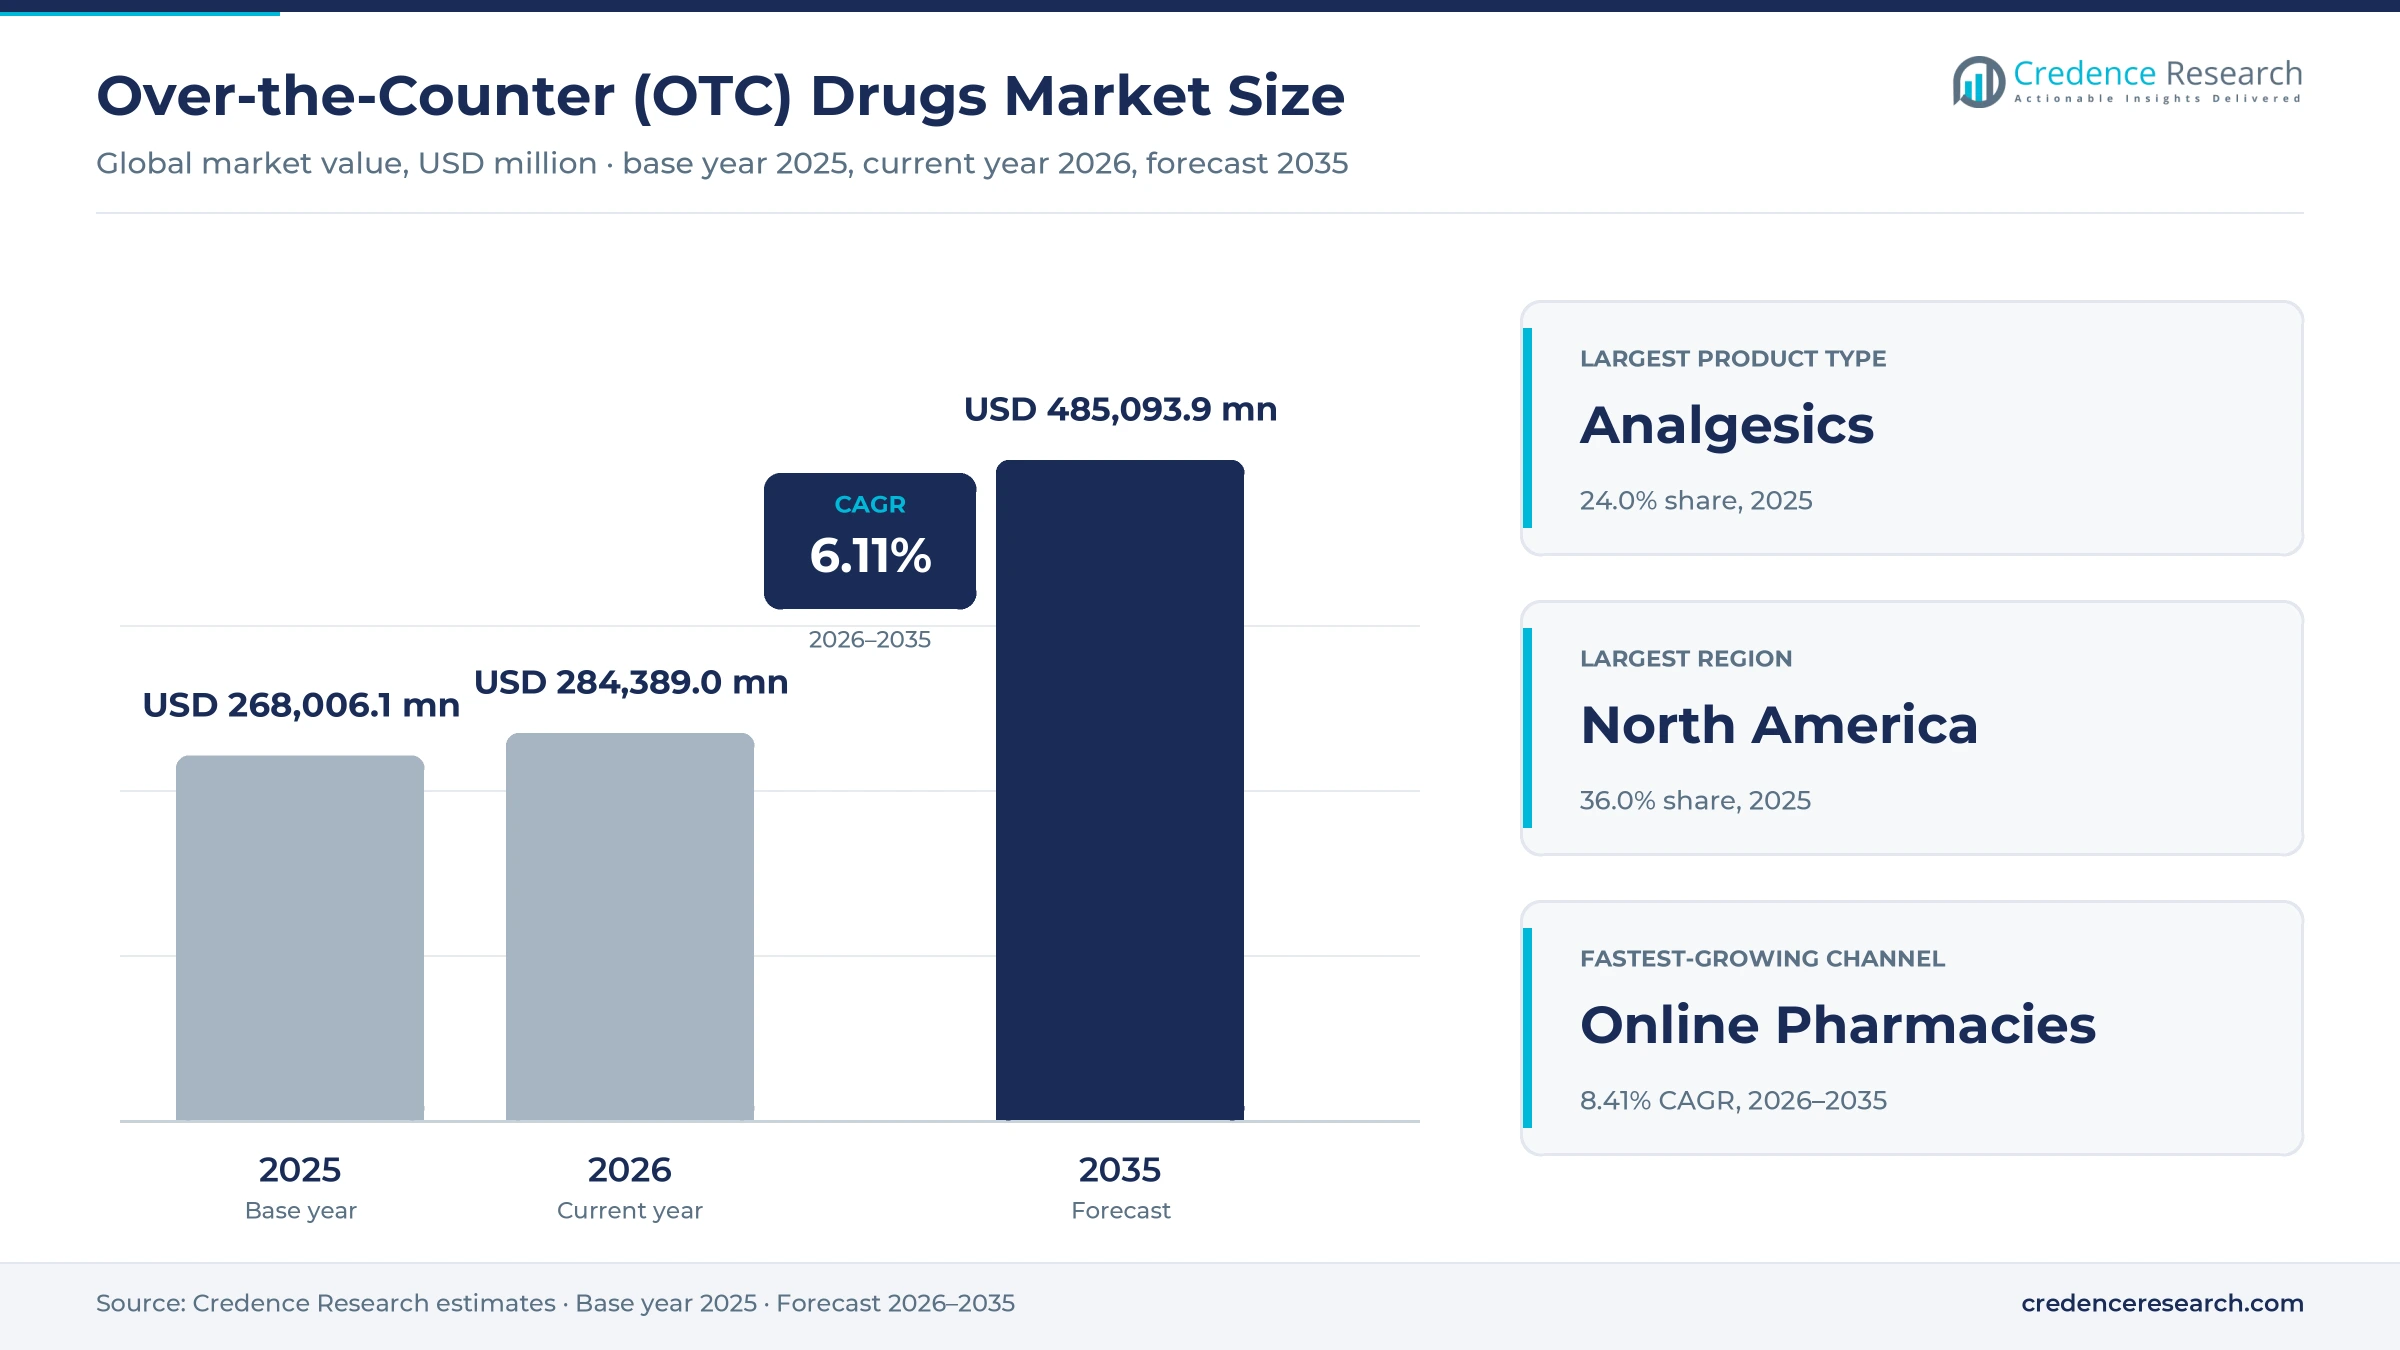
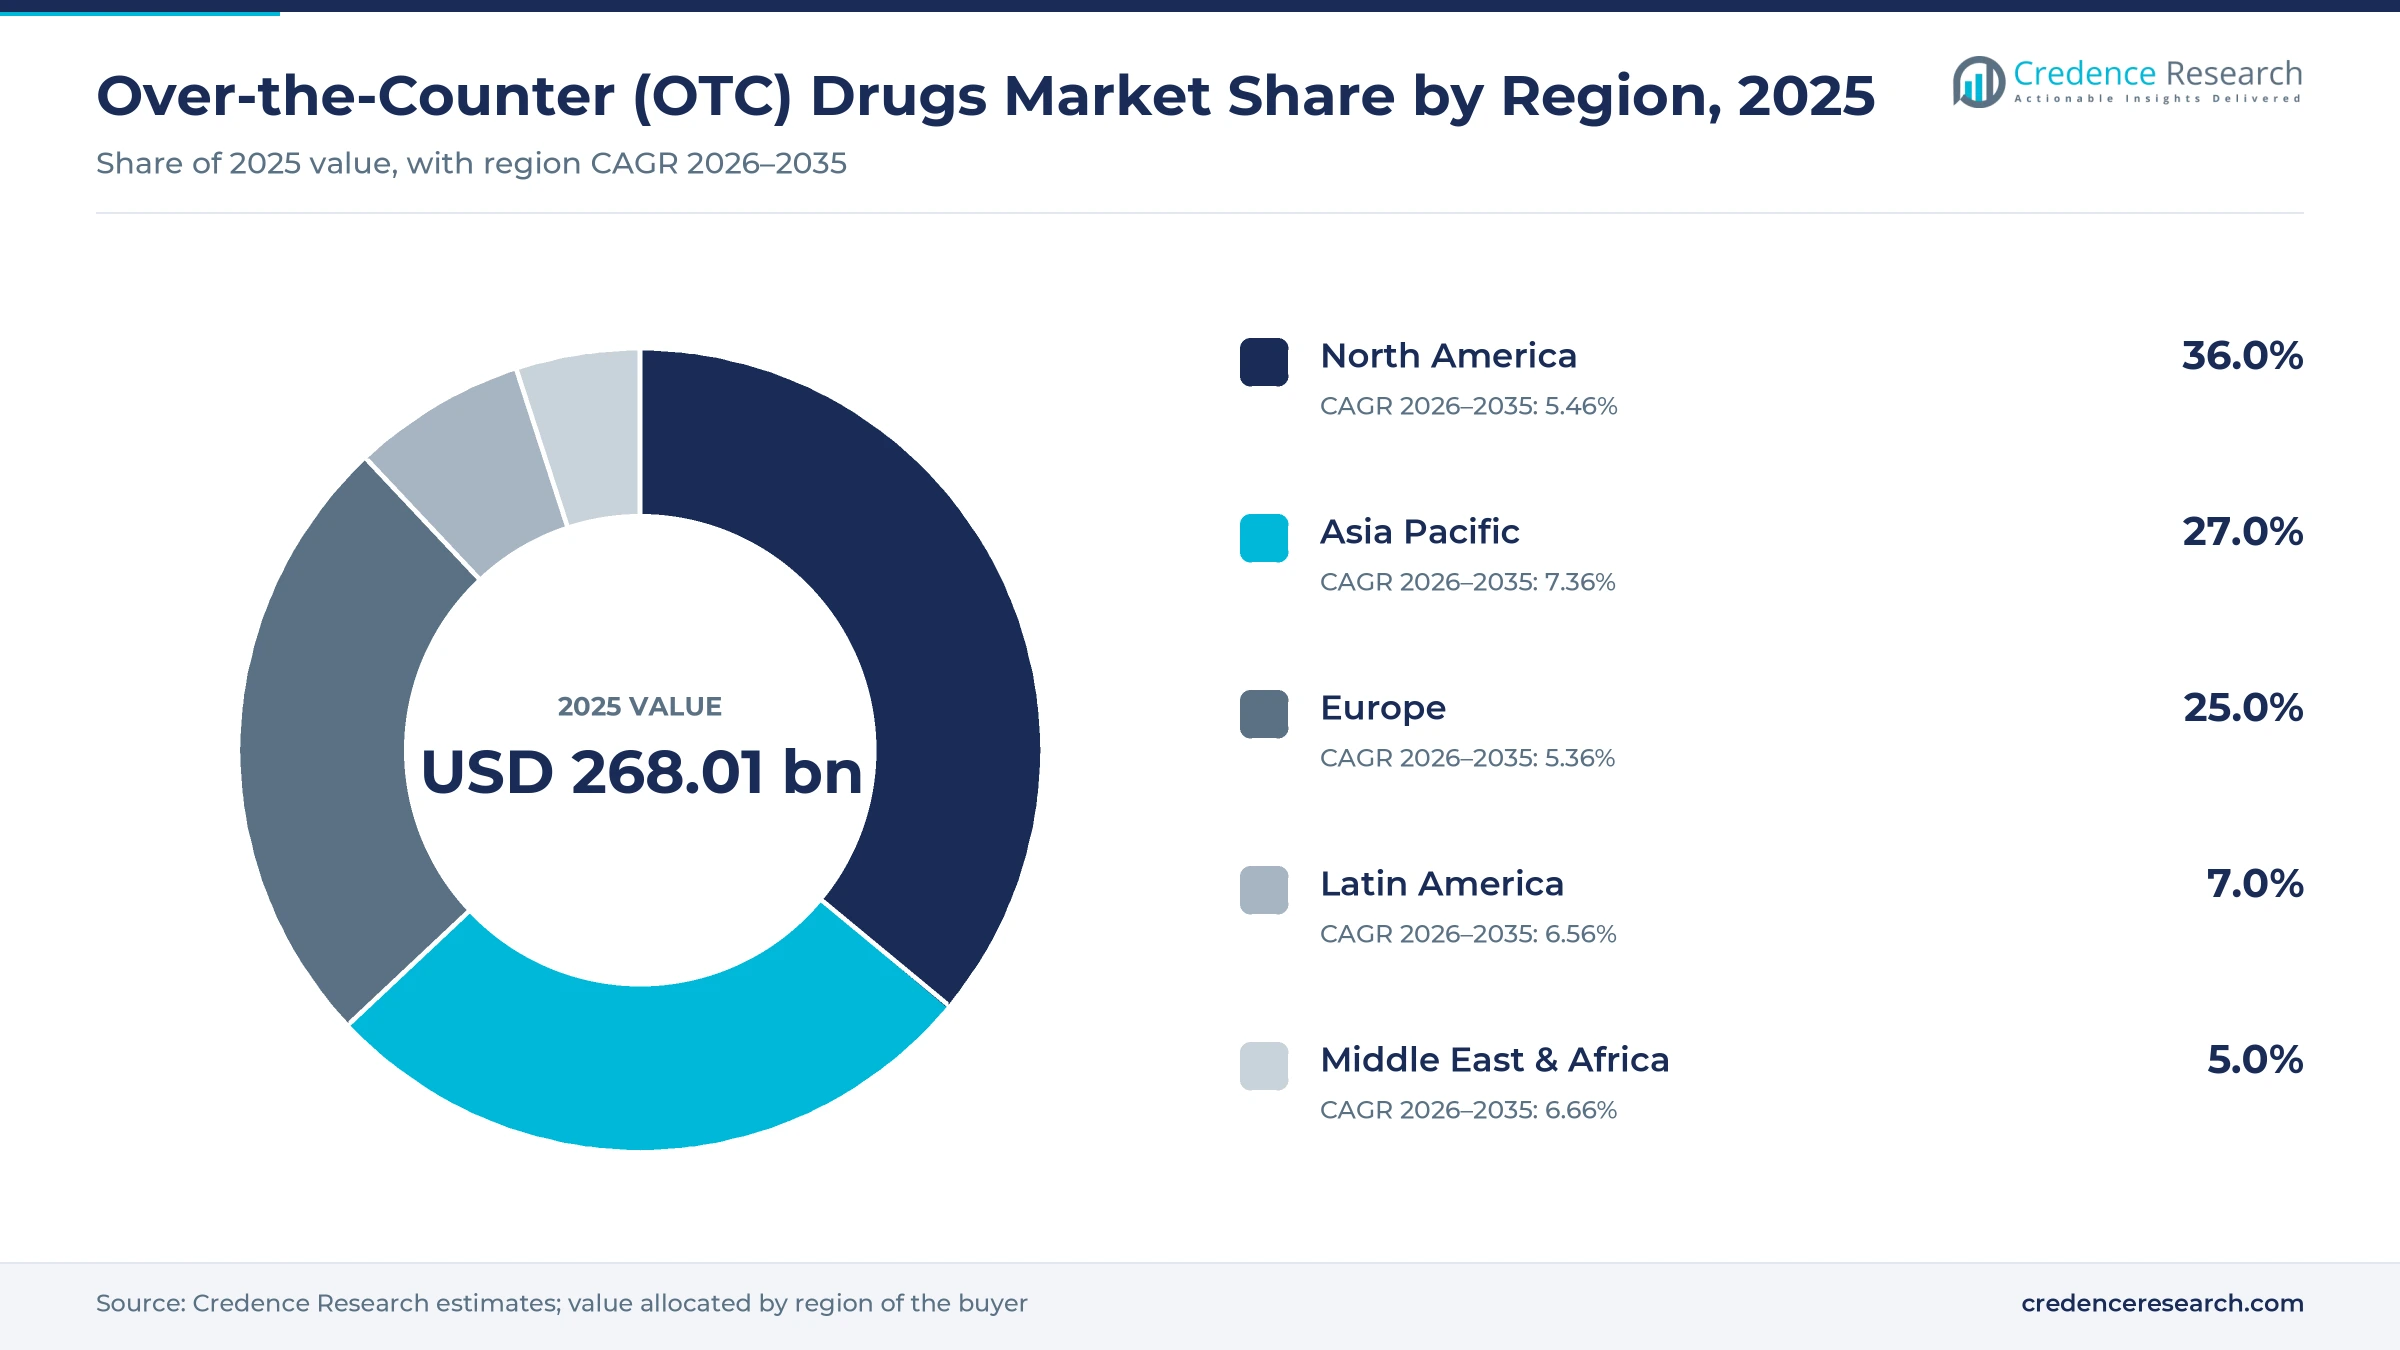
The global over-the-counter (OTC) drugs market was valued at USD 268.01 billion in 2025 and is projected to increase from USD 284.39 billion in 2026 to USD 485.09 billion by 2035, registering a CAGR of 6.11% during 2026–2035. Demand comes from consumers who treat pain, colds, digestive upsets and skin conditions without a doctor visit, and from aging adults who buy vitamins and minerals for daily health. North America held the largest regional share, 36.0% in 2025, because dense pharmacy networks and strong brands support high spending per person. Asia Pacific is the fastest-growing region at 7.36% a year, as rising incomes in China, India and Southeast Asia lift self-care purchases. The regulatory picture changed in December 2024, when the FDA finalized a rule that allows more medicines to move to nonprescription status with added safeguards. As a result, the range of self-care products is set to widen through 2035.
Which self-care medicines and channels does this analysis cover?
The analysis counts medicines sold without a prescription, including pain relievers, cold and cough remedies, digestive and intestinal remedies, skin treatments, vitamins and minerals, nicotine replacement products and other self-care medicines. Values reflect manufacturer selling prices after typical discounts, and consumers buy most products in drug stores, retail pharmacies, supermarkets and online stores.
Prescription medicines, medical devices and cosmetics without a drug claim sit outside this scope. The value chain runs from branded and private-label manufacturers through wholesalers and retail buyers to drug stores, hospital pharmacies and online pharmacies, where pharmacists and product labels guide consumer choice.
Over-the-Counter (OTC) Drugs Market Insights
- The over-the-counter (OTC) drugs market grows from USD 268.01 billion in 2025 to USD 485.09 billion by 2035, a 6.11% CAGR as self-care and new nonprescription options lift spending.
- North America held 36.0% of global nonprescription medicine value in 2025, supported by dense pharmacy networks and strong consumer brands.
- Analgesics led product types with 24.0% of 2025 value, while vitamins and minerals grow fastest at 6.97% a year.
- In December 2024, the FDA finalized a rule that allows nonprescription sale of some medicines when makers add a safeguard such as a consumer questionnaire.
- In April 2025, Sanofi and CD&R closed the Opella transaction, creating a standalone consumer health company that operates in 100 countries.
Analgesics lead as vitamins and minerals gain ground
Why do analgesics hold the largest share of self-care spending?
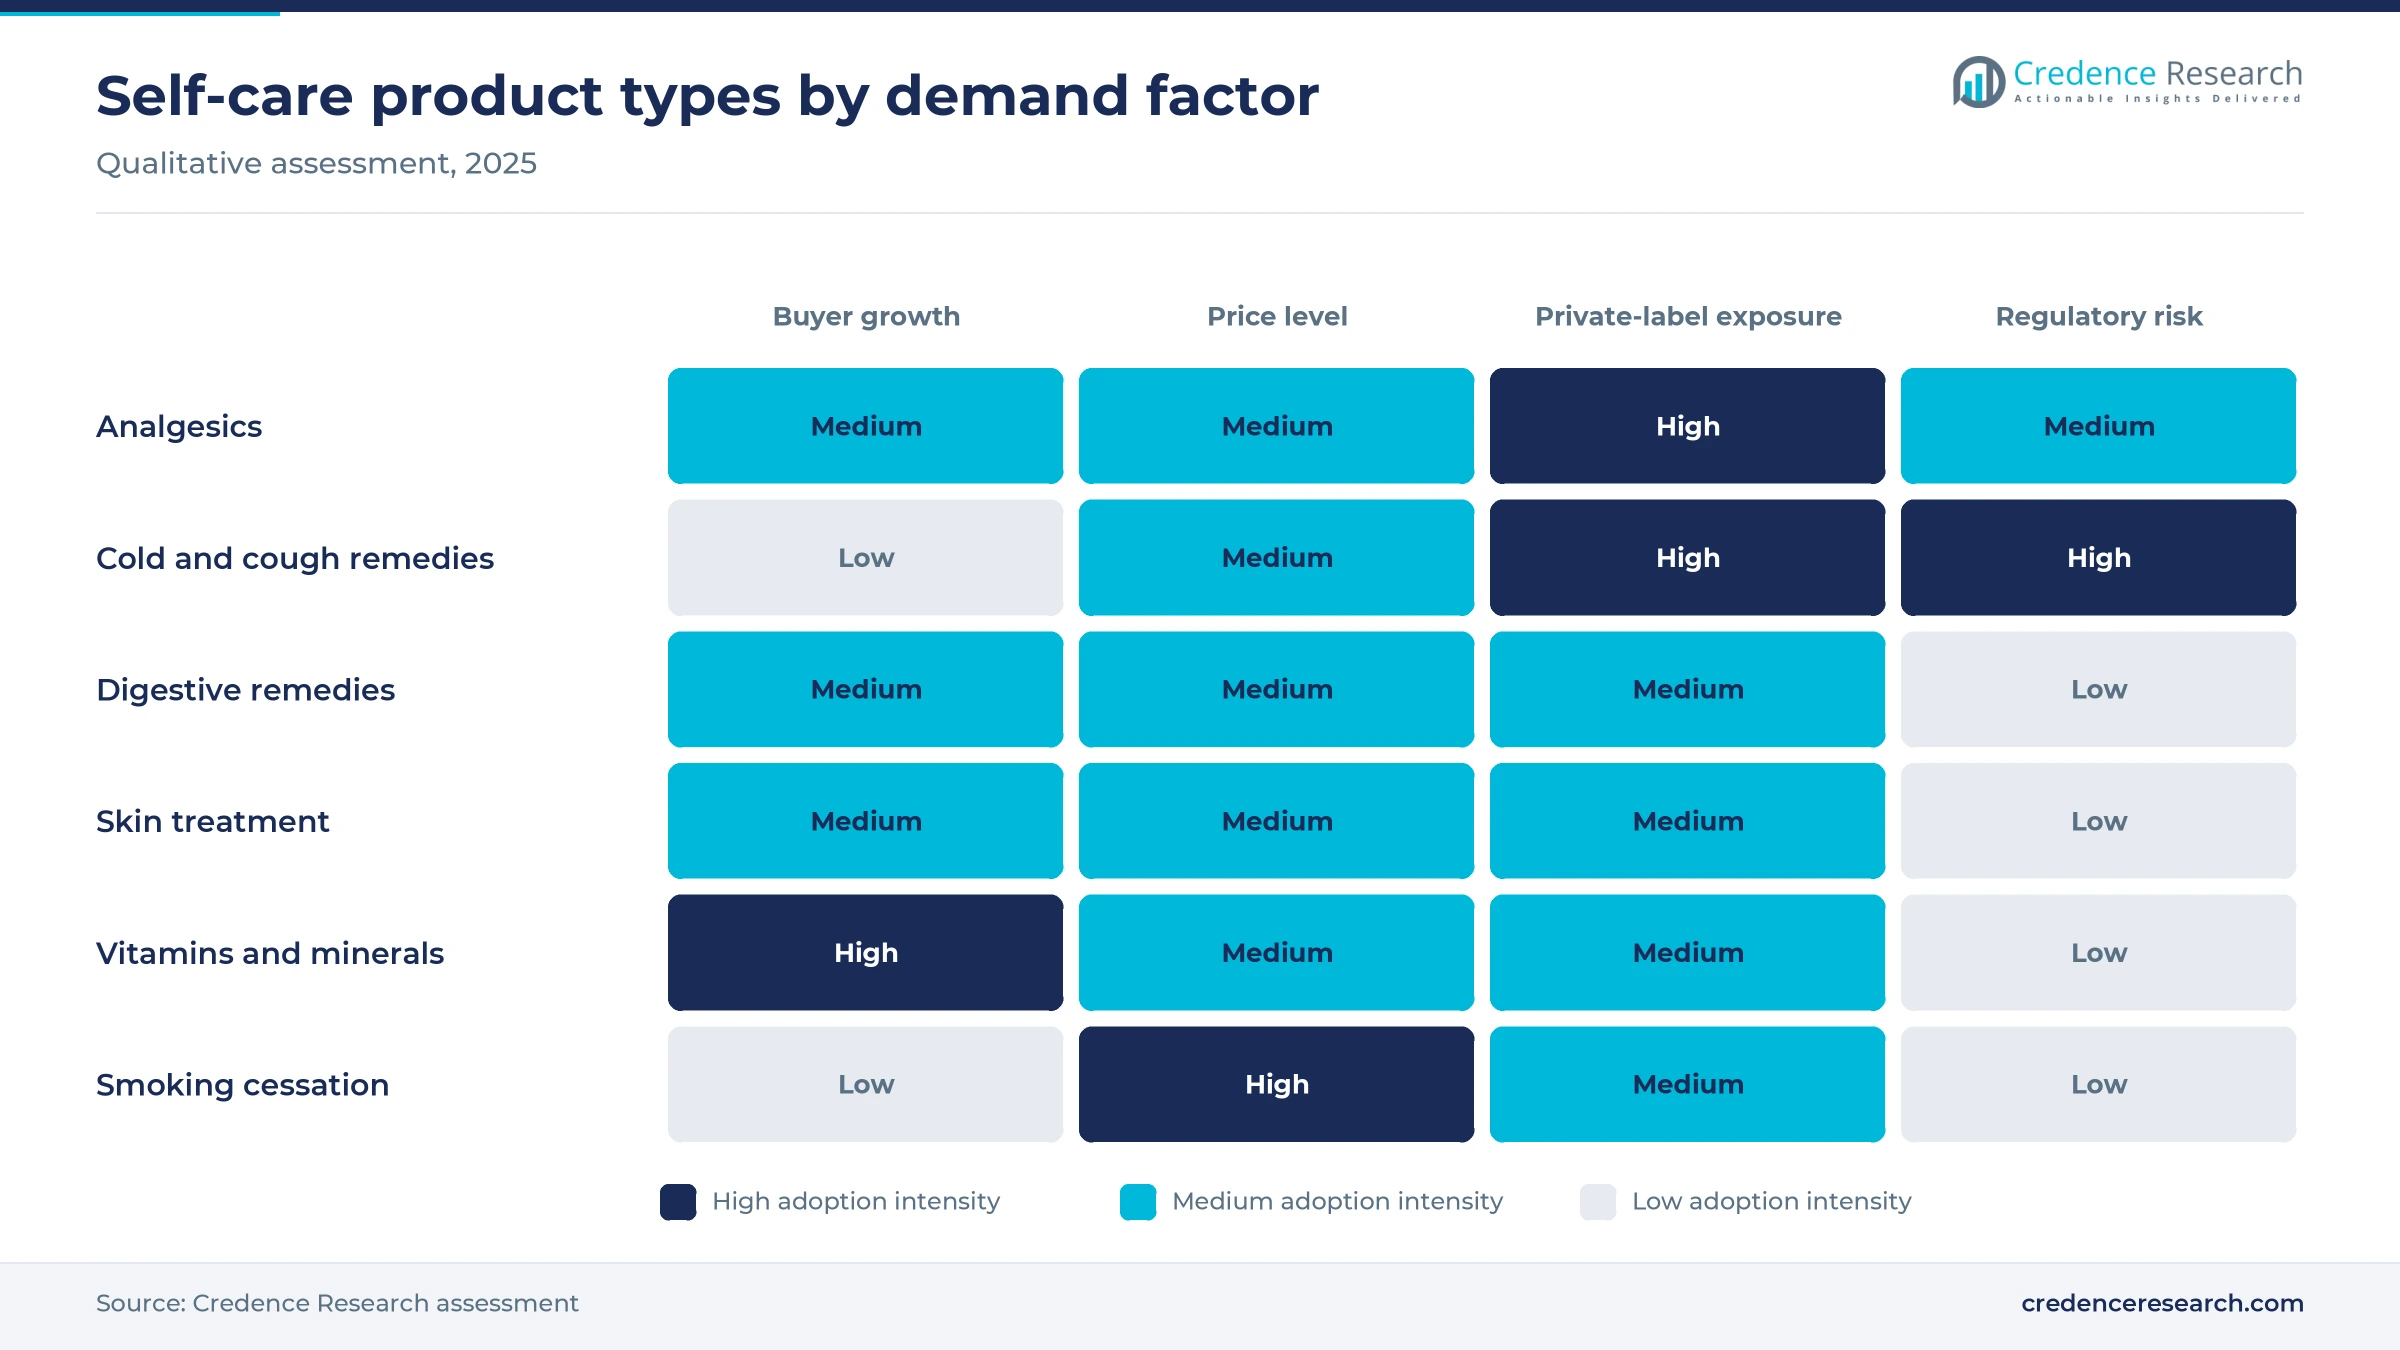
Based on product type, the market is categorized into analgesics, cold and cough remedies, digestives and intestinal remedies, skin treatment, vitamins and minerals, smoking cessation and others. Analgesics led with a 24.0% share of 2025 value, because pain and fever relievers are bought by almost every household. Vitamins & Minerals grow fastest at 6.97% a year, as aging adults use daily supplements. Digestive remedies and probiotics also gain from interest in gut health.
Why are online pharmacies gaining share?
Based on distribution channel, the market is categorized into drug stores and retail pharmacies, hospital pharmacies and online pharmacies. Drug Stores & Retail Pharmacies led with a 68.0% share of 2025 value, because consumers buy most self-care medicines on impulse or close to home. Online Pharmacies grow fastest at 8.41% a year, as e-pharmacy platforms and retailer apps offer home delivery, subscriptions and wider product ranges.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product Type | Analgesics | 24.0% | Vitamins & Minerals | 6.97% |
| By Distribution Channel | Drug Stores & Retail Pharmacies | 68.0% | Online Pharmacies | 8.41% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Self-pay health spending and new switches drive sales
How does high self-pay health spending push consumers to self-care?
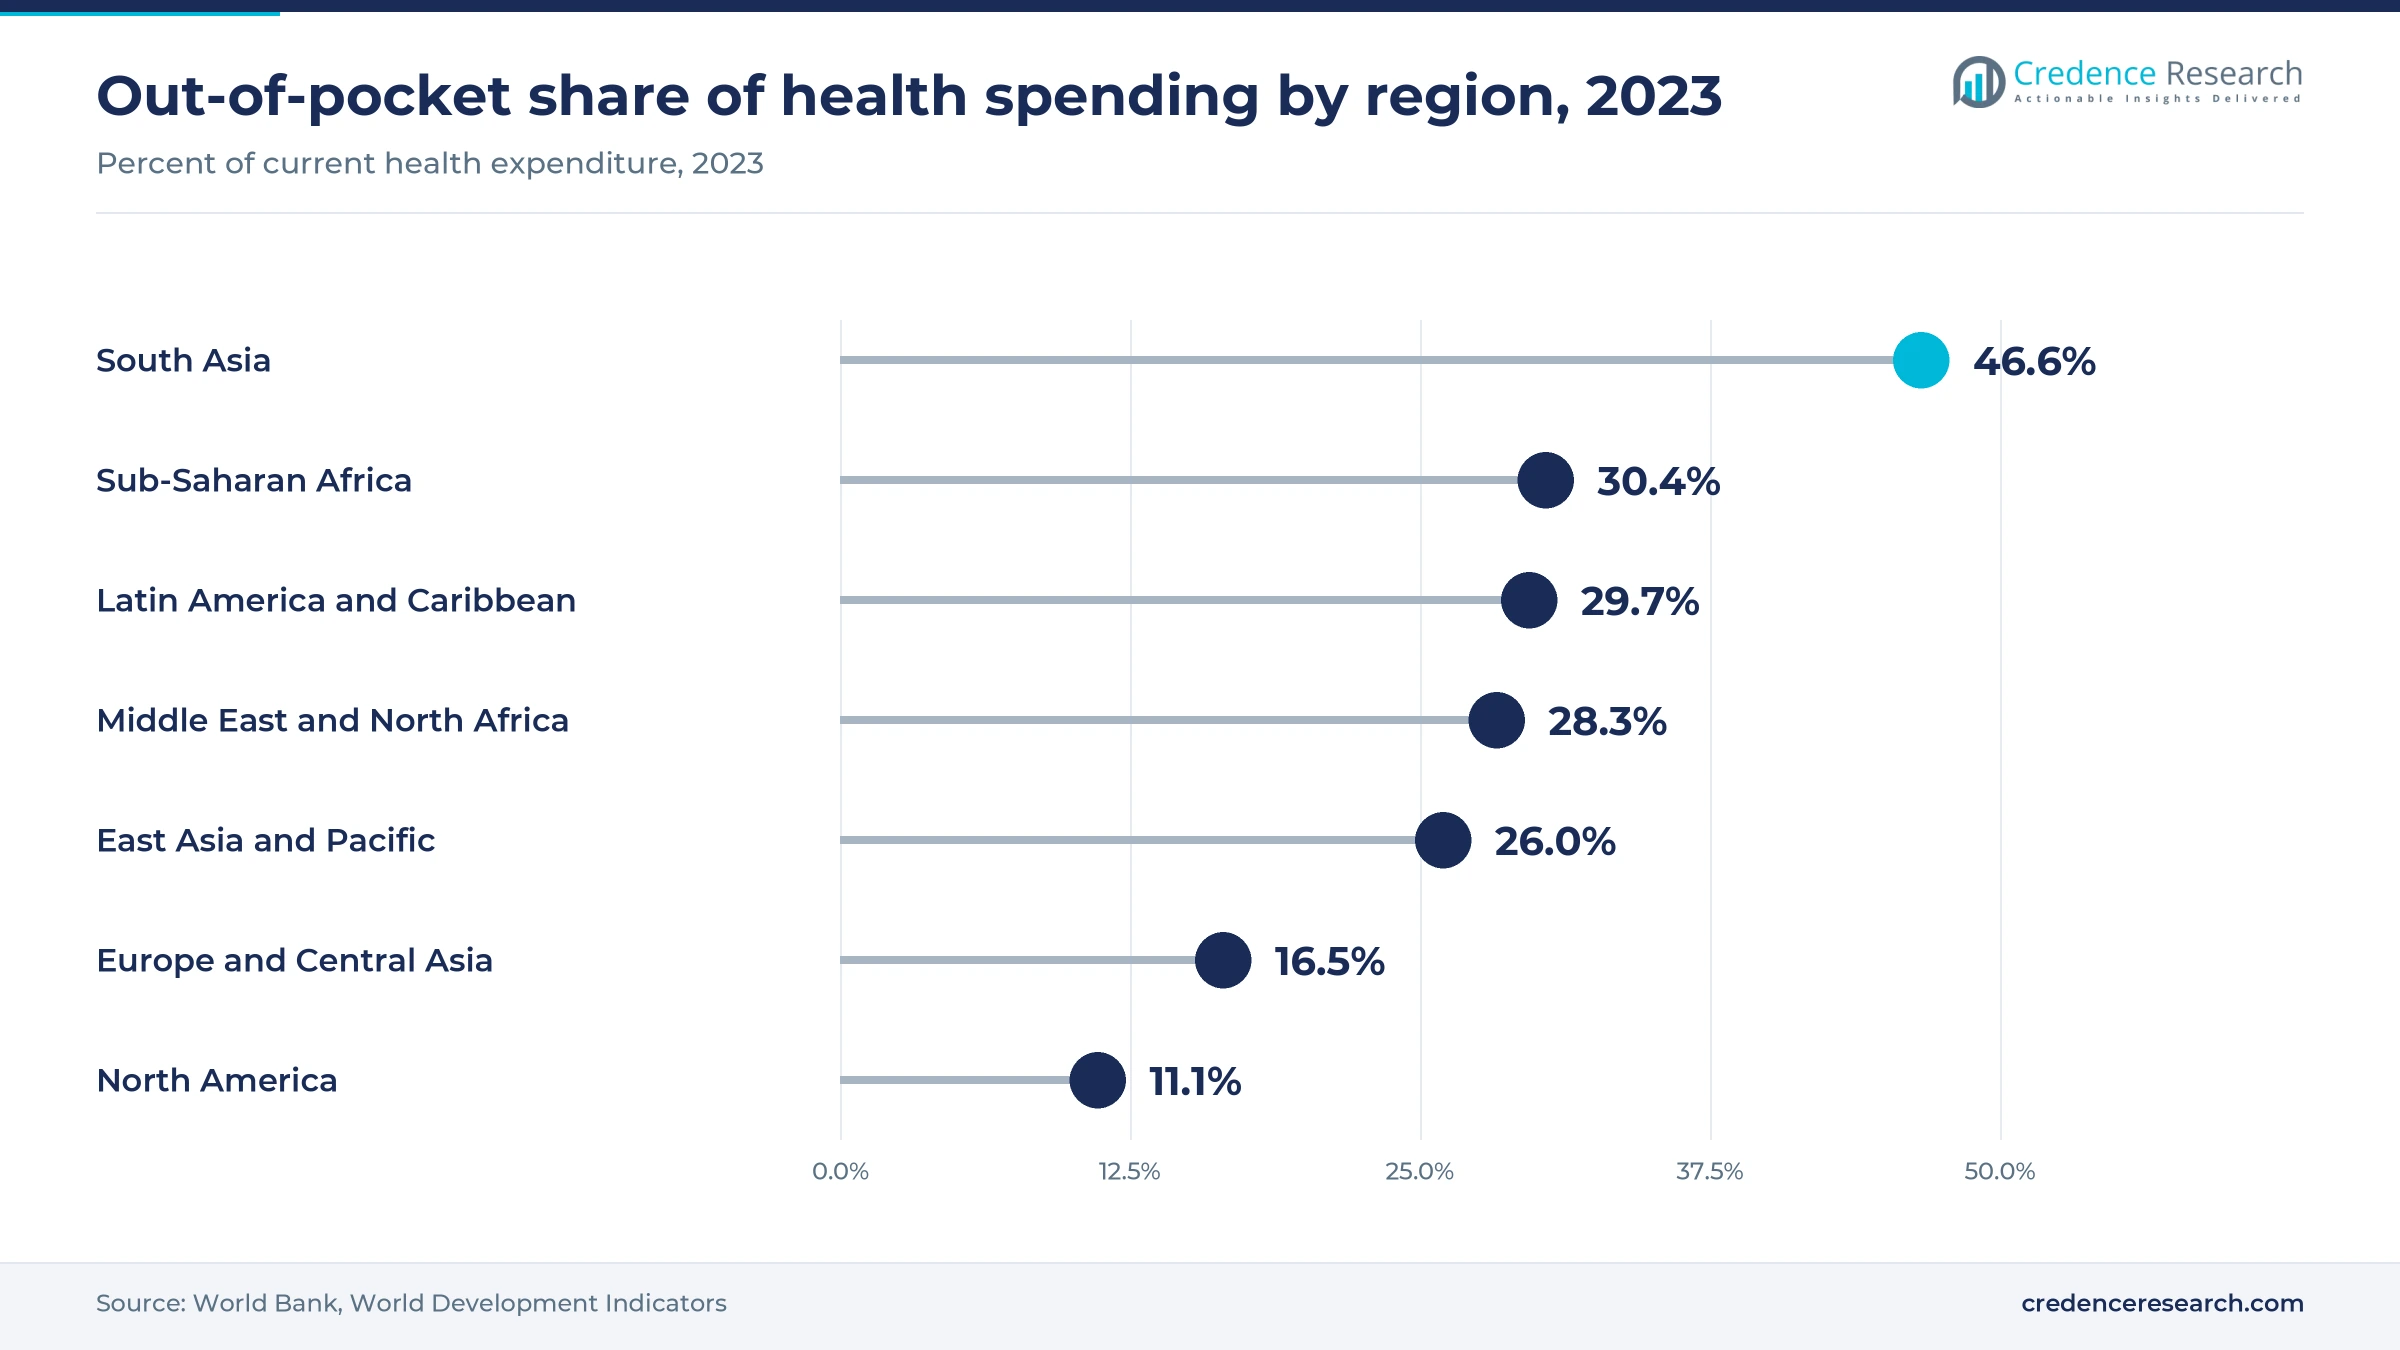
High self-pay health spending pushes consumers toward self-care, because many people pay for medicines directly rather than through insurance. World Bank data show that out-of-pocket payments made up about 46.6% of current health spending in South Asia in 2023. The same data put the share at about 29.7% in Latin America and the Caribbean and about 30.4% in Sub-Saharan Africa. Worldwide, out-of-pocket payments covered about 17.3% of health spending in 2023. As a result, consumers in these regions often visit a pharmacy first for pain, fever, colds and stomach problems. This habit keeps demand for low-cost nonprescription remedies strong across income groups.
Why do new nonprescription pathways widen product choice?
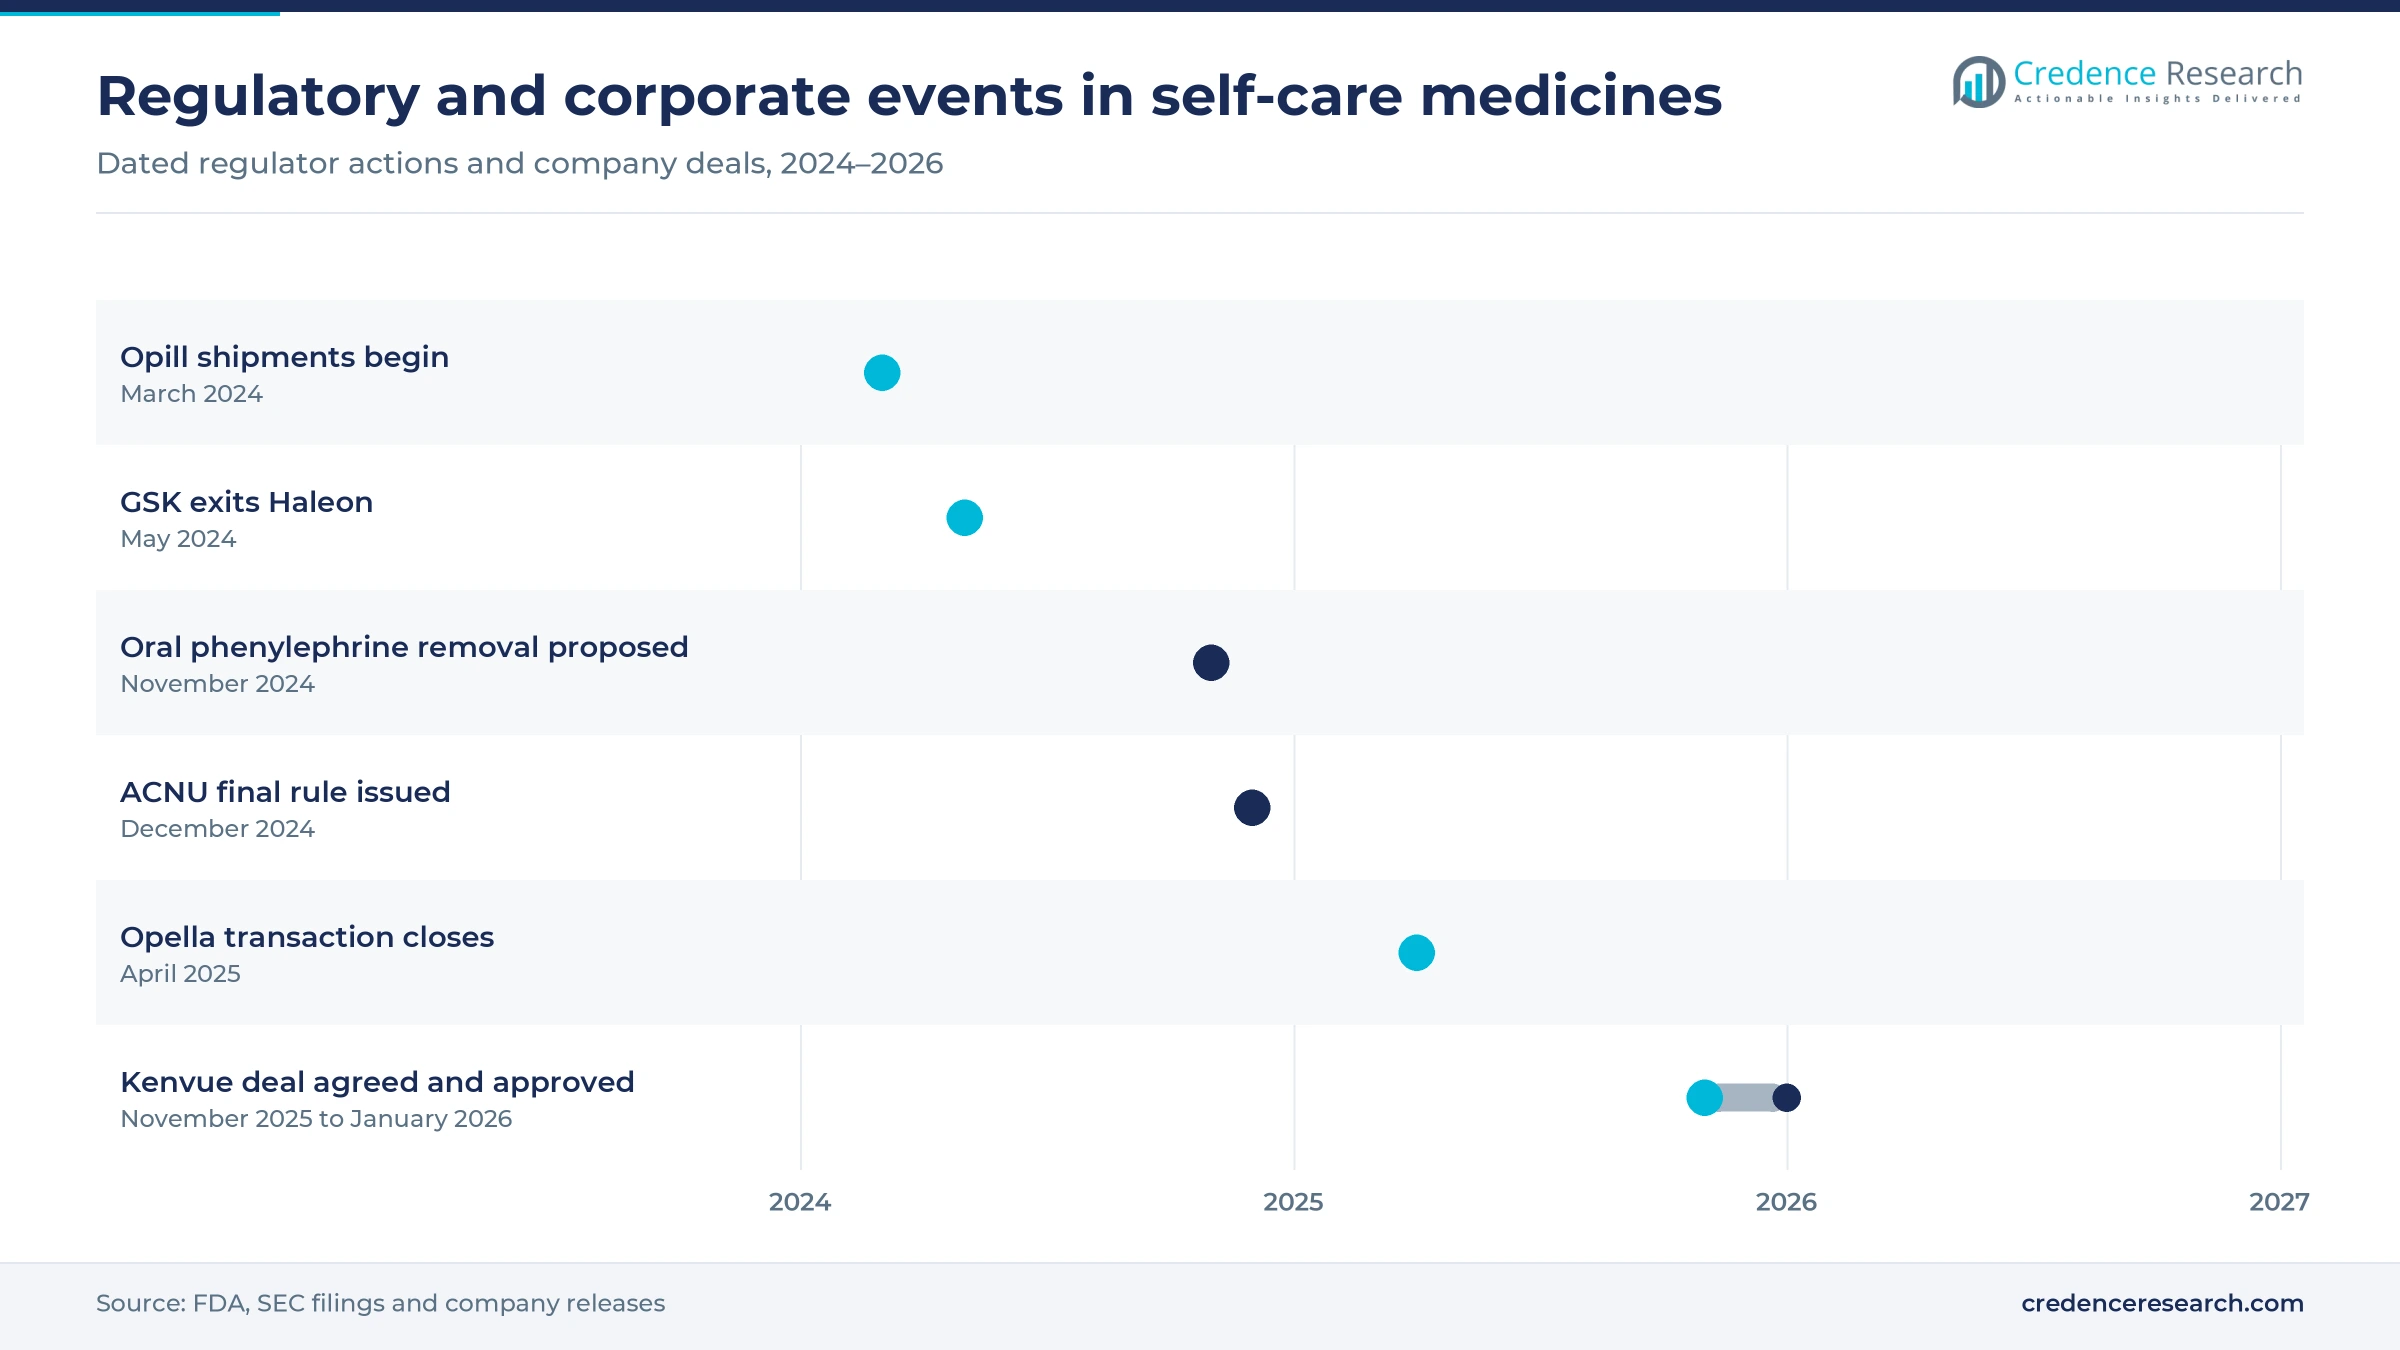
New nonprescription pathways widen product choice, because regulators now allow more medicines to move off prescription. On Dec. 23, 2024, the FDA issued a final rule that lets some medicines be sold without a prescription when makers add a safeguard such as a consumer questionnaire. The agency expects the rule to broaden the types of nonprescription products available, including some medicines for chronic conditions. In March 2024, Perrigo launched retail shipments of Opill, the first U.S. birth control pill sold without a prescription, at a suggested price of $19.99 for one month. In turn, switches bring new categories and new buyers to pharmacy shelves each year.
How does the tobacco burden support smoking cessation demand?
The tobacco burden supports smoking cessation demand, because many smokers try to quit with self-care products. The World Health Organization counts 1.2 billion tobacco users worldwide, with around 80% living in low and middle income countries. The agency also says tobacco causes more than 7 million deaths each year. National cessation services with full or partial cost coverage exist in only 31 countries, according to the same source. As a result, nicotine replacement therapy sold in pharmacies remains an important quit aid for smokers who lack access to clinics. Because cessation clinics remain scarce in most countries, pharmacies often serve as the first point of contact for smokers who want to quit.
Why does population aging lift vitamin and mineral sales?
Population aging lifts vitamin and mineral sales, because older adults buy supplements to support bone, heart and immune health. The World Health Organization expects 1 in 6 people worldwide to be aged 60 years or over by 2030. The agency also projects that the number of people aged 60 and older will reach 2.1 billion by 2050. Vitamins and minerals grow at 6.97% a year, the fastest pace among product types in this report. In turn, pharmacies and online stores give more shelf space to dietary supplements and multivitamin packs. This growth also reflects rising interest in bone and immune health among adults who prefer to manage minor conditions without a doctor visit.
Consumer health spinoffs and deals reshape supply
How is the shift to standalone consumer health firms reshaping supply?
The shift to standalone consumer health companies is reshaping supply, because large drugmakers have separated their self-care brands from prescription businesses. In August 2023, Johnson and Johnson finalized the separation of Kenvue, which owns brands such as Tylenol and Listerine. In May 2024, GSK announced the completed sale of its remaining shares in Haleon, so it no longer holds any ordinary shares in the company. On April 30, 2025, Sanofi and CD&R closed the Opella transaction, with CD&R holding 50.0%, Sanofi 48.2% and Bpifrance 1.8%. As a result, these focused companies now compete for shelf space with dedicated marketing budgets, focused research teams and faster product decisions.
Why is consolidation rising among consumer health brand owners?
Consolidation is rising among consumer health brand owners, because scale helps companies negotiate with large retailers and fund advertising. On Nov. 3, 2025, Kimberly-Clark agreed to acquire Kenvue at an enterprise value of about $48.7 billion. The deal brings together brands such as Tylenol, Listerine, Band-Aid and Neutrogena with household paper products. On Jan. 29, 2026, shareholders of both companies approved the transaction, with about 96% of shares present at the Kimberly-Clark meeting voting in favor. In turn, combined companies can use shared supply chains and retail contracts to support nonprescription brands across more countries. Smaller brand owners may face stronger pressure to find partners or sell.
Can ingredient efficacy reviews open room for new cold remedies?
Ingredient efficacy reviews give manufacturers a clear opening in cold remedies, because regulators are removing ingredients that do not work. In November 2024, the FDA proposed removing oral phenylephrine from its monograph for nasal decongestants after an extensive review found it ineffective. An FDA advisory committee had voted unanimously in September 2023 that the oral ingredient does not work as a decongestant. The proposal does not affect nasal sprays, and products can stay on sale until a final order takes effect. The FDA rule of December 2024 on added safeguards also gives companies a route to switch newer allergy and decongestant medicines. As a result, companies that reformulate cold and allergy products with proven ingredients can win shoppers who switch brands.
Where can online channels add value for brand owners?
Online channels give brand owners room to add value, because consumers increasingly buy repeat self-care items from home. Online pharmacies grow at 8.41% a year, the fastest pace among channels in this report. Perrigo sold Opill directly through its own website at $49.99 for three months and $89.99 for six months. Select online retailers also took pre-orders before in-store stock arrived in March 2024. In turn, brand owners that build direct sales, subscriptions and retailer app partnerships can capture loyal buyers of vitamins, allergy medicines and contraceptives. Direct channels also give these companies first-party data on reorder timing and product preferences.
Ingredient reviews and price pressure limit growth
How do ingredient reviews put some product lines at risk?
Ingredient reviews put some product lines at risk, because regulators can remove ingredients that fail efficacy tests. The FDA proposal on oral phenylephrine affects many cold, cough and allergy products sold in the United States. Manufacturers must reformulate, relabel and replace retail stock if a final order takes effect. As a result, cold remedy makers face added costs and short-term sales losses, which slows value growth in that segment.
Why does private-label competition limit pricing?
Private-label competition limits pricing, because large pharmacy chains and supermarkets sell store brands of common pain relievers, antacids and allergy medicines. These products use the same active ingredients as national brands at lower prices. Shoppers who trust pharmacist advice often switch to store brands during periods of high inflation. In turn, branded manufacturers must spend more on advertising and new formats to defend their shelf positions.
How do safety concerns limit some self-care products?
Safety concerns limit some self-care products, because misuse of pain relievers and cough medicines can cause serious harm. Acetaminophen overdose can damage the liver, and some cough medicines face age limits for young children. Regulators therefore require clear labels, dose limits and pack size rules in many countries. As a result, companies face strict review of claims and packaging, which slows launches of new combinations and formats.
Why do switch costs slow new product entry?
Switch costs slow new product entry, because moving a medicine from prescription to nonprescription status requires label comprehension and actual use studies. These studies add years and large costs before a product reaches shelves. The new ACNU rule adds options, but makers must also design and maintain the added safeguard. In turn, only large companies can fund most switches, which limits the number of new products each year.
North America leads as Asia Pacific gains pace
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 96.48 | 36.0% | 5.46% |
| Asia Pacific | 72.36 | 27.0% | 7.36% |
| Europe | 67.00 | 25.0% | 5.36% |
| Latin America | 18.76 | 7.0% | 6.56% |
| Middle East & Africa | 13.40 | 5.0% | 6.66% |
Why does North America hold the largest regional share?
North America held a 36.0% share of 2025 value and grows at 5.46% a year through 2035. The United States drives this position, because consumers buy branded pain relievers, allergy medicines and supplements in a dense network of drug stores and supermarkets. The FDA rule finalized in December 2024 adds new paths for switches. Strong advertising and private-label ranges keep spending per person high.
How fast is Asia Pacific adding buyers?
Asia Pacific held a 27.0% share of 2025 value and is the fastest-growing region at 7.36% a year. China, India, Japan and Southeast Asia drive this growth, because rising incomes and pharmacy chain expansion widen access to branded self-care products. World Bank data show out-of-pocket payments covered about 26.0% of health spending in East Asia and Pacific in 2023, which supports pharmacy-first care.
What shapes demand across Europe?
Europe held a 25.0% share of 2025 value and grows at 5.36% a year through 2035. Germany, France, the United Kingdom, Italy and Spain account for most spending, because pharmacists play a strong role in advising on self-care. Opella, now controlled by CD&R, sells brands such as Doliprane and Dulcolax across the region. However, price rules and pharmacy-only sales in several countries keep growth below the global average.
Where is Latin America adding demand?
Latin America held a 7.0% share of 2025 value and grows at 6.56% a year through 2035. Brazil and Mexico lead regional spending, because large pharmacy chains sell both branded and generic self-care medicines. High out-of-pocket payments push many consumers to treat minor illness at the pharmacy counter first.
What limits growth in the Middle East and Africa?
The Middle East and Africa held a 5.0% share of 2025 value and grows at 6.66% a year through 2035. Gulf states support modern pharmacy chains and branded products, while much of Africa relies on informal sellers and low-cost generics. Weak supply chains and informal sellers limit access to branded products outside major cities.
Regulatory rules and consumer health deals since 2024
| Development | Status and market relevance |
|---|---|
| In March 2024, Perrigo Company plc began shipping Opill, the first U.S. birth control pill sold without a prescription. | Launched; sold in retail stores and online at a suggested price of $19.99 per month |
| In November 2024, the FDA proposed removing oral phenylephrine from its nasal decongestant monograph. | Proposed; nasal sprays are not affected |
| In December 2024, the FDA issued a final rule on nonprescription products with an additional condition for use. | Final; allows safeguards such as consumer questionnaires |
| In April 2025, Sanofi and CD&R closed the Opella transaction. | Completed; CD&R holds a 50.0% controlling stake |
| In November 2025, Kimberly-Clark agreed to acquire Kenvue, the former Johnson and Johnson consumer health unit. | Approved by shareholders in January 2026 |
Switch pathways and digital retail lead innovation
- Consumer self-selection questionnaires help shoppers confirm a medicine suits them, which supports switches under the FDA rule finalized in 2024.
- Extended-release and fast-acting formats give longer or quicker relief from one dose, which helps brands stand apart from store labels.
- Nicotine gums, lozenges and patches deliver controlled doses that ease cravings, which supports quit attempts without a clinic visit.
- E-commerce and subscription platforms let consumers reorder vitamins and allergy medicines automatically, which builds repeat sales.
- Pharmacy point-of-care tools let pharmacists screen symptoms and suggest products, which raises trust in self-care advice.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Brand owners compete on trust, shelf space and price
Competition is led by consumer health companies with trusted brands, large advertising budgets and strong retail contracts. Johnson and Johnson separated its consumer brands into Kenvue in 2023, while GlaxoSmithKline Plc. exited Haleon in 2024. Sanofi S.A. now holds 48.2% of Opella after the April 2025 deal with CD&R. Bayer AG, Reckitt Benckiser Group PLC, Boehringer Ingelheim International GmbH, Pfizer Inc., Novartis AG and Takeda Pharmaceutical Company Ltd. compete with pain, cold, digestive and vitamin brands across regions. Perrigo Company plc leads in store brands and launched Opill in 2024. Sun Pharmaceutical Limited and Cipla Limited build self-care portfolios in India and emerging markets. As a result, competition centers on brand trust, shelf space, price and speed in launching switched products.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Johnson & Johnson Services Inc. | Former brand owner | Consumer brands separated into Kenvue in 2023 |
| Bayer AG | Consumer health division | Pain, allergy and vitamin brands |
| Novartis AG | Pharmaceutical company | Legacy self-care brands |
| Sanofi S.A. | Minority owner | 48.2% stake in Opella |
| Pfizer Inc. | Pharmaceutical company | Legacy consumer health interests |
| GlaxoSmithKline Plc. | Former owner | Exited Haleon shares in May 2024 |
| Boehringer Ingelheim International GmbH | Pharmaceutical company | Self-care products in selected markets |
| Reckitt Benckiser Group PLC | Consumer health company | Pain, cold and digestive brands |
| Takeda Pharmaceutical Company Ltd. | Pharmaceutical company | Self-care brands in Asia |
| Perrigo Company plc | Store brand leader | Private-label medicines and Opill |
| Sun Pharmaceutical Limited | Generics and consumer health | Self-care brands in India |
| Cipla Limited | Generics and consumer health | Consumer health brands in India and Africa |
Self-care demand and switches set the pace
Credence Research's view is that self-care demand and new switches will set the pace of growth through 2035. The overall market grows at 6.11% a year, supported by high out-of-pocket spending, aging populations and wider nonprescription access. Vitamins and minerals grow faster than other product types, while online pharmacies gain share from stores. Ingredient reviews and private labels pressure older cold and pain brands. Companies that combine trusted brands, proven ingredients and strong digital retail will capture the most new buyers.
How Credence Research sized nonprescription spending
The report uses 2025 as the base year and 2026 to 2035 as the forecast period. Market values come from the Credence Research model, which builds spending by product type, distribution channel and region. Regional and segment splits are Credence Research estimates informed by World Health Organization and World Bank data, FDA rules and orders, and company press releases and filings. No primary interviews or surveys were used in preparing this edition of the report.
Nonprescription medicine spending outlook to 2035
By 2035, the over-the-counter (OTC) drugs market is projected to reach USD 485.09 billion, with growth led by vitamins and minerals, switched medicines and online sales. Analgesics remain the largest product type, while cold remedies adjust after ingredient reviews. North America keeps the highest spending per person, while Asia Pacific adds the most new buyers. Consolidated consumer health companies gain scale in talks with large retail chains. As a result, advantage will depend on brand trust, proven ingredients and digital reach.
Frequently Asked Questions
How big is the global over-the-counter (OTC) drugs market?
Which product type leads nonprescription medicine spending?
Which region leads nonprescription medicine demand?
Why are online pharmacies growing fastest?
What did the FDA change for nonprescription medicines in 2024?
What recent deals affect consumer health companies?
Who are the leading over-the-counter (OTC) drugs companies?
What restrains growth in nonprescription medicines?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Analgesics
- 1.2.2 Cold & Cough Remedies
- 1.2.3 Digestives & Intestinal Remedies
- 1.2.4 Skin Treatment
- 1.2.5 Vitamins & Minerals
- 1.2.6 Smoking Cessation
- 1.2.7 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 268.01 billion → 2035: USD 485.09 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Over-the-Counter (OTC) Drugs Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Over-the-Counter (OTC) Drugs Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Over-the-Counter (OTC) Drugs Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Over-the-Counter (OTC) Drugs Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Over-the-Counter (OTC) Drugs Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Over-the-Counter (OTC) Drugs Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Over-the-Counter (OTC) Drugs Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Over-the-Counter (OTC) Drugs Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 268.01 billion → 2035: USD 485.09 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Over-the-Counter (OTC) Drugs Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Analgesics
- 12.3.7.2 Cold & Cough Remedies
- 12.3.7.3 Digestives & Intestinal Remedies
- 12.3.7.4 Skin Treatment
- 12.3.7.5 Vitamins & Minerals
- 12.3.7.6 Smoking Cessation
- 12.3.7.7 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 Segment Growth Comparison
- 12.5 Segment Attractiveness and Priority Matrix
Chapter 13 Global Over-the-Counter (OTC) Drugs Geographic Market Outlook, 2025-2035
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2035
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Over-the-Counter (OTC) Drugs Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Over-the-Counter (OTC) Drugs Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Johnson & Johnson Services Inc.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Bayer AG
- 17.4 Novartis AG
- 17.5 Sanofi S.A.
- 17.6 Pfizer Inc.
- 17.7 GlaxoSmithKline Plc.
- 17.8 Boehringer Ingelheim International GmbH
- 17.9 Reckitt Benckiser Group PLC
- 17.10 Takeda Pharmaceutical Company Ltd.
- 17.11 Perrigo Company plc
- 17.12 Sun Pharmaceutical Limited
- 17.13 Cipla Limited
- 17.14 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

