
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year41,937.14 | 2023 |
| Forecast Period | 2024-2032 |
| Pressure Vessels Market Size 2024 | USD 60,385 Million |
| Pressure Vessels Market, CAGR | 3.7% |
| Pressure Vessels Market Size 2032 | USD 80,753.08 Million |
Market Overview:
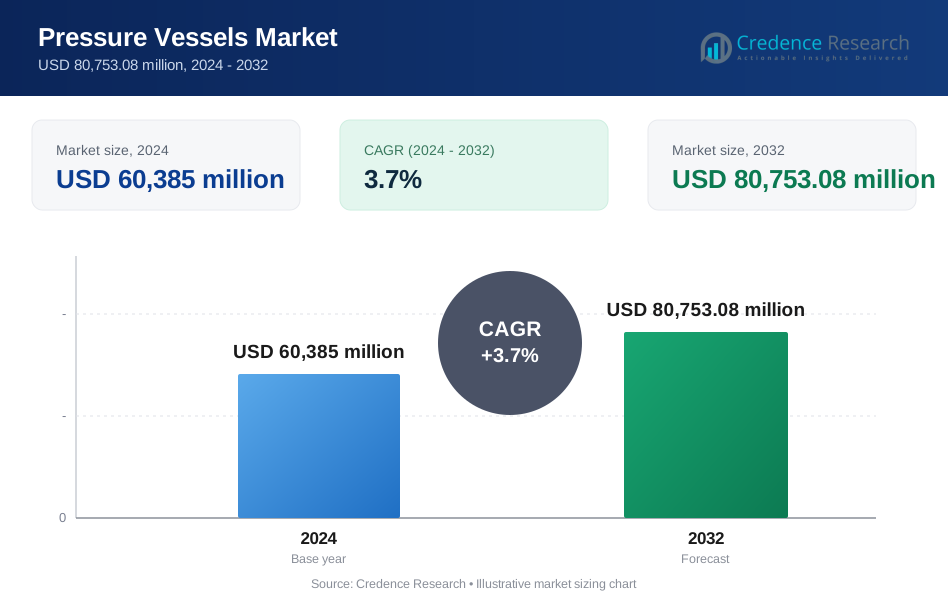
The Pressure Vessels Market is projected to grow from USD 60,385 million in 2024 to USD 80,753.08 million by 2032, representing a compound annual growth rate (CAGR) of 3.7%. Pressure vessels are essential components in various industries, including oil and gas, chemicals, and power generation, where they are used to contain gases or liquids under high pressure. The demand for pressure vessels is rising due to increased industrial activity and energy needs globally. Additionally, ongoing technological advancements have led to the development of more efficient and durable pressure vessel designs, further supporting market growth.
Several key factors are driving the expansion of the pressure vessels market. The growing demand for energy, especially from renewable sources, has increased the need for pressure vessels in power generation applications, such as nuclear and solar thermal energy plants. In the oil and gas industry, pressure vessels play a critical role in storage and transportation, with the sector’s growth contributing significantly to demand. Moreover, stricter safety regulations in industries handling hazardous materials have pushed manufacturers to innovate in terms of material quality and structural integrity. The development of corrosion-resistant and high-strength materials is helping to improve vessel durability and safety, making them suitable for high-pressure and high-temperature applications.
Asia-Pacific holds a substantial share of the pressure vessels market, driven by rapid industrialization and urbanization in countries such as China, India, and Japan. These countries are seeing increased investments in energy and infrastructure projects, particularly in the oil, gas, and chemical sectors, which drives the demand for pressure vessels. North America follows, with the United States leading due to a high concentration of petrochemical and power generation facilities. Meanwhile, Europe has a well-established market, with countries like Germany and the United Kingdom focusing on upgrading existing infrastructure to meet energy demands and environmental standards. The growth in these regions reflects a global shift toward modernizing and expanding industrial capabilities, which supports the overall demand for pressure vessels.
Market Drivers:
Increasing Energy Demand and Industrialization:
The rising global demand for energy, particularly in rapidly industrializing nations, is a primary driver of the pressure vessels market. With expanding industrial activities in countries such as China and India, energy consumption continues to climb. According to the International Energy Agency (IEA), global energy demand is expected to increase by nearly 25% by 2040, driven by growth in Asia and the Middle East. Pressure vessels play a crucial role in energy generation, especially in power plants that rely on high-pressure steam to produce electricity. As industrial activities surge, the need for pressure vessels in energy production is expected to grow, supporting market expansion.
Growth in the Oil and Gas Sector:
The oil and gas industry are a significant contributor to the demand for pressure vessels, which are essential for the storage and transportation of various hydrocarbons under high pressure. In regions like the Middle East and North America, increased exploration and production activities have intensified the need for pressure vessels. The U.S. Energy Information Administration (EIA) highlights that the United States has become one of the world’s largest oil producers, with pressure vessels playing an essential role in upstream, midstream, and downstream operations. Additionally, as companies like ExxonMobil and Royal Dutch Shell invest in new projects, the demand for high-capacity and durable pressure vessels is anticipated to grow in tandem.
Advancements in Pressure Vessel Materials and Technology:
Innovations in materials and construction technology are driving market growth by enabling manufacturers to create more durable and efficient pressure vessels. For example, the development of composite materials and advanced alloys, such as carbon fiber and stainless steel, enhances corrosion resistance and strength, which are critical for vessels operating under extreme conditions. BASF and Honeywell UOP are among companies pioneering in material technologies that improve structural integrity and reduce maintenance requirements. These advancements align with industry needs for vessels that can withstand high temperatures and pressures, particularly in chemical processing and nuclear energy applications.
Stringent Safety Regulations and Standards:
Safety regulations in sectors such as chemicals, nuclear energy, and pharmaceuticals have become more rigorous, prompting the adoption of high-quality pressure vessels. Government authorities, including the Occupational Safety and Health Administration (OSHA) and the American Society of Mechanical Engineers (ASME), set stringent standards for pressure vessel manufacturing to ensure safety and prevent hazardous incidents. For instance, ASME’s Boiler and Pressure Vessel Code outlines requirements for design, construction, and inspection to promote safe operations. These standards drive manufacturers to invest in R&D and adopt advanced technologies that enhance safety and compliance, fueling demand for innovative pressure vessel solutions.
Market Trends:
Increased Adoption of Advanced Materials:
A significant trend in the pressure vessels market is the use of advanced materials that enhance durability and performance under high-pressure conditions. Manufacturers are increasingly incorporating materials like stainless steel, composite materials, and carbon fiber, which offer higher resistance to corrosion and improved strength. Companies such as BASF have pioneered composite materials for pressure vessels, which are both lightweight and durable, making them ideal for applications in the chemical and oil industries. These materials not only extend the lifespan of pressure vessels but also reduce maintenance requirements, aligning with industry demands for cost-effective, long-term solutions.
Rising Demand in Renewable Energy Applications:
The shift toward renewable energy is driving demand for pressure vessels in solar, wind, and nuclear energy projects. In the solar energy sector, pressure vessels are essential for solar thermal plants, where they store heat-transfer fluids under high pressure. Nuclear power plants also rely heavily on pressure vessels for coolant and reactor systems. According to the International Atomic Energy Agency (IAEA), several countries are expanding their nuclear power capacity to reduce carbon emissions, thereby increasing the need for advanced pressure vessels. Companies like Siemens are focusing on developing pressure vessel technologies specifically suited for renewable energy applications, further supporting this trend.
Growth of Modular and Prefabricated Pressure Vessels:
To meet industry demands for efficiency and scalability, manufacturers are developing modular and prefabricated pressure vessels. This approach reduces on-site construction time, minimizes installation costs, and allows for easier transport to remote locations. For example, Honeywell UOP has introduced modular pressure vessels for gas processing, which can be transported and installed quickly, particularly benefiting industries with remote operational sites. Prefabricated pressure vessels are also in demand in the pharmaceutical and food processing sectors, where facilities often require quick, compliant solutions that can adapt to changing production requirements.
Digital Integration for Monitoring and Maintenance:
The integration of digital technologies, such as Internet of Things (IoT) sensors and predictive maintenance systems, is transforming the pressure vessels market. These technologies enable real-time monitoring of pressure, temperature, and corrosion levels, helping operators to proactively manage vessel performance and ensure safety. For instance, Emerson has developed smart sensors that provide continuous monitoring of pressure vessels in industrial plants, alerting operators to potential issues before they escalate. This trend aligns with the industry’s push toward automation and digitalization, which enhances operational efficiency, reduces downtime, and extends the lifecycle of pressure vessels.
Market Challenges Analysis:
High Costs and Material Constraints:
One of the primary challenges in the Pressure Vessels Market is the high cost of materials, particularly advanced alloys and composite materials that are essential for vessels operating under extreme pressures and temperatures. These materials, such as stainless steel and carbon fiber composites, significantly increase production costs. Additionally, the costs associated with ensuring structural integrity and safety, including testing and certification, add to overall expenses. For industries with limited budgets, such as small and medium-sized enterprises, these costs can be prohibitive, limiting access to advanced pressure vessel technologies.
Stringent Regulatory Requirements:
Stringent regulations regarding the design, manufacturing, and operation of pressure vessels pose a considerable challenge. Regulatory bodies, such as the American Society of Mechanical Engineers (ASME) and the Occupational Safety and Health Administration (OSHA) in the United States, enforce rigorous standards to ensure safety and prevent catastrophic failures. For example, ASME’s Boiler and Pressure Vessel Code outlines stringent requirements for material selection, design, and testing. Compliance with these regulations can be time-consuming and costly, requiring specialized expertise and resources. Additionally, frequent updates to these regulations require manufacturers to adapt continually, adding to production timelines and costs.
Maintenance and Inspection Challenges:
Regular maintenance and inspection are essential for pressure vessels to ensure safety and optimal performance, yet they present logistical and financial challenges. In industries such as oil and gas, chemical processing, and power generation, pressure vessels are often located in remote or hazardous environments, making access difficult. Furthermore, downtime associated with maintenance can impact operational efficiency, leading to productivity losses. The U.S. Environmental Protection Agency (EPA) mandates that facilities handling hazardous materials adhere to stringent maintenance protocols, further intensifying the need for regular inspections. The costs and logistical difficulties of maintaining compliance in these sectors can deter investment in new pressure vessel infrastructure.
Environmental and Safety Concerns:
The risk of leaks or catastrophic failures due to extreme pressures and temperatures is a significant safety concern. Incidents involving pressure vessels can lead to severe environmental consequences, particularly in the petrochemical and nuclear industries. Regulatory agencies like the EPA enforce strict environmental standards, compelling companies to invest in safety enhancements and advanced monitoring technologies. While these measures are necessary, they add to the financial burden and complexity of pressure vessel operations, challenging companies to balance safety and environmental compliance with cost-efficiency.
Market Segmentation Analysis:
By Type, the market is categorized into boilers, nuclear reactors, separators, and others. Boilers hold a significant share due to their widespread use in power generation and industrial applications where steam production is essential. Nuclear reactors also represent a notable segment, driven by investments in nuclear power as a cleaner energy source. Separators are commonly used in oil and gas and chemical processing, where they are vital for separating gas, oil, and water under high pressure.
By Technology, the market includes welded and composite pressure vessels. Welded vessels, constructed using advanced welding techniques, are prominent due to their durability and ability to withstand extreme conditions. Composite pressure vessels are gaining traction, particularly in sectors like aerospace and automotive, where lightweight yet strong materials are crucial. Composite vessels, often made with materials like carbon fiber, provide superior corrosion resistance and weight reduction, meeting the demands for high-performance applications.
By End User, the market is segmented into oil and gas, chemicals, power generation, and others. The oil and gas industry leads this segment, as pressure vessels are essential for storage, separation, and transportation. Power generation is also a significant end user, with nuclear, thermal, and renewable energy plants relying on pressure vessels to manage high-pressure systems. Additionally, the chemical industry uses pressure vessels for various processes, such as chemical synthesis and material processing, underscoring the broad applicability of these vessels across diverse industrial sectors.
Segmentations:
By Application:- Boilers
- Reactors
- Heat Exchangers
- Autoclaves
- Stainless Steel
- Titanium
- Aluminum
- Others (Carbon Steel, Nickel alloy, Hastelloy)
- Oil & Gas Industry
- Food & Beverages Industry
- Chemical Industry
- Energy Industry
- Other (Paper & Pulp, Pharmaceuticals, etc.)
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a significant share of the Pressure Vessels Market, accounting for approximately 35% of the global market. The United States leads this region due to its well-established energy and industrial sectors, particularly in oil and gas, petrochemicals, and power generation. The region’s demand for pressure vessels is driven by an increasing focus on expanding domestic energy production, including investments in natural gas and renewable energy projects. According to the U.S. Energy Information Administration (EIA), energy production in the U.S. continues to grow, necessitating reliable equipment such as pressure vessels for storage, transportation, and processing. Additionally, regulatory frameworks like the American Society of Mechanical Engineers (ASME) Boiler and Pressure Vessel Code set stringent standards for pressure vessel manufacturing, ensuring high-quality and safety compliance across industries.
Asia-Pacific
The Asia-Pacific region represents the fastest-growing segment in the pressure vessels market, capturing around 30% of global revenue. Countries such as China, India, and Japan are driving this growth due to rapid industrialization, urbanization, and infrastructure development. China, in particular, is investing heavily in the energy sector, with numerous power generation and petrochemical projects that require pressure vessels. Additionally, India’s expanding manufacturing base is increasing demand for industrial equipment, including pressure vessels used in chemical processing and pharmaceuticals. Government initiatives, such as China’s Belt and Road Initiative and India’s Make in India program, are also attracting foreign investment, boosting demand for pressure vessels as part of larger industrial projects. As renewable energy projects grow in the region, pressure vessels designed for solar and nuclear power plants are expected to see substantial demand.
Europe
Europe accounts for approximately 20% of the global pressure vessels market, with Germany, France, and the United Kingdom being key contributors. Europe’s well-established chemical and power generation sectors drive demand for pressure vessels, particularly in chemical processing and nuclear energy. The European Union’s commitment to reducing carbon emissions has led to increased investments in renewable energy, including nuclear power, which relies on pressure vessels for critical processes. For example, France is investing in nuclear reactor upgrades to meet both energy demand and climate goals. Additionally, Europe’s regulatory framework is among the most stringent, with agencies like the European Committee for Standardization (CEN) enforcing high safety standards that require manufacturers to invest in advanced technologies and materials.
Latin America
Latin America holds around 10% of the pressure vessels market share, driven by the growth of the oil and gas sector in countries like Brazil, Mexico, and Argentina. Brazil, in particular, has a thriving petrochemical industry that relies on pressure vessels for refining and storage processes. Furthermore, the region’s growing industrial base, coupled with investments in infrastructure development, is driving the adoption of pressure vessels. Latin American governments are also incentivizing oil and gas exploration, increasing demand for high-capacity and corrosion-resistant pressure vessels that can operate in challenging environments.
Middle East & Africa
The Middle East & Africa represent the remaining 5% of the global pressure vessels market. The Middle East, led by countries such as Saudi Arabia and the United Arab Emirates, sees consistent demand for pressure vessels due to its expansive oil and gas sector. The region’s focus on increasing production capacity and refining infrastructure supports the need for durable and high-performance pressure vessels. In Africa, infrastructure development in sectors such as chemicals and power generation, especially in South Africa and Nigeria, is boosting demand. However, limited industrialization and infrastructure challenges restrict market growth in some areas. Nevertheless, as investment in regional industrial development grows, the demand for pressure vessels is expected to rise gradually.
Key Player Analysis:
- Babcock & Wilcox Enterprises, Inc.
- General Electric (GE)
- Larsen & Toubro Limited
- Doosan Heavy Industries & Construction Co., Ltd.
- Mitsubishi Heavy Industries, Ltd.
- Thyssenkrupp AG
- IHI Corporation
- Samuel Pressure Vessel Group
- Westinghouse Electric Company LLC
- Halvorsen Company
Competitive Analysis:
The Pressure Vessels Market is highly competitive, with key players such as Babcock & Wilcox Enterprises, General Electric, and Doosan Heavy Industries leading due to their comprehensive product portfolios and advanced manufacturing capabilities. These companies leverage extensive R&D to enhance pressure vessel efficiency, durability, and compliance with stringent safety standards. Competition is driven by the need for innovation, as manufacturers focus on developing vessels with advanced materials like stainless steel and carbon composites to meet diverse industrial requirements. Additionally, companies are adopting modular and prefabricated designs to reduce installation times and offer customizable solutions for sectors such as oil and gas, power generation, and chemicals. Strategic partnerships and global expansion initiatives are also common, allowing market leaders to strengthen their presence in emerging regions like Asia-Pacific, where industrialization and energy projects are rapidly increasing. This competitive landscape highlights a strong focus on technology and safety advancements to meet growing demand across industrial applications.
Recent Developments:
- In early 2024, Babcock & Wilcox secured a $16 million grant from the Wyoming Energy Authority to advance its BrightLoop™ hydrogen generation project with integrated carbon capture. This development reflects the company’s focus on expanding renewable energy applications and decarbonization technologies, including other projects across Wyoming, Louisiana, and Ohio. Additionally, Babcock & Wilcox reported an increased pipeline of project opportunities totaling $9 billion, underscoring strong global demand for its environmental and renewable solutions.
- Doosan Heavy Industries announced in 2023 its active participation in a series of large-scale nuclear projects in South Korea and the UAE, highlighting its role as a key supplier of pressure vessels for nuclear power generation. This aligns with the region's focus on clean energy transitions, where Doosan aims to leverage its expertise in large, high-pressure vessels to support nuclear plant expansions and upgrades.
- In 2022, General Electric (GE) expanded its offerings in the renewable energy sector by introducing pressure vessels designed for hydrogen storage and carbon capture applications. GE’s recent focus has been on integrating these vessels into their gas turbines and renewable energy systems, as well as supporting projects aimed at reducing emissions from fossil fuel-based plants. This expansion showcases GE's commitment to sustainability and adaptation to the changing energy landscape.
- In 2021, Mitsubishi Heavy Industries secured contracts for pressure vessels used in ammonia production plants across Asia, particularly in Japan and South Korea. With ammonia gaining attention as a hydrogen carrier and fuel alternative, Mitsubishi’s contracts reflect the growing interest in pressure vessels for chemical and energy applications. These projects align with Mitsubishi’s strategic focus on green energy and sustainable chemical production, expanding its footprint in the Asian market.
Market Concentration & Characteristics:
The Pressure Vessels Market is moderately concentrated, with prominent players like Babcock & Wilcox, General Electric, Doosan Heavy Industries, and Mitsubishi Heavy Industries holding significant market shares due to their advanced manufacturing capabilities and global presence. These companies dominate through their expertise in producing high-performance pressure vessels for diverse applications, including power generation, oil and gas, and chemicals. The market is characterized by high entry barriers, as stringent regulatory standards, such as the American Society of Mechanical Engineers (ASME) Boiler and Pressure Vessel Code, demand extensive testing and certification. Additionally, the market is increasingly driven by the integration of new materials, such as composites and advanced alloys, which enhance durability and performance under extreme conditions. This focus on technological innovation, coupled with the need for customization and adherence to safety standards, underscores the competitive nature of the market, where major players continually invest in R&D to maintain their edge and address evolving industry demands.
Report Coverage:
The research report offers an in-depth analysis based on Application, Primary Material, Industry, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The pressure vessels market will see increased demand in renewable energy applications, especially in solar thermal and nuclear power, as countries invest in clean energy sources.
- Advancements in material technology, including the use of composites and corrosion-resistant alloys.
- Prefabricated and modular pressure vessels will gain popularity, enabling faster installation, reduced on-site labor, and greater customization options for end users.
- The market will benefit from rising investments in hydrogen and ammonia production as part of the global energy transition, with pressure vessels playing a critical role in these emerging sectors.
- Digital monitoring and IoT integration will become standard, allowing for real-time performance tracking, predictive maintenance, and enhanced safety in operations.
- As regulatory standards become more stringent, pressure vessel manufacturers will increasingly invest in R&D to ensure compliance with evolving safety and environmental requirements.
- Asia-Pacific is expected to drive market growth, fueled by rapid industrialization, urbanization.
- Strategic partnerships between pressure vessel manufacturers and technology firms will accelerate innovation.
- The demand for small-scale, portable pressure vessels will rise in sectors such as pharmaceuticals and food processing, where flexibility and mobility are critical.
- Lifecycle cost reduction will be a priority, with companies seeking to optimize materials, reduce maintenance needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
Q: What is the current size of the Pressure Vessels Market?
Q: What factors are driving the growth of the Pressure Vessels Market?
Q: What are some challenges faced by the Pressure Vessels Market?
Q: Who are the major players in the Pressure Vessels Market?
Q: Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 60,385 million → 2032: USD 80,753.08 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Pressure Vessels Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Pressure Vessels Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Pressure Vessels Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Pressure Vessels Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Pressure Vessels Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Pressure Vessels Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Pressure Vessels Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Pressure Vessels Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 60,385 million → 2032: USD 80,753.08 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Pressure Vessels Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Pressure Vessels Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Pressure Vessels Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Pressure Vessels Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
