
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
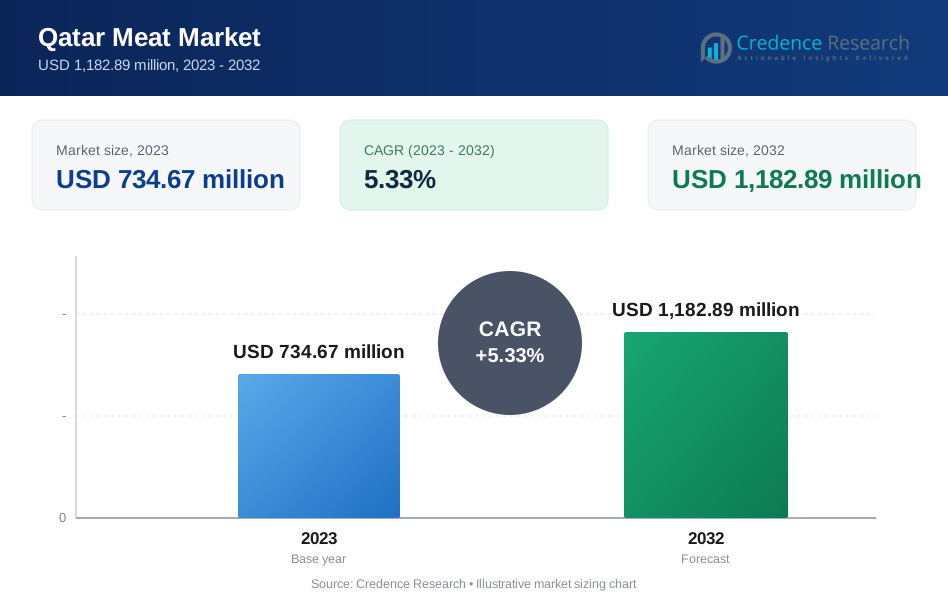
| Qatar Meat Market Size 2023 | USD 734.67 Million |
| Qatar Meat Market, CAGR | 5.33% |
| Qatar Meat Market Size 2032 | USD 1,182.89 Million |
Market Overview
The Qatar meat market is projected to grow from USD 734.67 million in 2023 to an estimated USD 1,182.89 million by 2032, with a compound annual growth rate (CAGR) of 5.33% from 2024 to 2032. This robust growth reflects the increasing demand for high-quality meat products driven by rising disposable incomes and an expanding population.
Market drivers for the Qatar meat market include changing dietary preferences, with a growing shift towards protein-rich diets and increased consumption of premium meat products. Additionally, the Qatari government's initiatives to enhance food security and self-sufficiency in meat production play a crucial role. Trends such as the rising popularity of organic and halal-certified meat products, coupled with technological advancements in meat processing, further propel market growth.
Geographically, the demand for meat in Qatar is concentrated in urban areas, with Doha being the primary market due to its high population density and economic activity. Key players in the Qatar meat market include Baladna Q.P.S.C., Widam Food Company Q.P.S.C., and National Food Company (Americana). These companies are investing in expanding their product portfolios and enhancing distribution networks to capitalize on the growing market opportunities.
Market Drivers
Rising Disposable Incomes and Changing Dietary Preferences
The increase in disposable incomes among Qatar's population has significantly influenced the meat market. For instance, as of 2017, the per capita disposable national income in Qatar was about 55.7 thousand U.S. dollars. Higher incomes allow consumers to spend more on quality food products, including premium meat cuts. As affluence grows, there's a marked shift in dietary preferences towards protein-rich diets. The Qatari population, influenced by global dietary trends and a growing awareness of nutrition, increasingly seeks out meat as a primary source of protein. This shift is further supported by the urban lifestyle, which often includes dining out and purchasing high-quality, convenient food products. The combination of higher spending power and evolving dietary habits drives the demand for a diverse range of meat products, from fresh and frozen to processed and ready-to-cook options.
For instance, programs aimed at improving animal husbandry practices and increasing local meat production capacity reduce dependence on imports and ensure a steady supply of high-quality meat products. The Qatari government's commitment to enhancing food security has been a critical driver for the meat market. Recognizing the strategic importance of a stable and secure food supply, the government has implemented various initiatives to boost domestic meat production. Investments in modern agricultural techniques, subsidies for livestock farmers, and the development of advanced meat processing facilities are key components of this strategy. For instance, programs aimed at improving animal husbandry practices and increasing local meat production capacity reduce dependence on imports and ensure a steady supply of high-quality meat products. These initiatives not only contribute to market growth but also enhance the overall resilience of Qatar's food supply chain.
Technological Advancements in Meat Processing and Distribution
Technological innovations in meat processing and distribution are transforming the Qatar meat market. Advanced processing techniques ensure higher standards of hygiene and quality, which are crucial for meeting consumer expectations and regulatory requirements. Automation and the use of cutting-edge equipment in slaughterhouses and processing plants enhance efficiency and product consistency. Additionally, advancements in cold chain logistics and storage solutions ensure that meat products remain fresh and safe from the point of production to the end consumer. These technological improvements not only improve the quality and variety of meat products available in the market but also reduce waste and operational costs, contributing to market growth.
Growing Demand for Organic and Halal-Certified Meat Products
Consumer preferences in Qatar are increasingly leaning towards organic and halal-certified meat products. The demand for organic meat is driven by health-conscious consumers who prioritize natural and ethically produced food items. Organic meat, free from synthetic additives and hormones, appeals to a segment of the market that values health and environmental sustainability. Concurrently, the demand for halal-certified meat, which adheres to Islamic dietary laws, is a significant driver in Qatar's predominantly Muslim population. Halal certification is not only a religious requirement but also assures consumers of high standards of cleanliness and quality. The increasing availability of organic and halal-certified meat products in retail and foodservice channels caters to these growing consumer preferences, thus driving market growth.
Market Trends
Increasing Demand for Convenience and Ready-to-Eat Meat Products
One of the prominent trends in the Qatar meat market is the rising demand for convenience and ready-to-eat meat products. This trend is driven by the fast-paced lifestyle of the urban population, which has less time for meal preparation. As a result, consumers increasingly prefer pre-cooked, marinated, and packaged meat products that offer quick and easy meal solutions without compromising on taste and quality. For instance, the market has seen a surge in products such as ready-to-cook kebabs, pre-seasoned chicken, and heat-and-serve meat dishes. The market has seen a surge in products such as ready-to-cook kebabs, pre-seasoned chicken, and heat-and-serve meat dishes, which cater to the needs of busy professionals and families. Retailers and food manufacturers are capitalizing on this trend by expanding their product lines to include a variety of ready-to-eat and convenience meat options. This trend not only reflects changing consumer behavior but also drives innovation in product development and packaging, ensuring that these products meet the highest standards of quality and safety.
Emphasis on Sustainability and Traceability in Meat Production
Sustainability and traceability have become crucial trends shaping the Qatar meat market. For instance, consumers are increasingly concerned about the environmental impact of meat production and are seeking products that are sustainably sourced. This trend is particularly significant in a market that relies heavily on imports to meet its meat demand. In response, producers and suppliers are adopting more sustainable practices, such as improving feed efficiency, reducing greenhouse gas emissions, and ensuring humane treatment of livestock. Additionally, there is a growing emphasis on traceability, with consumers demanding transparency about the origins of their meat products. Technological advancements, such as blockchain and RFID tagging, are being employed to provide detailed information about the entire supply chain, from farm to table 6. These technologies enable consumers to trace the journey of their meat products, ensuring that they are purchasing high-quality, ethically produced meat. The emphasis on sustainability and traceability not only addresses consumer concerns but also enhances the overall integrity and reputation of the meat market in Qatar. This trend is likely to continue, driven by both consumer demand and regulatory requirements, fostering a more sustainable and transparent meat industry.
Market Restraints and Challenges
Dependence on Meat Imports and Supply Chain Vulnerabilities
A significant restraint for the Qatar meat market is its heavy dependence on meat imports, which exposes the market to various supply chain vulnerabilities. Qatar imports a substantial portion of its meat due to limited domestic production capabilities, making the market susceptible to international trade fluctuations, geopolitical tensions, and logistical challenges. Disruptions in global supply chains, such as those caused by political instability in exporting countries or transportation bottlenecks, can lead to shortages and price volatility in the local market. This reliance on imports also subjects the market to foreign exchange risks and fluctuating import tariffs, further complicating cost management for meat suppliers and retailers. The challenge of ensuring a consistent and reliable supply of high-quality meat products necessitates strategic planning and investment in domestic production and alternative sourcing strategies.
High Production Costs and Regulatory Compliance
The high costs associated with meat production and stringent regulatory compliance requirements present significant challenges for the Qatar meat market. Local meat production, though limited, involves considerable expenses related to feed, veterinary services, and maintaining high standards of hygiene and animal welfare. Additionally, complying with stringent food safety and quality regulations incurs further costs, as producers must invest in advanced processing equipment and adhere to rigorous inspection and certification processes. These factors contribute to higher operational costs, which can limit the competitiveness of locally produced meat against imported alternatives. Moreover, small-scale producers often face financial and technical barriers in meeting regulatory standards, hindering their ability to scale up production and compete effectively in the market. Addressing these challenges requires coordinated efforts to provide financial support, technological assistance, and streamlined regulatory frameworks to encourage domestic production and ensure market stability.
Market Segmentation Analysis
By Type
In Qatar, beef remains a popular choice, catering to diverse preferences for various cuts and preparations, driven by both traditional dishes and international cuisine influences. Lamb and mutton hold cultural and traditional significance, especially during festivals and celebrations. Poultry, particularly chicken, is widely consumed for its affordability, versatility, and nutritional benefits, making it a staple in household diets and fast-food chains. Processed meat, including sausages, cold cuts, and ready-to-cook products, meets the demand for convenience among busy urban consumers. Halal certification is crucial, ensuring meat products comply with Islamic dietary laws and maintaining consistent demand across all consumer groups. The rising health consciousness and environmental awareness boost the demand for organic and sustainably sourced meat products, appealing to a niche but expanding market. Additionally, healthier meat alternatives, such as lean meats and fortified products, are gaining traction among health-conscious consumers seeking lower-fat and nutrient-enriched options.
By Product
Fresh meat remains a preferred choice for its quality and taste, widely available in supermarkets, butcher shops, and specialty meat stores. Frozen meat products cater to the need for longer shelf life and convenience, popular among households and institutional buyers. Processed and convenience meat, including pre-cooked and marinated options, are favored for their ease of preparation and time-saving attributes. High-end consumers and the hospitality sector drive demand for premium cuts of meat, often associated with fine dining and special occasions. Sausages and cold cuts are popular for quick snacks and easy meal additions, appealing to both households and the foodservice industry. Pre-marinated and value-added meats offer convenience and flavor variety, attracting consumers looking for quick yet gourmet meal options.
Segments
Based on Type
- Beef
- Lamb and Mutton
- Poultry
- Processed Meat
- Halal Meat
- Organic and Sustainable Meat
- Healthier Meat Alternatives
Based on Product
- Fresh Meat
- Frozen Meat
- Processed and Convenience Meat
- Premium Cuts
- Sausages and Cold Cuts
- Marinated and Value-Added Meat
Based on Application
- Household Consumption
- Restaurants and Foodservices
- Fast Food Chains
- Institutional Food Service
- Tourist and Hospitality Industry
Based on End User
- Individual Consumers
- Catering and Event Services
- Hotels and Resorts
- Institutions
- Restaurants and Fast-Food Chains
- Exports and International Markets
Based on Price Range
- Economy Meat
- Mid-Range Meat
- Premium Meat
Based on Distribution Channel
- Supermarkets and Hypermarkets
- Traditional Butcher Shops
- Specialty Meat Stores
- Online Meat Retail
- Restaurants and Foodservice Suppliers
- Meat Wholesalers
Based on Region
- Doha
- Al Rayyan
- Al Wakrah
Regional Analysis
Doha (55%):
Doha is the largest and most significant market for meat products in Qatar, commanding approximately 55% of the total market share. This dominance is attributed to its status as the capital city, with the highest population density and economic activity. Doha's diverse and affluent population drives substantial demand for various meat products, ranging from fresh and frozen meats to premium cuts and processed meats. The city's vibrant hospitality and foodservice sectors, including numerous restaurants, hotels, and catering services, further bolster meat consumption. Additionally, Doha's well-developed retail infrastructure, including supermarkets, hypermarkets, and specialty meat stores, ensures wide availability and accessibility of meat products to consumers.
Al Rayyan (20%):
Al Rayyan, the second-largest market, accounts for around 20% of the Qatar meat market share. The region has experienced significant urbanization and population growth in recent years, contributing to increased demand for meat products. Al Rayyan's expanding residential areas and commercial developments, including shopping malls and foodservice establishments, drive the need for a diverse range of meat offerings. The region's growing middle-class population, with rising disposable incomes, favors mid-range and premium meat products. Retail channels in Al Rayyan, including traditional butcher shops and modern supermarkets, cater to varied consumer preferences, ensuring steady market growth.
Key players
- Qatar Meat Production Co. (Q-Meat)
- Baladna
- Al Meera Consumer Goods Company
- Carrefour Qatar
- Lulu Hypermarket
- Widam Food Company QSC
- Al Qusaimi Meat Co.
- Mawashi
Competitive Analysis
The Qatar meat market is highly competitive, with several key players striving to capture market share through diverse strategies. Qatar Meat Production Co. (Q-Meat) and Baladna are leading domestic producers, emphasizing quality and sustainability in their offerings. Al Meera Consumer Goods Company, Carrefour Qatar, and Lulu Hypermarket dominate the retail landscape, leveraging extensive distribution networks and a wide variety of products to meet consumer demands. Widam Food Company QSC, known for its large-scale meat processing capabilities, focuses on both local and international markets. Al Qusaimi Meat Co. and Mawashi are notable for their specialized meat products and strong presence in traditional retail channels. These players compete on factors such as product quality, price, and innovation, constantly adapting to changing consumer preferences and market dynamics to maintain their competitive edge.
Recent Developments
In March 2023, Qatar Meat Production Co. (Q-Meat) announced the opening of a state-of-the-art meat processing facility in Doha. This facility is equipped with advanced technology to enhance the quality and efficiency of meat processing, ensuring higher standards of hygiene and safety. The new plant is part of Q-Meat’s strategy to increase its production capacity and reduce dependency on meat imports. By investing in local infrastructure, Q-Meat aims to meet the growing demand for high-quality meat products in Qatar while promoting food security and sustainability. The facility is expected to create numerous job opportunities and contribute significantly to the local economy.
In June 2023, Baladna, a leading dairy and meat producer in Qatar, launched a new line of organic meat products. This move aligns with the increasing consumer demand for health-conscious and environmentally sustainable food options. The organic meat range includes beef, lamb, and poultry, all sourced from animals raised on organic feed and without the use of synthetic hormones or antibiotics. Baladna’s commitment to organic farming practices not only caters to the niche market of health-conscious consumers but also reinforces its position as a leader in sustainable agriculture. The company has invested in organic certification processes to ensure compliance with international standards, thereby enhancing its brand reputation and market reach.
In September 2023, Widam Food Company QSC entered into a strategic partnership with a leading technology firm to implement blockchain technology in its supply chain. This initiative aims to enhance transparency and traceability in the meat supply chain, from farm to table. By adopting blockchain, Widam ensures that consumers can access detailed information about the origins and handling of their meat products, thereby building trust and confidence in their brand. This technological advancement is part of Widam’s broader digital transformation strategy to improve operational efficiency and product quality. The partnership is expected to set new standards in the meat industry, positioning Widam as a pioneer in leveraging technology for food safety and consumer assurance.
Market Concentration and Characteristics
The Qatar meat market is characterized by a moderate to high level of concentration, with a few key players such as Qatar Meat Production Co. (Q-Meat), Baladna, and Widam Food Company QSC dominating the market. These companies leverage advanced processing technologies, extensive distribution networks, and strong brand recognition to maintain significant market shares. The market is distinguished by its emphasis on quality and halal certification, reflecting consumer preferences and regulatory requirements. Additionally, the increasing demand for organic and sustainably sourced meat products highlights a shift towards health-conscious and environmentally aware consumption patterns. The presence of both large-scale retailers like Carrefour Qatar and Lulu Hypermarket, along with traditional butcher shops and specialty meat stores, provides diverse purchasing options for consumers, ensuring accessibility and variety in the meat market.
Report Coverage
The research report offers an in-depth analysis based on Type, Product, Application, End User, Price Range, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Qatar meat market is expected to maintain steady growth, driven by rising disposable incomes and evolving dietary preferences, with an emphasis on high-quality meat products.
- Investments in modern meat processing facilities and agricultural practices will likely boost domestic meat production, reducing reliance on imports and enhancing food security.
- Adoption of advanced technologies such as blockchain and AI in the supply chain will improve traceability, safety, and operational efficiency, meeting consumer demands for transparency.
- Growing consumer awareness about health and environmental sustainability will drive demand for organic and sustainably sourced meat products, creating new market opportunities.
- As the predominantly Muslim population continues to prioritize halal-certified meat, the market will see further investments in ensuring compliance with Islamic dietary laws.
- The market will witness a broader range of meat products, including convenience and ready-to-eat options, catering to the fast-paced lifestyles of urban consumers.
- Expansion and modernization of retail channels, including supermarkets, hypermarkets, and online platforms, will improve accessibility and convenience for consumers.
- The demand for premium cuts and high-end meat products will rise, driven by affluent consumers and the hospitality sector seeking superior quality and unique offerings.
- Producers and retailers will increasingly adopt sustainable practices, such as reducing carbon footprints and improving animal welfare, to align with global environmental standards.
- Key players will likely engage in strategic partnerships and collaborations to enhance their market position, innovate product lines, and expand their reach within and beyond Qatar.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Disposable Incomes and Changing Dietary Preferences
Higher disposable incomes in Qatar have enabled consumers to spend more on premium and high-quality meat products, while evolving dietary preferences are driving a shift towards protein-rich diets and greater meat consumption.
Government Initiatives for Food Security and Local Production
The Qatari government is investing in modern agricultural practices, subsidies, and advanced processing facilities to boost domestic meat production, reduce reliance on imports, and ensure a stable supply of high-quality meat.
Technological Advancements in Processing and Distribution
Adoption of advanced meat processing technologies and improvements in cold chain logistics are enhancing product quality, safety, and shelf life, making meat products more accessible and appealing to consumers.
Growing Demand for Organic and Halal-Certified Meat
Increasing health consciousness and religious adherence among consumers are fueling demand for organic and halal-certified meat products, prompting producers to expand offerings that meet these standards.
Urbanization and Expansion of Modern Retail Channels
Rapid urbanization, especially in Doha, and the growth of supermarkets, hypermarkets, and online retail platforms are making a wider variety of meat products available and convenient for a diverse and affluent consumer base.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Qatar meat market?
What factors are driving the growth of the Qatar meat market?
How are technological advancements impacting the Qatar meat market?
Why is there an increasing demand for organic and halal-certified meat in Qatar?
Which regions in Qatar dominate the meat market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Beef
- 1.2.2 Lamb and Mutton
- 1.2.3 Poultry
- 1.2.4 Processed Meat
- 1.2.5 Halal Meat
- 1.2.6 Organic and Sustainable Meat
- 1.3 By Product
- 1.3.1 Fresh Meat
- 1.3.2 Frozen Meat
- 1.3.3 Processed and Convenience Meat
- 1.3.4 Premium Cuts
- 1.3.5 Sausages and Cold Cuts
- 1.3.6 Marinated and Value-Added Meat
- 1.4 By Application
- 1.4.1 Household Consumption
- 1.4.2 Restaurants and Foodservices
- 1.4.3 Fast Food Chains
- 1.4.4 Institutional Food Service
- 1.4.5 Tourist and Hospitality Industry
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 734.67 million → 2032: USD 1,182.89 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Qatar Meat Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Qatar Meat Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Qatar Meat Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Qatar Meat Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Qatar Meat Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Qatar Meat Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Qatar Meat Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Qatar Meat Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 734.67 million → 2032: USD 1,182.89 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Qatar Meat Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Beef
- 12.3.7.2 Lamb and Mutton
- 12.3.7.3 Poultry
- 12.3.7.4 Processed Meat
- 12.3.7.5 Halal Meat
- 12.3.7.6 Organic and Sustainable Meat
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Fresh Meat
- 12.4.7.2 Frozen Meat
- 12.4.7.3 Processed and Convenience Meat
- 12.4.7.4 Premium Cuts
- 12.4.7.5 Sausages and Cold Cuts
- 12.4.7.6 Marinated and Value-Added Meat
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Household Consumption
- 12.5.7.2 Restaurants and Foodservices
- 12.5.7.3 Fast Food Chains
- 12.5.7.4 Institutional Food Service
- 12.5.7.5 Tourist and Hospitality Industry
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Qatar Meat End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Qatar Meat Geographic Market Outlook, 2023-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Qatar Meat Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Qatar Meat Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Qatar Meat Production Co. (Q-Meat)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Baladna
- 18.4 Al Meera Consumer Goods Company
- 18.5 Carrefour Qatar
- 18.6 Lulu Hypermarket
- 18.7 Widam Food Company QSC
- 18.8 Al Qusaimi Meat Co.
- 18.9 Mawashi
- 18.10 National Food Company (Americana)
- 18.11 Al Rawaq Trading
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

