
Toll tags, store rollouts and animal IDs set value
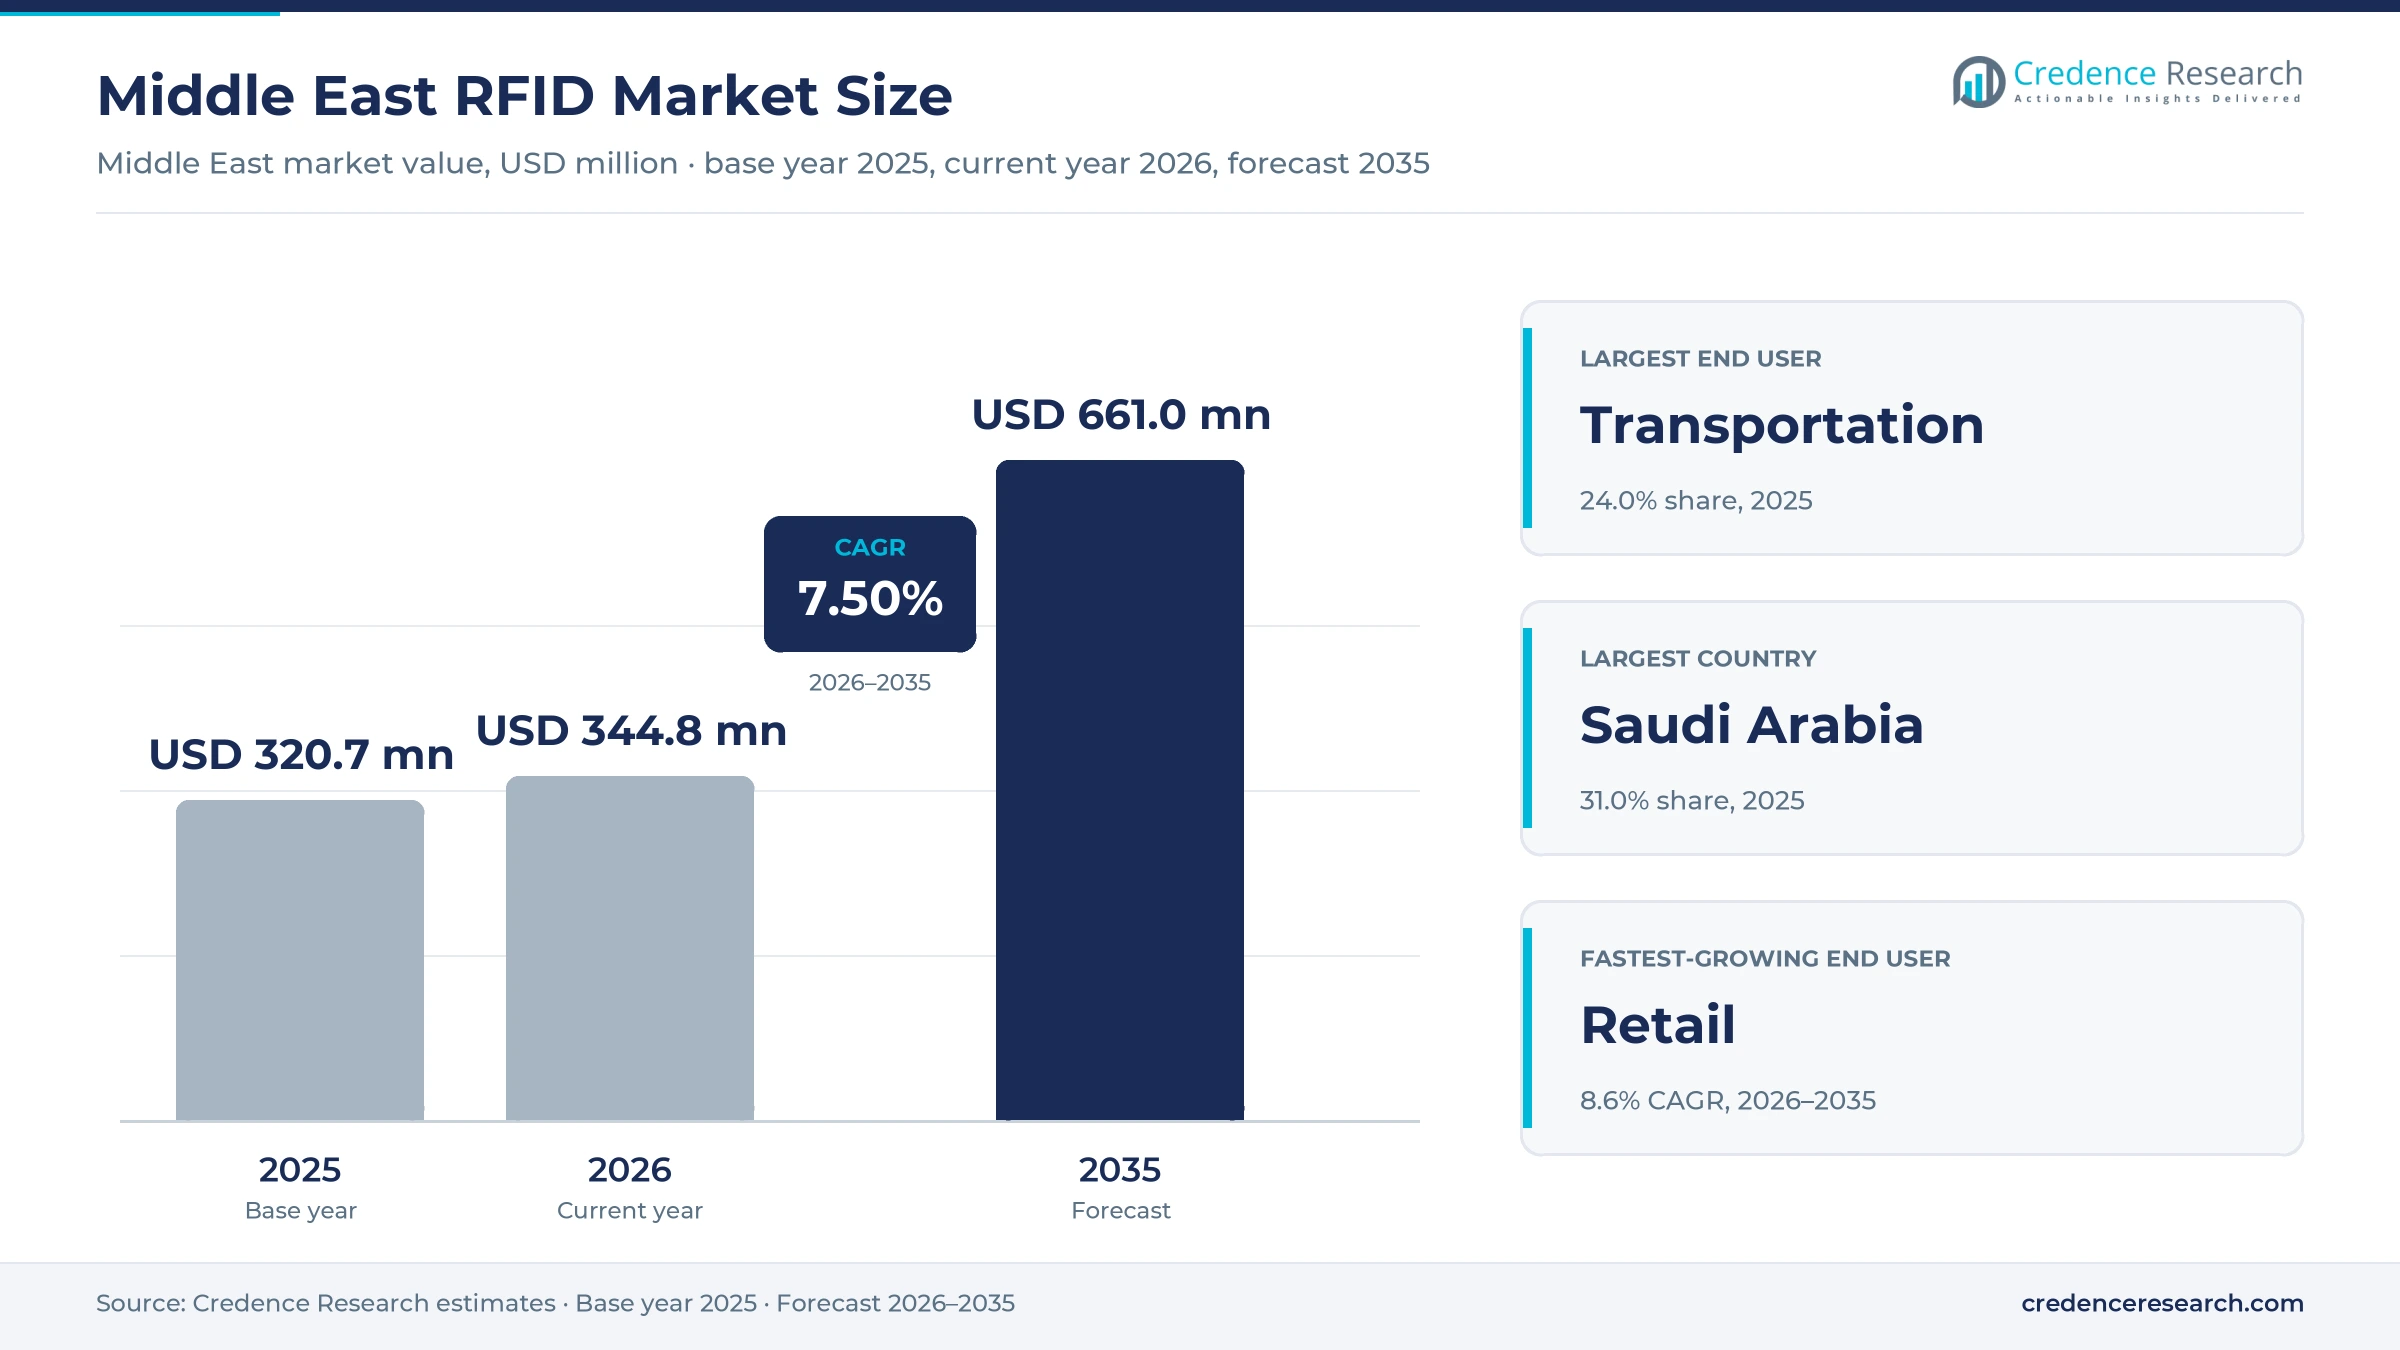
The Middle East RFID market was valued at USD 320.7 million in 2025 and is projected to increase from USD 344.8 million in 2026 to USD 661.0 million by 2035, registering a CAGR of 7.50% during 2026–2035. Spending comes from toll operators that read windshield tags on every vehicle, apparel retailers that tag merchandise for store counts and checkout, agriculture authorities that require animal identification, and hospitals, airports and industrial sites that track equipment. Saudi Arabia held the largest country share, 31.0% in 2025, and it is also the fastest-growing country at 8.2% a year, because Gulf retail groups are opening tagged stores across its cities and its camel herd now carries microchip-linked passports. The most important commercial change is Landmark Group's decision to put item-level tagging into more than 600 stores across the Gulf, Egypt and Jordan. Growth is held back where governments choose number plate cameras, QR codes or barcodes instead of tags for tolling, parking and transit tickets.
Tags, readers and software bought inside the region count
The market counts what buyers in Saudi Arabia, the UAE, Turkey, Qatar and the rest of the Middle East spend on RFID tags, labels, cards and microchips, on fixed, handheld and lane readers and printers, and on middleware, integration and managed services across low, high and ultra-high frequency bands. Toll operators sell windshield tags to drivers, retailers buy through label converters and integrators, and ministries buy tracking systems through tenders.
Toll charges, parking fees, plain barcode equipment and Bluetooth or camera-based tracking are excluded. The value chain runs from foreign chip designers through inlay converters and reader makers to regional integrators and tag issuers, and margins are widest for firms that hold the software and service contracts that turn reads into inventory, toll or health records.
Middle East RFID Market Insights
- The Middle East RFID market was valued at USD 320.7 million in 2025 and is projected to reach USD 661.0 million by 2035, growing at a 7.50% CAGR during 2026–2035.
- Saudi Arabia held 31.0% of 2025 value and grows fastest, as Gulf retail groups add tagged stores and camel owners register microchipped animals.
- Transportation held 24.0% of 2025 value, because Salik in Dubai and HGS in Turkey require a passive tag for every toll-paying vehicle.
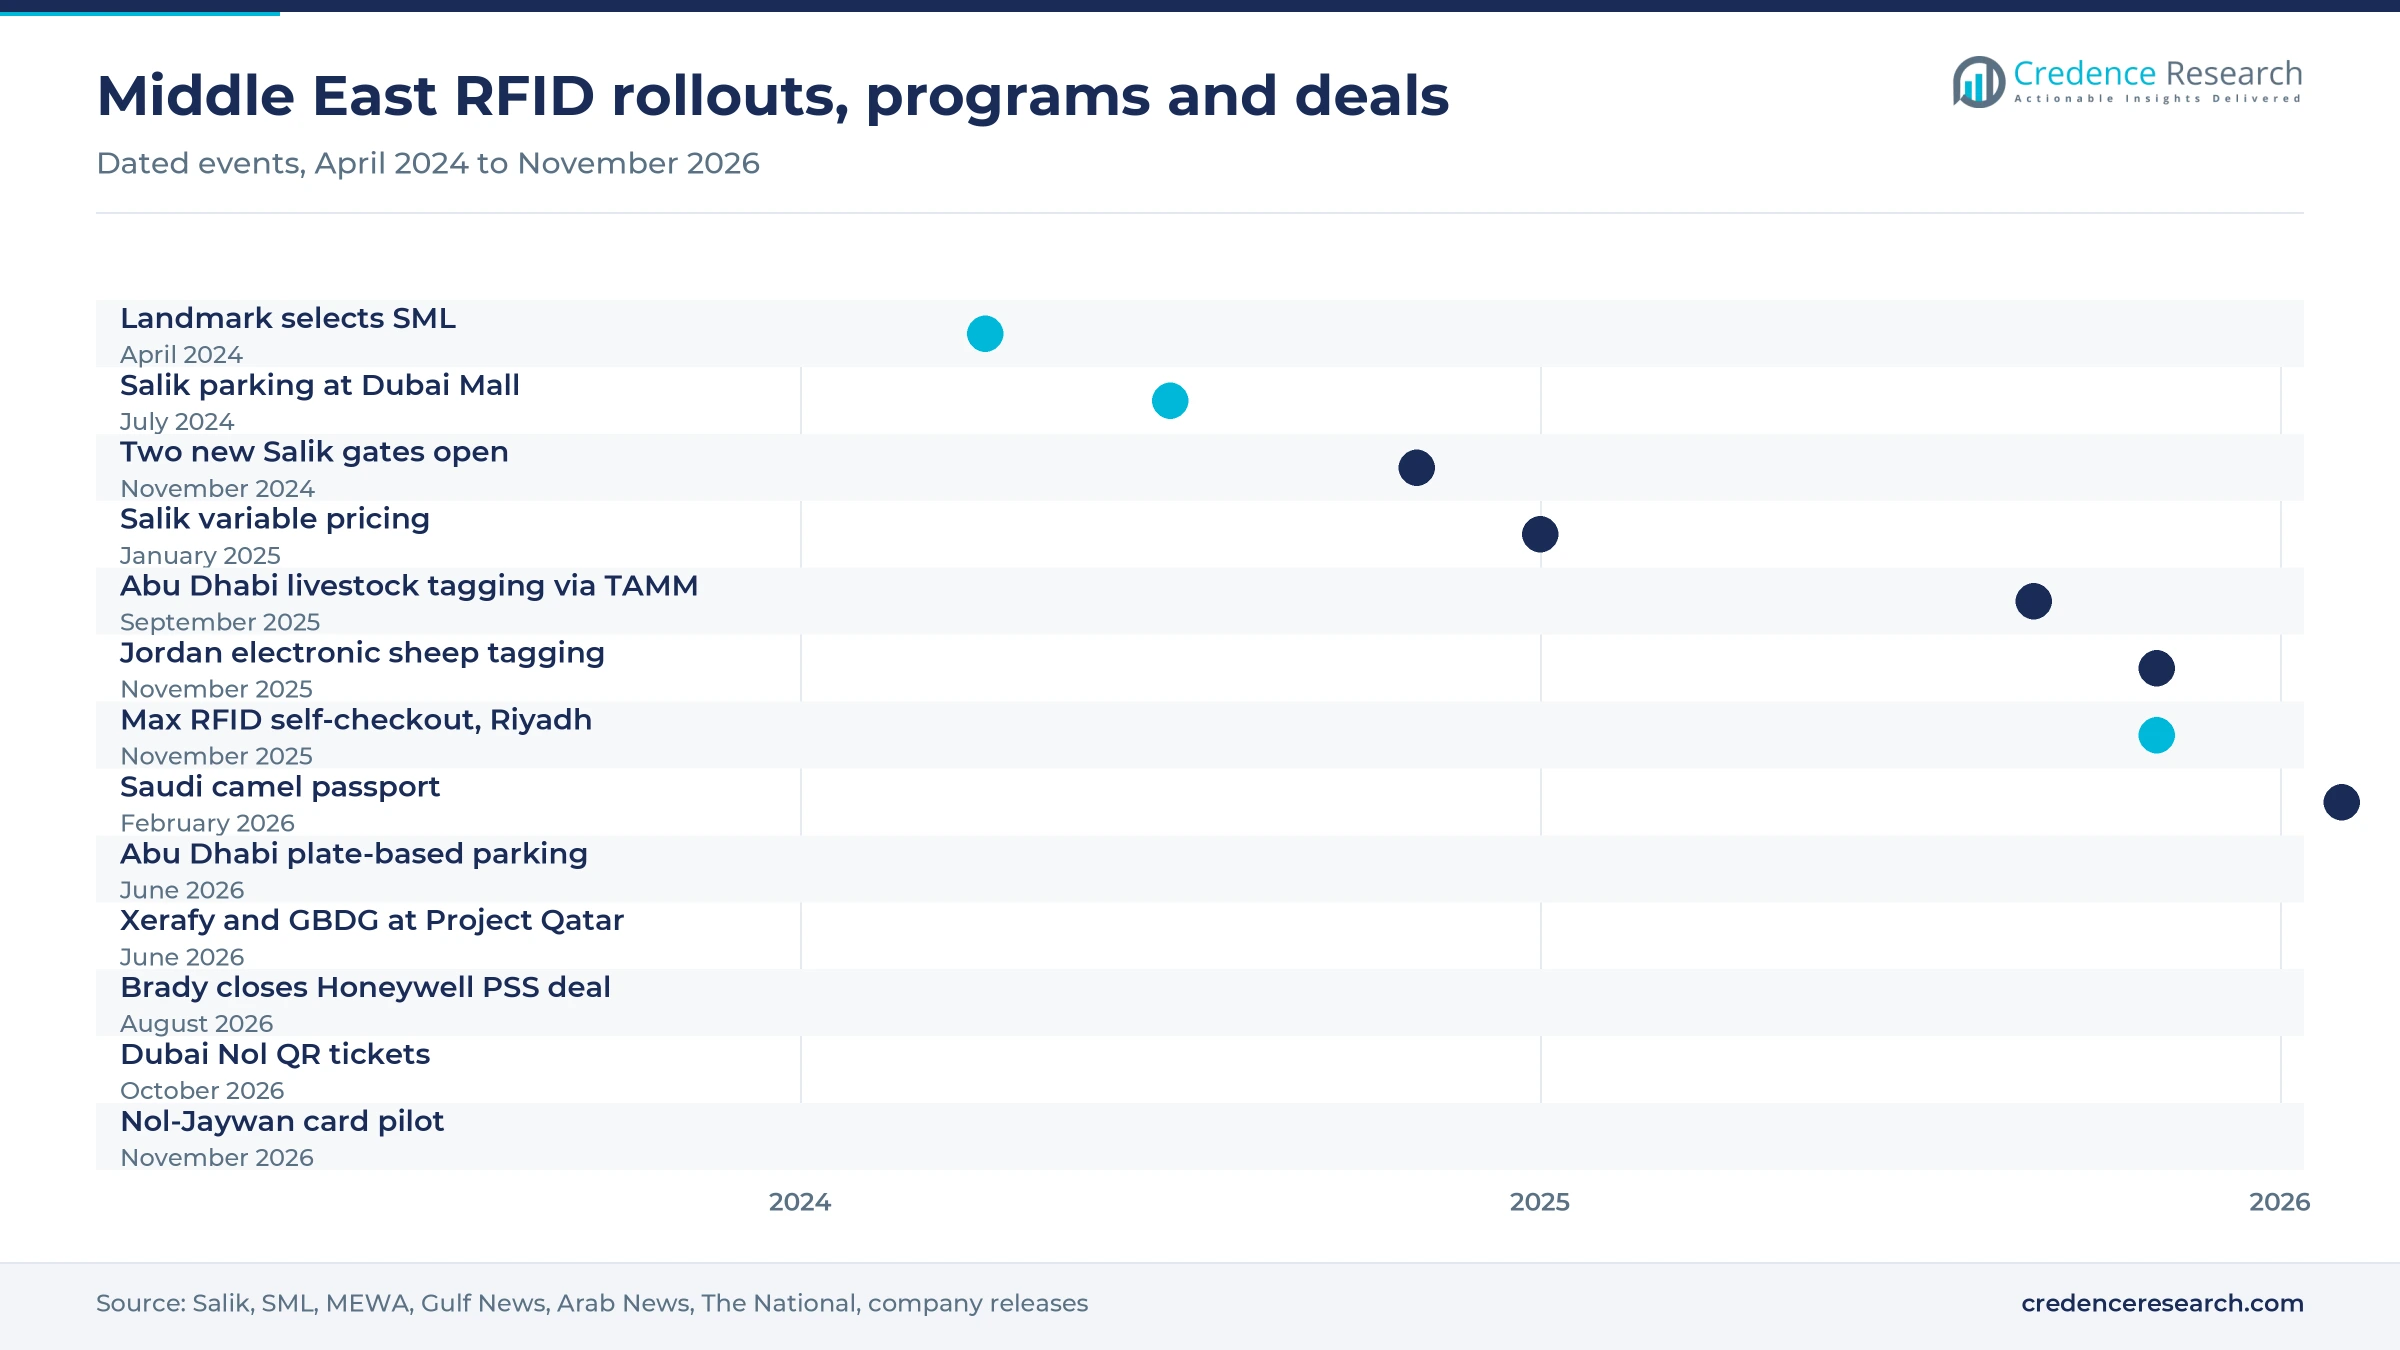
- Landmark Group chose SML in April 2024 to bring item-level tagging to more than 600 stores and 10 distribution centers across eight countries.
- Abu Dhabi tolling and parking run on number plate recognition rather than tags, which shows that public programs can bypass RFID.
Tags and UHF lead while retail use grows fastest
Tags lead while software and services grow fastest
Based on product type, the market is categorized into tags, readers and software and services. Tags led with 44.0% of 2025 value because spending scales with every item, vehicle and animal, even though high-volume passive UHF labels cost only about four cents each, so volume rather than price drives value. Software and Services grow fastest at 8.4% as retailers pay for platforms that use the reads, and SML says its cloud software, chosen by Landmark Group, manages more than 500 million items a week worldwide.
Ultra-high frequency leads and also grows fastest
Based on frequency, the market is categorized into low frequency, high frequency and ultra-high frequency. Ultra-High Frequency led with 50.0% of 2025 value because windshield toll tags, apparel labels and hospital asset tags need read range, and Turkey's HGS toll system runs on passive RFID transponders that lane antennas read at speed. Ultra-high frequency also grows fastest at 8.3% as apparel chains extend item tagging to checkout. High frequency keeps a large share through Dubai Nol transit cards, which stayed valid when QR tickets arrived in October 2026, hotel keys and office credentials, while low frequency serves the microchips in camels and other livestock.
Transportation leads while retail grows fastest
Based on end user, the market is categorized into commercial, animal tracking, transportation, agriculture, security and access control, healthcare, retail and others. Transportation led with 24.0% of 2025 value because tolling makes tags compulsory, and in Dubai a vehicle that passes a Salik gate without a tag draws a Dh100 fine for a first offense, rising to Dh400, according to The National. Retail grows fastest at 8.6% as Landmark Arabia's Max store at U Walk Riyadh, opened in November 2025, uses tags for self-checkout, according to Arab News.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product Type | Tags | 44.0% | Software and Services | 8.4% |
| By Frequency | Ultra-High Frequency | 50.0% | Ultra-High Frequency | 8.3% |
| By End User | Transportation | 24.0% | Retail | 8.6% |
Tags cost cents while toll programs set user prices
Tag prices follow Asian chip and inlay costs, while toll operators and banks decide what drivers pay for a windshield tag. SimplyRFID told RFID Journal in December 2022 that high-volume passive UHF tags cost about 3.6 to four cents when bought in Asia, which sets the reference price for labels that regional retailers buy through converters. Salik charges AED 50 for a tag sold with AED 50 of toll balance, while Turkish banks often give HGS tags free to win payment accounts. Published local prices for store readers and hospital systems are an evidence gap, and integrators recover margin through installation and support.
| Item | Typical price or fee | Basis |
|---|---|---|
| High-volume passive UHF tag, Asia sourcing | About USD 0.036-0.04 per tag | RFID Journal, December 2022 |
| Preprogrammed UHF tag, lots of 100,000 | About USD 0.11 per tag | RFID Journal, December 2022 |
| Salik windshield tag, Dubai | AED 50 plus AED 50 toll balance | Dubizzle Salik guide, 2026 |
| Salik toll per crossing, Dubai | AED 6 peak, AED 4 off-peak | The National, March 2026 |
| CSL handheld UHF reader | USD 995 per unit | RFID Journal, December 2022 |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Tolling, apparel rollouts and animal ID rules lift use
Dubai and Turkey keep toll payments on windshield tags
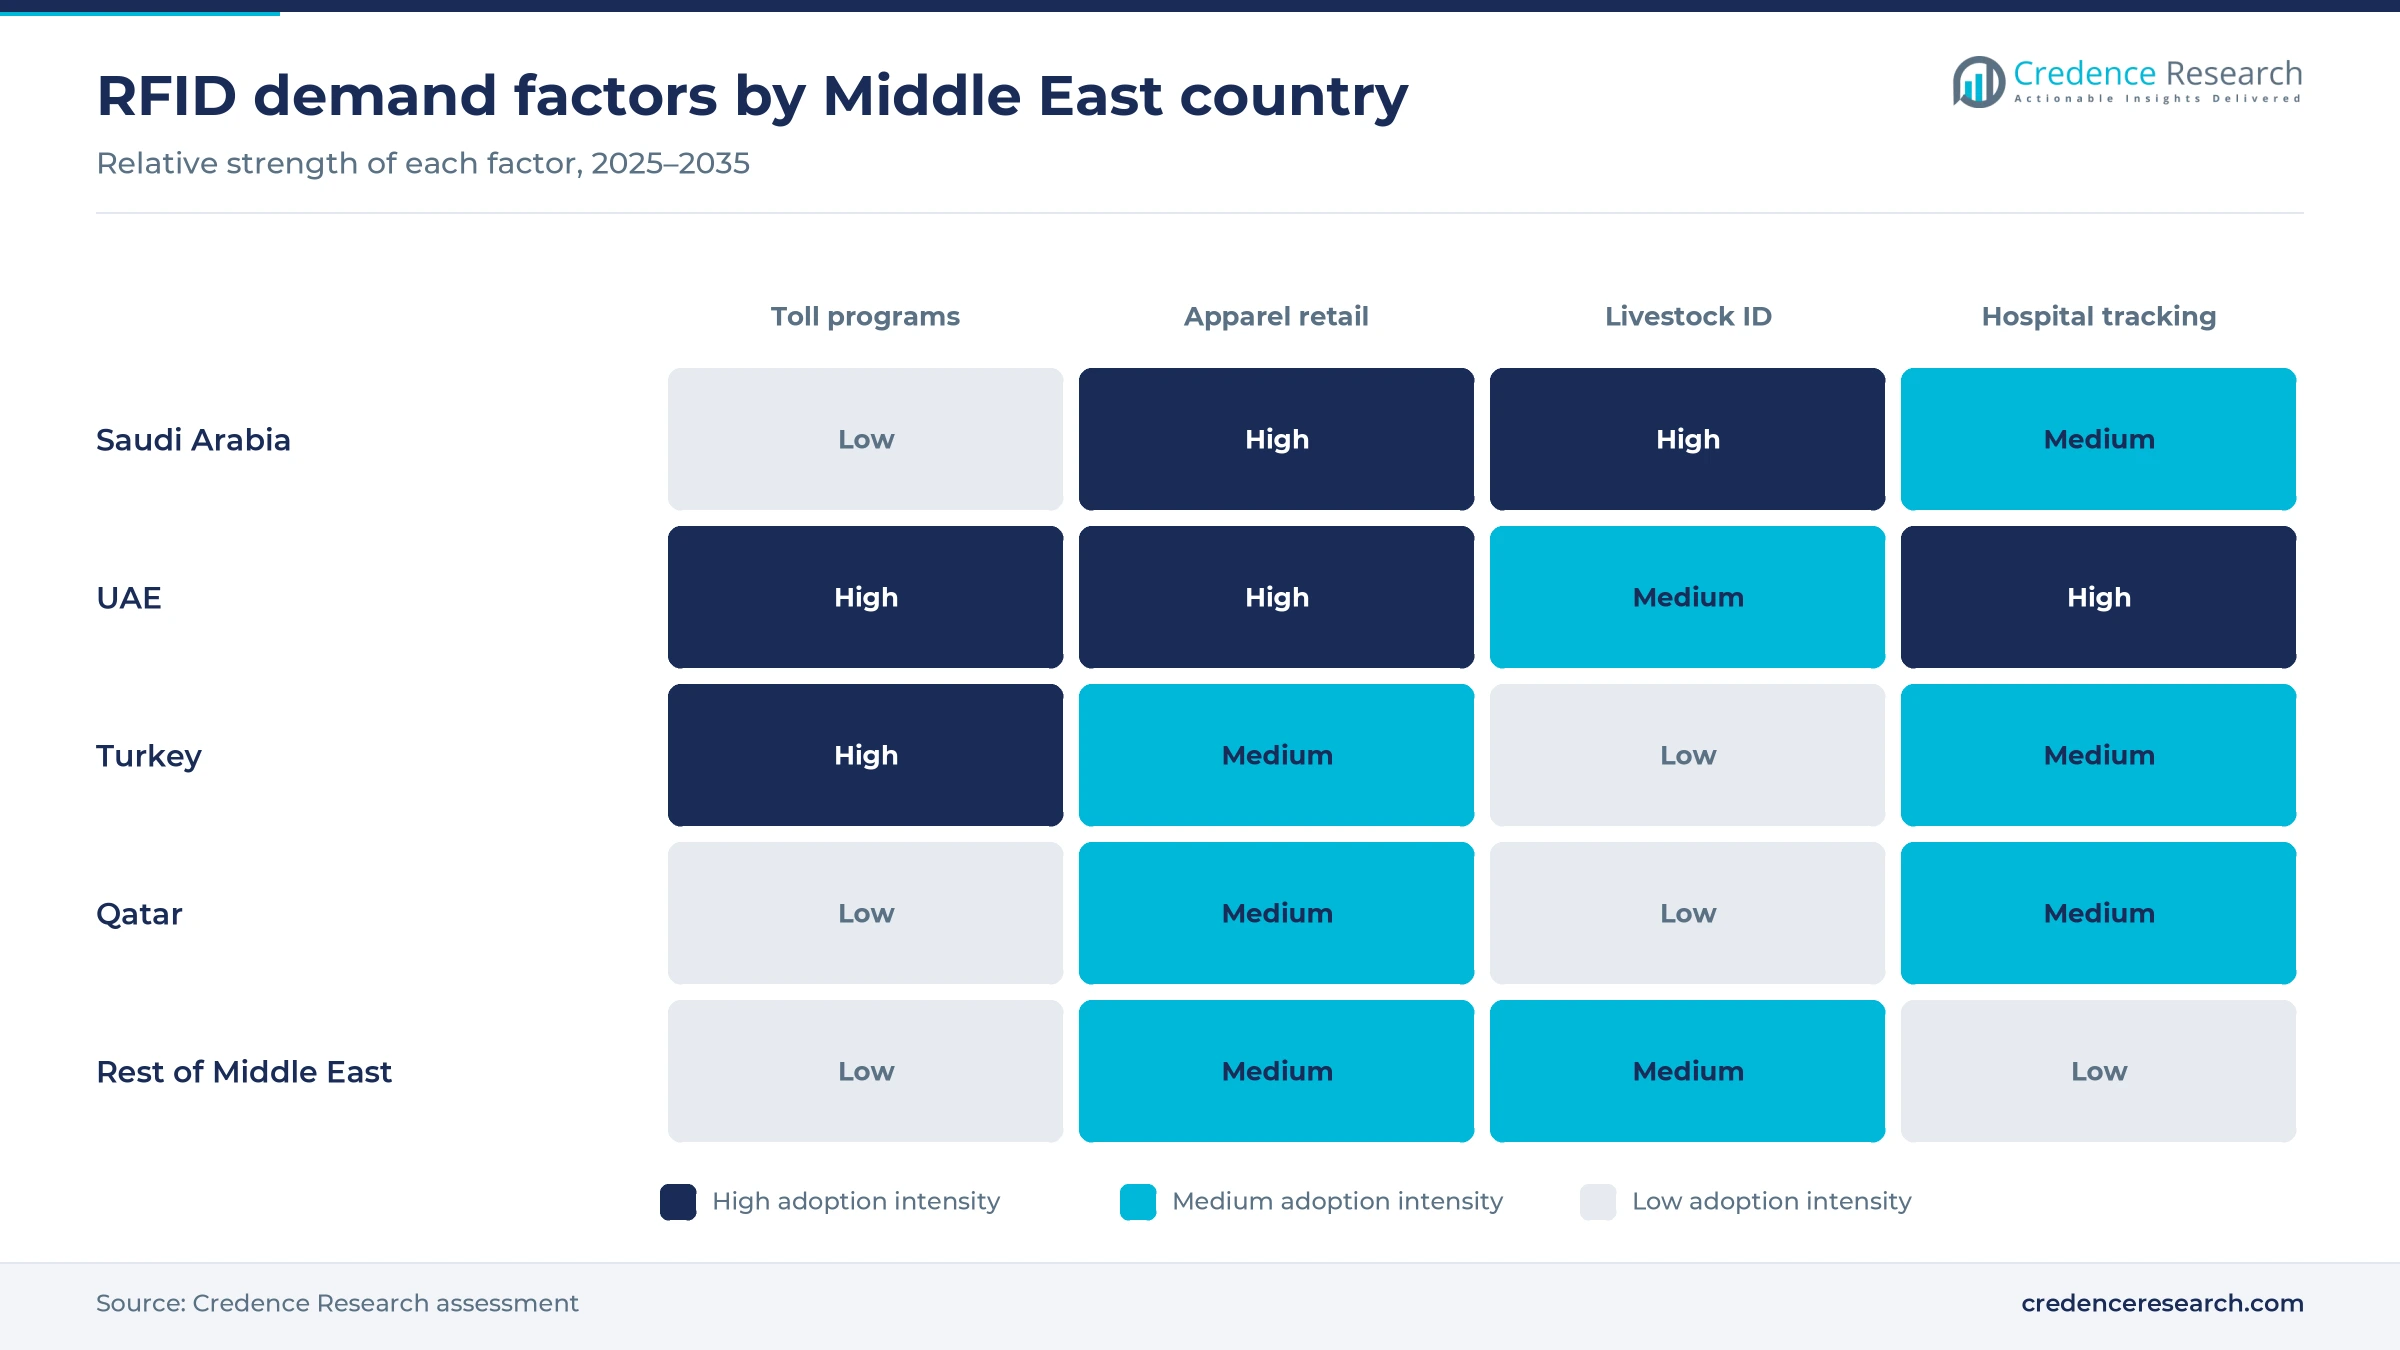
Tag-based tolling is the largest steady source of demand, because every toll-paying vehicle needs a readable windshield tag and every gate needs lane readers. Salik recorded 639.1 million chargeable trips in 2025, and total trips, including discounted ones, reached 852.7 million, according to its full-year results. Dubai opened two new gates at Business Bay and Al Safa South on Nov. 24, 2024, bringing the network to 10. In Turkey, transport minister Abdulkadir Uraloğlu said HGS tags had been used 585,906,492 times on motorways and the two Istanbul bridges as of the end of 2025. Suppliers of electronic toll collection lanes gain from each new gate.
Gulf retail groups tag merchandise across store networks
Gulf retail groups are moving item-level tagging from pilots to whole store networks, because accurate counts support online orders, transfers and faster checkout. Landmark Group selected SML in April 2024 to deploy tags, cloud software and partner hardware across more than 600 stores and 10 distribution centers in Saudi Arabia, Kuwait, the UAE, Qatar, Bahrain, Oman, Egypt and Jordan, according to SML. More than 100 H&M stores in the region, run by franchisee Alshaya Group, were deploying RFID by August 2023, according to RFID Journal. RFID Journal reported in August 2023 that SML had opened a Dubai sales office to serve this demand. Converters and integrators that win group-wide specifications gain multi-year volume, while smaller chains still rely on barcodes.
Livestock rules bring microchips and electronic tags
Livestock rules in the Gulf and Levant are turning animal identification into a recurring purchase of tags, microchips and readers. Saudi Arabia's Ministry of Environment, Water and Agriculture launched a camel passport in February 2026 that records each animal's microchip number, breed, birth details and vaccinations, and the kingdom holds more than 2.2 million camels, according to the Daily Tribune. Abu Dhabi's agriculture and food safety authority requires livestock, including newborn animals, to be tagged and registered through the TAMM platform, according to Gulf News in September 2025. Jordan launched an electronic sheep tagging platform across all governorates in November 2025 with 47 tagging centers. Suppliers of livestock identification devices and saleyard readers gain the most.
Public hospitals tag equipment across whole networks
Public health systems buy tags at network scale once they move equipment audits from paper to readers. The UAE Ministry of Health tagged its medical equipment, IT assets and mechanical gear with one million UHF tags across 147 facilities, with 10 facilities live in fall 2019 and the rest scheduled by early 2020, according to an Avery Dennison case study dated Dec. 12, 2019. The deployment used Smartrac Dogbone inlays with Impinj chips, ATID handheld readers, Feig portals and Zebra printers, integrated by OGTech. Programs of this size create service revenue for years, because every new asset must be tagged and every audit needs readers.
Toll accounts and store checkouts widen tag use
Toll tag accounts are shifting toward parking and fuel payments
Salik is shifting its tag accounts from toll gates toward parking, airport and fuel payments, which raises the value of each tag already on a windshield. Barrier-free parking payment through Salik has run at Dubai Mall since July 1, 2024, and its Parkonic partnership was live at 110 of 197 locations in early 2026. Salik signed a 10-year agreement with Dubai Airports for parking payments at Terminals 1, 2 and 3, with work starting Jan. 22, 2026. An ENOC fuel pilot at four or five stations is planned for the second half of 2026. Reader suppliers gain new sites, although Salik has not said which of these sites read the tag and which read plates.
Store tagging is shifting from stock counts to self-checkout
Apparel chains are shifting tags from back-room stock counts to the checkout, because a tag read at the till cuts queues without new labor. Landmark Arabia's Max, with 128 stores in more than 50 Saudi cities, uses RFID for self-checkout at its new U Walk Riyadh store, while its Centrepoint flagship added expanded self-checkout, according to Arab News in November 2025. Keonn lists RFID inventory, payment and self-checkout systems in H&M stores run by Alshaya. Cenomi Retail's reopened Zara at Al Nakheel Mall pairs assisted self-checkout with phone scanning. This favors suppliers of self-checkout systems that reuse tags bought for inventory.
Rugged tags for construction and plant assets are an opening
Rugged tags for construction equipment, metal tools and plant assets are an opening for specialist tag makers, because Gulf megaprojects and oil and gas sites lose time searching for equipment. Xerafy and its Qatar partner GBDG showed outdoor tags, micro tags for tools and Metal Skin labels for metal surfaces at the 22nd Project Qatar on June 9-11, 2026, according to the RAIN Alliance, which says the RAIN market grew 50% over four years. The showcase targeted construction equipment, infrastructure assets, airports, data centers and warehouses. The RAIN Alliance described oil and gas as the Gulf's traditional RFID market. No orders were announced, so the opening depends on contractors writing tagging into project specifications.
New transit and pilgrim credentials are an opening for cards
New transit and pilgrim credentials are an opening for card and reader suppliers, because each reissue brings new cards, validators and handheld checkers. Dubai's Roads and Transport Authority began piloting the Nol-Jaywan card with Al Etihad Payments in November 2026, linking transit fares with the national payment scheme, according to Khaleej Times. The Ministry of Hajj and Umrah recorded more than 3.5 million Nusuk card scans at verification checkpoints during the 1447 AH season. Riyadh Metro passed 100 million passengers in under nine months after its December 2024 launch, according to Arab News, which widens the base of fare media. None of these bodies has said which data carrier the cards use, so this opening is qualified, and card makers with local personalization lines gain most.
Plate cameras, QR codes and chip destocking cap growth
Abu Dhabi tolling and parking skip tags altogether
Abu Dhabi has built its toll and parking payments on number plate recognition, which removes tag and lane reader demand from a large program. Darb charges Dh4 at four bridge gates without any tag, according to Gulf News in August 2025, and Q Mobility unveiled automatic number plate parking payment on June 1, 2026. Tag issuers and lane reader suppliers are most exposed if other Gulf cities follow, while camera vendors gain.
QR codes and barcodes replace tags in public services
QR codes and barcodes are replacing tags in some public services, because phones and printed codes cost less than cards and readers. Dubai riders can now use a digital QR ticket instead of the single-use red Nol paper ticket on metro, tram and buses, according to The National in October 2026. Dubai Municipality's new household bins carry barcodes for collection tracking, reported in October 2026. Paper ticket and HF card suppliers are the suppliers most exposed to this shift.
Chip destocking cut tag volumes in 2025
Chip destocking cut tag volumes in 2025 and shows the demand risk that global retail cycles pose for regional converters. The RAIN Alliance reported 42.7 billion tag chip shipments for 2025 in April 2026, down from the 2024 record, as semiconductor inventories started 2025 at 26 days above the 10-year median and retailers destocked. Label importers serving Gulf apparel chains are most exposed when global brands delay tagging.
Bluetooth platforms compete for hospital tracking
Bluetooth platforms compete with RFID for hospital tracking, because they reuse beacons and screens that hospitals already own. People and Technology is validating indoor wayfinding, asset tracking and wearable monitoring at Prince Sultan Military Medical City in Riyadh, reusing Bluetooth broadcast from digital signage, according to an October 2026 release. Passive tag and portal suppliers are most exposed in Saudi hospital tenders, unless they bundle RFID with location software.
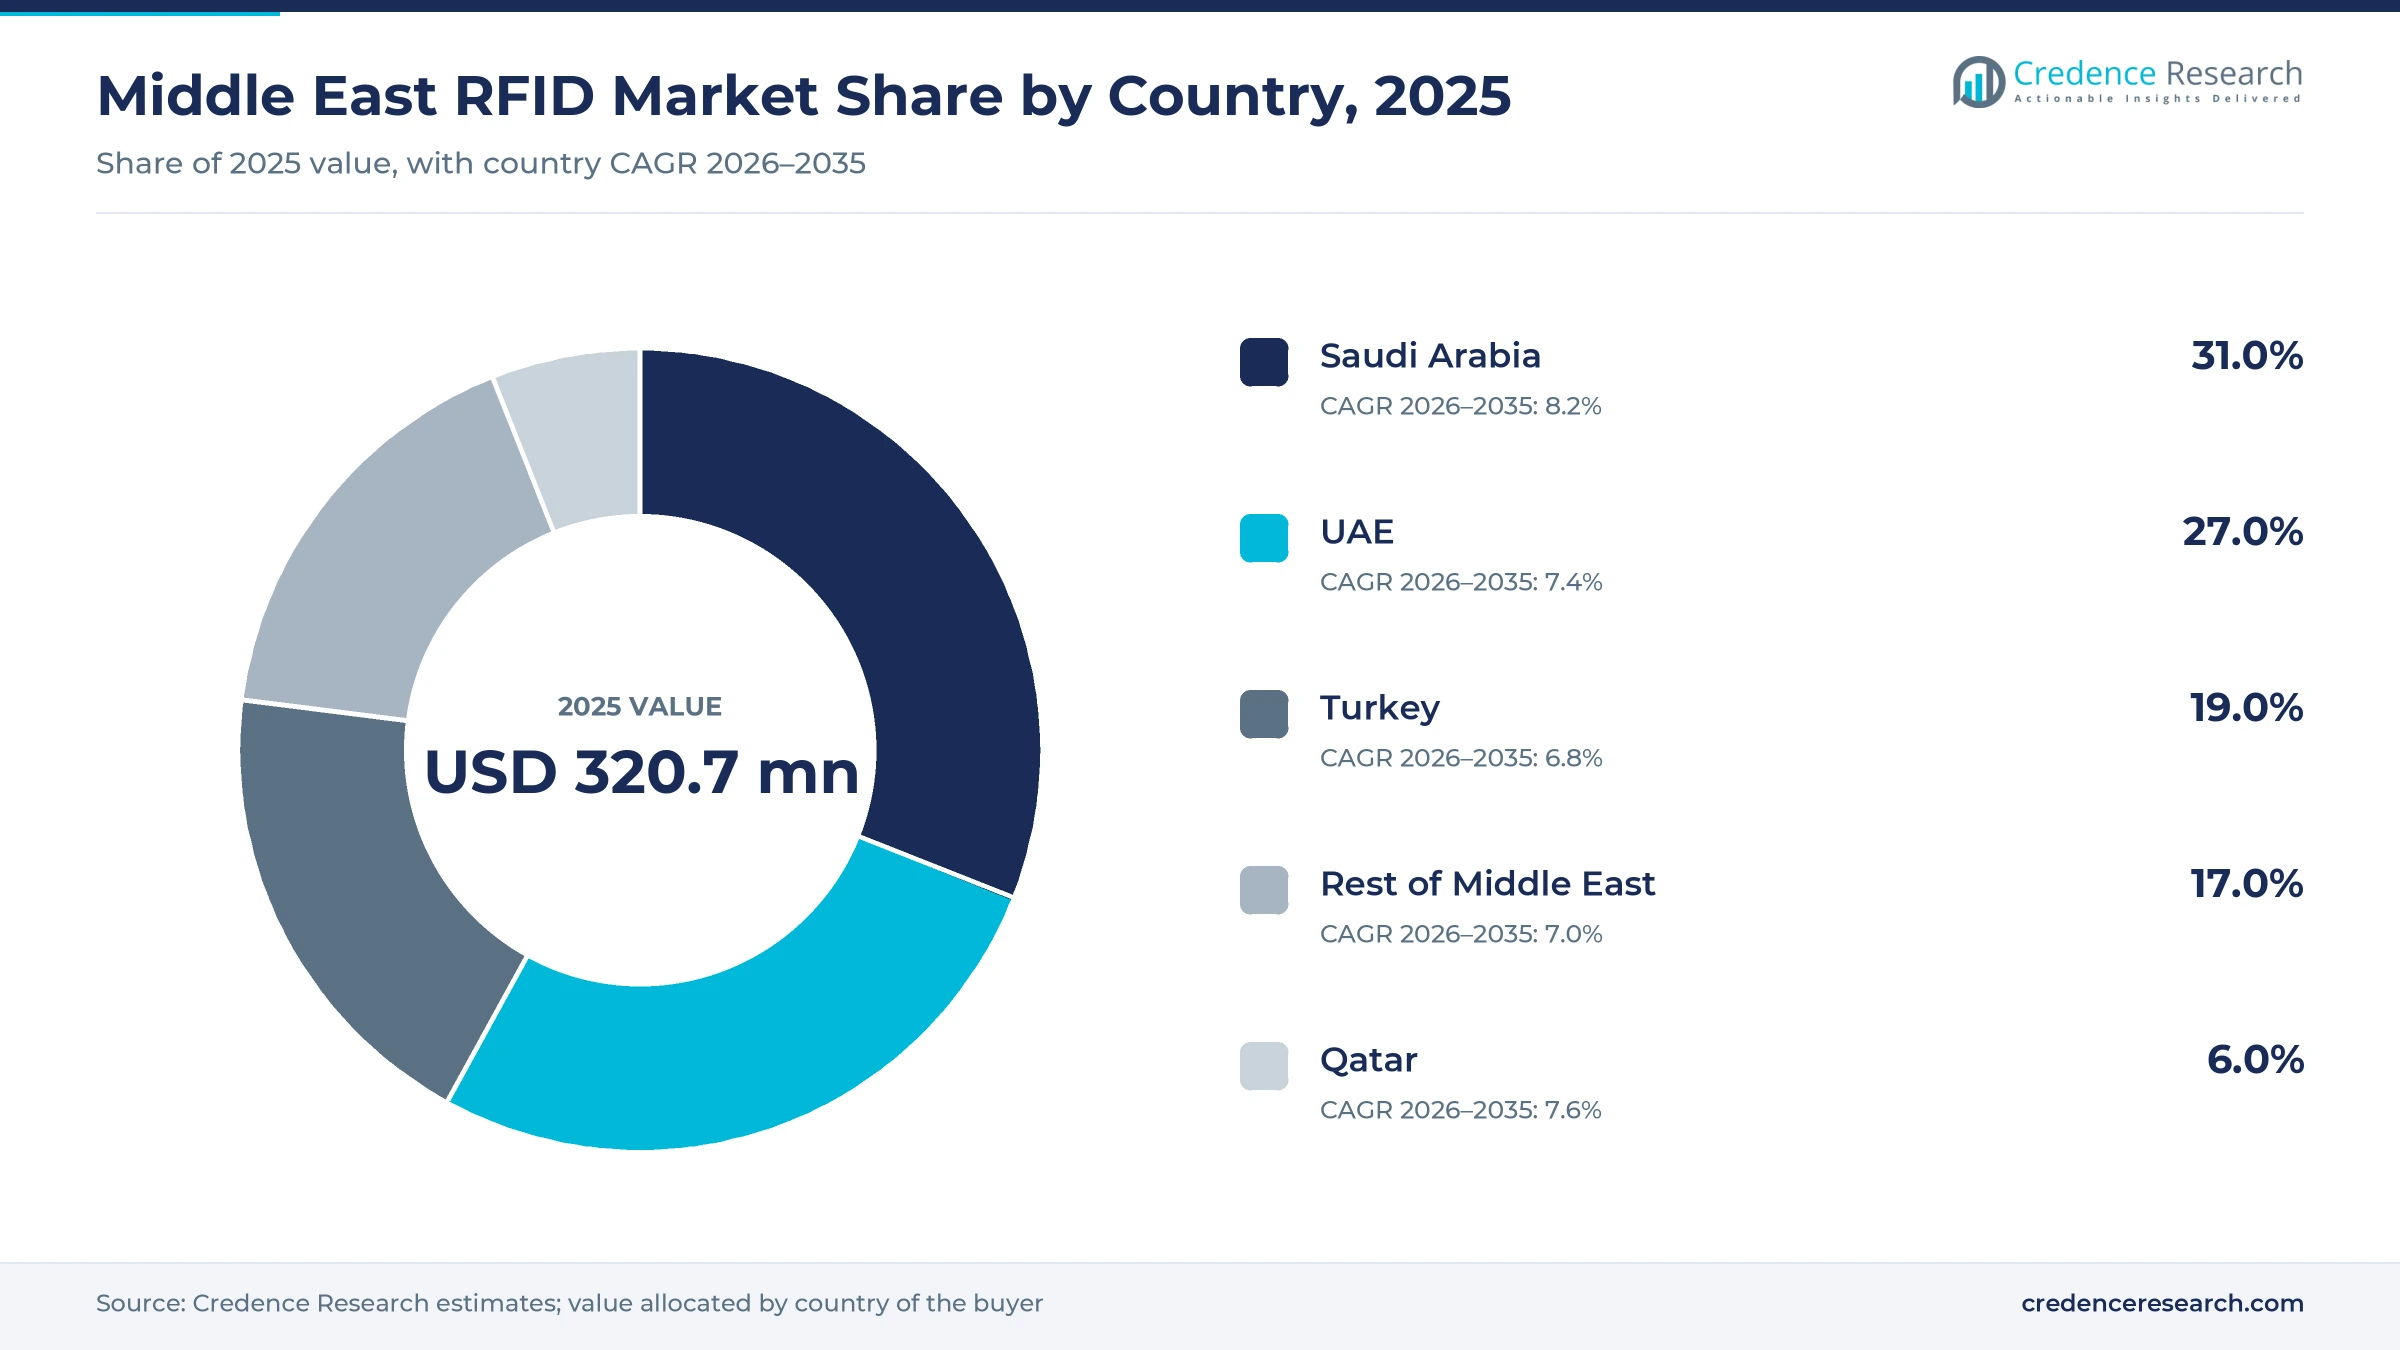
Saudi Arabia leads and also grows fastest
| Country | Value, 2025 (USD million) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Saudi Arabia | 99.4 | 31.0% | 8.2% |
| UAE | 86.6 | 27.0% | 7.4% |
| Turkey | 60.9 | 19.0% | 6.8% |
| Rest of Middle East | 54.5 | 17.0% | 7.0% |
| Qatar | 19.2 | 6.0% | 7.6% |
Saudi Arabia leads on retail rollouts and camel registration
Saudi Arabia held a 31.0% share of 2025 value and grows fastest at 8.2% a year. Centrepoint runs 92 stores across 32 Saudi cities, and the Max checkout format noted above extends tagging to the till. The camel passport adds microchip demand across a herd of more than 2.2 million. The kingdom has no Salik-style road tolling, so transport demand rests on fleets, ports and metro fare media.
The UAE combines Salik tags with large public programs
The UAE held a 27.0% share of 2025 value and grows at 7.4% a year. Dubai carries most of the transport value through the Salik network and its parking extensions described above, and federal hospitals add asset tracking. Dubai is also the regional sales base for SML and other converters that serve Gulf retailers. Growth trails Saudi Arabia, because Abu Dhabi chose plate recognition for Darb tolling and parking and Dubai is adding QR transit tickets.
Turkey rests on HGS tolling and apparel chains
Turkey held a 19.0% share of 2025 value and grows at 6.8% a year. HGS tags, sold at PTT branches and issued by banks, carry the toll volume noted above on motorways and the Istanbul Bosphorus bridges. Keonn lists an RFID self-checkout system built for LC Waikiki in Turkey. Published counts of source tagging by Turkish garment exporters are an evidence gap, so the country estimate leans on tolling and domestic retail, and lira weakness raises the local cost of imported tags.
Qatar adds construction and industrial asset demand
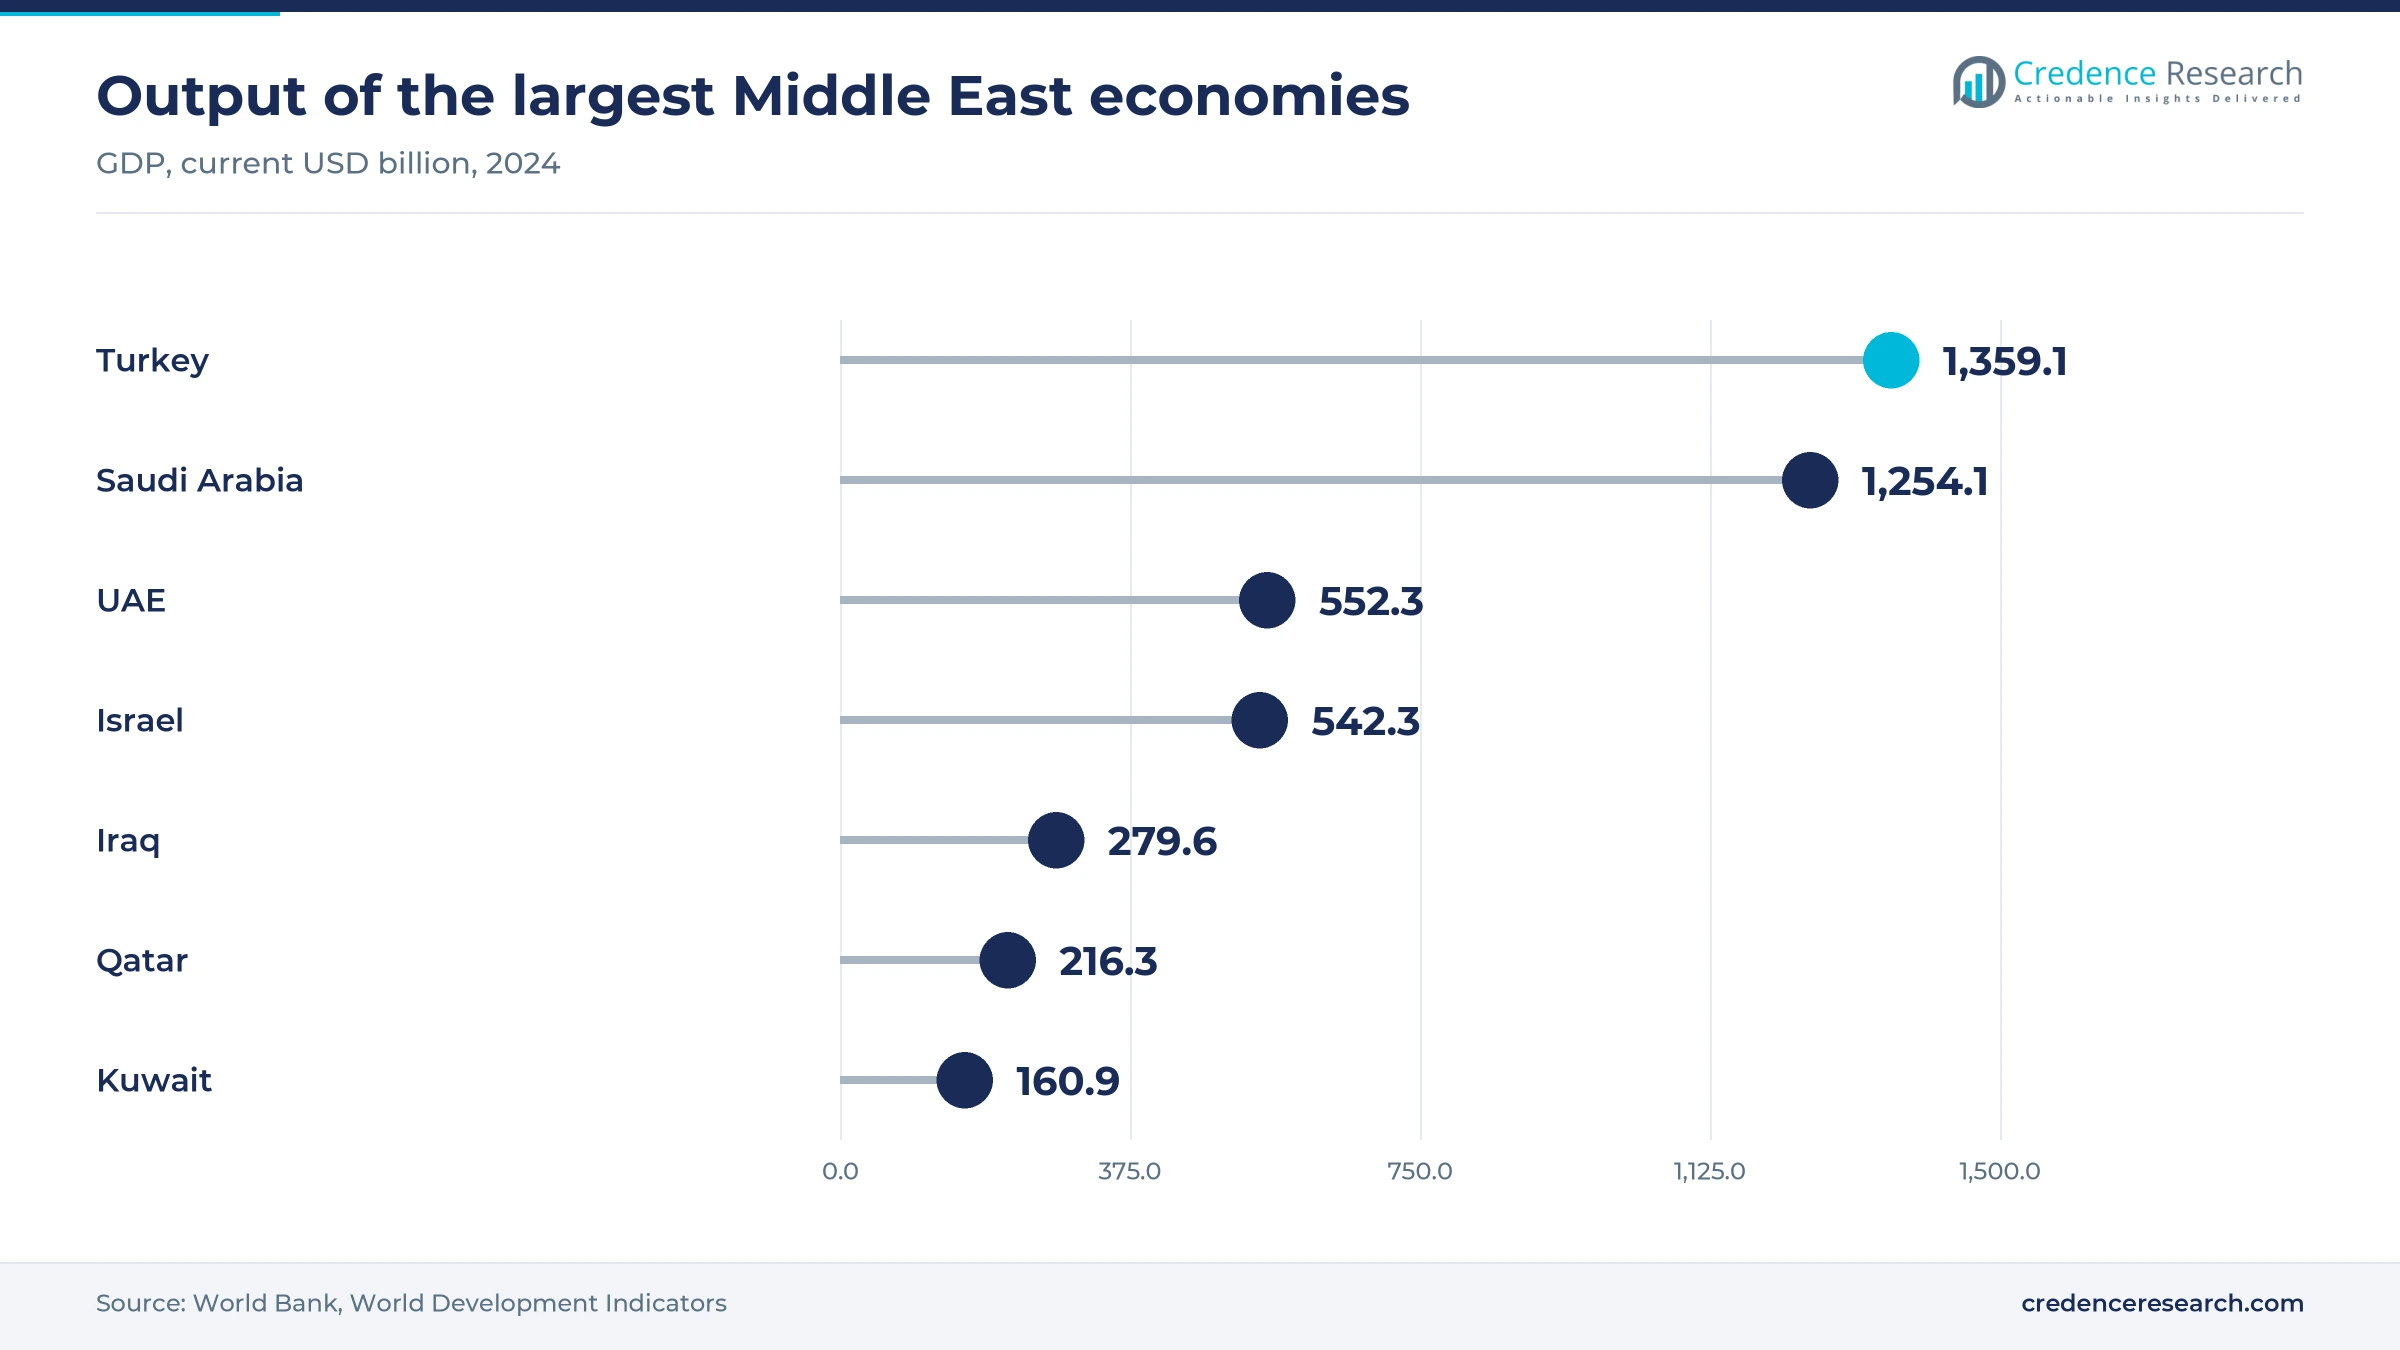
Qatar held a 6.0% share of 2025 value and grows at 7.6% a year. GBDG, a Doha distributor, now offers Xerafy industrial tags for construction, airports, data centers and warehouses, and Landmark Group stores in Qatar are part of the regional tagging rollout. Published counts of Qatari hospital and logistics deployments are an evidence gap, so this estimate rests more on World Bank GDP weights and project activity.
Kuwait, Oman, Bahrain, Jordan and Israel form the rest
The rest of the Middle East held 17.0% of 2025 value and grows at 7.0% a year. Landmark Group stores in Kuwait, Bahrain, Oman and Jordan are covered by the SML rollout, and Jordan's electronic sheep tagging platform adds animal tags. Israel hosts Tadbik, a label and RFID maker with three Israeli plants. Country splits within this group are Credence Research estimates from GDP and program data, because no official RFID spending statistics exist by country.
Rollouts, programs and deals that moved buyers, 2024–2026
| Development | Status and market relevance |
|---|---|
| In April 2024, Landmark Group selected SML to deploy item-level RFID across its Middle East stores and distribution centers. | Supplier selection with sites already live; rollout covers more than 600 stores and 10 distribution centers in eight countries. |
| In November 2024, Dubai opened Salik toll gates at Business Bay and Al Safa South. | Operational launch; the network reached 10 gates and the new sites added a full year of tag reads in 2025. |
| In November 2025, Landmark Arabia opened a Max store at U Walk Riyadh with RFID self-checkout. | Operational launch; Max runs 128 stores in more than 50 Saudi cities, so the format can scale. |
| In February 2026, Saudi Arabia's Ministry of Environment, Water and Agriculture launched the camel passport. | Program launch; each passport records the animal's microchip number, linking registration to implanted tags. |
| In August 2026, Brady Corporation completed its purchase of Honeywell's productivity solutions and services business. | Completed acquisition; the former Honeywell scanners, printers and mobile computers now sit with Brady. |
Tag format and band decide where each read works
- Passive UHF labels imported from Asian converters carry a chip and antenna on a thin inlay, which lets apparel chains tag every item for a few cents.
- Windshield toll tags issued by Salik and HGS banks are read by overhead gate antennas, which lets traffic pass at speed without booths.
- Implanted microchips and ear tags use low frequency, which reads reliably through animal tissue and links each camel or sheep to a registry.
- Handheld and fixed readers from Zebra, Brady and Keonn read many tags in one pass, which makes store counts, checkout and hospital audits fast.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Global chip makers supply local converters and integrators
Competition splits between chip suppliers, label converters, reader and printer brands, and local integrators. Impinj and NXP supply most UHF and HF chips, and Avery Dennison, SML and Tadbik convert them into labels and inlays for regional buyers. SML competes on group-wide retail programs, as its Landmark contract shows, while Keonn supplies store inventory and checkout systems for H&M stores run by Alshaya and for LC Waikiki in Turkey. Zebra Technologies and Brady Corporation, which completed its purchase of Honeywell's productivity business in August 2026 according to a Honeywell release, supply readers, mobile computers and printers. HID Global competes on access credentials, and Xerafy on rugged industrial tags through GBDG in Qatar. Approved hardware, local integrators and references in large programs decide most contracts.
Foreign chip makers supply local converters, issuers and integrators
Supply is organized as a narrow foreign top and a wide local base. The four chip makers whose shipments the RAIN Alliance counts, Impinj, NXP, EM Microelectronic and Shanghai Quanray, sell through converters such as Avery Dennison, SML and Tadbik, and through reader brands such as Zebra, Brady and Keonn. Local integrators, including OGTech in the UAE and GBDG in Qatar, install and support systems. Tolling adds tag issuers, Salik in Dubai and PTT and banks for HGS in Turkey, which own the driver accounts. No Gulf inlay plant has been announced, so margins sit with integrators and issuers.
Key RFID suppliers active in the Middle East
| Company | Type | Role in the market |
|---|---|---|
| Avery Dennison Corporation | Inlay and label converter | UHF inlays and tags for apparel, logistics and hospital assets |
| Zebra Technologies Corporation | Reader and printer brand | Fixed and handheld readers and printers used in Gulf retail and hospitals |
| Impinj, Inc. | Chip supplier | UHF tag chips and readers used in regional tags and portals |
| NXP Semiconductors | Chip supplier | UHF and HF chips for tags, transit cards and credentials |
| SML Group | Retail label and software supplier | Item-level tags and cloud software for Landmark Group stores, Dubai office |
| HID Global (ASSA ABLOY) | Credential and tag supplier | HF and UHF access credentials, readers and industrial tags |
| Brady Corporation (former Honeywell PSS) | Reader and mobile computer brand | RFID readers, scanners and printers from the former Honeywell business |
| Keonn Technologies | Store systems supplier | RFID inventory, payment and self-checkout systems for H&M and LC Waikiki |
| Xerafy | Specialty tag maker | Rugged outdoor, micro and on-metal tags sold in Qatar through GBDG |
| Tadbik Advanced Technologies | Label and tag converter | Labels and RFID tags made at three plants in Israel |
Store software and program contracts will carry margin
Credence Research's view is that value in this market will shift from tags toward store software and program contracts through 2035. Tags stay the largest item, but chip price cuts and destocking keep their prices low, and some public programs have chosen cameras and QR codes instead. Retail rollouts, livestock registration and hospital asset programs carry more value per tag, because each needs readers, databases and support. The suppliers best placed are those with local integrators in Riyadh, Dubai and Istanbul and software that ties reads to stock, payment or health records.
Old estimate carried to 2025 and checked by end use
The report uses 2025 as the base year and forecasts to 2035. Market values in this report come from the Credence Research model. This edition of the Middle East RFID report replaces the previous 2024 estimate with a 2025 value carried forward at the earlier growth rate and checked against spending by end use, published tag and reader prices, toll program results, retail rollouts and livestock rules. Segment and country shares are Credence Research estimates based on government statistics, regulator and ministry notices, company results and announcements, and trade press. No interviews or surveys were carried out for this edition.
Retail rollouts and livestock rules set the pace to 2035
In the base case the Middle East RFID market grows at 7.50% a year through 2035, as retail rollouts, livestock registration and hospital programs add value faster than toll tags and basic cards. Tags keep the largest share, while software and services grow fastest as buyers pay for integration and data. Ultra-high frequency extends its lead in stores, warehouses and vehicles. Saudi Arabia keeps the largest country share and gains further on retail and livestock work. Plate cameras, QR tickets and tag price erosion are the main risks to that path.
Retail rollouts, plate cameras and tag prices decide the range
The outcome depends on how fast Gulf retail groups take item tagging to every store, whether other cities copy Abu Dhabi's plate-based tolling and parking, and how quickly tag prices fall. A long chip price war and more QR and camera programs would hold growth near the downside case. Store-wide self-checkout, livestock registration beyond camels and rugged tags written into megaproject specifications would push the market toward the upside case.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 5.5% | USD 558.2 million | More cities adopt plate cameras and QR tickets while retail tagging stalls after pilots |
| Base | 7.50% | USD 661.0 million | Tolling, retail and livestock programs continue at the pace seen in 2025 and 2026 |
| Upside | 9.0% | USD 748.8 million | Self-checkout spreads across Gulf chains and Saudi livestock rules extend to sheep and goats |
Frequently Asked Questions
How big is the Middle East RFID market?
Which RFID solution providers are active in the Middle East?
How is UHF RFID used in the Middle East?
Which RFID providers serve Saudi Arabia?
How is RFID used for inventory tracking in Saudi Arabia and the UAE?
Does Dubai tolling depend on RFID tags?
What are the main challenges for RFID suppliers in the region?
Which country leads the market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Tags
- 1.2.2 Readers
- 1.2.3 Software and Services
- 1.3 By Frequency
- 1.3.1 Low Frequency
- 1.3.2 High Frequency
- 1.3.3 Ultra-High Frequency
- 1.4 By End User
- 1.4.1 Transportation
- 1.4.2 Retail
- 1.4.3 Security and Access Control
- 1.4.4 Commercial
- 1.4.5 Healthcare
- 1.4.6 Animal Tracking
- 1.4.7 Agriculture
- 1.4.8 Others
- 1.5 By Country
- 1.5.1 Saudi Arabia
- 1.5.2 UAE
- 1.5.3 Turkey
- 1.5.4 Qatar
- 1.5.5 Rest of Middle East
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 320.7 million → 2035: USD 661.0 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Middle East RFID Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Middle East RFID Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Middle East RFID Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Middle East RFID Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Middle East RFID Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Middle East RFID Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Middle East RFID Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Middle East RFID Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 320.7 million → 2035: USD 661.0 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Middle East RFID Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Tags
- 12.3.7.2 Readers
- 12.3.7.3 Software and Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Frequency - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Low Frequency
- 12.4.7.2 High Frequency
- 12.4.7.3 Ultra-High Frequency
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End User - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Transportation
- 12.5.7.2 Retail
- 12.5.7.3 Security and Access Control
- 12.5.7.4 Commercial
- 12.5.7.5 Healthcare
- 12.5.7.6 Animal Tracking
- 12.5.7.7 Agriculture
- 12.5.7.8 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Country - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Saudi Arabia
- 12.6.7.2 UAE
- 12.6.7.3 Turkey
- 12.6.7.4 Qatar
- 12.6.7.5 Rest of Middle East
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Middle East RFID End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Middle East RFID Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Country-Level Shares, 2025
- 14.2 Country Market Size Comparison, 2025
- 14.3 Country Market Forecasts, 2025-2035
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Middle East RFID Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Middle East RFID Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Avery Dennison Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Zebra Technologies Corporation
- 18.4 Impinj, Inc.
- 18.5 NXP Semiconductors
- 18.6 SML Group
- 18.7 HID Global (ASSA ABLOY)
- 18.8 Brady Corporation (former Honeywell PSS)
- 18.9 Keonn Technologies
- 18.10 Xerafy
- 18.11 Tadbik Advanced Technologies
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

