
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Qatar Data Center Cooling Market Size 2023 | USD 81.04 Million |
| Qatar Data Center Cooling Market, CAGR | 15.06% |
| Qatar Data Center Cooling Market Size 2032 | USD 248.97 Million |
Market Overview
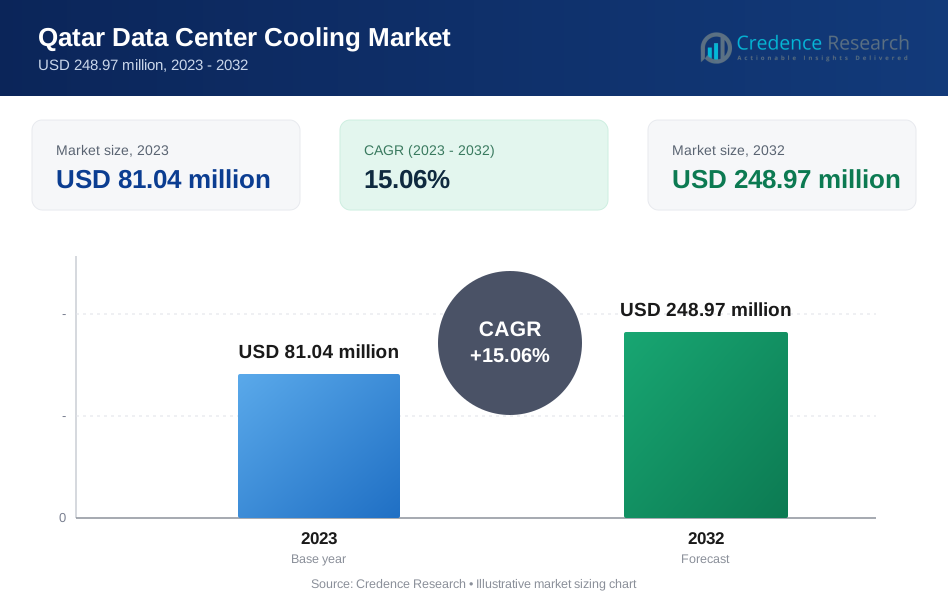
The Qatar Data Center Cooling Market is expected to grow from USD 81.04 million in 2023 to USD 248.97 million by 2032, at a CAGR of 15.06%.
The Qatar data center cooling market is driven by the rapid expansion of data centers and the increasing demand for cloud-based services, fueling the need for efficient cooling solutions. The country's growing reliance on digital infrastructure, alongside high temperatures and the need for energy-efficient cooling systems, further supports market growth. The rise in big data, IoT, and AI applications contributes to the higher heat generation in data centers, driving demand for advanced cooling technologies such as liquid cooling and evaporative cooling. Additionally, the government's emphasis on energy conservation and sustainability initiatives is fostering the adoption of green cooling solutions. Trends indicate a shift towards innovative, environmentally friendly cooling methods that reduce energy consumption while maintaining optimal performance. The growing preference for modular cooling solutions also provides flexibility for data centers, driving efficiency and scalability in response to increasing workloads.
Qatar's data center cooling market is primarily driven by the country’s focus on digital transformation and the rapid growth of data center infrastructure. Key players in the market, such as Schneider Electric, Stulz GmbH, and Vertiv Group, are actively contributing to the development of energy-efficient and sustainable cooling solutions. These companies offer a range of advanced technologies, including liquid cooling, AI-driven optimization, and air-cooled systems, tailored to meet the unique challenges posed by Qatar’s extreme climate. Other prominent players, such as Mitsubishi Electric Corporation, Daikin Industries Limited, and Johnson Controls, also play significant roles in providing reliable cooling solutions for high-density data centers. The growing demand for data centers in regions like Doha, Al Rayyan, and Al Wakrah is driving the need for advanced cooling technologies. With government initiatives promoting smart city projects and the expansion of 5G networks, these players are poised for continued growth in the Qatari market.
Market Insights
- The Qatar data center cooling market was valued at USD 81.04 million in 2023 and is expected to reach USD 248.97 million by 2032, growing at a CAGR of 15.06%.
- The increasing demand for data centers, driven by digital transformation, cloud computing, and big data analytics, is propelling the market growth.
- Government initiatives, including smart city projects and investment incentives, are boosting the demand for efficient cooling solutions.
- Rising adoption of energy-efficient and sustainable cooling technologies, such as AI-driven optimization and liquid cooling, is a key market trend.
- The market faces challenges such as high ambient temperatures, water scarcity, and high energy costs, which necessitate innovative and efficient cooling systems.
- Doha dominates the market, followed by emerging regions like Al Rayyan and Al Wakrah, which are seeing increased demand for data center infrastructure.
- Key players in the market include Schneider Electric, Stulz GmbH, Mitsubishi Electric, and Daikin Industries, providing advanced cooling solutions tailored to Qatar's unique climate.
Market Drivers
Focus on Sustainability and Energy Efficiency
As Qatar moves towards greater reliance on renewable energy sources like solar power, integrating these technologies into data center operations aligns with sustainability goals. For instance, the Al Kharsaah solar power plant is expected to produce around 800 MW of power once fully operational. There is a growing demand for energy-efficient cooling technologies, such as liquid cooling and AI-driven optimization, to reduce operational costs and minimize environmental impact. Additionally, the trend towards higher server density in data centers requires advanced cooling systems to effectively manage the thermal challenges, driving innovation in cooling technologies to meet these needs.
Growing Demand for Data Centers
The increasing adoption of cloud computing and big data analytics is driving the demand for advanced data center infrastructure in Qatar. For instance, the rollout of 5G networks is expected to generate substantial data traffic, further necessitating the development of robust and scalable cooling solutions to manage the resulting heat in these centers. As businesses and government entities undergo digital transformation initiatives, there is a growing need for data centers that can efficiently handle vast amounts of data and support critical services. Additionally, the rollout of 5G networks is expected to generate substantial data traffic, further necessitating the development of robust and scalable cooling solutions to manage the resulting heat in these centers.
Government Initiatives
Qatar’s government is actively promoting smart city projects, which will significantly boost the demand for data centers and associated cooling infrastructure. With these projects, the country aims to enhance urban living through advanced technology, including IoT and cloud-based solutions, creating more demand for data processing and storage. Furthermore, the government’s favorable investment policies and incentives are attracting global technology companies to establish data centers in the country, fueling market growth in the cooling sector as well.
Strategic Geographic Location
Qatar’s strategic position at the crossroads of Europe, Asia, and Africa makes it an attractive hub for data centers catering to the Middle East and North Africa (MENA) region. The country’s strong fiber-optic network and low-latency connectivity further enhance its appeal, providing an efficient, high-speed data transmission environment. This geographical advantage enables data centers in Qatar to serve as a key regional hub, making advanced cooling systems critical to maintaining data integrity and performance.
Market Trends
Increasing Demand for Data Centers and Government Support
Qatar’s rapid digital transformation, driven by the government's initiatives, is significantly increasing the demand for robust data center infrastructure. For instance, the Ministry of Communications and Information Technology (MCIT) has launched the first global cloud data center region in partnership with Microsoft, enhancing the country's digital infrastructure. With cloud computing and big data analytics becoming integral to businesses and government operations, there is an escalating need for advanced data centers to handle and process vast amounts of data. Additionally, the deployment of 5G networks in Qatar is expected to generate substantial data traffic, necessitating cutting-edge cooling solutions to manage the heat and ensure efficient operation of data centers. Moreover, the government's active investment in smart city projects further fuels the demand for data centers to support the growing need for connectivity, IoT, and other digital services. The government's supportive policies, including attractive investment incentives, are also encouraging global technology players to establish their data centers in Qatar, further driving market growth.
Focus on Sustainability, Advanced Cooling Technologies, and Edge Computing
Qatar’s increasing reliance on renewable energy sources, such as solar power, is aligning with the country’s push for sustainable data center practices. This transition has led to a rising demand for energy-efficient cooling solutions that minimize environmental impact while maintaining performance. Technologies such as liquid immersion cooling and AI-driven optimization are gaining traction due to their ability to significantly reduce energy consumption and improve cooling efficiency in high-density data centers. These advanced cooling systems are vital to maintaining optimal conditions for data processing and storage. Furthermore, the growing adoption of IoT devices and real-time applications is driving the need for edge computing, which requires localized data centers that offer low-latency connectivity. Edge data centers present unique thermal challenges, leading to a demand for specialized cooling solutions that cater to their specific needs. Additionally, the trend toward modular data centers provides greater scalability and flexibility, allowing for rapid expansion and efficient cooling design tailored to each module’s requirements, enhancing overall operational efficiency.
Market Challenges Analysis
Environmental and Resource Challenges
Qatar’s extreme climate, characterized by high temperatures and humidity, poses significant hurdles for traditional air-cooling systems in data centers. For instance, summer temperatures in Qatar can exceed 45°C (113°F), necessitating the adoption of advanced cooling technologies to maintain optimal operating conditions and prevent equipment overheating. Additionally, the country’s water scarcity further complicates the use of water-based cooling solutions like traditional chillers. This drives the need for water-efficient cooling systems, such as air-cooled chillers or dry cooling technologies, which can reduce reliance on water while still ensuring effective cooling. Qatar's commitment to environmental sustainability also requires data centers to comply with stringent regulations related to energy consumption and emissions. As a result, there is a growing emphasis on eco-friendly cooling technologies that utilize natural refrigerants and integrate renewable energy sources, ensuring that data centers meet both regulatory standards and sustainability goals.
Operational and Security Challenges
High energy costs in Qatar present another significant challenge for data centers, impacting their overall operational expenses. To mitigate these costs, there is a strong push toward adopting energy-efficient cooling solutions, such as free cooling systems and optimized airflow management. These systems help reduce reliance on conventional energy sources and lower the cooling costs of data centers. Infrastructure constraints, such as limited availability of reliable power supply and a skilled workforce, can hinder the development of large-scale data centers in the region. To address these challenges, a robust power supply and efficient cooling systems are essential for ensuring uninterrupted operations. Additionally, data centers in Qatar, like those around the world, face threats from cyberattacks and physical security breaches. In response, data centers must implement advanced security measures, including resilient cooling systems with redundant components, to safeguard their critical infrastructure against potential risks and disruptions.
Market Opportunities
The Qatar data center cooling market presents significant opportunities driven by the increasing demand for advanced cooling technologies in response to the country’s harsh climate. As Qatar’s digital transformation accelerates, with the government’s push for smart cities, cloud computing, and big data analytics, the demand for data centers is expected to rise. This, in turn, creates opportunities for innovative cooling solutions to address the challenges posed by high ambient temperatures and humidity. The adoption of energy-efficient and sustainable cooling technologies, such as liquid immersion cooling, AI-driven optimization, and dry cooling systems, is poised to grow, as they offer solutions to reduce energy consumption and maintain optimal operating conditions. The increasing reliance on renewable energy sources, such as solar power, further aligns with the adoption of eco-friendly cooling solutions, providing opportunities for businesses to capitalize on the shift toward sustainable practices in the data center sector.
Moreover, Qatar’s strategic location as a regional data hub for the Middle East and North Africa (MENA) region offers significant market potential. With its advanced infrastructure and growing connectivity needs due to 5G deployment and IoT applications, the demand for edge data centers is expected to rise. These localized data centers require specialized cooling solutions to ensure low-latency operations, creating a niche market for customized cooling technologies. Additionally, the growing trend of modular data centers offers scalability and flexibility, which presents opportunities for companies to provide modular cooling systems that optimize energy efficiency while meeting the specific needs of rapidly expanding data centers. These opportunities position the Qatar data center cooling market for substantial growth in the coming years.
Market Segmentation Analysis:
By Component:
The Qatar data center cooling market is segmented into solutions and services, each offering unique growth opportunities. Solutions are the primary driver of the market, encompassing advanced cooling technologies such as liquid cooling, evaporative cooling, and AI-driven optimization systems. These solutions are critical for managing high-density data centers, ensuring energy efficiency, and meeting environmental regulations. As data center demands grow, the need for innovative and sustainable cooling solutions continues to rise. On the other hand, services within the data center cooling market include installation, maintenance, and consulting services that support the deployment and optimization of cooling systems. These services are essential for ensuring that cooling systems are installed correctly, operate efficiently, and adhere to regulatory standards. As Qatar's data center market expands, the demand for both solutions and services is expected to grow in tandem, driven by technological advancements and the increasing complexity of cooling requirements.
By Application:
The Qatar data center cooling market is also segmented by application, including telecom and IT, retail and BFSI, healthcare, energy, and others. Telecom and IT, as well as retail and BFSI, are the leading sectors, with the rapid adoption of digital services and cloud-based infrastructure driving the need for robust cooling solutions. Data centers in these sectors require efficient, high-performance cooling to manage substantial data traffic and ensure uninterrupted services. Healthcare and energy sectors also present significant opportunities, with increasing data storage needs related to medical records, patient data management, and energy monitoring. These sectors demand reliable and energy-efficient cooling systems to maintain optimal performance in their critical data centers. The “others” segment includes industries like manufacturing and logistics, where data-driven processes require specialized cooling systems to handle varying workloads. Each application segment offers distinct requirements for cooling technologies, further diversifying the opportunities within the Qatar data center cooling market.
Segments:
Based on Component:
- Solution
- Services
Based on Application:
- Telecom & IT
- Retail & BFSI
- Healthcare
- Energy
- Others
Based on Solution:
- Air Conditioners
- Precision Air Conditioners
- Chillers
- Air Handling Units
- Others
Based on Containment:
- Raised Floor with Containment
- Hot Aisle Containment (HAC)
- Cold Aisle Containment (CAC)
- Raised Floor without Containment
Based on Services:
- Installation & Deployment
- Support & Consulting
- Maintenance Services
Based on Cooling Type:
- Raised Floor
- Non-Raised Floors
Based on Structure:
- Rack-based Cooling
- Row-based Cooling
- Room-based Cooling
Based on the Geography:
- Doha
- Al Rayyan
- Al Wakrah
Regional Analysis
Doha
Doha, the capital city of Qatar, commands the largest share of the data center cooling market in the country, with an estimated market share of 50%. As the economic and technological hub of the nation, Doha is home to a significant concentration of data centers serving key sectors such as government, telecom, IT, and finance. The city’s focus on digital transformation, including cloud computing, big data analytics, and smart city development, has created a strong demand for robust data center infrastructure. The increasing deployment of 5G networks, IoT applications, and the rise of digital services further accelerates the need for advanced and energy-efficient cooling solutions. Doha’s infrastructure investments and the presence of multinational corporations continue to drive the expansion of the data center cooling market, making it the dominant region in Qatar’s growing data center landscape.
Al Rayyan
Al Rayyan and Al Wakrah, while smaller in comparison to Doha, are emerging as key regions for data center cooling in Qatar. Al Rayyan holds an approximate 30% share of the market, driven by its strategic proximity to Doha and its increasing importance as a commercial and residential area. The region is witnessing growth in data center development, fueled by investments from global technology companies and regional infrastructure projects. As the demand for digital services and data storage increases, Al Rayyan is set to see continued growth in its data center cooling requirements.
Key Player Analysis
- Schneider Electric
- Stulz GmbH
- Astek Group
- Vertiv Group Corp.
- Mitsubishi Electric Corporation
- Daikin Industries Limited
- Johnson Controls International PLC
- Emerson Electric Co.
Competitive Analysis
The Qatar data center cooling market is highly competitive, with several global players offering advanced solutions to meet the growing demand for energy-efficient and reliable cooling systems. Leading companies such as Schneider Electric, Stulz GmbH, Mitsubishi Electric, Daikin Industries, Johnson Controls, Emerson Electric, and Vertiv Group are actively involved in providing cutting-edge technologies. Companies operating in the market are focusing on developing advanced cooling solutions that can address the challenges posed by Qatar's extreme temperatures and high-density data centers. To stay competitive, players are increasingly adopting AI-driven optimization technologies and liquid cooling solutions that offer superior energy efficiency and lower operational costs. Modular cooling systems are also gaining traction, providing scalability and flexibility for data center operators. In addition to technological advancements, companies are placing a strong emphasis on meeting stringent environmental regulations and sustainability goals. The demand for eco-friendly cooling solutions is rising, prompting providers to integrate renewable energy sources, such as solar power, into their systems. The market is also witnessing collaborations and partnerships between technology providers and local infrastructure developers to meet the growing demand for data center cooling. As the data center market in Qatar continues to expand, the competition is intensifying, with players focusing on differentiation through superior product offerings, cost-effectiveness, and reliability. The ability to provide customized, energy-efficient solutions will be a key factor in gaining a competitive edge in this dynamic market.
Recent Developments
- In May 2024, STULZ Modular, a provider of modular data center solutions and a subsidiary of STULZ GmbH, collaborated with Asperitas to explore the potential of liquid cooling technology. This partnership aimed to leverage immersion cooling for high-density data center environments, offering innovative solutions to meet the evolving demands of the industry. The collaboration focused on a modular data center concept integrating immersion cooling for both indoor and outdoor installations.
- In April 2024, Schneider Electric reinforced its commitment to India by investing USD 438.4 million to establish the country as a manufacturing hub. The inauguration of a state-of-the-art facility in Bengaluru, with an initial investment of USD 130.0 million, underscores the company's dedication to meeting the escalating demand for data center cooling solutions. This manufacturing hub would focus on developing innovative cooling solutions customized for India's burgeoning data center ecosystem.
- In April 2024, Mitsubishi Electric launched the MECH-iF range, featuring an air-cooled chiller equipped with a proprietary single-screw compressor, enhancing energy efficiency and reliability for a prolonged operational lifespan. With capacities ranging from 345kW to 921kW, this range offers flexibility with either R1234ze (G04) or R513A (G05) refrigerant and patented screw variable-speed compressors.
- In March 2024, Daikin Applied unveiled the Navigator WW water-cooled screw chiller with low-global warming potential (GWP) R-513A refrigerant, providing customers with an eco-friendly cooling solution. Clients can enhance efficiency further by combining the chiller with the optional Templifier TW water heater for a cost-effective heat recovery solution.
- In December 2023, Vertiv, a worldwide supplier of essential digital infrastructure and continuity solutions, revealed its acquisition of CoolTera Ltd., a specialist in coolant distribution infrastructure for liquid cooling technology in data centers. This acquisition aims to bolster Vertiv's capacity to deploy AI solutions at a large scale and improve its ability to meet the demands of global data center clients. CoolTera specializes in designing and producing coolant distribution units (CDU), secondary fluid networks (SFN), and manifolds tailored for liquid cooling solutions in data centers.
- In May 2023, Fujitsu and Microsoft unveiled a worldwide collaboration to facilitate "sustainability transformation" and assist enterprises in migrating their workloads to the cloud. Fujitsu will leverage its expertise in data center infrastructure, complemented by Microsoft's Azure cloud computing platform. This strategic partnership offers businesses a holistic solution for modernizing their IT infrastructure.
- In November 2023, Schneider Electric and Compass Datacenters extended their collaboration through a multi-year agreement valued at USD 3 billion. This initiative focuses on producing and distributing prefabricated modular data center solutions. The goal is to streamline their supply chains, ensuring faster, more reliable, and cost-effective delivery of finished products.
Market Concentration & Characteristics
The market concentration of Qatar’s data center cooling sector is relatively moderate, with a mix of global and regional players providing a range of advanced cooling solutions. While the market is dominated by a few key international companies, local players are increasingly making their mark by offering customized solutions to meet the unique challenges of Qatar’s climate. The presence of large multinational corporations ensures a high level of competition, with providers differentiating themselves based on product innovation, energy efficiency, and environmental sustainability. One of the key characteristics of this market is the strong emphasis on energy-efficient technologies due to the high energy costs in Qatar. As a result, providers are focusing on solutions such as liquid cooling, AI-driven optimization, and evaporative cooling, which reduce operational costs while maintaining the required cooling performance. Additionally, sustainability is a central focus, with many companies offering eco-friendly cooling solutions aligned with Qatar’s commitment to reducing carbon emissions. The demand for scalable and flexible systems, such as modular cooling solutions, is also growing as data centers in the region increasingly seek to accommodate rising data traffic and the deployment of 5G networks. The market is characterized by a constant drive for technological innovation and the need for solutions that can operate efficiently in extreme temperatures.
Report Coverage
The research report offers an in-depth analysis based on Component, Application, Solution, Containment, Services, Cooling Type, Structure and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Qatar data center cooling market is expected to continue its strong growth, driven by the increasing demand for data centers and digital transformation.
- Energy-efficient and sustainable cooling technologies will be a major focus, with rising emphasis on AI-driven optimization and liquid cooling systems.
- The adoption of renewable energy sources, such as solar power, will increase to align with Qatar’s sustainability goals.
- The demand for high-density cooling solutions will grow as data centers expand to accommodate more servers and processing power.
- Modular cooling systems will gain traction, providing flexibility and scalability for growing data center operations.
- The rollout of 5G networks will drive higher data traffic, necessitating advanced and efficient cooling solutions.
- Edge computing will lead to the development of smaller, localized data centers, requiring specialized cooling technologies.
- Increased government initiatives, such as smart city projects, will boost the need for reliable data center cooling infrastructure.
- Rising ambient temperatures in Qatar will push companies to innovate cooling systems that can withstand extreme conditions.
- The competitive landscape will intensify, with both global and regional players offering cutting-edge cooling solutions to meet market demands.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Qatar Data Center Cooling market?
What factors are driving the growth of the Qatar Data Center Cooling market?
What are the key segments within the Qatar Data Center Cooling market?
What are some challenges faced by the Qatar Data Center Cooling market?
Who are the major players in the Qatar Data Center Cooling market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Qatar Data Center Cooling Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Qatar Data Center Cooling Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 81.04 million → 2032: USD 248.97 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Qatar Data Center Cooling Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Qatar Data Center Cooling Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Qatar Data Center Cooling Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Qatar Data Center Cooling Market Drivers
- 3.3 Qatar Data Center Cooling Market Restraints & Challenges
- 3.4 Qatar Data Center Cooling Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Qatar Data Center Cooling Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Qatar Data Center Cooling Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Qatar Data Center Cooling category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Qatar Data Center Cooling Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Qatar Data Center Cooling Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Qatar Data Center Cooling market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Qatar Data Center Cooling Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Qatar Data Center Cooling Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Qatar Data Center Cooling Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Qatar Data Center Cooling (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Qatar Data Center Cooling Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Qatar Data Center Cooling Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Qatar Data Center Cooling Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Qatar Data Center Cooling Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Qatar Data Center Cooling Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Qatar Data Center Cooling Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Qatar Data Center Cooling Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Qatar Data Center Cooling Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Qatar Data Center Cooling Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
