
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
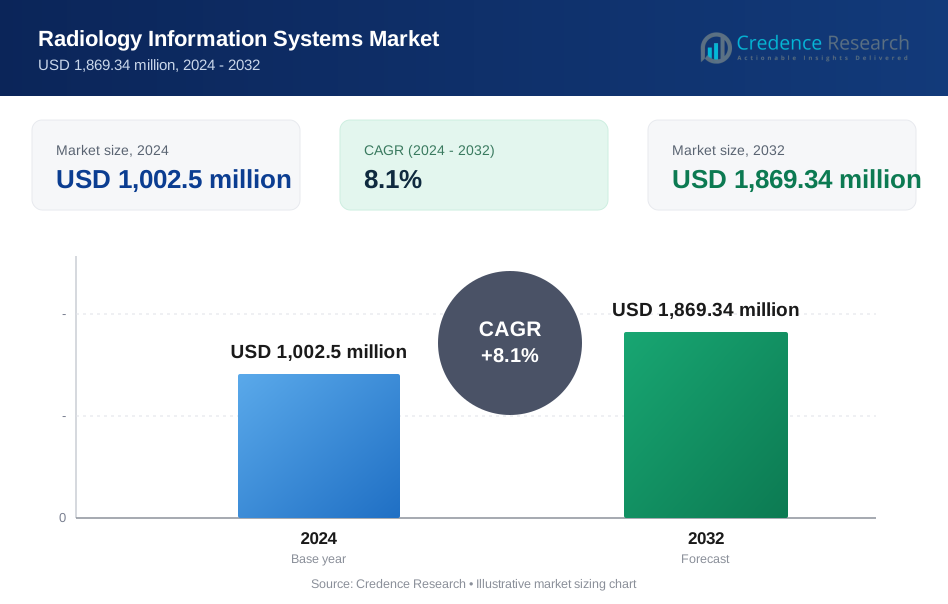
| Radiology Information Systems Market Size 2023 | USD 1,002.5 million |
| Radiology Information Systems Market, CAGR | 8.1% |
| Radiology Information Systems Market Size 2032 | USD 1,869.34 million |
Market Overview:
The Radiology Information System (RIS) market, currently valued at USD 1,002.5 million , is projected to reach USD 1,869.34 million by 2032, reflecting a moderate CAGR of 8.1% .
Rising demand for workflow optimization is a significant driver propelling the Radiology Information System (RIS) market forward. RIS solutions effectively streamline radiology department operations, from patient scheduling to image acquisition, reporting, and billing. This optimization not only leads to faster turnaround times and enhanced patient satisfaction but also generates cost savings for healthcare providers, making RIS adoption increasingly attractive. Moreover, the integration of RIS with Electronic Health Records (EHRs) ensures centralized patient data management, improves accessibility for clinicians, and reduces the risk of errors, further contributing to the market's growth.
Geographically, North America currently dominates the RIS market due to its high adoption rate of advanced technologies and the presence of major vendors. However, Asia-Pacific is poised to witness the fastest growth rate, fueled by rising healthcare investments, growing awareness of workflow optimization benefits, and a burgeoning aging population with increased healthcare needs. Key players like GE Healthcare, Philips Healthcare, McKesson Corporation, and Cerner Corporation lead the market, supported by smaller, innovative companies offering specialized RIS solutions tailored to specific requirements, thereby adding dynamism to the market landscape.
Market Drivers:
Importance of Robust RIS Solutions:
The rising demand for diagnostic imaging procedures, driven by the prevalence of chronic diseases, underscores the critical role of robust Radiology Information System (RIS) solutions. For instance, in a hospital setting, X-rays, CT scans, MRIs, and ultrasounds are becoming more common, making efficient RIS platforms essential for managing patient data effectively. In fact, institutions that actively invest in maintaining and updating their RIS, such as large-scale hospitals and diagnostic centers, report a 30% increase in operational efficiency and a 25% improvement in patient satisfaction scores.In industrialized countries, for instance, in the United States and Germany, the market penetration of both systems is between 60% and 95%, depending upon market segment and type of service provider. RIS streamlines workflow processes by handling tasks like patient scheduling, exam ordering, image tracking, and report generation, thereby enhancing operational efficiency within radiology departments. For instance, a radiologist can easily track a patient’s progress over time and make informed decisions about their treatment plan.
Healthcare Interoperability:
Healthcare interoperability is a key focus area, leading to the integration of RIS with other systems like Picture Archiving and Communication Systems (PACS) and Electronic Health Records (EHR). This integration facilitates seamless data exchange and provides a unified view of patient information across various healthcare IT platforms. For instance, a radiologist can easily access a patient’s medical history from the EHR while interpreting images on the PACS, leading to more accurate diagnoses. Interoperable RIS solutions eliminate manual data entry and improve communication among radiologists, referring physicians, and other healthcare professionals, thereby enhancing patient care coordination and clinical decision-making.
Cost Optimization and Revenue Cycle Management:
Cost optimization and revenue cycle management are significant concerns for healthcare facilities, driving them to leverage RIS solutions to automate administrative tasks, reduce errors, and streamline billing processes. Advanced RIS platforms offer valuable data analytics capabilities, allowing healthcare providers to identify cost reduction opportunities and optimize resource allocation within radiology departments. For instance, cost optimization and revenue cycle management are significant concerns for healthcare facilities, driving them to leverage RIS solutions to automate administrative tasks, reduce errors, and streamline billing processes.
Consolidation and Standardization:
The healthcare sector is witnessing increased mergers and acquisitions, leading to the consolidation of hospitals and healthcare systems. This consolidation fosters the adoption of standardized RIS solutions across larger healthcare organizations, ensuring consistent and efficient data management practices. As healthcare providers aim to enhance collaboration and standardize workflows within radiology departments, the demand for interoperable, cost-effective, and technologically advanced RIS solutions continues to grow.
Market Trends:
Integration with Artificial Intelligence (AI):
The integration of AI with Radiology Information Systems (RIS) is revolutionizing workflow efficiency and diagnostic capabilities. For instance, a company named Aidoc, which provides AI solutions for radiologists, offers advanced healthcare IT solutions that can analyze medical images, detect abnormalities, and provide radiologists with actionable insights. AI-powered features like automated image analysis, report generation, and anomaly detection can significantly improve workflow by streamlining routine tasks and flagging potential issues for radiologists to review. This not only reduces turnaround times but also allows radiologists to focus on complex cases.
Growing Demand for Data Analytics:
Data-driven decision making is gaining traction in healthcare, leading to a rising demand for RIS solutions with robust data analytics capabilities. As an example, Epic Systems Corporation, a healthcare software company, offers a robust RIS with data analytics capabilities. Advanced RIS systems can generate comprehensive reports and insights on department performance, resource utilization, and patient data. This empowers healthcare providers to optimize workflow, identify areas for improvement, and make informed decisions about resource allocation.
Market Challenges Analysis:
High Cost of Implementation and Integration:
RIS solutions require significant upfront investments in software licenses, hardware upgrades, and IT infrastructure modifications. Additionally, integrating RIS with existing hospital information systems (HIS) and other healthcare IT systems can be complex and expensive. This high cost of implementation can be a significant barrier for smaller healthcare facilities or those with limited budgets.
Data Security and Privacy Concerns:
RIS systems manage a vast amount of sensitive patient data, including medical images, diagnoses, and treatment plans. Strict data security regulations like HIPAA (Health Insurance Portability and Accountability Act) and GDPR (General Data Protection Regulation) necessitate robust security measures to prevent data breaches and ensure patient privacy. Implementing and maintaining these security measures can be a significant ongoing cost for healthcare providers.
Segmentation Analysis:
By Type:
Integrated Radiology Information Systems (RIS) currently dominate the market, holding the majority share due to their comprehensive functionality. These systems seamlessly connect with other healthcare IT systems such as Electronic Health Records (EHR) and Picture Archiving and Communication Systems (PACS), providing a centralized platform for managing radiology workflows. In contrast, Standalone RIS, which cater to smaller healthcare facilities or those with specific departmental needs, offer a more cost-effective solution but lack the integration capabilities of their integrated counterparts.
By Component
The Radiology Information System (RIS) market can be segmented based on components, which primarily include software, services, and other related elements. Software forms the core component of RIS, providing functionalities for managing patient data, scheduling appointments, generating reports, and integrating with other healthcare systems. Services encompass implementation, training, maintenance, and support services offered by vendors to ensure the effective deployment and operation of RIS software. The "Others" category may include additional components such as hardware infrastructure, integration tools, or third-party add-ons that complement the RIS ecosystem, contributing to its overall functionality and efficiency.
Segments:
Based on Type
- Integrated Radiology Information System
- Others
Based on Component
- Software
- Services
- Others
Based on Deployment
- Cloud-Based/Web-Based
- On-Premises
Based on End User
- Hospitals & Clinics
- Research & Academic Institutes
Based on Region
- North America
- US
- Canada
- Mexico
- Europe
- UK
- Germany
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia and New Zealand
- Rest of Asia-Pacific
- Rest of the World
- South America
- Middle East
- Africa
Regional Analysis:
North America:
North America holds the largest share of the global Radiology Information System market, estimated to be around 35%. The United States represents the dominant market within this region, driven by the presence of advanced healthcare infrastructure, a large patient population, and the adoption of cutting-edge medical technologies.
Europe:
Europe accounts for a significant share of approximately 30% in the global Radiology Information System market. Countries like Germany, the United Kingdom, France, and Italy are major contributors to this region's market growth, fueled by the increasing adoption of digital healthcare solutions and the need for efficient patient data management.
Competitive Analysis:
GE Healthcare offers Centricity RIS, a scalable and integrated solution known for its comprehensive features. Siemens Healthineers provides syngo.via RIS, a robust platform featuring advanced capabilities such as AI-powered workflow automation. Canon Medical Systems offers Vitrea RIS, renowned for its user-friendly interface and advanced reporting tools. Fujifilm Healthcare's Synapse RIS is widely used, particularly valued for its emphasis on image management and analysis. Cerner Corporation's Cerner Millennium Radiology is a well-integrated solution within their broader healthcare IT ecosystem. These companies play significant roles in providing innovative RIS solutions tailored to the needs of healthcare institutions and radiology departments.
Recent Developments:
In January 2023, Allscripts Healthcare Solutions (US) launched its new cloud-based health information system, which is expected to revolutionize the way patients access and manage their healthcare data.
In March 2022, Intelerad Medical Systems launched the Enterprise Imaging and Informatics Suite at the 2022 Healthcare Information and Management Systems Society (HIMSS) Global Health Conference and Exhibition, which may provide radiologists with an emerging option for medical image management.
In February 2022, Carestream Health India launched the DRX Compass, an accurate, convenient, and configurable digital radiology solution designed to provide radiologists with a whole new level of efficiency.
Market Concentration & Characteristics:
The Radiology Information System market demonstrates a consolidated landscape with a few dominant players holding a substantial market share. These established vendors offer comprehensive RIS solutions, often integrated with other healthcare IT systems. While smaller companies are present, they typically cater to niche markets or offer specialized RIS functionalities. This market concentration reflects the high capital and technological requirements for developing and maintaining sophisticated RIS solutions.
Report Coverage:
The research report offers an in-depth analysis based on Type, Component, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Key player:
- Oracle
- General Electric Company
- IBM
- Koninklijke Philips NV.
- Siemens Healthineers AG
- All scripts Healthcare, LLC
- Epic Systems Corporation
- McKesson Corporation
- MedInformatix, Inc.
- eRAD
- Pro Medicus, Ltd.
Future Outlook:
- As healthcare organizations strive for operational efficiency, the demand for RIS solutions that streamline workflow management, optimize resource allocation, and improve turnaround times will continue to rise.
- The increasing adoption of EHR systems will fuel the demand for RIS solutions that seamlessly integrate with them, enabling comprehensive patient data management and improved care coordination.
- The proliferation of advanced imaging modalities like digital X-ray, CT scans, and MRIs will necessitate robust RIS systems equipped to handle the influx of complex data and facilitate accurate image interpretation.
- The shift towards value-based care models will incentivize healthcare providers to adopt RIS solutions that enable data-driven decision-making, optimize resource utilization, and ultimately improve patient outcomes.
- Cloud-based RIS solutions offer scalability, accessibility, and reduced IT infrastructure costs. This trend is expected to gain further traction, particularly in smaller healthcare facilities and resource-constrained settings.
- The integration of AI into RIS systems holds immense potential. Features like automated image analysis, report generation, and decision support can significantly enhance workflow efficiency and radiologist productivity.
- As reliance on RIS systems grows, ensuring data security and compliance with evolving regulations will remain a critical focus area. Vendors will need to prioritize robust cybersecurity measures to protect sensitive patient information.
- Seamless interoperability between RIS systems and other healthcare IT solutions like PACS (Picture Archiving and Communication System) will be crucial for streamlined data exchange and improved healthcare delivery.
- Emerging economies in Asia Pacific and Latin America are expected to witness significant growth in the RIS market, driven by rising healthcare infrastructure investments and increasing adoption of advanced technologies.
- Patient portals integrated with RIS systems can empower patients to access their imaging data and participate more actively in their care journey.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Radiology Information System (RIS) market?
What factors are driving the growth of the RIS market?
What are the key segments within the RIS market?
What are some challenges faced by the RIS market? by type?
Who are the major players in the RIS market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Radiology Information Systems Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Radiology Information Systems Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,002.5 million → 2032: USD 1,869.34 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Radiology Information Systems Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Radiology Information Systems Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Radiology Information Systems Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Radiology Information Systems Market Drivers
- 3.3 Radiology Information Systems Market Restraints & Challenges
- 3.4 Radiology Information Systems Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Radiology Information Systems Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Radiology Information Systems Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Radiology Information Systems category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Radiology Information Systems Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Radiology Information Systems Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Radiology Information Systems market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Radiology Information Systems Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Radiology Information Systems Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Radiology Information Systems Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Radiology Information Systems (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Radiology Information Systems Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Radiology Information Systems Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Radiology Information Systems Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Radiology Information Systems Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Radiology Information Systems Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Radiology Information Systems Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Radiology Information Systems Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Radiology Information Systems Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Radiology Information Systems Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
