
Market Overview:
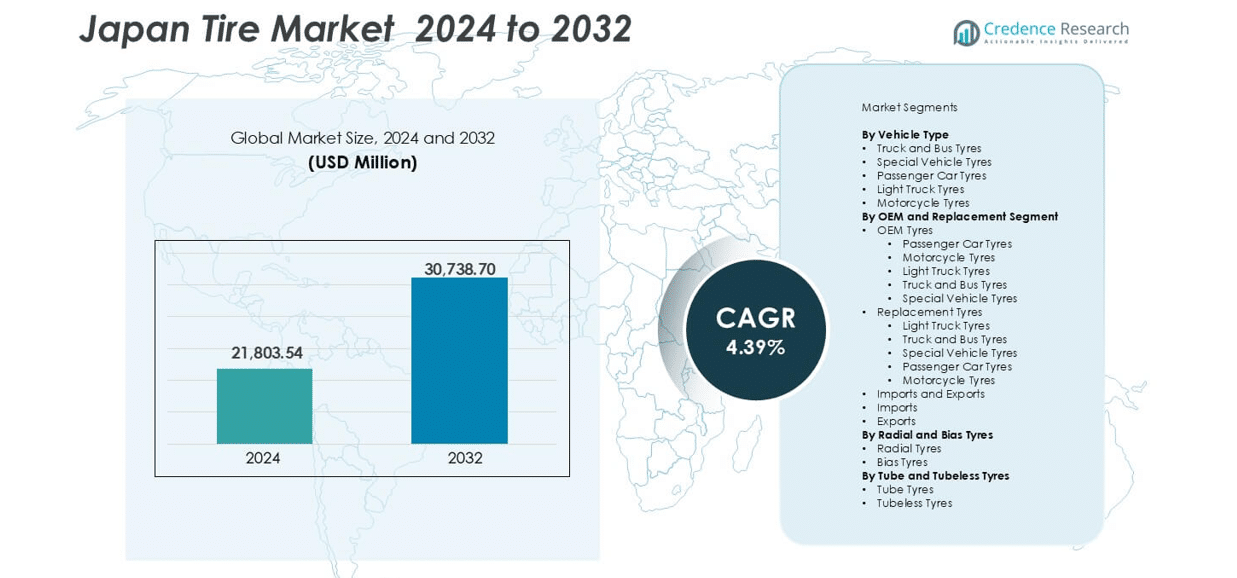
Japan tire market size was valued at USD … million in 2018, increased to USD 21,803.54 million in 2024, and is anticipated to reach USD 30,738.70 million by 2032, growing at a CAGR of 4.39% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Japan Tire Market Size 2024 | USD 21,803.54 million |
| Japan Tire Market, CAGR | 4.39% |
| Japan Tire Market Size 2032 | USD 30,738.70 million |
The Japan tire market is led by Bridgestone Corporation, Yokohama Rubber Company, and Sumitomo Rubber Industries, which collectively account for over 70% of domestic production. Bridgestone maintains dominance through advanced tire technology, extensive OEM partnerships, and strong export capacity. Yokohama Rubber focuses on eco-friendly and performance tires, while Sumitomo Rubber emphasizes smart tire systems and digital mobility integration. Toyo Tire and Nitto Tire strengthen the high-performance and off-road segments, supported by steady aftermarket sales. Among international brands, Michelin, Goodyear, Continental, and Pirelli maintain a premium presence in passenger and performance categories. Regionally, Kanto leads the market with 42% share, driven by dense vehicle ownership, robust logistics activity, and major manufacturing facilities.
Market Insights
- The Japan tire market was valued at USD 21,803.54 million in 2024 and is projected to reach USD 30,738.70 million by 2032, growing at a CAGR of 4.39%.
- Growth is driven by expanding EV and hybrid vehicle production, rising replacement demand from an aging fleet, and advancements in smart tire technologies enhancing performance and efficiency.
- Key trends include the adoption of eco-friendly, low-rolling-resistance tires and increased digitalization through sensor-enabled and connected tire systems for improved safety and data insights.
- The market is highly competitive, led by Bridgestone, Yokohama Rubber, and Sumitomo Rubber, while international brands like Michelin, Goodyear, and Continental strengthen premium and performance segments.
- Regionally, Kanto holds 42% share, followed by Kansai at 24% and Chubu at 18%; passenger car tires dominate the segment with 48% share, supported by steady OEM and strong replacement demand across urban areas.
Market Segmentation Analysis:
By Vehicle Type
Passenger car tyres dominate the Japan tire market with nearly 48% share in 2024. Their dominance stems from strong domestic car ownership, rising hybrid and electric vehicle registrations, and high replacement frequency. Leading brands like Bridgestone and Yokohama Rubber invest in advanced tread compounds and low-rolling-resistance technology to enhance fuel efficiency and ride comfort. Truck and bus tyres follow, driven by logistics expansion and highway freight movement. Motorcycle tyres maintain steady demand, supported by commuter bikes and recreational riding growth across urban and suburban regions.
- For instance, in 2024, the Japan Automobile Tyre Manufacturers Association (JATMA) reported production of 89,422 thousand passenger-car tyres.
By OEM and Replacement Segment
Replacement tyres hold the largest share of about 68% in Japan’s tire market. The segment benefits from an aging vehicle fleet, frequent maintenance practices, and consumer preference for premium aftermarket brands. Passenger car replacement tyres lead within this segment due to their high turnover and expanding e-commerce tire distribution. OEM tyres remain vital, supported by new vehicle production and export-oriented manufacturing by Toyota, Honda, and Nissan. Demand for motorcycle and truck OEM tyres also increases as local automakers enhance safety and fuel-efficiency standards in new models.
- For example, JATMA reports 66,280 thousand replacement tyres were sold in 2024
By Radial and Bias Tyres
Radial tyres dominate with over 85% share in the Japan market, replacing traditional bias tyres in almost all on-road vehicles. Their stronghold comes from superior durability, ride comfort, and fuel-saving capabilities. The shift aligns with Japan’s focus on energy-efficient mobility and safety regulations. Major manufacturers such as Sumitomo Rubber and Bridgestone invest in advanced steel-belted radial designs with smart tire sensors and silica-based compounds. Bias tyres retain a limited presence in off-road and heavy-duty special vehicles, valued for their toughness and cost-effectiveness in construction and agricultural applications.
Key Growth Drivers
Expansion of Electric and Hybrid Vehicle Production
Japan’s growing shift toward electric and hybrid vehicles is significantly boosting tire demand. Leading automakers such as Toyota and Nissan are expanding EV production, creating a surge in specialized tire requirements that support low rolling resistance, quiet operation, and enhanced energy efficiency. These vehicles require tires with high grip and durability to handle increased torque and instant acceleration. Tire manufacturers like Bridgestone and Yokohama Rubber are developing EV-dedicated lines featuring advanced silica compounds and noise-canceling tread designs. The country’s strong EV policy incentives and technology-driven automotive ecosystem continue to drive steady growth in this segment, reinforcing Japan’s leadership in sustainable mobility solutions.
- For instance, the Yokohama Rubber Co., Ltd. began production of its EV-dedicated tyre, the ADVAN Sport EV, in September 2023 using renewable energy at that plant.
Rising Replacement Demand from Aging Vehicle Fleet
Japan’s aging vehicle fleet is fueling robust growth in the replacement tire segment. With an average vehicle age exceeding 8.5 years, the need for frequent tire replacements remains high. Consumers prioritize quality and safety, encouraging purchases of premium and all-season tires. Established distributors and digital retail channels such as Autobacs and Tire Hood are expanding tire delivery and installation networks. Seasonal tire swaps, especially between winter and summer, also add to replacement volume. This mature aftermarket base supports consistent demand for passenger car, truck, and motorcycle tires. The preference for high-performance tires with enhanced tread life and fuel efficiency further strengthens market expansion, particularly across urban and suburban areas.
- For instance, Seasonal tyre swaps, especially between winter and summer, also add to replacement volume-replacement tyre sales in Japan reached 46,420 thousand units for passenger car tyres in 2024.
Strong Export Orientation and Technological Leadership
Japan’s tire industry benefits from strong export performance and advanced R&D capabilities. Major producers, including Bridgestone, Sumitomo Rubber, and Toyo Tires, export to over 150 countries, supported by production hubs in Asia, Europe, and North America. These firms focus on smart tire technology integrating sensors for pressure, wear monitoring, and performance analytics, improving safety and predictive maintenance. Continuous innovation in eco-friendly materials and noise-reduction compounds enhances global competitiveness. The country’s leadership in precision manufacturing and automation strengthens productivity and consistency in tire quality. Export-driven growth, coupled with sustained technological advancement, keeps Japan at the forefront of global tire innovation and performance standards.
Key Trends & Opportunities
Adoption of Smart and Connected Tire Technologies
The integration of smart tire systems is emerging as a key trend in Japan’s tire industry. Manufacturers are incorporating pressure, temperature, and wear sensors into tire structures to enable real-time monitoring and predictive maintenance. Bridgestone’s “AirFree” and Sumitomo’s “Sensing Core” systems highlight this trend by offering data-driven insights for fleet operators and EV manufacturers. These technologies improve safety, reduce downtime, and extend tire life through early anomaly detection. As Japan embraces vehicle connectivity and automation, such digital integration is becoming essential. The rise of telematics-enabled tires supports fleet management efficiency and aligns with the nation’s intelligent transportation initiatives.
- For instance, Bridgestone Corporation’s “CAIS™” (Contact Area Information Sensing) technology classifies road surfaces into seven types - dry, semi-dry, wet, slush, fresh snow, compacted snow, and ice - using sensors attached to tyres.
Growth of Eco-Friendly and Low-Rolling-Resistance Tires
Sustainability is a central focus for Japan’s tire manufacturers. The government’s carbon neutrality targets and consumer preference for fuel-efficient vehicles are pushing companies to design green tires using bio-based rubber, recycled materials, and energy-efficient tread patterns. Yokohama’s “BluEarth” and Bridgestone’s “ENLITEN” series exemplify innovations that reduce CO₂ emissions without compromising performance. These tires deliver improved fuel economy and longer service life. Tire makers are also implementing circular economy models by enhancing retreading, recycling, and sustainable sourcing practices. This green shift supports Japan’s broader environmental objectives and provides competitive differentiation in export markets that value sustainability.
Key Challenges
Declining Domestic Vehicle Ownership and Population Aging
Japan faces a gradual decline in domestic tire demand due to an aging population and falling vehicle ownership rates. Urbanization and efficient public transport reduce personal vehicle use, particularly among younger demographics. This shift limits growth potential for OEM and replacement tire segments. Rural demand remains stable but cannot offset urban declines. Tire companies are responding by expanding into mobility services, tire leasing, and recycling solutions. However, maintaining profitability in a shrinking domestic base remains challenging. Companies must continue investing in export diversification and technology-driven differentiation to balance weakening home-market consumption.
Rising Raw Material and Energy Costs
Fluctuating prices of natural rubber, synthetic polymers, and crude oil-derived compounds pose cost pressures on Japanese tire manufacturers. Energy-intensive production processes amplify the impact of global oil and utility price volatility. Firms like Bridgestone and Toyo Tires are adopting cost-optimization strategies, including material substitution, renewable energy sourcing, and digital production monitoring. Despite these efforts, profit margins remain sensitive to input cost fluctuations. Additionally, currency exchange variations affect export pricing competitiveness. Maintaining stability amid these rising costs requires continued innovation in material science, local sourcing diversification, and operational efficiency across production lines.
Regional Analysis
Kanto Region
Kanto dominates the Japan tire market with nearly 42% share in 2024. The region’s leadership stems from its dense population, high vehicle ownership, and concentration of automotive and logistics hubs in Tokyo, Yokohama, and Saitama. Continuous urban development and commuter traffic sustain strong replacement tire demand, especially for passenger cars and motorcycles. OEM demand remains steady, driven by production facilities of major automakers such as Nissan and Honda. The expansion of e-commerce fleets and EV adoption further supports tire sales, making Kanto the most dynamic and revenue-intensive regional market.
Kansai Region
Kansai holds about 24% share of the Japan tire market, supported by strong industrial and commercial vehicle activity across Osaka, Kyoto, and Kobe. The region’s robust logistics network and manufacturing base drive demand for truck and bus tires. Passenger vehicle tire sales remain healthy due to consistent urban commuting patterns and growing EV registrations. OEM activity benefits from tire production and distribution centers operated by leading brands like Bridgestone. The region’s focus on sustainable manufacturing and smart mobility solutions continues to attract investment, enhancing its long-term market potential.
Chubu Region
Chubu accounts for nearly 18% share of the national tire market, led by Nagoya’s automotive manufacturing cluster. The presence of Toyota Motor Corporation significantly boosts OEM tire demand, supporting large-scale supply contracts for premium passenger and light truck tires. Industrial vehicle use also contributes to replacement tire growth, aided by active logistics and construction sectors. The region’s well-developed road infrastructure and highway connectivity strengthen aftermarket opportunities. Chubu’s continued investments in next-generation vehicle development, including hydrogen and hybrid platforms, further enhance demand for advanced, durable, and energy-efficient tire solutions.
Kyushu Region
Kyushu represents around 10% share of Japan’s tire market, backed by its growing automotive manufacturing and export activity. Fukuoka and Kumamoto host production facilities for manufacturers like Bridgestone and Yokohama Rubber, supporting OEM tire output. The region’s expanding EV and hybrid assembly lines also stimulate demand for specialized tires. Replacement tire sales benefit from a rising number of commercial vehicles supporting trade and shipping routes. Regional focus on renewable energy and green manufacturing practices complements the adoption of eco-friendly tire technologies, enhancing Kyushu’s role as an emerging tire production hub.
Hokkaido and Tohoku Region
Hokkaido and Tohoku collectively hold about 6% share in the Japan tire market. The regions experience strong seasonal tire demand due to harsh winter conditions, driving sales of studless and snow-specific tires. Rural road networks and agricultural activity support steady light truck and special vehicle tire consumption. Manufacturers cater to these regions through localized distribution and storage facilities for quick seasonal replacements. The replacement segment remains dominant as passenger vehicles and small commercial fleets rely heavily on winter tire swaps. Despite modest population density, cold-weather demand ensures consistent regional revenue.
Market Segmentations:
By Vehicle Type
- Truck and Bus Tyres
- Special Vehicle Tyres
- Passenger Car Tyres
- Light Truck Tyres
- Motorcycle Tyres
By OEM and Replacement Segment
- OEM Tyres
-
- Passenger Car Tyres
- Motorcycle Tyres
- Light Truck Tyres
- Truck and Bus Tyres
- Special Vehicle Tyres
- Replacement Tyres
-
- Light Truck Tyres
- Truck and Bus Tyres
- Special Vehicle Tyres
- Passenger Car Tyres
- Motorcycle Tyres
- Imports and Exports
-
- Imports
- Exports
By Radial and Bias Tyres
- Radial Tyres
- Bias Tyres
By Tube and Tubeless Tyres
- Tube Tyres
- Tubeless Tyres
By Geography
- Kanto Region
- Kansai Region
- Chubu Region
- Kyushu Region
- Hokkaido and Tohoku Region
Competitive Landscape
The Japan tire market features a highly competitive landscape dominated by global and domestic manufacturers focusing on innovation, quality, and sustainability. Bridgestone Corporation leads the market with extensive product diversity, advanced smart tire systems, and strong OEM partnerships with major automakers such as Toyota and Nissan. Yokohama Rubber and Sumitomo Rubber Industries maintain competitive strength through eco-friendly materials and performance-driven technologies. Toyo Tire and Nitto Tire emphasize ultra-high-performance and off-road tire lines, while international brands like Michelin, Goodyear, Continental, and Pirelli reinforce premium market competition through advanced tread designs and noise-reduction features. Companies continue to invest in R&D for electric vehicle-compatible and low-rolling-resistance tires, aligning with Japan’s carbon-neutral goals. Strategic collaborations, digital sales expansion, and automation-based production further enhance competitiveness, positioning Japan as a global hub for tire innovation and sustainable manufacturing excellence.
Key Player Analysis
- Bridgestone Corporation
- Yokohama Rubber Company
- Sumitomo Rubber Industries
- Toyo Tire Corporation
- Nitto Tire
- Dunlop Tires
- Michelin
- Goodyear
- Continental AG
- Pirelli
Recent Developments
- In December 2023, Michelin Tire Japan announced a price increase for its tires in the Japanese market, effective February 1, 2024. The prices of Michelin, BF Goodrich, and Camso brand tires would be increased by 6-10%, depending on the product. This hike was applicable to commercial tires for passenger cars, light trucks, and motorcycles in Japan.
- In August 2023, Toyo Tires released its Integrated Report 2023. This report is the company’s first annual report to combine financial and non-financial information in an integrated manner. It is a part of Toyo Tires’ Mid-Term ’21 Plan, emphasizing the integration of sustainability and ESG into its business management to address social issues and support the development of a sustainable society.
- In April 2023, Bridgestone Corporation implemented a significant environmental initiative by transitioning all the electricity purchased for six of its tire and raw materials plants in Japan to renewable energy sources. This move was part of Bridgestone’s broader commitment to sustainability and reducing its environmental impact.
- In January 2023, The Yokohama Rubber Co., Ltd. announced the start of operations at their new indoor ice circle test facility within the Tire Test Center of Hokkaido (TTCH). This facility, renowned for being the most extensive of its kind in Japan, is dedicated to conducting detailed tests on the turning capabilities of winter tires on icy surfaces. The establishment of this state-of-the-art facility underscores Yokohama Rubber’s commitment to advancing tire safety and performance, particularly under challenging winter conditions.
Report Coverage
The research report offers an in-depth analysis based on Vehicle Type, OEM and Replacement Segment, Radial and Bias Tyres, Tube and Tubeless Tyres and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Growing demand for electric and hybrid vehicle tires will remain a key growth factor.
- Replacement tire sales will expand due to Japan’s aging vehicle fleet and seasonal change cycles.
- Manufacturers will focus on low-rolling-resistance and eco-friendly materials for sustainability.
- Smart and connected tires with sensor technology will gain wider adoption in fleet management.
- Leading players will strengthen domestic and export operations with advanced R&D investments.
- Rising raw material and energy costs may pressure production margins in coming years.
- Increasing preference for premium and performance tires will enhance revenue streams.
- Digital retail and e-commerce platforms will drive tire accessibility and brand competition.
- Regional leadership will continue in Kanto with 42% share, followed by Kansai and Chubu.
- Long-term outlook remains positive, supported by innovation, EV adoption, and regulatory compliance.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Electric and Hybrid Vehicle Production
Japan's strong push towards electric and hybrid vehicles is driving demand for specialized tires that offer low rolling resistance, quiet operation, and enhanced energy efficiency. Leading automakers and tire manufacturers are collaborating to develop EV-dedicated tire lines, supporting market growth.
Rising Replacement Demand from Aging Vehicle Fleet
With the average vehicle age exceeding 8.5 years, frequent tire replacements are necessary, especially for passenger cars. This trend is reinforced by seasonal tire swaps and a mature aftermarket supported by digital retail channels, boosting replacement tire sales.
Technological Leadership and Smart Tire Adoption
Japanese tire manufacturers are at the forefront of integrating smart tire technologies, such as sensor-enabled systems for real-time monitoring and predictive maintenance. These innovations enhance safety, fleet management, and align with Japan's intelligent transportation initiatives.
Growth of Eco-Friendly and Low-Rolling-Resistance Tires
Government carbon neutrality targets and consumer preferences for sustainability are pushing manufacturers to develop green tires using bio-based and recycled materials. These eco-friendly products improve fuel economy and support Japan’s environmental goals.
Strong Export Orientation
Japan’s tire industry benefits from robust export activity, with major producers supplying advanced tires to over 150 countries. Continuous innovation and high-quality standards ensure global competitiveness and drive revenue beyond the domestic market.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the expected growth rate of the Japanese tire market and its key drivers?
At what Compound Annual Growth Rate is the Japan Tire market projected to grow between 2025 and 2032?
How does technological innovation impact the Japanese tire market?
What role does the Japanese automotive industry play in the tire market's growth?
What are some notable tire innovations from Japan?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Vehicle Type
- 1.2.1 Passenger Car Tyres
- 1.2.2 Truck and Bus Tyres
- 1.2.3 Light Truck Tyres
- 1.2.4 Motorcycle Tyres
- 1.2.5 Special Vehicle Tyres
- 1.3 By Radial and Bias Tyres
- 1.3.1 Radial Tyres
- 1.3.2 Bias Tyres
- 1.4 By OEM and Replacement Segment
- 1.4.1 OEM Tyres
- 1.4.2 Replacement Tyres
- 1.4.3 Imports
- 1.4.4 Exports
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 21,803.54 million → 2032: USD 30,738.70 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Japan Tire Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Japan Tire Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Japan Tire Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Japan Tire Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Japan Tire Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Japan Tire Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Japan Tire Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Japan Tire Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 21,803.54 million → 2032: USD 30,738.70 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Japan Tire Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Vehicle Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Passenger Car Tyres
- 12.3.7.2 Truck and Bus Tyres
- 12.3.7.3 Light Truck Tyres
- 12.3.7.4 Motorcycle Tyres
- 12.3.7.5 Special Vehicle Tyres
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Radial and Bias Tyres - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Radial Tyres
- 12.4.7.2 Bias Tyres
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By OEM and Replacement Segment - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 OEM Tyres
- 12.5.7.2 Replacement Tyres
- 12.5.7.3 Imports
- 12.5.7.4 Exports
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Japan Tire Geographic Market Outlook, 2024-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 Japan Tire Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Japan Tire Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Bridgestone Corporation
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Yokohama Rubber Company
- 17.4 Sumitomo Rubber Industries
- 17.5 Toyo Tire Corporation
- 17.6 Nitto Tire
- 17.7 Dunlop Tires
- 17.8 Michelin
- 17.9 Goodyear
- 17.10 Continental AG
- 17.11 Pirelli
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

