
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
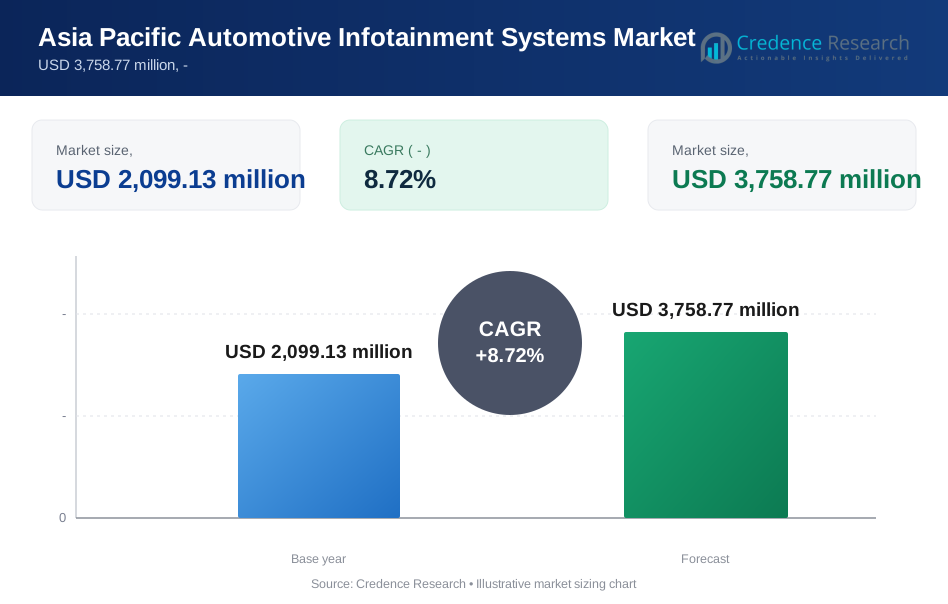
| Asia Pacific Automotive Infotainment Systems Market Size 2023 | USD 2,099.13 million |
| Asia Pacific Automotive Infotainment Systems Market, CAGR | 8.72% |
| Asia Pacific Automotive Infotainment Systems Market Size 2032 | USD 3,758.77 million |
Market Overview:
The APAC automotive infotainment systems market is witnessing substantial growth, driven by various factors. In 2023, the market was valued at USD 2,099.13 million and is projected to reach USD 3,758.77 million by 2032, reflecting a robust compound annual growth rate (CAGR) of 8.72%. Rising disposable incomes in developing economies like China and India are fueling consumer spending on vehicles equipped with advanced infotainment systems, while shifting consumer preferences towards in-vehicle entertainment and connectivity options contribute to market expansion. Additionally, the integration of advanced driver-assistance systems (ADAS) with infotainment systems to enhance safety features further propels market growth.
Several key drivers are expected to shape the future trajectory of the APAC automotive infotainment systems market. Rapid urbanization in the region is leading to increased car ownership, creating a larger market for automotive infotainment systems. Furthermore, expanding internet penetration and high smartphone adoption foster demand for connected-car features accessible through infotainment systems. Automakers' focus on in-vehicle technology as a key differentiator drives the development of advanced infotainment systems with personalized features and seamless connectivity, catering to evolving consumer preferences. Moreover, the emphasis on localization to address regional preferences and content is vital for sustaining market growth and meeting diverse consumer demands.
The competitive landscape of the APAC automotive infotainment systems market comprises established global players and regional competitors. Key players include Panasonic Corporation, Continental AG, Harman International Inc., and others. As technology advances and consumer demand for connectivity and personalization grows, the market is poised for further expansion. Integration of artificial intelligence (AI) to enhance the user experience, a focus on autonomous driving to facilitate passenger entertainment, and increased emphasis on cybersecurity to protect against data breaches are anticipated trends shaping the future outlook of the market.
Market Drivers:
Rising Demand for Comfort, Convenience, and Safety:
In the APAC region, consumers are placing increasing emphasis on cars that offer not only comfortable and convenient driving experiences but also enhanced safety features. For instance, entertainment systems address these demands by providing in-car entertainment options, navigation assistance, and connectivity features. Moreover, the integration of safety features such as rearview cameras, blind-spot monitoring, and parking sensors enhances driver awareness and contributes to overall road safety, aligning with the region’s growing focus on safer transportation solutions.
Increasing Smartphone Penetration and Flawless Supply of High-Speed Internet:
The widespread adoption of smartphones in the APAC region has significantly influenced consumer expectations regarding in-vehicle connectivity. In 2022, for instance, the smartphone adoption rate across the Asia-Pacific region reached 76 percent, marking an increase from 64 percent in 2019. By 2030, smartphone adoption in APAC is projected to reach over 90 percent. With a strong reliance on smartphones for communication and entertainment, consumers expect seamless integration of these features into their vehicles’ infotainment systems. For instance, the expansion of high-speed internet infrastructure across the region ensures reliable connectivity, enabling real-time access to services like online music streaming, navigation apps, and traffic updates directly through the vehicle’s infotainment system.
Growing Focus on Innovation and Design:
Automakers in the APAC region are increasingly prioritizing innovation and user-friendly design in their infotainment systems. Features such as voice recognition, intuitive touchscreen interfaces, and customizable displays are becoming standard, offering drivers a more engaging and personalized experience. Moreover, manufacturers are seamlessly integrating infotainment systems into the vehicle's dashboard design, ensuring both visual appeal and ergonomic functionality, thereby enhancing user interaction and the overall driving experience.
Government Initiatives Promoting Electric Vehicles (EVs) and Connected Cars:
Government initiatives across various APAC countries are driving the adoption of electric vehicles (EVs) and connected car technologies. Modern EVs often come equipped with advanced infotainment systems that provide essential information on battery status, charging station locations, and other EV-specific functionalities. Additionally, government support is fostering the development of connected car technologies, with infotainment systems serving as crucial components in enabling vehicle-to-everything (V2X) communication, potentially improving traffic management and safety on the region's roads.
Rising disposable income and evolving consumer preferences:
Increasing disposable income levels in the APAC region are empowering consumers to invest in vehicles equipped with advanced features, including sophisticated infotainment systems. Particularly among younger generations accustomed to a digital lifestyle, there's a growing expectation for cars to offer connectivity and entertainment features akin to smartphones and other digital devices. As a result, automakers are prioritizing the integration of cutting-edge infotainment technologies to cater to evolving consumer preferences and lifestyles.
Market Trends:
Rising Demand for Connectivity and Convenience:
Consumers in the Asia-Pacific region are increasingly seeking connected car experiences that offer seamless integration with smartphones, navigation apps, and entertainment platforms. This demand is fueling the adoption of advanced infotainment systems featuring touchscreen interfaces, voice control, and internet connectivity.
Focus on In-Vehicle Safety and Advanced Driver-Assistance Systems (ADAS):
Growing awareness of road safety is leading to a rise in ADAS features like lane departure warning and blind-spot monitoring. Integration of these functionalities with infotainment systems creates a centralized hub for information display and driver assistance, enhancing safety and the user experience. For example, by 2025, ADAS features will be ubiquitous, with 85% of vehicles produced globally featuring some level of driving automation.
Expansion into New Applications and Features:
Manufacturers are constantly innovating and expanding the capabilities of entertainment systems. This includes features like rear-seat entertainment systems, integration with ride-hailing services, and personalized user profiles. Additionally, the rise of electric vehicles (EVs) is creating demand for infotainment systems that can display charging station information and manage battery range anxiety.
Evolving Consumer Preferences for Personalization and User Experience:
Consumers are looking for entertainment systems that are intuitive, customizable, and cater to their individual preferences. This trend is driving the development of voice-activated interfaces, gesture recognition technology, and personalized content recommendations within the entertainment system. For instance, by 2030, futuristic infotainment systems like Mercedes-Benz’s MBUX system are expected to redefine our relationship with vehicles, making journeys more engaging, efficient, and enjoyable. The shift in consumer expectations has forced automakers to focus on designing vehicles and accompanying technologies that put the user at the center. Infotainment systems have transformed the way we interact with our vehicles, from integration with smartphones and smart home devices to voice-activated commands and real-time navigation updates. Data personalization in entertainment systems can provide several benefits, such as saving time and effort, improving comfort and convenience, enhancing safety and security, and increasing enjoyment and satisfaction.
Market Restraints and Challenges:
- Cost Considerations and Consumer Price Sensitivity:
- Integrating advanced infotainment systems often increases vehicle production costs, potentially leading to higher car prices.
- In price-sensitive markets within the Asia-Pacific region, consumers might prioritize affordability over advanced features, especially in budget and entry-level vehicle segments.
- Manufacturers will need to strike a balance between offering innovative features and maintaining competitive pricing strategies.
- Data privacy and security concerns:
- The growing integration of internet connectivity and advanced features raises concerns about data privacy and security.
- Consumers are increasingly wary of data breaches and unauthorized access to personal information collected through entertainment systems.
- Manufacturers need to prioritize robust data security measures and ensure user privacy through transparent data collection and usage practices.
- Lack of Standardized Regulations and Infrastructure:
- The Asia-Pacific region encompasses diverse economies with varying levels of technological infrastructure and regulatory frameworks for connected car technologies.
- The absence of standardized regulations across the region can create complexities for manufacturers in terms of product development, homologation, and data security compliance.
- Collaboration between governments and industry stakeholders is crucial to establishing harmonized regulations and supporting infrastructure development for connected car technologies.
- Skill Gap and Aftermarket Support:
- The growing sophistication of entertainment systems requires technicians with specialized skills for installation, maintenance, and troubleshooting.
- A potential skill gap in the automotive service sector could hinder the widespread adoption and user experience of advanced infotainment systems.
- Investments in training programs and upskilling initiatives for service personnel are essential to ensuring adequate aftermarket support for these complex systems.
- Driver distraction and safety concerns:
- The increasing complexity and functionality of infotainment systems can lead to driver distraction, potentially impacting road safety.
- Balancing the user experience with driver safety is crucial. Manufacturers must prioritize intuitive interface design, voice control options, and minimizing in-screen interaction while driving.
- Regulatory bodies might implement stricter guidelines to address driver distraction concerns and ensure the safe operation of vehicles with advanced infotainment systems.
Recent Developments:
- In February 2024, Harman International collaborated with Qualcomm to unveil the Ready Connect 5G TCU, a groundbreaking telematics control unit designed to revolutionize connected car technologies.
- In January 2023, Panasonic Corporation demonstrated a state-of-the-art virtualization security solution, setting a new benchmark for next-generation vehicle cockpit systems.
- In September 2023, Mitsubishi Electric Corporation selected BlackBerry to power its innovative in-vehicle system, Mitsubishi Electric FLEXConnectTM, a move that underscores the company’s dedication to enhancing in-cabin connectivity.
- At CES 2023, Continental AG presented its Curved Ultrawide Display, a technological marvel that promises to redefine the automotive display experience.
- In May 2023, Nvidia Corp. and MediaTek Inc. will partner on technology to power advanced vehicle infotainment systems that can stream video or games or interact with drivers through artificial intelligence, the companies said. Under the agreement, MediaTek will integrate the Nvidia graphic processing unit chiplet and Nvidia software into the system-on-chips it provides to automakers for infotainment displays, Reuters reported, citing the company's announcement at the Computex Technology Trade Show.
Segmentation Analysis:
Products:
- Audio-only systems: These basic systems offer functionalities like radio and CD players. While their market share is expected to decline due to consumer preference for more advanced features, they might remain relevant in entry-level vehicles.
- Display-only Systems: These systems integrate a display screen for navigation and basic infotainment functions. They are expected to witness moderate growth as they offer a balance between affordability and functionality.
- Embedded Systems: These advanced systems are tightly integrated with the vehicle's dashboard and offer a wide range of features, including navigation, connectivity, entertainment options, and even vehicle diagnostics. This segment is anticipated to experience the fastest growth due to increasing consumer demand for a connected and convenient in-car experience.
- Other Systems: This segment includes emerging technologies like head-up displays (HUDs) and augmented reality (AR) integration, which are expected to gain traction in the premium car segment in the later stages of the forecast period.
Segments:
By Product Type
- Audio Players
- Video Display Screen
- Navigation Unit
- Accessories
- Rear Seat Entertainments
- Speakers
- Others
By Channel Type
- OEM’s
- Aftermarket
By Vehicle Type
- Passenger Vehicle
- Compact Car
- Midsize
- SUV
- Luxury
- Commercial Vehicle
By Country
- China
- Japan
- India
- ASEAN
- Oceania
Key player:
- Harman International Industries, Inc. (U.S.)
- Visteon Corporation (U.S.)
- Aptiv PLC (U.S.)
- Alpine Electronics (Japan)
- Pioneer Corporation (Japan)
- Panasonic Corporation (Japan)
- Mitsubishi Electric Corporation (Japan)
- Continental AG (Germany)
- KenWood (Japan)
- Garmin Ltd. (U.S.)
- LG Electronics (South Korea)
- Forvia Faurecia (France)
Regional Analysis:
Japan and South Korea emerge as major players in the Asia Pacific automotive infotainment systems market, with well-established automotive industries and technological prowess. These countries are home to leading automotive manufacturers and technology giants, driving innovation and setting industry standards. Their significant contributions to research and development, coupled with a strong focus on consumer preferences, position them as key drivers of market growth and innovation within the region.
Additionally, China, with its burgeoning automotive market and rapidly expanding middle class, presents immense opportunities for the automotive infotainment systems market. As one of the largest automotive markets globally, China's demand for advanced in-vehicle technologies continues to rise. The country's strategic investments in electric vehicles (EVs), connected cars, and smart mobility solutions further bolster the demand for automotive infotainment systems. As a result, China's market share within the Asia-Pacific region is expected to grow substantially, contributing significantly to the overall market expansion.
Furthermore, emerging economies in Southeast Asia, such as India, Thailand, and Indonesia, are witnessing a surge in automotive sales and technological advancements. These countries represent untapped potential for the automotive infotainment systems market, driven by increasing urbanization, rising disposable incomes, and growing consumer demand for connected and technologically advanced vehicles. As these economies continue to develop and modernize their automotive sectors, they are poised to become key contributors to the Asia Pacific automotive infotainment systems market, further diversifying the regional landscape and strengthening its global influence.
Future Outlook:
- Rising Demand for Advanced Features: Consumers will increasingly seek vehicles with advanced infotainment systems offering features like integrated navigation, voice control, internet connectivity, and advanced smartphone integration (Apple CarPlay, Android Auto).
- Focus on In-Vehicle Entertainment: Manufacturers will prioritize in-vehicle entertainment capabilities, incorporating features like high-resolution displays, premium sound systems, and rear-seat entertainment options, to enhance the passenger experience.
- Technological Advancements: Continuous advancements in display technologies, artificial intelligence, and connectivity solutions will lead to more intuitive, personalized, and connected infotainment systems.
- Growth of Electric Vehicles (EVs): The rise of EVs will create demand for infotainment systems designed for electric mobility, potentially including features like charging station locators and energy consumption monitoring.
- Focus on Safety and Driver Awareness: Integration of advanced driver-assistance systems (ADAS) with infotainment systems will be crucial, promoting a balance between user engagement and driver safety.
- Expansion into Emerging Markets: Growth in Southeast Asia and developing economies within the region will present significant opportunities for infotainment system manufacturers and suppliers.
- Increased Focus on Customization: Automakers will personalize infotainment systems based on user preferences and driving habits, further enhancing the user experience.
- Focus on Cloud-Based Services: Cloud connectivity will enable access to real-time traffic updates, weather information, and personalized recommendations through infotainment systems.
- Growing Importance of Cybersecurity: Manufacturers will prioritize robust cybersecurity measures to protect entertainment systems from hacking and data breaches.
- Rise of Autonomous Vehicles: The development of autonomous vehicles will lead to a demand for advanced infotainment systems that can handle navigation, entertainment, and communication in a driverless environment.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Asia Pacific Automotive Infotainment Systems market between 2023 and 2032?
What factors are driving the growth of the Asia Pacific Automotive Infotainment Systems market?
Who are the major players in the Asia-Pacific Automotive Infotainment Systems market?
How is the availability of Asia Pacific Automotive Infotainment Systems expanding, and through what channels?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Asia Pacific Automotive Infotainment Systems Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Asia Pacific Automotive Infotainment Systems Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 2,099.13 million → forecast year: USD 3,758.77 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Asia Pacific Automotive Infotainment Systems Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Asia Pacific Automotive Infotainment Systems Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Asia Pacific Automotive Infotainment Systems Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Asia Pacific Automotive Infotainment Systems Market Drivers
- 3.3 Asia Pacific Automotive Infotainment Systems Market Restraints & Challenges
- 3.4 Asia Pacific Automotive Infotainment Systems Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Asia Pacific Automotive Infotainment Systems Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Asia Pacific Automotive Infotainment Systems Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Asia Pacific Automotive Infotainment Systems category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Asia Pacific Automotive Infotainment Systems Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Asia Pacific Automotive Infotainment Systems Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Asia Pacific Automotive Infotainment Systems market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Asia Pacific Automotive Infotainment Systems Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Asia Pacific Automotive Infotainment Systems Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Asia Pacific Automotive Infotainment Systems Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Asia Pacific Automotive Infotainment Systems (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Asia Pacific Automotive Infotainment Systems Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Asia Pacific Automotive Infotainment Systems Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Asia Pacific Automotive Infotainment Systems Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Asia Pacific Automotive Infotainment Systems Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Asia Pacific Automotive Infotainment Systems Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Asia Pacific Automotive Infotainment Systems Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Asia Pacific Automotive Infotainment Systems Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Asia Pacific Automotive Infotainment Systems Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Asia Pacific Automotive Infotainment Systems Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
