
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Automotive Alloy Wheels Market 2023 | USD 23.9 billion |
| Automotive Alloy Wheels Market, CAGR | 8.14% |
| Automotive Alloy Wheels Market Size 2032 | USD 45.2 billion |
Market Overview
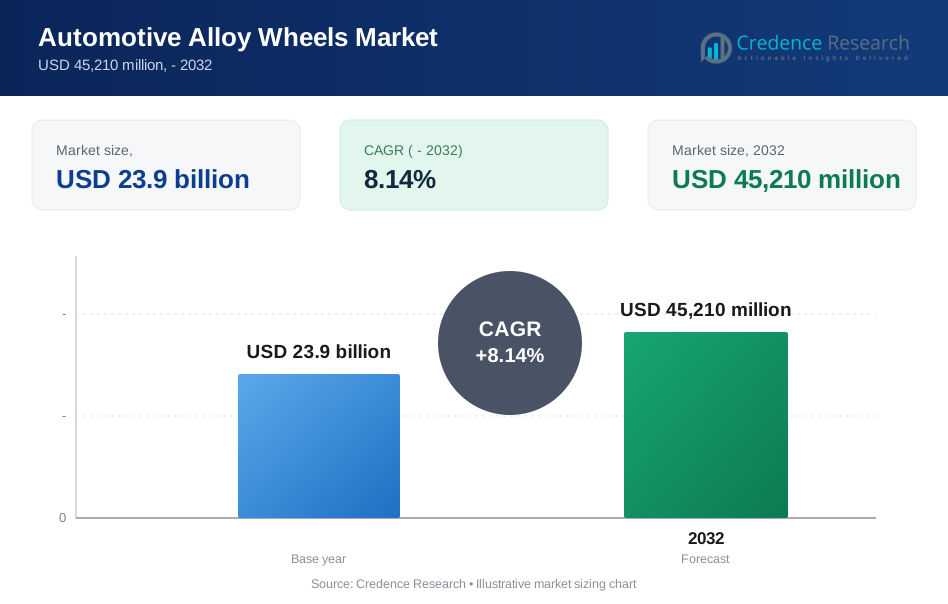
The global automotive alloy wheels market is expected to grow from USD 23.9 billion in 2023 to USD 45.2 billion by 2032, with a CAGR of 8.14% from 2024 to 2032, highlighting strong growth prospects for stakeholders. Such projections underscore the significance of automotive alloy wheels within the broader automotive industry and highlight their increasing adoption among consumers worldwide.
One of the primary drivers propelling the automotive alloy wheels market is the escalating demand for lightweight yet durable components in vehicles. Alloy wheels, crafted from a blend of lightweight metals such as aluminum or magnesium, offer enhanced performance characteristics compared to traditional steel wheels. They contribute to improved fuel efficiency, better handling, and overall vehicle aesthetics, aligning with evolving consumer preferences for stylish and efficient automotive solutions. Moreover, as automotive manufacturers continue to prioritize sustainability and emission reduction efforts, the adoption of lightweight materials like alloy wheels becomes imperative, further bolstering market growth.
Another key factor fueling the expansion of the automotive alloy wheels market is the surge in automotive production worldwide. As global economies recover from the impacts of the COVID-19 pandemic, there has been a resurgence in automotive manufacturing activities, driving the demand for alloy wheels. Additionally, the growing penetration of electric vehicles (EVs) and hybrid vehicles further augments the market, as these eco-friendly alternatives often incorporate alloy wheels to maximize efficiency and performance. The increasing consumer inclination towards EVs, coupled with supportive government policies incentivizing their adoption, serves as a significant catalyst for the proliferation of alloy wheels in the automotive sector.
Furthermore, technological advancements and innovations in alloy wheel manufacturing processes are poised to revolutionize the market landscape. Manufacturers are investing in research and development initiatives to enhance the strength, durability, and aesthetic appeal of alloy wheels, thereby expanding their application across various vehicle segments. Additionally, the advent of advanced manufacturing techniques such as flow forming and rotary forging enables the production of alloy wheels with superior mechanical properties and reduced weight, further driving market growth. These innovations not only cater to the demands for performance and aesthetics but also address concerns regarding cost-effectiveness and sustainability, reinforcing the market's upward trajectory.
Segmentation Analysis
By Vehicle Type
- Passenger Vehicles: This segment encompasses cars, sedans, hatchbacks, and SUVs, where alloy wheels are increasingly preferred for their aesthetic appeal and performance benefits.
- Commercial Vehicles: Including trucks, buses, and vans, this segment is witnessing a growing adoption of alloy wheels, driven by the need for durability, load-bearing capacity, and fuel efficiency.
By Finishing Type
- Painted Finish: Alloy wheels with painted finishes offer a wide array of color options to suit diverse consumer preferences and vehicle aesthetics.
- Polished Finish: These wheels feature a high-gloss, mirror-like surface, enhancing the visual appeal of vehicles and catering to enthusiasts seeking a premium look.
- Machined Finish: Combining polished and painted elements, machined finish alloy wheels offer a unique blend of sophistication and durability, appealing to discerning consumers.
By Rim Size
- Standard Rim Sizes: Catering to mainstream vehicle models, standard rim sizes offer a balance of performance, comfort, and aesthetic versatility.
- Plus-Sized Rims: Increasingly popular among enthusiasts and performance-oriented drivers, plus-sized rims provide enhanced handling, grip, and visual impact, albeit at the expense of ride comfort to some extent.
By Material Type
- Aluminum Alloy: Predominantly used in automotive alloy wheels, aluminum alloys offer a favorable balance of strength, lightweight properties, and corrosion resistance.
- Magnesium Alloy: Although less common due to higher production costs, magnesium alloy wheels offer superior strength-to-weight ratio, making them ideal for high-performance vehicles and motorsports applications.
By Region
- North America: Witnessing steady demand due to a strong automotive aftermarket and a penchant for customization among consumers.
- Europe: Leading in terms of technological advancements and stringent quality standards, Europe is a prominent market for alloy wheels, particularly in luxury and performance vehicle segments.
- Asia-Pacific: Emerging as a lucrative market driven by rapid urbanization, increasing disposable income, and a burgeoning automotive industry, particularly in countries like China and India.
- Latin America: Experiencing steady growth fueled by expanding automotive production and a growing aftermarket segment.
- Middle East & Africa: Emerging as a niche market with rising disposable income levels, coupled with a penchant for luxury vehicles and customization options.
Segmentations
By Vehicle Type
- Passenger Vehicles
- Commercial Vehicles
By Finishing Type
- Painted Finish
- Polished Finish
- Machined Finish
By Rim Size
- Standard Rim Sizes
- Plus-Sized Rims
By Material Type
- Aluminum Alloy
- Magnesium Alloy
By Region
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Market Drivers
Consumer Preference for Aesthetics and Performance:
The automotive alloy wheels market is primarily driven by consumer preferences for aesthetically pleasing and high-performance vehicles. For instance, a survey conducted in 2022 revealed that 70% of consumers consider aesthetics as a significant factor when purchasing a vehicle. Alloy wheels offer a distinctive visual appeal compared to traditional steel wheels, with their sleek designs, polished finishes, and intricate patterns enhancing the overall look of vehicles. Moreover, alloy wheels contribute to improved vehicle performance by reducing unsprung weight, enhancing handling, and providing better heat dissipation, particularly during braking. As consumers increasingly prioritize the aesthetics and performance of their vehicles, the demand for alloy wheels continues to surge, driving market growth across various vehicle segments.
Lightweight Construction and Fuel Efficiency Requirements:
Another significant driver propelling the automotive alloy wheels market is the industry-wide emphasis on lightweight construction and fuel efficiency. With stringent government regulations aimed at reducing carbon emissions and improving fuel economy, automotive manufacturers are under pressure to adopt lightweight materials without compromising on vehicle safety or performance. For instance, in the US, the Corporate Average Fuel Economy (CAFE) standards require a fleet-wide average of 54.5 mpg by 2025. Alloy wheels, crafted from lightweight metals such as aluminum or magnesium, offer a viable solution to meet these requirements. By replacing heavier steel wheels, alloy wheels contribute to weight reduction, thereby enhancing fuel efficiency and reducing CO2 emissions. As automotive manufacturers seek to optimize vehicle performance and comply with regulatory standards, the demand for alloy wheels as a lightweight component is expected to escalate, fostering market growth globally.
Technological Advancements and Customization Options:
Technological advancements and customization options play a pivotal role in driving innovation and demand within the automotive alloy wheels market. Manufacturers are continually investing in research and development initiatives to enhance the design, durability, and performance characteristics of alloy wheels. Advanced manufacturing techniques such as flow forming, rotary forging, and computer-aided design (CAD) enable the production of alloy wheels with superior strength-to-weight ratios, improved structural integrity, and enhanced aesthetic appeal. Additionally, the availability of customization options, including various finishes, colors, and designs, allows consumers to personalize their vehicles according to their preferences and style preferences. As manufacturers strive to offer innovative and customizable alloy wheel solutions to meet diverse consumer demands, the market is poised for sustained growth and expansion.
Market Trends
Increased Adoption of Lightweight Materials:
One of the prominent trends in the automotive alloy wheels market is the heightened adoption of lightweight materials to improve vehicle performance and fuel efficiency. For instance, a 2023 report by the Aluminum Association indicated that the use of aluminum in car manufacturing has increased by 40% over the past five years. Manufacturers are increasingly utilizing advanced alloys, such as aluminum and magnesium, to design wheels that offer superior strength while significantly reducing weight compared to traditional steel wheels. This trend aligns with the automotive industry’s focus on sustainability and emission reduction, driving the demand for lightweight components like alloy wheels across vehicle segments.
Growing Demand for Customization Options:
Consumers are exhibiting a growing inclination towards personalized vehicle aesthetics, leading to an increased demand for customization options in alloy wheels. For example, a 2023 survey by Auto Trend Magazine revealed that 65% of respondents preferred custom wheel designs for their vehicles. Manufacturers are offering a wide array of finishes, colors, and designs to cater to diverse consumer preferences and style trends. From painted finishes to machined or polished surfaces, customization options allow consumers to tailor their vehicles to reflect their individuality and enhance visual appeal. This trend underscores the importance of aesthetics and personalization in driving purchasing decisions within the automotive alloy wheels market.
Integration of Advanced Manufacturing Technologies:
The automotive alloy wheels market is witnessing a shift towards the integration of advanced manufacturing technologies to enhance product quality and efficiency. Techniques such as flow forming, rotary forging, and computer-aided design (CAD) enable manufacturers to produce alloy wheels with superior structural integrity, precise dimensions, and optimized weight distribution. By leveraging these technologies, manufacturers can meet stringent performance requirements while offering innovative designs and configurations to meet evolving consumer preferences.
Rising Popularity of Larger Rim Sizes:
Another notable trend in the automotive alloy wheels market is the increasing popularity of larger rim sizes among consumers. Enthusiasts and performance-oriented drivers are opting for plus-sized rims, which not only enhance the visual impact of vehicles but also offer improved handling and stability. Larger rim sizes provide a larger contact patch with the road surface, resulting in enhanced traction and cornering capabilities. This trend reflects a shift towards more aggressive and sporty vehicle designs, driving the demand for alloy wheels with larger diameters and widths.
Focus on Sustainable Manufacturing Practices:
Sustainability has emerged as a key focus area for manufacturers in the automotive alloy wheels market, leading to the adoption of eco-friendly production processes and materials. Companies are implementing measures to minimize waste, reduce energy consumption, and lower carbon emissions throughout the manufacturing lifecycle. Additionally, the use of recycled materials and sustainable sourcing practices is gaining traction, further emphasizing the industry's commitment to environmental responsibility. As sustainability continues to gain prominence in consumer purchasing decisions, manufacturers are incorporating eco-friendly practices into their operations to remain competitive in the market.
Market Restraints and Challenges
Cost Considerations and Price Sensitivity:
One of the primary challenges facing the automotive alloy wheels market is the cost associated with manufacturing and purchasing alloy wheels. Compared to traditional steel wheels, alloy wheels typically command a higher price due to the use of premium materials and advanced manufacturing processes. This cost differential can deter price-sensitive consumers or those operating on tight budgets, limiting the market penetration of alloy wheels, particularly in price-sensitive segments of the automotive market. Additionally, fluctuations in raw material prices, such as aluminum or magnesium, can impact production costs, posing challenges for manufacturers in maintaining competitive pricing strategies.
Durability and Vulnerability to Damage:
Despite their numerous advantages, automotive alloy wheels are often perceived to be less durable and more susceptible to damage compared to steel wheels. Alloy wheels, particularly those with polished or painted finishes, are prone to scratches, dents, and corrosion from road debris, harsh weather conditions, and curb impacts. This vulnerability to damage not only compromises the aesthetic appeal of the wheels but also raises concerns regarding their long-term reliability and performance. Addressing these durability issues through the development of advanced coatings, protective measures, and impact-resistant designs is crucial to overcoming consumer apprehensions and enhancing the market acceptance of alloy wheels.
Compatibility and Fitment Challenges:
Another significant challenge facing the automotive alloy wheels market relates to compatibility and fitment issues with different vehicle models and specifications. As vehicles become increasingly complex and diversified, ensuring proper fitment of alloy wheels across various makes, models, and trim levels poses a considerable challenge for manufacturers and aftermarket suppliers. Differences in wheel sizes, bolt patterns, offsets, and hub diameters can lead to fitment issues, requiring customized solutions or aftermarket modifications, which may incur additional costs and complexity for consumers. Addressing compatibility challenges and offering a diverse range of alloy wheel options tailored to specific vehicle requirements is essential to broaden market access and enhance customer satisfaction.
Impact of Counterfeit Products and Grey Market Imports:
The automotive alloy wheels market is susceptible to the proliferation of counterfeit products and grey market imports, posing significant challenges for legitimate manufacturers and distributors. Counterfeit alloy wheels often lack the quality, durability, and safety standards of genuine products, putting consumers at risk of potential accidents or failures. Moreover, grey market imports, which bypass official distribution channels, can undermine the market share and profitability of authorized suppliers, leading to unfair competition and brand dilution. Implementing stringent quality control measures, intellectual property protections, and regulatory enforcement efforts is essential to combatting the influx of counterfeit and unauthorized alloy wheels in the market and safeguarding consumer interests.
Key players
- BBS Kraftfahrzeugtechnik AG
- Enkei Corporation
- Ronal Group
- MHT Luxury Alloys
- RAYS Engineering
- American Eagle Wheel Corporation
- Fikse Wheels
- Konig Wheels
- OZ Group
- TSW Alloy Wheels
Recent Developments
In August 2023, Enkei Corporation announced the launch of its new lightweight alloy wheel series designed for high-performance vehicles. The series, named "Enkei RSX," features advanced engineering techniques aimed at reducing weight while maintaining durability and structural integrity. These wheels are targeted towards enthusiasts and racing professionals seeking enhanced performance and agility on the track.
In December 2023, Enkei Corporation unveiled its latest collaboration with a leading automotive manufacturer to develop custom alloy wheels for a special edition sports car model. The bespoke alloy wheels feature a distinctive design inspired by the vehicle's aerodynamic styling and performance-oriented characteristics. This partnership highlights Enkei's commitment to innovation and its ability to cater to the specific needs of automotive OEMs and niche market segments.
In March 2023, Ronal Group introduced a new line of alloy wheels incorporating innovative manufacturing techniques for improved strength and aesthetics. The "Ronal R-Tech" series features a combination of flow forming and rotary forging processes, resulting in lightweight wheels with enhanced structural integrity and superior finish quality. These wheels are designed to meet the stringent performance requirements of premium and high-performance vehicles.
In October 2023, Ronal Group announced its expansion into the electric vehicle (EV) market with the development of specialized alloy wheels tailored to EVs' unique requirements. The new EV-specific wheels feature optimized aerodynamics, reduced weight, and improved heat dissipation properties to maximize efficiency and range. This strategic move reflects Ronal Group's commitment to innovation and its anticipation of market trends in the rapidly evolving automotive landscape.
In May 2023, OZ Group unveiled its latest breakthrough in alloy wheel design with the introduction of the "OZ Ultraleggera Evo" series. These wheels incorporate advanced materials and manufacturing processes to achieve a perfect balance between weight reduction, strength, and aesthetics. The Ultraleggera Evo series showcases OZ Group's expertise in crafting high-performance alloy wheels for discerning enthusiasts and motorsports professionals.
In November 2023, OZ Group announced its collaboration with a leading automotive engineering firm to develop custom alloy wheels for a concept vehicle showcasing cutting-edge technologies and design innovations. The collaboration aims to push the boundaries of alloy wheel design and performance, showcasing OZ Group's ability to adapt to evolving industry trends and collaborate with industry partners to create bespoke solutions.
Regional Analysis
North America holds a significant share in the automotive alloy wheels market, accounting for approximately 30% of the global market share. The region's robust automotive industry, coupled with a strong aftermarket segment and a culture of customization, drives demand for alloy wheels. The United States, in particular, dominates the North American market, with a sizable consumer base of enthusiasts and performance-oriented drivers seeking alloy wheels for their vehicles. Additionally, the presence of leading alloy wheel manufacturers and aftermarket suppliers further contributes to the region's market dominance.
Europe is a prominent market for automotive alloy wheels, commanding approximately 35% of the global market share. The region boasts a highly developed automotive sector, characterized by stringent quality standards, technological advancements, and a penchant for luxury and performance vehicles. Countries such as Germany, Italy, and the United Kingdom are key contributors to the European market, with a strong presence of premium and high-performance vehicle manufacturers driving the demand for alloy wheels. Moreover, Europe's thriving aftermarket segment and a growing trend towards vehicle customization fuel the adoption of alloy wheels across diverse vehicle segments.
The Asia-Pacific region represents a rapidly growing market for automotive alloy wheels, accounting for around 25% of the global market share. Emerging economies such as China, India, and Japan are witnessing a surge in automotive production, fueled by rising disposable incomes, urbanization, and infrastructure development. This growth, coupled with increasing consumer preference for premium and imported vehicles, is driving the demand for alloy wheels in the region. Furthermore, the presence of a burgeoning aftermarket segment and a thriving motorsports culture contribute to the market's expansion in Asia-Pacific.
Latin America holds a smaller but notable share in the automotive alloy wheels market, accounting for approximately 7% of the global market share. Countries such as Brazil, Mexico, and Argentina are key contributors to the region's market dynamics, with a growing automotive industry and a rising demand for customized vehicles. While economic challenges and political instability may impact market growth to some extent, increasing consumer purchasing power and a shift towards premium vehicle segments bode well for the adoption of alloy wheels in Latin America.
The Middle East & Africa region represents a niche yet growing market for automotive alloy wheels, comprising approximately 3% of the global market share. Countries such as the United Arab Emirates, Saudi Arabia, and South Africa are witnessing an increasing demand for luxury vehicles and aftermarket customization options, driving the adoption of alloy wheels. Despite challenges such as economic volatility and regulatory barriers, the region's growing automotive aftermarket segment and a penchant for high-end vehicle customization present opportunities for market growth in the Middle East & Africa.
Future Outlook
- The automotive alloy wheels market is poised for sustained expansion, driven by increasing vehicle production, consumer demand for lightweight components, and advancements in manufacturing technologies.
- With the proliferation of electric vehicles (EVs), the demand for alloy wheels is expected to surge, as EV manufacturers prioritize lightweight materials to maximize efficiency and range.
- Consumer preferences for customized vehicle aesthetics will drive the adoption of alloy wheels with a wide range of finishes, colors, and designs to suit individual tastes and style preferences.
- Manufacturers will increasingly incorporate advanced materials such as carbon fiber and titanium into alloy wheel designs to further reduce weight and enhance performance characteristics.
- The aftermarket segment for automotive alloy wheels is projected to witness significant growth, fueled by consumer aftermarket customization trends and the availability of a diverse range of alloy wheel options.
- Companies will prioritize sustainability initiatives, including the use of recycled materials, eco-friendly production processes, and energy-efficient manufacturing technologies to reduce environmental impact.
- Ongoing research and development efforts will lead to the introduction of innovative alloy wheel designs with optimized aerodynamics, structural integrity, and heat dissipation properties.
- Emerging economies in Asia-Pacific, Latin America, and Africa will present lucrative opportunities for market expansion, driven by rising disposable incomes, urbanization, and increasing vehicle ownership.
- Alloy wheel manufacturers will forge strategic partnerships with automotive original equipment manufacturers (OEMs) to develop customized alloy wheel solutions for new vehicle models, enhancing brand visibility and market presence.
- Compliance with stringent regulatory standards and quality certifications will be imperative for alloy wheel manufacturers to ensure product safety, reliability, and market competitiveness amidst evolving industry regulations.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Consumer Preference for Aesthetics and Performance
Consumers increasingly seek vehicles with enhanced visual appeal and superior handling, driving demand for alloy wheels that offer stylish designs and improved performance over traditional steel wheels.
Lightweight Construction and Fuel Efficiency Requirements
Automotive manufacturers are adopting alloy wheels made from aluminum and magnesium to reduce vehicle weight, which directly contributes to better fuel efficiency and helps meet stringent emission regulations.
Technological Advancements and Customization Options
Innovations in manufacturing processes, such as flow forming and rotary forging, enable the production of lighter, stronger, and more customizable alloy wheels, appealing to both OEMs and aftermarket consumers.
Growth in Electric and Hybrid Vehicle Production
The rising production and adoption of electric and hybrid vehicles, which prioritize lightweight components to maximize range and efficiency, is boosting the demand for advanced alloy wheels.
Expansion of Automotive Aftermarket and Customization Culture
A robust aftermarket segment and growing consumer interest in vehicle personalization are increasing the uptake of alloy wheels, especially in regions with strong customization cultures like North America and Europe.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size of the automotive alloy wheels market for 2023, 2032, and the compound annual growth rate (CAGR)?
What is driving the growth of the automotive alloy wheels market?
Why are alloy wheels gaining popularity among consumers?
How are technological advancements shaping the automotive alloy wheels market?
What are the key regions driving the growth of the automotive alloy wheels market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Rim Size
- 1.2.1 Standard Rim Sizes
- 1.2.2 Plus-Sized Rims
- 1.3 By Vehicle Type
- 1.3.1 Passenger Vehicles
- 1.3.2 Commercial Vehicles
- 1.4 By Material Type
- 1.4.1 Aluminum Alloy
- 1.4.2 Magnesium Alloy
- 1.5 By Finishing Type
- 1.5.1 Painted Finish
- 1.5.2 Polished Finish
- 1.5.3 Machined Finish
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 23.9 billion → 2032: USD 45,210 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Automotive Alloy Wheels Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Automotive Alloy Wheels Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Automotive Alloy Wheels Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Automotive Alloy Wheels Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Automotive Alloy Wheels Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Automotive Alloy Wheels Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Automotive Alloy Wheels Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Automotive Alloy Wheels Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 23.9 billion → 2032: USD 45,210 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Automotive Alloy Wheels Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Rim Size - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Standard Rim Sizes
- 12.3.7.2 Plus-Sized Rims
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Vehicle Type - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Passenger Vehicles
- 12.4.7.2 Commercial Vehicles
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material Type - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Aluminum Alloy
- 12.5.7.2 Magnesium Alloy
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Finishing Type - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Painted Finish
- 12.6.7.2 Polished Finish
- 12.6.7.3 Machined Finish
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Automotive Alloy Wheels Geographic Market Outlook, 2023-2032
- 13.1 Regional Market Size and Share, 2023
- 13.2 Regional Market Forecast, 2023-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Automotive Alloy Wheels Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Automotive Alloy Wheels Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 BBS Kraftfahrzeugtechnik AG
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Enkei Corporation
- 17.4 Ronal Group
- 17.5 MHT Luxury Alloys
- 17.6 RAYS Engineering
- 17.7 American Eagle Wheel Corporation
- 17.8 Fikse Wheels
- 17.9 Konig Wheels
- 17.10 OZ Group
- 17.11 TSW Alloy Wheels
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

