
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Automotive Steel Wheels Market 2023 | USD 33.4 billion |
| Automotive Steel Wheels Market, CAGR | 5.8% |
| Automotive Steel Wheels Market Size 2032 | USD 53.1 billion |
Market Overview
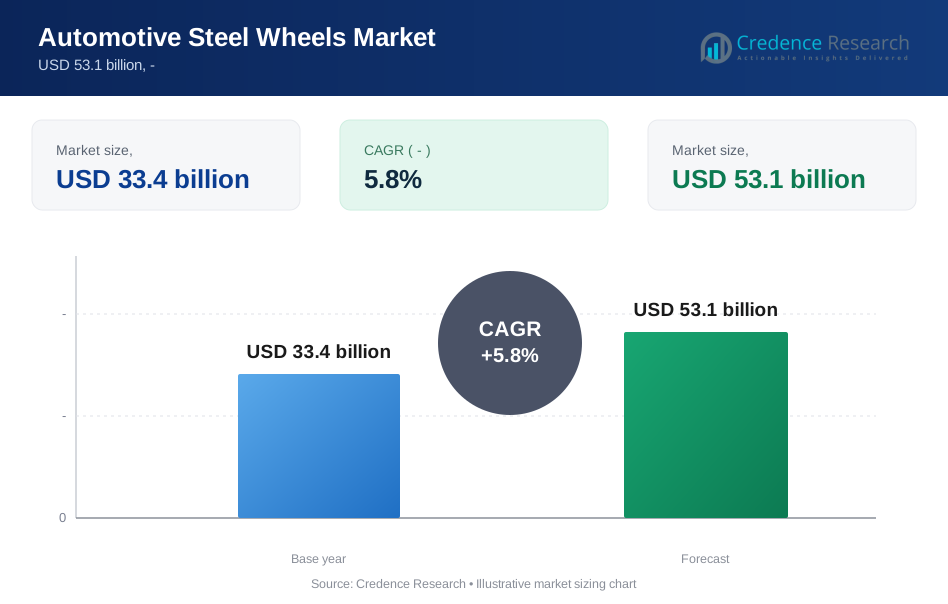
The global Automotive Steel Wheels Market is set to expand from USD 33.4 billion in 2023 to USD 53.1 billion by 2032, at a CAGR of 5.8% between 2024 and 2032, showcasing significant growth potential.
The automotive steel wheels market plays a vital role in the automotive industry, providing durable and cost-effective solutions for vehicle manufacturers and consumers alike. As the automotive sector continues to evolve, driven by technological advancements and shifting consumer preferences, the demand for steel wheels remains resilient, underpinned by their reliability, strength, and affordability.
One of the key drivers propelling the growth of the automotive steel wheels market is the increasing production and sales of automobiles worldwide. With rising urbanization, expanding middle-class populations, and improving disposable incomes in emerging economies, there has been a surge in demand for passenger and commercial vehicles. Steel wheels, known for their robustness and suitability for various road conditions, are preferred by automotive manufacturers seeking cost-effective solutions without compromising on quality. Additionally, the automotive aftermarket segment contributes significantly to the demand for steel wheels, driven by the need for replacements and upgrades, further fueling market growth.
Moreover, stringent regulations pertaining to vehicle safety and emissions are bolstering the adoption of lightweight materials in automotive manufacturing. While aluminum and alloy wheels have gained popularity owing to their lighter weight, steel wheels remain a preferred choice for heavy-duty applications and commercial vehicles, where durability and load-bearing capacity are paramount. Manufacturers are innovating in terms of design and production processes to enhance the performance and aesthetics of steel wheels, catering to the evolving needs of customers and regulatory requirements. Furthermore, the advent of electric vehicles (EVs) is anticipated to create new opportunities for the automotive steel wheels market, as EVs require wheels capable of withstanding higher torque and weight, making steel wheels a viable option.
However, the automotive steel wheels market faces challenges such as competition from alternative materials and fluctuating raw material prices. The availability of lightweight materials like aluminum poses a threat to the market share of steel wheels, particularly in the passenger vehicle segment where weight reduction is a priority for fuel efficiency and performance. Additionally, fluctuations in steel prices influenced by factors such as trade policies, geopolitical tensions, and supply chain disruptions can impact the profitability of manufacturers and influence pricing strategies. Despite these challenges, strategic collaborations, technological advancements, and product innovations are expected to sustain the growth momentum of the automotive steel wheels market, ensuring its relevance in the evolving automotive landscape.
Segmentation Analysis
By Rim Size
- Small Rim Size (Below 16 inches): This segment primarily caters to compact and subcompact vehicles, where cost-effectiveness and durability are key considerations. Small rim sizes are popular in urban areas with congested traffic conditions and limited parking space.
- Medium Rim Size (16 to 20 inches): Medium-sized rims are commonly found in mid-size sedans, SUVs, and light trucks. These vehicles require wheels that balance performance, comfort, and load-bearing capacity, making steel wheels a suitable choice.
- Large Rim Size (Above 20 inches): Large rims are prevalent in luxury vehicles, high-performance cars, and heavy-duty trucks. While alloy wheels dominate this segment for their aesthetics and weight advantages, steel wheels remain relevant for their strength and resilience, particularly in commercial applications.
By Vehicle Type
- Passenger Vehicles: This segment encompasses cars, SUVs, and vans used for personal transportation. Passenger vehicles account for a significant share of the automotive steel wheels market, driven by the need for durable and cost-effective wheel solutions.
- Commercial Vehicles: Commercial vehicles such as trucks, buses, and trailers rely heavily on steel wheels due to their ability to withstand heavy loads and rough road conditions. The commercial vehicle segment presents lucrative opportunities for steel wheel manufacturers, especially in emerging economies with growing logistics and transportation sectors.
By Application
- OEM (Original Equipment Manufacturers): Steel wheels are extensively used as original equipment by vehicle manufacturers worldwide. OEMs collaborate with steel wheel suppliers to ensure compatibility, performance, and regulatory compliance, driving demand in this segment.
- Aftermarket: The aftermarket segment includes replacement and upgrade sales for steel wheels. Consumers opt for aftermarket steel wheels for reasons such as customization, maintenance, or damage replacement. The aftermarket segment offers a diverse range of sizes and designs to cater to varying customer preferences.
By End User
- Automotive Manufacturers: End users in this segment are vehicle manufacturers who integrate steel wheels into their production lines. Automotive manufacturers prioritize factors such as quality, cost-effectiveness, and supply chain reliability when selecting steel wheel suppliers.
- Individual Consumers: Individual consumers purchase steel wheels either as part of vehicle purchase or for aftermarket customization. Factors influencing their buying decisions include price, durability, aesthetics, and brand reputation.
Regional Analysis
- North America: Witnessing steady demand due to the robust automotive industry and preference for durable steel wheels in commercial vehicles.
- Europe: Strong market driven by stringent safety regulations favoring steel wheels' reliability and cost-effectiveness.
- Asia Pacific: Largest market share attributed to rapid urbanization, increasing vehicle production, and growing aftermarket demand.
- Latin America: Emerging market with expanding automotive sector, driving demand for affordable steel wheels.
- Middle East & Africa: Growing adoption fueled by infrastructure development and rising commercial vehicle sales, particularly in construction and logistics sectors.
Segments
By Rim Size
- Small Rim Size (Below 16 inches)
- Medium Rim Size (16 to 20 inches)
- Large Rim Size (Above 20 inches)
By Vehicle Type
- Passenger Vehicles
- Commercial Vehicles
By Application
- OEM (Original Equipment Manufacturers)
- Aftermarket
By End User
- Automotive Manufacturers
- Individual Consumers
By Region
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Market Drivers
The robust demand for automobiles globally serves as a primary driver. For instance, global new light vehicle sales in 2024 are expected to see a 2.8% increase year-over-year. With urbanization on the rise and burgeoning middle-class populations, particularly in emerging economies, there has been a steady uptick in vehicle sales. The urban population in emerging market and developing economies (EMDEs) nearly doubled from 27% to 52%. The middle-class market in these economies is projected to grow at annual rates of 6 percent or more. Steel wheels, renowned for their durability, strength, and cost-effectiveness, are preferred by both automotive manufacturers and consumers. This preference is especially notable in commercial vehicles and heavy-duty applications, where the reliability and load-bearing capacity of steel wheels are indispensable. As the automotive sector continues to expand, fueled by economic growth and technological advancements, the demand for steel wheels remains steady, ensuring sustained market growth.
Secondly, stringent regulations governing vehicle safety and emissions act as catalysts for the automotive steel wheels market. Governments worldwide are increasingly imposing stringent standards to enhance road safety and reduce environmental impact. In this regulatory landscape, steel wheels offer a compelling solution, meeting stringent safety requirements while being environmentally sustainable. Moreover, steel wheels are known for their recyclability, aligning with the automotive industry’s sustainability goals. As automakers strive to comply with regulatory mandates and consumer preferences for eco-friendly solutions, the demand for steel wheels is further bolstered. Additionally, the automotive aftermarket segment significantly contributes to the demand for steel wheels, driven by the need for replacements and upgrades. This aftermarket demand is fueled by factors such as vehicle aging, wear and tear, and customization trends, ensuring a consistent market for automotive steel wheels.
Market Trends
Lightweight Design:
While steel wheels are traditionally known for their robustness and durability, there’s a growing trend towards lightweight design. Manufacturers are leveraging advanced engineering techniques and materials to reduce the weight of steel wheels without compromising strength and performance. For instance, one study found that among six different wheel designs, the best design exhibited a lighter weight of 27.192 kg. This trend aligns with the automotive industry’s emphasis on fuel efficiency and emissions reduction, particularly in passenger vehicles.
Advanced Coating Technologies:
Coating technologies play a crucial role in enhancing the durability and aesthetics of steel wheels. Current trends include the adoption of advanced coating methods such as powder coating and electroplating, which offer superior corrosion resistance and aesthetic appeal. These coatings not only protect steel wheels from environmental factors but also contribute to extended service life and enhanced visual appeal, catering to consumer preferences for stylish yet durable automotive components.
Customization Options:
Personalization and customization are gaining prominence in the automotive sector, extending to steel wheels as well. Manufacturers are offering a wide range of customization options, including color choices, finishes, and unique designs, to cater to individual consumer preferences. This trend is particularly evident in the aftermarket segment, where consumers seek to differentiate their vehicles and express their personal style through customized steel wheels.
Integration of Advanced Technologies:
The integration of advanced technologies is reshaping the automotive steel wheels market. Innovations such as sensor integration for tire pressure monitoring systems (TPMS) and advanced manufacturing processes like laser cutting and robotic welding are enhancing the performance, safety, and quality of steel wheels. These technological advancements not only improve the functionality of steel wheels but also enable manufacturers to meet stringent regulatory requirements and consumer demands for safety and reliability.
Sustainable Practices:
Sustainability is becoming increasingly important in the automotive industry, driving trends towards eco-friendly manufacturing processes and materials. In the automotive steel wheels market, manufacturers are adopting sustainable practices such as recycling and reducing energy consumption in production processes. Additionally, the recyclability of steel makes it an attractive option for environmentally conscious consumers and automakers, further driving the adoption of steel wheels in the automotive sector.
Growing Market Penetration in Emerging Economies:
Emerging economies represent a significant growth opportunity for the automotive steel wheels market. Rapid urbanization, increasing disposable incomes, and infrastructure development initiatives in countries across Asia Pacific, Latin America, and Africa are fueling demand for automobiles, including vehicles equipped with steel wheels. As a result, manufacturers are expanding their presence and production capacity in these regions to capitalize on the growing market potential.
Market Restraints and Challenges
Despite its promising growth prospects, the Automotive Steel Wheels Market faces several key restraints and challenges that impede its expansion and adaptation to evolving industry dynamics. One significant challenge is the growing competition from alternative materials such as aluminum and alloy. These materials offer advantages such as lighter weight, which contributes to improved fuel efficiency and performance, particularly in passenger vehicles. As automotive manufacturers increasingly prioritize weight reduction to meet stringent emissions standards and consumer demands for efficiency, steel wheels face pressure to demonstrate their competitiveness in terms of weight, without compromising on durability and cost-effectiveness.
Fluctuating raw material prices represent another critical restraint for the automotive steel wheels market. Steel prices are subject to volatility influenced by various factors such as global economic conditions, trade policies, and supply chain disruptions. These fluctuations can significantly impact the profitability of steel wheel manufacturers, leading to challenges in pricing strategies and supply chain management. Moreover, geopolitical tensions and trade disputes can exacerbate uncertainty in the steel market, creating challenges for manufacturers in forecasting demand and managing production costs effectively.
Regulatory compliance poses a persistent challenge for the automotive steel wheels market, particularly concerning safety and emissions standards. While steel wheels are known for their durability and reliability, stringent regulations governing vehicle safety require continuous innovation and adaptation to ensure compliance. Additionally, evolving emissions regulations drive demand for lightweight materials, posing a challenge for steel wheels to compete with alternative materials in passenger vehicles. Manufacturers must invest in research and development to enhance the performance and sustainability of steel wheels while meeting regulatory requirements, which can entail substantial costs and resource allocation.
Furthermore, the commoditization of steel wheels presents a challenge for manufacturers in differentiating their products and maintaining profitability. As steel wheels are perceived as standardized components, manufacturers face pressure to compete on price, leading to margin compression and pricing wars. To address this challenge, manufacturers must focus on value-added features such as advanced coatings, customization options, and technological innovations to differentiate their offerings and capture market share. Additionally, market saturation in mature economies poses challenges for growth, prompting manufacturers to explore opportunities in emerging markets and diversify their product portfolios to sustain competitiveness and mitigate risks associated with market concentration.
Key players
- Accuride Corporation
- Borbet GmbH
- CITIC Dicastal Co., Ltd.
- Enkei Corporation
- IOCHPE-MAXION S.A.
- Steel Strips Wheels Ltd.
- Superior Industries International, Inc.
- TOPY Industries Limited
- Wheels India Limited
- Maxion Wheels
Recent Developments
On September 15, 2023, Maxion Wheels announced the inauguration of its new aluminum wheel manufacturing plant in Limeira, Brazil. This state-of-the-art facility is strategically positioned to meet the growing demand for lightweight wheels in the automotive industry, catering to both domestic and international markets. With an investment of USD 50 million, the plant is equipped with advanced production technologies and is expected to significantly enhance Maxion Wheels' production capacity and operational efficiency. The expansion underscores Maxion Wheels' commitment to innovation and sustainability, as aluminum wheels gain prominence in the automotive market due to their weight-saving advantages.
On December 5, 2023, IOCHPE-MAXION S.A. announced a strategic partnership with a leading technology company to develop next-generation steel wheels with integrated sensor capabilities. This collaboration aims to leverage advanced sensor technologies to enhance the functionality and safety features of steel wheels, particularly in commercial vehicles and heavy-duty applications. By integrating sensors for tire pressure monitoring systems (TPMS) and other vehicle diagnostics, IOCHPE-MAXION S.A. aims to provide innovative solutions that improve vehicle performance, reduce maintenance costs, and enhance overall safety standards. The partnership highlights IOCHPE-MAXION S.A.'s commitment to driving technological innovation and meeting the evolving needs of the automotive industry.
On April 20, 2023, Steel Strips Wheels Ltd. announced the acquisition of a majority stake in a leading alloy wheel manufacturing company based in Europe. This strategic investment is part of Steel Strips Wheels Ltd.'s expansion strategy to diversify its product portfolio and strengthen its presence in the global automotive market. With this acquisition, Steel Strips Wheels Ltd. aims to leverage synergies between steel and alloy wheel manufacturing capabilities, tapping into new market segments and enhancing its competitive positioning. The move underscores Steel Strips Wheels Ltd.'s commitment to growth and innovation, as it continues to explore opportunities for strategic partnerships and acquisitions in the automotive industry.
Regional Analysis
North America holds a significant market share percentage, accounting for approximately 25% of the global automotive steel wheels market. The region boasts a robust automotive industry, driven by strong demand for commercial vehicles and trucks. Steel wheels are preferred in this region for their durability and suitability for heavy-duty applications. Additionally, stringent safety regulations favor the use of steel wheels, contributing to their dominance in the market. Moreover, the presence of leading automotive manufacturers and technological advancements further bolster the demand for automotive steel wheels in North America.
Europe commands a substantial market share percentage, accounting for approximately 30% of the global automotive steel wheels market. The region's automotive sector is characterized by a preference for steel wheels due to their reliability and cost-effectiveness. Strict safety standards and regulations favor the use of steel wheels in both passenger and commercial vehicles. Furthermore, Europe's focus on sustainability aligns with the recyclability of steel, further driving its adoption in the automotive industry. With the presence of established automotive OEMs and a growing aftermarket segment, Europe remains a significant market for automotive steel wheels.
Asia Pacific emerges as the largest market share holder, commanding approximately 45% of the global automotive steel wheels market. The region's dominance can be attributed to rapid industrialization, urbanization, and the expanding automotive sector. Countries like China and India exhibit robust demand for steel wheels, driven by increasing vehicle production and aftermarket sales. Moreover, the preference for durable and cost-effective solutions in commercial vehicles and two-wheelers further boosts the demand for automotive steel wheels in Asia Pacific. With growing investments in infrastructure and manufacturing capabilities, the region is poised for continued growth in the automotive steel wheels market.
Latin America holds a smaller yet significant market share percentage, contributing approximately 10% to the global automotive steel wheels market. The region's automotive industry relies on steel wheels for their affordability and reliability, particularly in light of challenging road conditions and terrain. As the automotive sector in Latin America continues to expand, driven by economic growth and urbanization, the demand for automotive steel wheels is expected to remain steady.
The Middle East & Africa region accounts for a modest share of the global automotive steel wheels market, approximately 5%. However, the region's growing investments in infrastructure and transportation drive the demand for commercial vehicles, where steel wheels are preferred for their durability and load-bearing capacity. Additionally, stringent safety regulations and the presence of established automotive manufacturers contribute to the steady demand for automotive steel wheels in the Middle East & Africa.
Future Outlook
- Continued innovation in manufacturing processes and materials will enhance the performance and aesthetics of automotive steel wheels, meeting evolving consumer preferences for safety and design.
- Rapid urbanization and infrastructure development in emerging economies will fuel the demand for commercial vehicles equipped with durable and cost-effective steel wheels.
- The increasing adoption of EVs will create opportunities for automotive steel wheels, as these vehicles require wheels capable of withstanding higher torque and load-bearing capacities.
- Manufacturers will invest in lightweight steel wheel designs to address regulatory mandates for fuel efficiency and emissions reduction, particularly in passenger vehicles.
- The integration of sensor technologies and connectivity features into steel wheels will enhance vehicle performance, safety, and maintenance, driving demand for advanced steel wheel solutions.
- Environmental sustainability will remain a key focus, driving the adoption of recyclable materials and eco-friendly manufacturing processes in the automotive steel wheels market.
- Collaborations between steel wheel manufacturers and automotive OEMs will lead to product innovations and customized solutions tailored to meet specific market demands.
- Increasing competition and regulatory pressures may lead to market consolidation, with larger players acquiring smaller firms to strengthen their market position and expand their product portfolios.
- Manufacturers will diversify their product offerings to cater to niche segments such as off-road vehicles, luxury cars, and aftermarket customization, tapping into new revenue streams.
- Optimization of global supply chains and logistics networks will improve operational efficiency and reduce production costs, ensuring competitiveness in the global automotive steel wheels market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the global Automotive Steel Wheels Market?
What factors are driving the demand for steel wheels in the automotive industry?
How are manufacturers addressing the challenge of lightweight design in steel wheels?
What opportunities does the growing adoption of electric vehicles (EVs) present for the automotive steel wheels market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Automotive Steel Wheels Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Automotive Steel Wheels Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 33.4 billion → forecast year: USD 53.1 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Automotive Steel Wheels Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Automotive Steel Wheels Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Automotive Steel Wheels Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Automotive Steel Wheels Market Drivers
- 3.3 Automotive Steel Wheels Market Restraints & Challenges
- 3.4 Automotive Steel Wheels Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Automotive Steel Wheels Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Automotive Steel Wheels Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Automotive Steel Wheels category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Automotive Steel Wheels Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Automotive Steel Wheels Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Automotive Steel Wheels market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Automotive Steel Wheels Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Automotive Steel Wheels Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Automotive Steel Wheels Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Automotive Steel Wheels (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Automotive Steel Wheels Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Automotive Steel Wheels Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Automotive Steel Wheels Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Automotive Steel Wheels Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Automotive Steel Wheels Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Automotive Steel Wheels Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Automotive Steel Wheels Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Automotive Steel Wheels Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Automotive Steel Wheels Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
