
Market Overview:
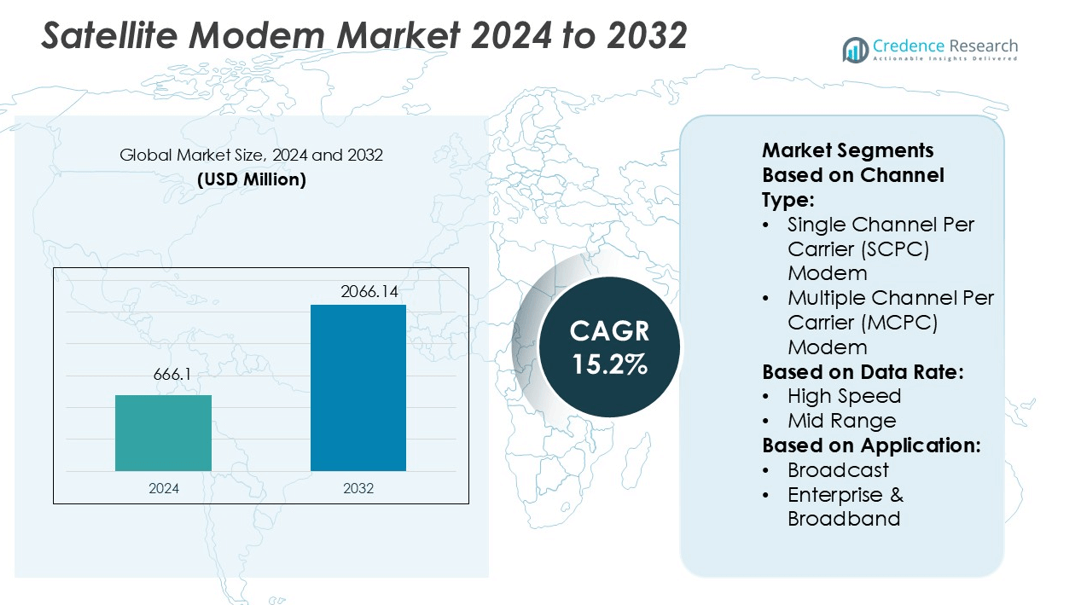
Satellite Modem Market size was valued USD 666.1 million in 2024 and is anticipated to reach USD 2066.14 million by 2032, at a CAGR of 15.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Satellite Modem Market Size 2024 | USD 666.1 million |
| Satellite Modem Market, CAGR | 15.2% |
| Satellite Modem Market Size 2032 | USD 2066.14 million |
The satellite modem market is driven by leading players such as NOVELSAT, ORBCOMM Inc., Hughes Network Systems, Datum Systems, SatixFy, Gilat Satellite Networks Ltd., AYECKA Ltd., ND SATCOM, Amplus Communication, and Comtech Telecommunications Corp. These companies focus on delivering high-performance modems that support advanced applications including enterprise broadband, broadcasting, in-flight connectivity, and maritime communication. Product innovations aligned with high-throughput satellites (HTS) and low Earth orbit (LEO) constellations strengthen their competitive position. North America emerges as the leading region with a 38% market share in 2024, supported by strong adoption across defense, aviation, and enterprise sectors.
Market Insights
- The Satellite Modem Market size was valued at USD 666.1 million in 2024 and is projected to reach USD 2066.14 million by 2032, registering a CAGR of 15.2% during the forecast period.
- Growing demand for high-speed connectivity in defense, aviation, maritime, and enterprise broadband drives market expansion, supported by innovations in secure and bandwidth-efficient communication.
- Integration with high-throughput satellites (HTS) and low Earth orbit (LEO) constellations is a key trend, enabling enhanced data capacity, reduced latency, and expanded applications across industries.
- High costs of deployment and competition from terrestrial and 5G networks act as major restraints, limiting adoption in price-sensitive regions despite strong connectivity benefits.
- North America leads the market with 38% share, followed by Europe at 27% and Asia Pacific at 22%, while enterprise broadband applications account for 30% share, making it the dominant segment in 2024.
Market Segmentation Analysis:
By Channel Type
The Single Channel Per Carrier (SCPC) modem segment dominates the satellite modem market with over 55% share in 2024. Its leadership comes from high reliability, dedicated bandwidth, and low latency performance, which are crucial for applications like defense, enterprise networks, and broadcast services. Demand for SCPC modems continues to rise with the growing need for uninterrupted, secure, and mission-critical communication. MCPC modems, while cost-effective for shared bandwidth scenarios, lag behind due to limitations in handling large data-intensive applications compared to SCPC solutions.
- For instance, NOVELSAT’s NS3000 professional modem supports data rates ranging from 100 Kbps to 850 Mbps, integrates DVB-S2X technology with efficiency gains of up to 40% in satellite spectrum use, and features built-in AES-256 encryption for secure transmissions.
By Data Rate
High-speed modems hold the largest share, capturing 48% of the market in 2024. Their dominance stems from increasing demand for real-time video streaming, enterprise broadband, and in-flight connectivity. Organizations and service providers prefer high-speed solutions to support data-heavy applications with consistent quality of service. Mid-range modems serve smaller enterprises and regional broadcasters, while entry-level models cater to basic communication needs. However, the surge in video-based services, telemedicine, and remote learning ensures that high-speed modems remain the most adopted choice across multiple industries.
- For instance, ORBCOMM's ST 6100 satellite modem is engineered for industrial IoT and maritime connectivity, providing reliable, two-way messaging for tracking and monitoring fixed and mobile assets in remote areas.
By Application
Enterprise & broadband applications lead the market, representing 30% of the share in 2024. Enterprises rely on satellite modems to extend connectivity in remote and underserved regions, supporting critical functions like cloud access and secure data transfer. The broadcast segment also accounts for significant adoption due to increasing content distribution demands. In-flight connectivity is rapidly expanding, driven by rising air travel and passenger expectations for seamless internet. Meanwhile, offshore communication and tracking applications gain traction in maritime and logistics, though they remain smaller segments compared to enterprise broadband.
Market Overview
Rising Demand for High-Speed Connectivity
The increasing demand for high-speed and reliable connectivity is a primary growth driver for the satellite modem market. Industries such as aviation, maritime, defense, and energy require uninterrupted broadband services in remote locations. High-definition video streaming, cloud-based enterprise applications, and remote healthcare further boost demand. Satellite modems enable secure, low-latency data transmission, meeting critical communication needs where terrestrial networks are absent. This growing reliance on high-speed connectivity accelerates the adoption of advanced satellite modems worldwide.
- For instance, Hughes Network Systems’ JUPITER System hardware upgrades enabling throughputs exceeding 300 Mbps on the latest terminals, designed to meet the demands of enterprise, mobility, and cellular backhaul applications.
Expansion of Defense and Government Applications
Defense and government sectors significantly drive the satellite modem market due to rising requirements for secure, mission-critical communication. Military operations rely on satellite modems to ensure real-time data sharing, command, and surveillance in areas lacking terrestrial infrastructure. Governments invest heavily in modernizing communication systems to enhance national security and disaster management. The demand for resilient and encrypted satellite communication solutions continues to grow, ensuring stable revenue streams from public sector and defense contracts.
- For instance, Datum Systems’ M7LT modem is a configurable satellite modem that supports data rates up to 350 Mbps using DVB-S2X technology. It is designed to operate with low processing latency and offers a variety of configurations for applications requiring high spectral efficiency.
Growing Adoption of In-Flight and Maritime Connectivity
The aviation and maritime industries are increasingly adopting satellite modems to meet rising connectivity expectations. Airlines invest in in-flight broadband solutions to enhance passenger experience, while shipping operators use satellite systems for navigation, safety, and crew welfare. Growing international trade and global air travel further expand this demand. Satellite modems support seamless, high-bandwidth communication in these sectors, ensuring efficient operations. This adoption is further encouraged by technological advancements and partnerships between satellite operators and service providers.
Key Trends & Opportunities
Integration with High-Throughput Satellites (HTS)
A major trend in the satellite modem market is the integration with high-throughput satellites (HTS). HTS offers higher bandwidth capacity and efficiency, reducing cost per bit and enhancing service delivery. This integration allows satellite modems to support data-intensive applications like 4K broadcasting, telemedicine, and enterprise cloud services. Vendors are focusing on designing modems compatible with HTS networks to capitalize on the growing demand for high-capacity communication solutions.
- For instance, SatixFy’s SX-3000 modem chip supports high throughput rates and is capable of dynamic beam hopping, enabling efficient resource allocation in High-Throughput Satellite (HTS) systems.
Emergence of IoT and Remote Monitoring Applications
The growth of the Internet of Things (IoT) presents new opportunities for satellite modems. Industries such as oil & gas, logistics, and agriculture are increasingly deploying IoT-based remote monitoring and control systems. Satellite modems provide connectivity in regions lacking terrestrial infrastructure, ensuring continuous monitoring of critical assets. This trend creates a new market segment where lightweight, energy-efficient, and cost-effective modems gain adoption, fueling innovation and expansion.
- For instance, AYECKA’s SR1 satellite receiver supports DVB-S2 with downstream throughput up to 150 Mbps, enabling applications such as high-speed data casting and content delivery for meteorological services like EUMETCast and NOAAPORT.
Key Challenges
High Cost of Deployment and Maintenance
The high cost associated with satellite communication systems remains a major challenge. Satellite modem deployment requires significant investment in ground infrastructure, installation, and ongoing maintenance. For many enterprises and governments, especially in emerging economies, these expenses limit adoption. The high upfront cost compared to terrestrial alternatives creates entry barriers, slowing market penetration in price-sensitive regions despite the long-term benefits of satellite connectivity.
Competition from Terrestrial and 5G Networks
The rapid expansion of terrestrial broadband and 5G networks poses a competitive challenge for the satellite modem market. These technologies offer lower latency and cost advantages in urban and semi-urban areas, reducing the reliance on satellite solutions. As telecom operators aggressively expand 5G coverage, satellite modem providers face pressure to differentiate through unique offerings. To remain competitive, they must focus on niche markets like aviation, maritime, and remote regions where terrestrial options are limited.
Regional Analysis
North America
North America leads the satellite modem market with 38% share in 2024. The region benefits from strong adoption across defense, aerospace, and enterprise communication sectors. Government programs, such as military modernization and space exploration projects, drive consistent demand. Airlines increasingly deploy satellite-based in-flight connectivity, boosting commercial adoption. Large investments in broadband access for rural and underserved areas further strengthen market expansion. The presence of leading technology providers, along with advanced satellite infrastructure, positions North America as the dominant region. Continued focus on secure and high-capacity communication ensures sustained growth over the forecast period.
Europe
Europe holds 27% share in the satellite modem market in 2024, supported by strong uptake in enterprise broadband, broadcasting, and maritime communication. Leading aerospace and defense programs across France, Germany, and the UK fuel market growth. The European Union’s investments in digital inclusion projects and satellite constellations further enhance adoption. Rising demand for seamless connectivity in aviation and offshore industries also boosts modem deployments. Companies in Europe focus on innovations in bandwidth efficiency and HTS integration. These developments reinforce the region’s strong position in global satellite communication infrastructure and ensure steady market expansion through 2032.
Asia Pacific
Asia Pacific accounts for 22% share in the satellite modem market in 2024, emerging as the fastest-growing region. Expanding aviation, maritime, and telecom industries drive significant adoption. Countries such as China, India, and Japan invest heavily in space programs and broadband expansion to rural areas. The increasing use of in-flight connectivity and enterprise broadband strengthens regional demand. Growing trade and offshore activities add momentum to maritime applications. Rising government initiatives for digital infrastructure and rapid technology adoption make Asia Pacific a key growth engine, with strong prospects for surpassing Europe in the coming years.
Latin America
Latin America represents 7% share of the satellite modem market in 2024, with growth driven by increasing broadband penetration in remote and rural areas. Countries like Brazil and Mexico lead adoption, supported by government-backed initiatives to bridge the digital divide. The maritime and energy sectors in offshore oil and gas operations add further demand for satellite connectivity. Growing use of enterprise broadband solutions and broadcast services strengthens market growth. While infrastructure investment remains limited compared to other regions, rising reliance on satellite networks in underserved areas ensures steady expansion of the modem market in Latin America.
Middle East & Africa
The Middle East & Africa hold 6% share in the satellite modem market in 2024, supported by growing adoption in defense, oil and gas, and offshore communication. Countries such as Saudi Arabia, UAE, and South Africa are major contributors. The region’s reliance on satellite connectivity for rural and desert areas drives demand for modems. Increasing use in enterprise broadband and government-led projects to improve digital access further contribute to growth. Despite infrastructure and cost challenges, strong investments in energy, aviation, and defense communication ensure steady expansion of the satellite modem market in this region.
Market Segmentations:
By Channel Type:
- Single Channel Per Carrier (SCPC) Modem
- Multiple Channel Per Carrier (MCPC) Modem
By Data Rate:
- High Speed
- Mid Range
By Application:
- Broadcast
- Enterprise & Broadband
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Competitive Landscape
The satellite modem market features strong competition among key players such as NOVELSAT, ORBCOMM Inc., Hughes Network Systems, Datum Systems, SatixFy, Gilat Satellite Networks Ltd., AYECKA Ltd., ND SATCOM, Amplus Communication, and Comtech Telecommunications Corp. The satellite modem market is highly competitive, shaped by rapid technological advancements and evolving customer requirements. Companies compete by developing high-speed, bandwidth-efficient, and secure communication solutions to serve diverse applications such as enterprise broadband, broadcasting, in-flight connectivity, and maritime communication. Innovation in compatibility with high-throughput satellites (HTS) and low Earth orbit (LEO) constellations remains a central focus, enabling service providers to deliver enhanced performance at lower costs. Market players also invest in expanding global reach, forming strategic partnerships, and targeting specialized sectors like IoT, defense, and remote monitoring. This competitive environment drives continuous product development, positioning technology differentiation and scalability as critical success factors in sustaining market leadership.
Key Player Analysis
- NOVELSAT
- ORBCOMM Inc.
- Hughes Network Systems
- Datum Systems
- SatixFy
- Gilat Satellite Networks Ltd.
- AYECKA Ltd.
- ND SATCOM
- Amplus Communication
- Comtech Telecommunications Corp.
Recent Developments
- In July 2025, Digital Communications Commission (DCC), which is the apex decision-making body in telecommunications. The recommendations of the Telecom Regulatory Authority of India (TRAI) will be reviewed, and the rules for the satellite communication (Satcom) services will be finalized in this meeting.
- In July 2025, Israel's new national communications satellite, Dror-1, was successfully launched into space early Sunday morning from Elon Musk's SpaceX With the use of SpaceX Falcon 9 two-stage rocket, the satellite was carried into orbit.
- In December 2024, Airbus and CNES successfully launched the TELEO optical link, which provides high-speed data transmission (10Gbps) between the Badr-8 geostationary satellite and ground stations. The launch highlights the potential of satellite laser communication to provide high-capacity, secure, and interference-resistant connectivity.
- In June 2024, Transcelestial and Axiom Space collaborated to develop advanced space laser communications in Southeast Asia, focusing on optical intersatellite links and space-based cloud infrastructure. This collaboration is aiming to develop joint demonstrations, share technical expertise, and align government agencies, revolutionizing space communications for commercial, civil, and defense sectors, with a focus on orbital data centers and secure connectivity
Report Coverage
The research report offers an in-depth analysis based on Channel Type, Data Rate, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will see stronger adoption of high-throughput satellite compatible modems.
- Integration with low Earth orbit constellations will drive demand for advanced solutions.
- Enterprise broadband will remain the leading application segment for modem deployment.
- In-flight connectivity adoption will continue to expand with rising air passenger traffic.
- Maritime communication will witness steady growth supported by global trade expansion.
- IoT-driven applications will create opportunities for lightweight and energy-efficient modem designs.
- Defense and government sectors will invest in secure, encrypted satellite communication systems.
- Cost optimization will push innovation in compact and bandwidth-efficient modem technologies.
- Emerging markets in Asia Pacific and Latin America will accelerate adoption in rural areas.
- Strategic collaborations between operators and technology vendors will shape future market growth.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of High-Speed Connectivity Needs
Industries such as defense, aviation, maritime, and enterprise broadband require reliable, high-speed connectivity in remote and underserved locations, driving the adoption of advanced satellite modems that can deliver secure, low-latency data transmission.
Integration with High-Throughput Satellites (HTS) and LEO Constellations
The shift toward HTS and LEO satellite networks enables satellite modems to support higher bandwidth, lower latency, and more data-intensive applications, expanding their use in sectors like 4K broadcasting, telemedicine, and cloud services.
Growth in Defense and Government Communication
Military and government agencies increasingly invest in satellite modems for secure, mission-critical communications, especially in areas lacking terrestrial infrastructure, ensuring stable demand from public sector contracts.
Rising Adoption in In-Flight and Maritime Connectivity
Airlines and shipping operators are deploying satellite modems to meet growing expectations for seamless internet access and operational communications, fueled by global air travel and trade expansion.
Emergence of IoT and Remote Monitoring Applications
Industries such as oil & gas, logistics, and agriculture are leveraging satellite modems for IoT-based remote monitoring and control in areas without terrestrial networks, creating new opportunities for lightweight and energy-efficient modem solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Satellite Modem Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Satellite Modem Market projected to grow between 2025 and 2032?
Which Satellite Modem Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Satellite Modem Market?
Who are the leading companies in the Satellite Modem Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Data Rate
- 1.2.1 High Speed
- 1.2.2 Mid Range
- 1.2.3 Entry Level
- 1.3 By Application
- 1.3.1 Enterprise & Broadband
- 1.3.2 Broadcast
- 1.3.3 In-Flight Connectivity
- 1.3.4 Maritime Communication
- 1.3.5 Remote Monitoring & IoT
- 1.4 By Channel Type
- 1.4.1 Single Channel Per Carrier (SCPC) Modem
- 1.4.2 Multiple Channel Per Carrier (MCPC) Modem
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 666.1 million → 2032: USD 2066.14 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Satellite Modem Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Satellite Modem Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Satellite Modem Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Satellite Modem Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Satellite Modem Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Satellite Modem Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Satellite Modem Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Satellite Modem Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 666.1 million → 2032: USD 2066.14 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Satellite Modem Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Data Rate - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 High Speed
- 12.3.7.2 Mid Range
- 12.3.7.3 Entry Level
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Enterprise & Broadband
- 12.4.7.2 Broadcast
- 12.4.7.3 In-Flight Connectivity
- 12.4.7.4 Maritime Communication
- 12.4.7.5 Remote Monitoring & IoT
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Channel Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Single Channel Per Carrier (SCPC) Modem
- 12.5.7.2 Multiple Channel Per Carrier (MCPC) Modem
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Satellite Modem End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Satellite Modem Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Satellite Modem Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Satellite Modem Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 NOVELSAT
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 ORBCOMM Inc.
- 18.4 Hughes Network Systems
- 18.5 Datum Systems
- 18.6 SatixFy
- 18.7 Gilat Satellite Networks Ltd.
- 18.8 AYECKA Ltd.
- 18.9 ND SATCOM
- 18.10 Amplus Communication
- 18.11 Comtech Telecommunications Corp.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

