
Market Overview
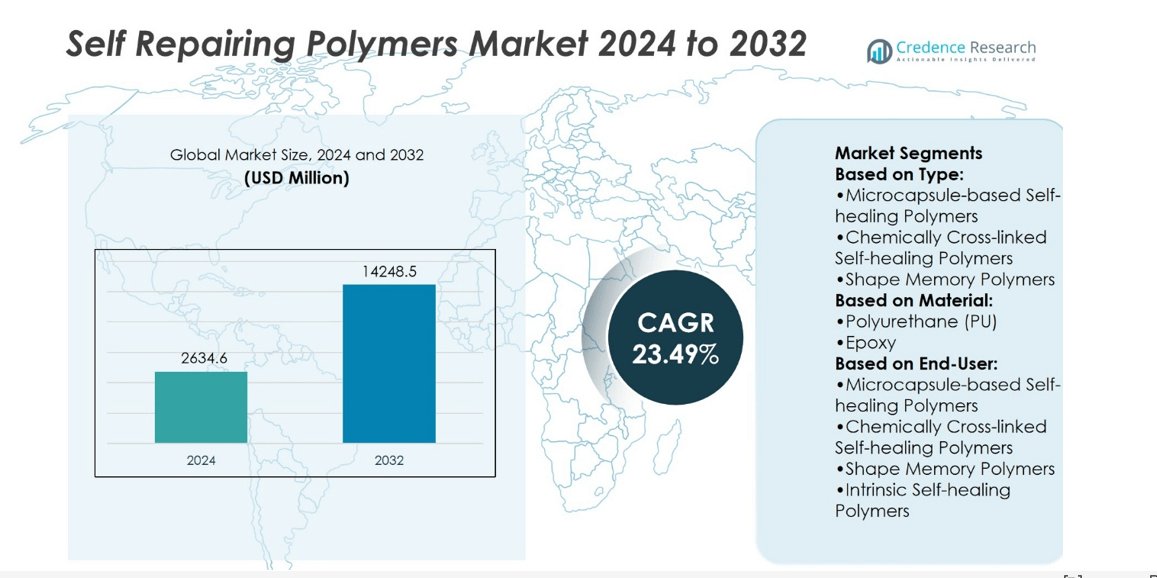
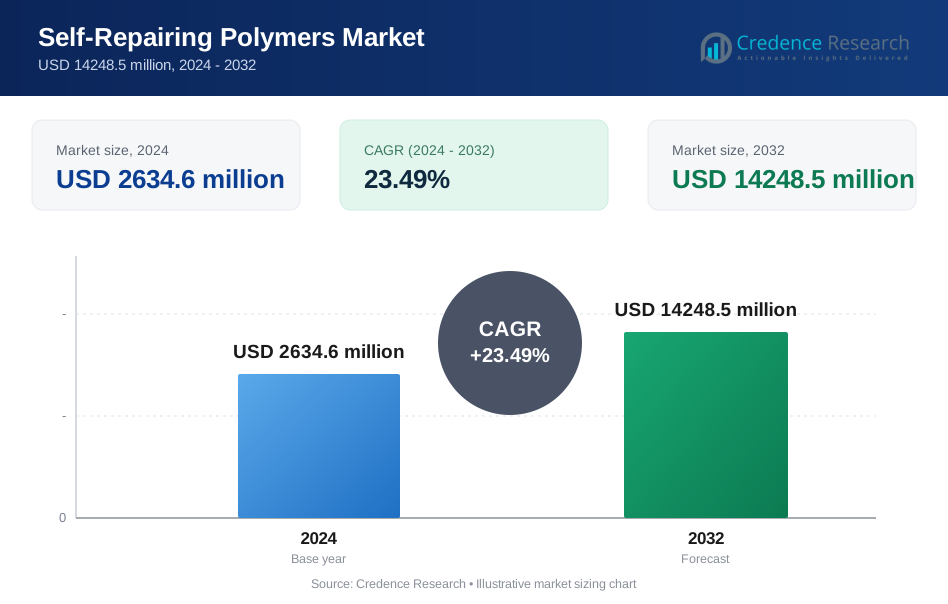
Self-Repairing Polymers Market size was valued at USD 2634.6 million in 2024 and is anticipated to reach USD 14248.5 million by 2032, at a CAGR of 23.49% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Self-Repairing Polymers Market Size 2024 | USD 2634.6 million |
| Self-Repairing Polymers Market, CAGR | 23.49% |
| Self-Repairing Polymers Market Size 2032 | USD 14248.5 million |
The Self-Repairing Polymers Market grows through strong drivers and evolving trends that highlight durability, sustainability, and advanced performance. Rising demand from automotive, aerospace, and construction sectors pushes adoption of materials that extend product lifespans and reduce maintenance costs. Healthcare and electronics industries explore self-healing polymers for implants, coatings, and device protection, reflecting broader demand for reliability. Advances in nanotechnology, smart coatings, and bio-based formulations set new standards for repair efficiency and environmental compliance. The market trends toward integration with renewable energy systems, consumer goods, and infrastructure, creating wider opportunities for innovative applications across diverse global industries.
The Self-Repairing Polymers Market shows strong presence across North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa, with North America leading through advanced R&D and early adoption in aerospace and automotive sectors. Europe follows closely, supported by sustainability initiatives and strong industrial bases, while Asia-Pacific demonstrates rapid growth in electronics and infrastructure. Key players driving innovation include BASF SE, Covestro AG, Evonik Industries, Arkema SA, DuPont, AkzoNobel N.V., Autonomic Materials Inc., and Acciona S.A.
Market Insights
- The Self-Repairing Polymers Market size was valued at USD 2634.6 million in 2024 and is projected to reach USD 14248.5 million by 2032, at a CAGR of 23.49%.
- Market drivers include rising demand from automotive, aerospace, and construction sectors seeking durable and cost-saving materials.
- Trends highlight adoption in healthcare, electronics, renewable energy, and infrastructure, supported by advances in nanotechnology and bio-based polymers.
- Competitive analysis shows large chemical companies investing in scaling production, while specialized firms focus on niche applications and sustainability.
- Market restraints include high production costs, complex synthesis methods, and limited large-scale commercialization.
- Regional analysis shows North America leading adoption through R&D and aerospace use, with Europe emphasizing sustainability and Asia-Pacific expanding in electronics and infrastructure.
- Key players such as BASF SE, Covestro AG, Evonik Industries, Arkema SA, DuPont, AkzoNobel N.V., Autonomic Materials Inc., and Acciona S.A. drive innovation and market competitiveness.
Market Drivers
Rising Demand for Durable and Sustainable Materials
The Self-Repairing Polymers Market gains momentum from industries seeking durable materials with longer lifespans. It reduces replacement costs and minimizes environmental waste. Manufacturers adopt self-repairing solutions to address sustainability targets and extend product utility. Automotive and aerospace sectors prefer polymers that repair surface cracks under stress or heat. Construction companies evaluate polymers that increase the service life of coatings and concrete structures. Demand continues to rise where maintenance costs remain high. This driver reinforces the relevance of advanced materials across critical applications.
- For instance, Evonik Industries has developed thermoplastic polyurethanes (TPU) with intrinsic self-healing functionality, capable of recovering mechanical strength by up to 90% after surface damage when exposed to heat between 50 °C and 120 °C.
Expanding Applications in Electronics and Energy Systems
Electronics manufacturers adopt self-repairing polymers to protect circuits and extend device reliability. The Self-Repairing Polymers Market benefits from polymers that heal micro-cracks in protective coatings. Energy storage systems apply these materials in batteries and cables to ensure stability. It supports safer and more efficient use of renewable energy networks. Companies integrate repairable polymers into solar panels to reduce downtime and improve resilience. Growth opportunities increase where consistent energy delivery remains essential. The expansion of electronics and energy applications secures long-term industry adoption.
- For instance, under the EU-funded SHINE project, Acciona was involved in developing new self-healing elastomers with the aim of recovering 60% of their initial mechanical properties at room temperature without human intervention
Advancements in Material Science and Nanotechnology
Ongoing research drives new formulations that improve repair speed, efficiency, and performance. The Self-Repairing Polymers Market reflects innovations where nanotechnology enables healing at microstructural levels. It allows materials to recover strength after mechanical stress or environmental exposure. Researchers develop polymers that heal at ambient temperatures, reducing energy requirements. Industry collaborations between chemical companies and universities accelerate commercial adoption. Breakthroughs create polymers with greater compatibility across industrial applications. Advancements continue to set new benchmarks for performance standards.
Supportive Regulations and Sustainability Goals Across Industries
Regulatory bodies encourage the use of eco-friendly materials with lower lifecycle impacts. The Self-Repairing Polymers Market aligns with global policies promoting green technologies and circular economies. It offers industries an alternative to traditional plastics with high waste outputs. Government programs push for sustainable solutions in automotive, construction, and consumer goods. Corporate sustainability goals accelerate adoption by integrating polymers into product designs. Supply chain stakeholders see long-term value in reduced waste streams. Supportive frameworks position self-repairing polymers as a priority in advanced material strategies.
Market Trends
Integration of Self-Repairing Polymers into Automotive and Aerospace Designs
The Self-Repairing Polymers Market shows a growing trend toward advanced adoption in mobility industries. Automotive manufacturers apply these polymers to extend the life of coatings and interiors. Aerospace companies test self-healing composites that maintain structural safety after minor cracks. It enables reduced maintenance and longer performance cycles for critical components. Suppliers highlight the value of lightweight, repairable materials that meet safety standards. Demand from these industries pushes innovation toward scalable and efficient solutions. The trend positions self-repairing polymers as a strategic material in high-value sectors.
- For instance, Arkema introduced the “Reverlink™” supramolecular self-healing elastomer range in 2009. It entered semi-industrial production at its Feuchy, France plant with an annual capacity of almost 100 metric tons.
Expansion into Consumer Electronics and Wearable Devices
Consumer electronics manufacturers integrate self-repairing polymers into protective films and casings. The Self-Repairing Polymers Market benefits from devices that maintain surface integrity after scratches. Wearable device makers explore these materials for flexible screens and smart sensors. It reduces replacement needs and enhances user experience through longer device lifespans. Startups introduce coatings that heal minor damage in seconds under heat or light. Major brands invest in partnerships with polymer developers for commercial-ready solutions. The expansion into electronics signals broad consumer acceptance of repairable technologies.
- For instance, BASF developed its MasterProtect® 180, a protective epoxy coating with high chemical resistance to sea and brackish water. This feature, among others, helps to extend the service life of reinforced concrete structures.
Increasing Role of Smart Coatings and Infrastructure Applications
Construction industries explore self-repairing coatings to protect concrete, metals, and pipelines. The Self-Repairing Polymers Market incorporates smart materials that heal when exposed to moisture or stress. It improves durability of bridges, roads, and industrial facilities under harsh conditions. Companies adopt these polymers to reduce long-term repair costs in infrastructure projects. Research highlights systems that close micro-cracks in coatings without human intervention. Adoption accelerates in regions where infrastructure sustainability remains a policy priority. The trend strengthens the role of self-repairing polymers in large-scale public works.
Advancements in Bio-Based and Sustainable Polymer Formulations
Manufacturers develop bio-based self-repairing polymers to align with environmental and regulatory demands. The Self-Repairing Polymers Market reflects rising interest in renewable feedstocks for advanced materials. It reduces dependence on petroleum-derived polymers and supports circular economy practices. Research teams design polymers that heal while maintaining biodegradability. Industry players pursue certifications that demonstrate environmental compliance and product responsibility. End users in packaging and consumer goods industries seek sustainable material options. The trend creates opportunities for eco-friendly alternatives in diverse market segments.
Market Challenges Analysis
High Production Costs and Limited Commercial Scalability
The Self-Repairing Polymers Market faces significant challenges due to high production expenses and complex synthesis methods. It requires advanced manufacturing facilities and specialized raw materials, which raise costs for producers. Limited scalability restricts large-scale adoption, particularly in cost-sensitive industries such as packaging and consumer goods. Companies struggle to balance research investments with the demand for affordable applications. Technical hurdles include ensuring consistent performance across varying environmental conditions. High costs slow down commercialization despite strong interest from multiple sectors. The challenge highlights the need for more efficient production techniques to support wider adoption.
Performance Reliability and Regulatory Barriers Across Industries
Ensuring reliable performance under real-world conditions remains a critical barrier for adoption. The Self-Repairing Polymers Market reflects concerns over polymers that fail to repair consistently under extreme stress or temperature. It creates hesitation among end users who depend on material durability for safety-critical applications. Regulatory approvals also slow adoption, as agencies demand extensive validation of long-term safety and effectiveness. Industries such as aerospace, automotive, and construction require proven standards before deployment. The lack of unified testing protocols creates delays in certification and commercialization. Addressing these barriers is essential to expand confidence and strengthen market growth.
Market Opportunities
Expanding Potential in Healthcare and Biomedical Applications
The Self-Repairing Polymers Market presents strong opportunities in healthcare, where demand for advanced materials continues to grow. It supports the development of self-healing implants, wound dressings, and drug delivery systems. Hospitals and clinics value materials that extend device reliability and reduce replacement risks. Research groups explore polymers that repair under body temperature and natural conditions. Medical device companies see potential in coatings that reduce infection and improve durability. Governments encourage innovation in healthcare materials through research grants and pilot programs. These factors create a clear pathway for growth within the biomedical sector.
Rising Adoption in Renewable Energy and Smart Infrastructure
The Self-Repairing Polymers Market also benefits from opportunities in renewable energy and infrastructure projects. It contributes to solar panels, wind turbines, and smart grids where durability is vital. Energy firms pursue polymers that heal surface cracks in cables and coatings to avoid downtime. Infrastructure planners integrate repairable coatings into bridges, pipelines, and road systems for long-term resilience. Demand grows in regions prioritizing sustainable infrastructure development. Companies offering polymers that meet both performance and environmental standards position themselves as leaders. This opportunity links innovation in materials directly with global energy and infrastructure goals.
Market Segmentation Analysis:
By Type
The Self-Repairing Polymers Market divides into microcapsule-based, chemically cross-linked, shape memory, and intrinsic self-healing polymers. Microcapsule-based polymers remain widely studied because they release healing agents when cracks appear, ensuring effective repair of coatings and composites. Chemically cross-linked polymers show strength in applications where durability and mechanical stability are critical. Shape memory polymers offer flexibility and structural recovery in automotive and aerospace applications. Intrinsic self-healing polymers attract attention for their ability to repair repeatedly without external agents. It highlights how each type offers distinct advantages that match specific industrial demands. The segment reflects the diversity of innovation shaping adoption across high-performance industries.
- For instance, AkzoNobel Interchar® 1120 is an intumescent coating that protects steel structures by providing up to 120 minutes of fire resistance, as certified by independent testing to international standards. This coating is not described as self-sealing.
By Material
Polyurethane (PU) and epoxy dominate material preferences due to their strong mechanical properties and adaptability. PU-based self-repairing polymers show promise in coatings, foams, and sealants that require durability with elasticity. Epoxy-based polymers excel in electronics, aerospace, and adhesives where high chemical resistance and stability are needed. It supports extensive use across transportation, construction, and industrial equipment. Research continues to expand material formulations to enhance self-healing cycles and environmental resistance. Both materials reinforce the importance of balancing performance with repairability in advanced applications. The material segment remains central to ongoing product development strategies.
- For instance, CompPair HealTech™ composite is a developing product that can heal microcracks and delamination by applying local heat between 100°C and 150°C. The company claims that the repair can take as little as one minute for some minor damage and that the material can regain up to 100% of its initial mechanical strength. CompPair also states the composite can undergo more than 60 damage–healing cycles while maintaining its initial properties, based on its internal tests.
By End User
End users range from automotive and aerospace to healthcare, electronics, and infrastructure. Automotive companies integrate self-healing coatings to extend the lifespan of exterior parts and interiors. Aerospace firms apply these polymers in composites to enhance safety and reduce inspection intervals. Healthcare sectors explore hydrogels and bio-based polymers for implants, wound dressings, and regenerative solutions. Electronics manufacturers apply thin-film self-repairing coatings to circuits and casings to ensure device reliability. It demonstrates strong adaptability of self-repairing polymers to both industrial and consumer markets. The end-user segment reflects broad opportunities across traditional and emerging sectors.
Segments:
Based on Type:
- Microcapsule-based Self-healing Polymers
- Chemically Cross-linked Self-healing Polymers
- Shape Memory Polymers
Based on Material:
- Polyurethane (PU)
- Epoxy
Based on End-User:
- Microcapsule-based Self-healing Polymers
- Chemically Cross-linked Self-healing Polymers
- Shape Memory Polymers
- Intrinsic Self-healing Polymers
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds the largest share of the Self-Repairing Polymers Market at 38%. The region benefits from strong research institutions, early adoption in aerospace, and advanced automotive sectors. It shows consistent investment in material innovation driven by defense and infrastructure projects. Companies in the United States collaborate with universities to develop polymers that extend the lifespan of coatings, electronics, and composites. The healthcare sector also contributes through the use of hydrogels and bio-based polymers in medical devices and implants. It positions the region as a leader in technological advancements and commercialization. The dominance of North America reflects its capacity to integrate innovative materials across multiple high-value industries.
Europe
Europe accounts for 28% of the Self-Repairing Polymers Market. The region demonstrates leadership in sustainability and regulatory frameworks that encourage the use of eco-friendly materials. It supports growth in automotive, construction, and renewable energy industries where durability and low maintenance costs remain vital. Germany, France, and the United Kingdom act as major hubs for both research and industrial deployment. Aerospace applications in countries such as France and Germany further strengthen regional demand. It also aligns with the European Union’s circular economy goals, encouraging polymer innovation based on renewable feedstocks. Europe’s position highlights its balance of innovation, regulation, and practical adoption across industries.
Asia-Pacific
Asia-Pacific represents 22% of the Self-Repairing Polymers Market. The region shows rapid adoption across automotive, electronics, and infrastructure projects, particularly in China, Japan, and South Korea. Strong electronics manufacturing bases support integration of self-repairing coatings and films in consumer devices. It benefits from government-backed initiatives that promote advanced material research and industrial resilience. Growing healthcare markets in India and Southeast Asia also encourage adoption of hydrogel-based polymers for biomedical use. Rapid industrial growth and rising demand for cost-effective durability position Asia-Pacific as the fastest-growing regional market. The region’s share underscores its expanding role in both production and end-use adoption.
Latin America
Latin America holds 7% of the Self-Repairing Polymers Market. The region focuses on applications in construction, energy, and mining where equipment durability reduces operational costs. Brazil and Mexico lead in adoption, supported by infrastructure modernization programs. It also sees demand for automotive coatings and protective materials in local manufacturing sectors. Limited research infrastructure compared to North America or Europe slows wider adoption, but rising industrial demand creates steady opportunities. International players expand distribution networks to increase presence in this region. Latin America’s share highlights a growing yet still developing position within the global market landscape.
Middle East and Africa
The Middle East and Africa account for 5% of the Self-Repairing Polymers Market. Demand originates mainly from infrastructure development, oil and gas, and defense projects. It benefits from government investment in smart city projects and durable materials for energy networks. Countries such as Saudi Arabia, the UAE, and South Africa represent key adopters. Research activity remains limited, but collaborations with global chemical firms support technology transfer. It also reflects rising demand for polymers that reduce maintenance costs in harsh climates. The share demonstrates the region’s role as an emerging market with future potential tied to large-scale infrastructure and energy projects.
Key Player Analysis
- Evonik Industries (Germany)
- Applied Thin Films, Inc. (U.S.)
- Acciona S.A. (Spain)
- Arkema SA (France)
- Autonomic Materials Inc. (U.S.)
- Covestro AG (Germany)
- BASF SE (Germany)
- Avecom N.V. (Belgium)
- I. Du Pont De Nemours and Company (U.S.)
- AkzoNobel N.V. (Netherlands)
Competitive Analysis
The Self-Repairing Polymers Market features include Evonik Industries, Applied Thin Films Inc., Acciona S.A., Arkema SA, Autonomic Materials Inc., Covestro AG, BASF SE, Avecom N.V., E.I. Du Pont De Nemours and Company, and AkzoNobel N.V. The Self-Repairing Polymers Market is highly competitive, driven by continuous innovation and expanding application areas. Large multinational chemical companies focus on scaling production capacity, advancing R&D, and ensuring compliance with environmental standards. Smaller specialized firms emphasize niche technologies, including bio-based formulations and advanced coating solutions, to differentiate their offerings. Competition intensifies around the ability to deliver cost-effective products that maintain performance reliability across automotive, aerospace, electronics, healthcare, and construction industries. Strategic collaborations with universities, research institutes, and industrial partners strengthen pipelines for commercial deployment. Patents, product launches, and sustainable material development remain core strategies shaping leadership and long-term positioning.
Recent Developments
- In June 2024, a researcher at Swinburne University of Technology in Australia, created a new type of carbon fiber reinforced polymer composites that enable future submarines to self-identify microcracks and self-heal. This innovative material is designed to mimic the behavior of living organisms, with the ability to sense, respond, and adapt to stresses and defects in real-time.
- In October 2023, DuPont, in collaboration with U.S. Steel, unveiled COASTALUME. This self-healing product is designed with superior corrosion and UV resistance, tailored for coastal environments, making it perfect for roofing and exterior cladding applications in the construction sector.
- In May 2023, Covestro launched a new series of polyurethane-based self-healing coatings designed for automotive surfaces. These coatings automatically mend minor damage, enhancing aesthetic longevity while decreasing the need for manual upkeep or repainting.
Report Coverage
The research report offers an in-depth analysis based on Type, Material, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand will rise from automotive and aerospace sectors for lightweight, durable, and repairable materials.
- Healthcare applications will expand with hydrogels and bio-based polymers supporting medical devices and wound care.
- Electronics manufacturers will adopt self-repairing coatings for flexible screens and protective casings.
- Construction industries will use smart coatings and polymers to extend infrastructure lifespan and reduce maintenance costs.
- Renewable energy projects will integrate polymers into solar panels, wind turbines, and cables for higher resilience.
- Bio-based and sustainable formulations will gain preference to align with global environmental regulations.
- Research will improve healing speed, efficiency, and multi-cycle performance of advanced polymers.
- Collaborations between universities, startups, and major chemical firms will accelerate commercialization.
- Asia-Pacific will emerge as a high-growth region driven by electronics and infrastructure development.
- Intellectual property strategies and patent portfolios will remain central to maintaining market competitiveness.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Self-Repairing Polymers Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Self-Repairing Polymers Market projected to grow between 2025 and 2032?
Which Self-Repairing Polymers Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Self-Repairing Polymers Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Self-Repairing Polymers Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Self-Repairing Polymers Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2634.6 million → 2032: USD 14248.5 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Self-Repairing Polymers Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Self-Repairing Polymers Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Self-Repairing Polymers Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Self-Repairing Polymers Market Drivers
- 3.3 Self-Repairing Polymers Market Restraints & Challenges
- 3.4 Self-Repairing Polymers Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Self-Repairing Polymers Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Self-Repairing Polymers Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Self-Repairing Polymers category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Self-Repairing Polymers Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Self-Repairing Polymers Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Self-Repairing Polymers market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Self-Repairing Polymers Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Self-Repairing Polymers Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Self-Repairing Polymers Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Self-Repairing Polymers (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Self-Repairing Polymers Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Self-Repairing Polymers Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Self-Repairing Polymers Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Self-Repairing Polymers Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Self-Repairing Polymers Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Self-Repairing Polymers Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Self-Repairing Polymers Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Self-Repairing Polymers Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Self-Repairing Polymers Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
