
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Semiconductor Annealing Equipment MarketSize 2024 | USD 1,410.15 million |
| Semiconductor Annealing Equipment Market, CAGR | 10.6% |
| Semiconductor Annealing Equipment Market Size 2032 | USD 3,157.2 million |
Market Overview:
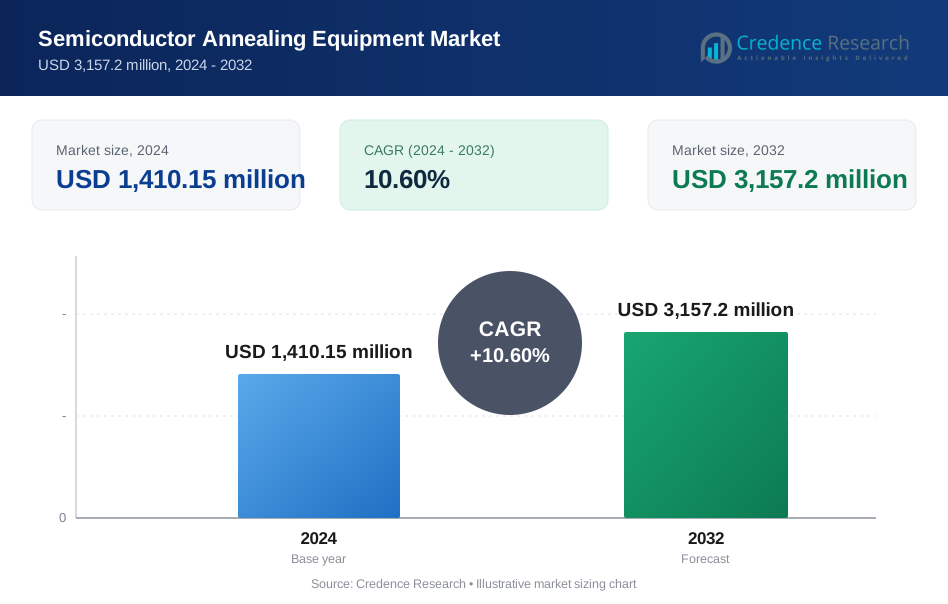
The Semiconductor Annealing Equipment Market is projected to grow from USD 1,410.15 million in 2024 to USD 3,157.2 million by 2032, registering a compound annual growth rate (CAGR) of 10.6% during the forecast period.
The Semiconductor Annealing Equipment Market is driven by the rising demand for advanced consumer electronics, rapid growth in semiconductor fabrication, and increasing adoption of cutting-edge technologies such as 5G, AI, and IoT. As chip designs become more complex and miniaturized, the need for precise thermal processing and improved yield drives the adoption of advanced annealing equipment. Additionally, the transition to smaller nodes in semiconductor manufacturing and the increasing use of FinFET and 3D NAND technologies boost demand for high-performance annealing solutions. Governments and private players are also investing heavily in semiconductor infrastructure, further accelerating market growth. Key trends include the integration of automation and AI-driven process controls to enhance efficiency, the shift toward rapid thermal annealing (RTA) and laser annealing for better precision, and the rising focus on energy-efficient and sustainable manufacturing practices. Strategic collaborations, innovations in annealing technology, and expansion of fabrication facilities in Asia-Pacific are also shaping the competitive landscape of the market.
The Semiconductor Annealing Equipment Market is experiencing growth across key regions including Asia-Pacific, North America, and Europe. Asia-Pacific leads with a dominant market share of around 50%, driven by strong semiconductor manufacturing hubs in China, South Korea, Taiwan, and Japan. North America follows with 25% of the market, fueled by advancements in research, innovation, and government-backed semiconductor initiatives in the U.S. Europe holds a 15% share, with a focus on high-tech manufacturing and sustainable growth, especially in automotive electronics. Key players in the market include Applied Materials, Mattson Technology, Kokusai Electric, and Centrotherm, among others. These companies leverage technological innovations to cater to diverse regional needs, enhancing competitiveness and market presence globally.
Market Insights:
- The Semiconductor Annealing Equipment Market is projected to grow from USD 1,410.15 million in 2024 to USD 3,157.2 million by 2032, at a CAGR of 10.6%.
- Rising demand for advanced consumer electronics and high-performance devices drives the adoption of precise thermal processing for improved chip reliability and power efficiency.
- Rapid expansion of semiconductor manufacturing, fueled by global investment in domestic production facilities, directly benefits the market with increased demand for annealing equipment.
- Technological advancements in semiconductor architectures, such as FinFET and 3D NAND, require new annealing methods for uniformity and low thermal budgets.
- The proliferation of IoT, AI, and 5G infrastructure worldwide increases demand for high-density, low-power semiconductors, expanding the market for advanced annealing solutions.
- High equipment costs and capital-intensive manufacturing requirements pose a challenge, limiting access to advanced thermal processing systems for smaller firms.
- The technical complexity of modern annealing systems requires a skilled workforce, presenting a challenge in regions with a shortage of trained engineers and technicians.
Market Drivers:
Increasing Demand for Advanced Consumer Electronics and High-Performance Devices:
The Semiconductor Annealing Equipment Market is experiencing strong growth due to rising consumer demand for compact, high-performance electronics. Smartphones, tablets, wearables, and laptops require semiconductors with improved power efficiency and speed. This demand compels manufacturers to adopt precise annealing processes that enhance electrical performance and reliability. The need for thinner and more densely packed chips drives investment in advanced thermal processing technologies. It enables the production of semiconductors with smaller nodes and better performance characteristics. Manufacturers rely on annealing equipment to meet the stringent quality standards required in today’s electronics industry.
For instance, Mattson Technology’s millisecond annealing equipment is used in the fabrication of high-speed memory chips, enabling faster and more energy-efficient consumer electronics.
Rapid Expansion of Global Semiconductor Manufacturing Capacity:
The global semiconductor industry is undergoing a significant expansion to meet supply chain demands and geopolitical goals. Many countries are investing in domestic semiconductor production, prompting new fabrication plant construction and upgrades. The Semiconductor Annealing Equipment Market benefits directly from this trend, with equipment required for both front-end and back-end processing. Governments and private investors fund infrastructure aimed at reducing dependence on external chip sources. It results in a steady increase in equipment procurement, including thermal processing systems. Annealing equipment is integral to ensuring consistent material properties across advanced semiconductor devices.
For instance, SEMI reports that 18 new semiconductor fabrication plants are set to begin construction worldwide in 2025, including major projects in the Americas, Japan, China, and Europe, with most facilities expected to be operational by 2026 or 2027.
Technological Advancement in Thermal Processing and Device Architectures:
Evolving device architectures such as FinFETs, GAA (Gate-All-Around), and 3D NAND demand new annealing methods that deliver uniformity and low thermal budgets. The Semiconductor Annealing Equipment Market responds by incorporating laser and rapid thermal annealing technologies that address complex material and structural needs. These innovations support faster production cycles and minimize defect rates in delicate semiconductor layers. It strengthens process control, ensuring critical performance parameters are achieved during each stage of fabrication. Manufacturers prioritize flexibility and scalability in equipment to align with varying product specifications. Advanced thermal systems now support precise temperature management, a key factor in next-generation chip production.
Surging Adoption of IoT, AI, and 5G Infrastructure Worldwide:
The proliferation of connected devices and intelligent systems requires a large volume of high-performance chips. Markets driven by IoT, AI, and 5G create new opportunities for chipmakers, increasing demand for reliable semiconductor manufacturing solutions. The Semiconductor Annealing Equipment Market plays a vital role in supporting this shift by enabling the creation of high-density, low-power components. It addresses the stringent processing requirements necessary for devices operating at higher speeds and lower voltages. As telecom and industrial sectors scale up, the need for durable and high-yield chips intensifies. Thermal annealing ensures consistent performance, extending device life and supporting system reliability.
Market Trends:
Shift Toward Advanced Annealing Techniques and Energy-Efficient Systems:
The Semiconductor Annealing Equipment Market is witnessing a shift toward advanced annealing methods such as laser annealing and rapid thermal processing. These techniques provide greater temperature control, faster processing times, and reduced risk of thermal damage to delicate structures. It supports the development of next-generation semiconductor devices that require higher precision and uniformity. Manufacturers are focusing on energy-efficient systems to meet sustainability goals and reduce operating costs. The integration of smart temperature controls and real-time monitoring improves process stability and yields. Equipment suppliers are optimizing system designs to handle complex wafer materials and diverse device architectures without compromising throughput.
For instance, Powerlase’s Procyon g2000 laser system is used for green laser silicon annealing in the manufacture of Low Temperature Poly Silicon (LTPS) displays, delivering process speeds up to 150 cm²/s-over 60% faster than traditional excimer laser annealing-while reducing operating costs to just 18% of excimer systems and minimizing toxic gas handling risks.
Growing Focus on Automation, AI Integration, and Smart Manufacturing:
Automation and AI integration are transforming semiconductor fabrication, driving demand for intelligent annealing equipment. The Semiconductor Annealing Equipment Market is evolving to include systems that support data analytics, predictive maintenance, and adaptive control features. It enhances production efficiency and minimizes human error during critical thermal processes. Equipment with smart interfaces and diagnostic tools helps streamline operations across increasingly complex production lines. Manufacturers are adopting modular and flexible platforms that can be reconfigured to meet changing production requirements. These trends align with the global move toward Industry 4.0, where connected, data-driven systems enable faster innovation cycles and consistent product quality.
For instance, KUKA’s KMR iiwa clean robot is used for the autonomous handling and transportation of delicate semiconductor wafers, operating without safety fencing and reducing contamination risks in cleanroom environments.
Market Challenges Analysis:
High Equipment Costs and Capital-Intensive Manufacturing Requirements:
The Semiconductor Annealing Equipment Market encounters major challenges due to the high costs associated with acquiring and operating advanced thermal processing systems. These systems require significant upfront capital, making them accessible primarily to large semiconductor manufacturers. It restricts smaller firms from entering or expanding within the market. The total cost of ownership, including installation, system calibration, maintenance, and energy consumption, places an additional burden on operational budgets. For companies with limited financial flexibility, justifying the return on investment becomes increasingly difficult. Delays in procurement and equipment upgrades hinder innovation and slow down production capabilities. Emerging markets face the greatest impact, where funding limitations and infrastructure gaps reduce opportunities for adoption and growth. This financial barrier remains a critical constraint, affecting both market expansion and technological advancement.
For instance, SCREEN Semiconductor Solutions Co., Ltd. has established strategic partnerships with leading semiconductor manufacturers to develop next-generation laser annealing technologies, an effort that demands significant R&D investment and high-end equipment, often accessible only to major industry players.
Technical Complexity and Need for Skilled Workforce:
The Semiconductor Annealing Equipment Market also struggles with the increasing technical complexity of its systems and the corresponding need for specialized labor. Operating modern annealing tools requires deep understanding of semiconductor processes, thermal dynamics, and precision controls. It presents a major obstacle in regions lacking a robust pipeline of trained engineers and technicians. Companies face delays in system integration and must invest time and resources into workforce training programs. The risk of production errors or equipment misconfiguration rises when experienced personnel are unavailable. Technical missteps can lead to reduced yield, material waste, or equipment damage. As thermal processing technologies advance, the talent gap widens, placing additional strain on manufacturers. Ensuring operational efficiency and product quality becomes difficult without a qualified workforce to manage complex annealing processes effectively.
Market Opportunities:
Rising Investments in Semiconductor Fabrication Across Emerging Economies
The Semiconductor Annealing Equipment Market has strong growth potential due to expanding fabrication activities in emerging economies. Countries such as India, Vietnam, and Malaysia are investing in local semiconductor manufacturing to reduce import reliance and strengthen technology infrastructure. It creates demand for new processing equipment, including advanced annealing systems. Government incentives, public-private partnerships, and foreign direct investments are accelerating the setup of fabrication plants. These developments open new revenue channels for equipment providers looking to enter untapped regions. Local demand for consumer electronics and automotive chips further supports this growth. Manufacturers can gain early advantage by aligning with national strategies and offering scalable solutions tailored to local needs.
Growing Adoption of AI, Electric Vehicles, and Smart Technologies
Technological shifts toward artificial intelligence, electric vehicles, and smart devices present long-term opportunities for the Semiconductor Annealing Equipment Market. These applications require high-performance chips manufactured with tight thermal and material tolerances. It increases the need for precision annealing systems capable of supporting advanced node technologies. As industries transition to digital and autonomous systems, chip complexity rises, making thermal control critical for yield and reliability. Equipment vendors can benefit by developing solutions optimized for these high-growth segments. Collaboration with chip designers and system integrators helps tailor annealing equipment for future manufacturing demands. This alignment enables greater value delivery across emerging technology ecosystems.
Market Segmentation Analysis:
By Type of Equipment The Semiconductor Annealing Equipment Market includes several equipment types tailored to specific processing needs. Rapid Thermal Annealing (RTA) dominates the segment due to its speed and precision, making it ideal for advanced semiconductor nodes. Laser Annealing is gaining popularity for its capability to process thin wafers and advanced materials with high accuracy. Plasma and Flash Annealing are being adopted for applications requiring shorter thermal cycles and reduced thermal budgets. Conventional Furnace Annealing, though older, remains valuable in high-volume, cost-sensitive production lines. Each type serves a different manufacturing requirement, offering varying levels of precision, energy efficiency, and throughput.
By Technology Technological segmentation plays a key role in shaping the capabilities of annealing systems. Optical and Non-Contact Technologies are widely adopted for their ability to handle delicate wafers without physical contact, reducing contamination risks. Hybrid Technology is emerging as a preferred solution, combining the accuracy of non-contact systems with the stability of contact methods. Contact Technology remains important in legacy systems and standard manufacturing setups where cost and simplicity are critical. It provides stable performance in less demanding thermal processes. Each technology type supports distinct production goals based on speed, accuracy, and integration flexibility.
By Application Application-wise, the Semiconductor Annealing Equipment Market caters to a broad range of semiconductor devices. Memory Devices and Logic Devices represent the largest segments, driven by their extensive use in computing and mobile technologies. Power Devices are growing steadily, fueled by demand in electric vehicles and energy systems. RF Devices benefit from the global expansion of 5G infrastructure and require precise thermal control. Optoelectronics is an emerging area supported by the need for high-performance sensors, lasers, and display technologies. Each application defines unique performance specifications, influencing the choice of annealing technology and equipment.
Segments:
Based on Type of Equipment
- Rapid Thermal Annealing (RTA)
- Conventional Fuace Annealing
- Laser Annealing
- Plasma Annealing
- Flash Annealing
Based on Technology
- Optical Technology
- Contact Technology
- Non-Contact Technology
- Hybrid Technology
Based on Application
- Memory Devices
- Logic Devices
- Power Devices
- RF Devices
- Optoelectronics
Based on End-User Industry
- Consumer Electronics
- Telecommunications
- Automotive
- Aerospace & Defense
- Healthcare
Based on Process Stage
- Wafer Level Annealing
- Post-Ion-Implantation Annealing
- Pre-Metal Annealing
- Post-Deposition Annealing
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia-Pacific
The Asia-Pacific region holds the largest share of the Semiconductor Annealing Equipment Market, accounting for 50% of the global market. Countries such as China, South Korea, Taiwan, and Japan lead in chip production, supported by advanced foundries and strong supply chain networks. It benefits from favorable government policies, skilled labor, and significant foreign investments in fabrication facilities. Taiwan’s TSMC, South Korea’s Samsung, and China’s SMIC are major players driving equipment demand. Government-backed initiatives to boost domestic semiconductor capabilities continue to accelerate regional growth. The availability of raw materials and proximity to major electronics manufacturers further strengthens its position.
North America
North America holds 25% of the Semiconductor Annealing Equipment Market share, supported by advanced research, innovation, and the strong presence of leading semiconductor companies. The United States is investing heavily in onshore chip manufacturing to reduce dependency on foreign supply chains. It is home to major technology developers and research institutions that contribute to next-generation annealing equipment. Federal funding under programs like the CHIPS Act supports the expansion of local fabrication capacity. The region shows steady demand for high-precision thermal processing systems, particularly in AI, defense, and high-performance computing sectors. This focus on strategic autonomy and technology leadership continues to create opportunities for equipment vendors.
Europe
Europe holds 15% of the Semiconductor Annealing Equipment Market share, playing an important role through its emphasis on advanced manufacturing and sustainability. Countries such as Germany, France, and the Netherlands support semiconductor innovation through public funding and industry collaboration. It benefits from a strong automotive electronics sector, which drives demand for power and logic devices. Regional companies focus on precision engineering and environmental compliance, influencing the design of annealing systems. Europe’s regulatory framework promotes energy-efficient, safe, and clean technologies in semiconductor processing. While smaller in market share than Asia or North America, Europe remains a key hub for high-value, specialized semiconductor applications.
Key Player Analysis:
- Kokusai Electric
- Centrotherm
- SemiTEq
- ECM
- Mattson Technology
- ADVANCE RIKO
- Applied Materials
- JTEKT Thermo Systems Corporation
- Koyo Thermo Systems
- CVD Equipment Corporation
- AnnealSys
Competitive Analysis:
The Semiconductor Annealing Equipment Market is highly competitive, with several established players offering advanced thermal processing solutions. Companies like Applied Materials, Mattson Technology, and Kokusai Electric dominate the market, leveraging their strong R&D capabilities and established customer base in semiconductor manufacturing. These leaders focus on offering highly precise, energy-efficient systems that meet the increasing demands for miniaturized, high-performance chips. Emerging players such as AnnealSys and ECM are gaining traction by introducing cost-effective, specialized solutions for specific applications. Innovation in equipment efficiency, process automation, and integration with advanced technologies like AI and IoT continues to drive competitive differentiation. It is crucial for companies to address the rising need for sustainability and energy-efficient solutions while maintaining high throughput. Strategic collaborations, acquisitions, and technological advancements are common strategies used by market leaders to maintain their competitive edge in an evolving market landscape.
Recent Developments:
- On December 5, 2024, JTEKT Thermo Systems Corporation announced the development of new heat treatment equipment models for SiC power semiconductors, including the "RLA-4200-V" contact annealing system and the "VF-5300HLP" activation annealing system, which increase productivity by enabling parallel processing and batch wafer handling.
- In December 2023, CVD Equipment Corporation planned the launch of a SiC Epi Single Wafer System for 2024, following their 2022 launch of the PVT150™ Crystal Growth System and the 2023 launch of the PVT200™ Crystal Growth System, aimed at improving SiC wafer quality and manufacturing efficiency.
- June 2024, Kokusai Electric announced the development of a new ultra-high temperature annealing system compatible with 150mm and 200mm wafers, featuring plasma-assisted treatment for improved film properties in batch processing.
- In December 2024, JTEKT Thermo Systems announced new models of heat treatment equipment for SiC power semiconductors. The latest activation annealing system, VF-5300HLP, is a batch processing tool that can process up to 100 wafers (6-inch or 8-inch) simultaneously.
Market Concentration & Characteristics:
The Semiconductor Annealing Equipment Market is moderately concentrated, with a few large players dominating the competitive landscape. Major companies such as Applied Materials, Kokusai Electric, and Mattson Technology lead the market, benefiting from strong brand recognition, significant financial resources, and established relationships with key semiconductor manufacturers. These companies focus on technological innovation, product customization, and offering high-performance annealing solutions. Smaller players, while contributing to market diversity, face challenges in competing with industry giants due to the high costs of advanced equipment and technical expertise required. The market is characterized by a high degree of specialization, with increasing demand for precision, energy efficiency, and automation. As semiconductor technology evolves, companies must continuously innovate to stay competitive and address the rising complexity of chip designs and manufacturing processes. The growth of new fabrication facilities and technological advancements continues to shape the market’s dynamics.
Report Coverage:
The research report offers an in-depth analysis based on Type of Equipment, Technology, Application, Process Stage, End-User Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing demand for smaller, more powerful semiconductors will drive the need for advanced annealing solutions.
- Rapid advancements in AI, IoT, and 5G technologies will further fuel the market for high-performance semiconductor manufacturing.
- Expansion of semiconductor manufacturing capabilities in regions like North America and Asia-Pacific will boost the demand for annealing equipment.
- Technological innovations in rapid thermal annealing (RTA) and laser annealing will enhance precision and speed in semiconductor production.
- Automation and AI-driven process control systems will be integrated into annealing equipment to improve operational efficiency.
- The transition to more complex semiconductor architectures, including FinFET and 3D NAND, will demand highly specialized annealing technologies.
- Growing environmental concerns will lead to increased focus on energy-efficient and sustainable manufacturing practices in the semiconductor industry.
- The rise of electric vehicles and the automotive electronics sector will further increase the demand for power and logic semiconductor devices.
- Strategic collaborations and partnerships between semiconductor manufacturers and equipment providers will intensify to drive innovation.
- Emerging markets will play a critical role in the expansion of semiconductor infrastructure, increasing demand for cost-effective annealing solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Proliferation of Advanced Consumer Electronics
The increasing complexity and miniaturization of consumer electronics such as smartphones, wearables, and laptops require highly precise annealing processes to enhance chip performance and reliability, driving demand for advanced annealing equipment.
Expansion of Semiconductor Manufacturing Capacity
Global investments in new semiconductor fabrication plants, especially in Asia-Pacific and North America, are directly increasing the need for annealing equipment to support both front-end and back-end processing in expanded production lines.
Technological Advancements in Device Architectures
The shift to advanced semiconductor architectures like FinFET, GAA, and 3D NAND necessitates new annealing methods such as rapid thermal and laser annealing, which offer better uniformity and lower thermal budgets, thus fueling market growth.
Adoption of IoT, AI, and 5G Infrastructure
The global rollout of IoT, AI, and 5G technologies is boosting demand for high-density, low-power chips, which in turn increases the need for precise and reliable annealing solutions to ensure device performance and longevity.
Government and Private Investments in Semiconductor Infrastructure
Strategic investments and incentives from governments and private entities to localize semiconductor production and reduce supply chain risks are accelerating the procurement of advanced annealing equipment, especially in emerging economies.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Semiconductor Annealing Equipment Market?
What factors are driving the growth of the Semiconductor Annealing Equipment Market?
What are some challenges faced by the Semiconductor Annealing Equipment Market?
Who are the major players in the Semiconductor Annealing Equipment Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Technology
- 1.2.1 Optical Technology
- 1.2.2 Contact Technology
- 1.2.3 Non-Contact Technology
- 1.2.4 Hybrid Technology
- 1.3 By Application
- 1.3.1 Memory Devices
- 1.3.2 Logic Devices
- 1.3.3 Power Devices
- 1.3.4 RF Devices
- 1.3.5 Optoelectronics
- 1.4 By End-User Industry
- 1.4.1 Consumer Electronics
- 1.4.2 Telecommunications
- 1.4.3 Automotive
- 1.4.4 Aerospace & Defense
- 1.4.5 Healthcare
- 1.5 By Type of Equipment
- 1.5.1 Rapid Thermal Annealing (RTA)
- 1.5.2 Conventional Furnace Annealing
- 1.5.3 Laser Annealing
- 1.5.4 Plasma Annealing
- 1.5.5 Flash Annealing
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,410.15 million → 2032: USD 3,157.2 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Semiconductor Annealing Equipment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Semiconductor Annealing Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Semiconductor Annealing Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Semiconductor Annealing Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Semiconductor Annealing Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Semiconductor Annealing Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Semiconductor Annealing Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Semiconductor Annealing Equipment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,410.15 million → 2032: USD 3,157.2 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Semiconductor Annealing Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Technology - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Optical Technology
- 12.3.7.2 Contact Technology
- 12.3.7.3 Non-Contact Technology
- 12.3.7.4 Hybrid Technology
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Memory Devices
- 12.4.7.2 Logic Devices
- 12.4.7.3 Power Devices
- 12.4.7.4 RF Devices
- 12.4.7.5 Optoelectronics
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-User Industry - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Consumer Electronics
- 12.5.7.2 Telecommunications
- 12.5.7.3 Automotive
- 12.5.7.4 Aerospace & Defense
- 12.5.7.5 Healthcare
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Type of Equipment - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Rapid Thermal Annealing (RTA)
- 12.6.7.2 Conventional Furnace Annealing
- 12.6.7.3 Laser Annealing
- 12.6.7.4 Plasma Annealing
- 12.6.7.5 Flash Annealing
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Semiconductor Annealing Equipment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Semiconductor Annealing Equipment Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Semiconductor Annealing Equipment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Semiconductor Annealing Equipment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Applied Materials
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Mattson Technology
- 18.4 Kokusai Electric
- 18.5 Centrotherm
- 18.6 JTEKT Thermo Systems Corporation
- 18.7 CVD Equipment Corporation
- 18.8 AnnealSys
- 18.9 ADVANCE RIKO
- 18.10 Koyo Thermo Systems
- 18.11 SemiTEq
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

