
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Semiconductor Advanced Ceramics Market Size 2024 | USD 3,550 million |
| Semiconductor Advanced Ceramics Market, CAGR | 6% |
| Semiconductor Advanced Ceramics Market Size 2032 | USD 5,658 million |
Market Overview:
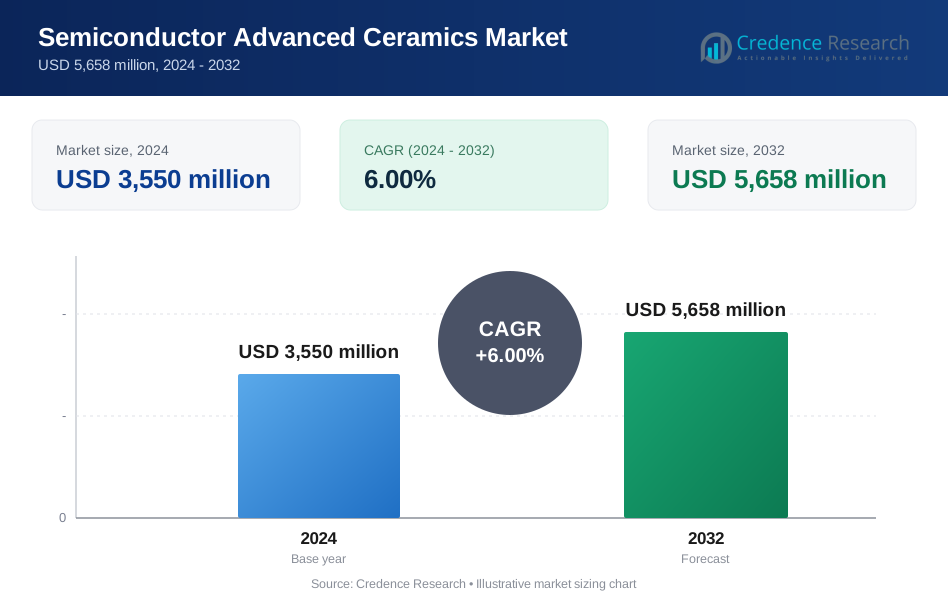
The Semiconductor Advanced Ceramics Market is projected to grow from USD 3,550 million in 2024 to USD 5,658 million by 2032, registering a compound annual growth rate (CAGR) of 6% during the forecast period.
The Semiconductor Advanced Ceramics Market is driven by the rising demand for high-performance materials in semiconductor manufacturing processes, particularly in extreme thermal and corrosive environments. Advanced ceramics offer superior properties such as high thermal conductivity, mechanical strength, and chemical stability, making them ideal for use in wafer processing, deposition equipment, and packaging applications. The market benefits from the ongoing miniaturization of electronic components, the expansion of 5G infrastructure, and the increasing adoption of electric vehicles, all of which require advanced semiconductor devices. Additionally, the growing need for energy-efficient and durable components in consumer electronics and industrial automation supports market expansion. Key trends include the development of next-generation ceramic composites for enhanced durability, increased investment in R&D for precision-engineered ceramic components, and strategic collaborations between ceramic manufacturers and semiconductor companies. The market also witnesses a shift towards eco-friendly and recyclable materials to meet environmental standards, further fueling innovation in ceramic technology tailored for semiconductor applications.
The Semiconductor Advanced Ceramics Market exhibits strong regional concentration, with Asia Pacific holding the largest share due to extensive semiconductor manufacturing activities in China, Japan, South Korea, and Taiwan. North America follows, driven by technological advancements and demand in aerospace, defense, and power electronics, while Europe benefits from innovations in automotive electronics and renewable energy sectors. Other contributing regions include Latin America, the Middle East, and Africa, where market growth remains moderate but promising with expanding industrial bases. Key players operating globally include Coorstek, Kyocera, Ferrotec, NGK Insulators, 3M Ceramics, TOTO Advanced Ceramics, Maruwa, GBC Advanced Materials, MiCo Ceramics Co., Ltd., ASUZAC Fine Ceramics, NGK Spark Plug (NTK Ceratec), and Japan Fine Ceramics Co., Ltd. (JFC). These companies compete on innovation, material quality, application range, and strategic partnerships to serve diverse semiconductor manufacturing requirements across geographies.
Market Insights:
- The Semiconductor Advanced Ceramics Market is projected to grow from USD 3,550 million in 2024 to USD 5,658 million by 2032, registering a CAGR of 6%.
- Rising demand for high-performance materials in wafer etching, deposition, and lithography processes is a primary growth driver.
- Expansion of 5G infrastructure and miniaturization of electronic components are increasing ceramic adoption in RF and power electronics.
- The electric vehicle sector fuels market growth with its need for thermally stable, electrically insulated ceramic components.
- Environmental regulations are driving innovation in recyclable and energy-efficient ceramic technologies.
- Asia Pacific leads the market with 45% share, followed by North America at 25% and Europe at 18%, supported by strong manufacturing and technology ecosystems.
- Key players including Coorstek, Kyocera, Ferrotec, NGK Insulators, and 3M Ceramics compete on innovation, product quality, and global partnerships.
Market Drivers:
Rising Demand for High-Performance Materials in Semiconductor Manufacturing:
The Semiconductor Advanced Ceramics Market is growing due to the increasing need for materials that withstand extreme thermal and chemical environments in semiconductor production. Advanced ceramics offer excellent thermal conductivity, high mechanical strength, and superior resistance to corrosion. These properties are critical in processes like wafer etching, deposition, and lithography. It supports precise manufacturing with minimal contamination. The shift toward smaller, more powerful chips further boosts the demand for reliable ceramic components.
- For instance, Morgan Advanced Materials manufactures custom-engineered ceramic heater substrates and insulators for semiconductor processing, enabling precise temperature control and electrical insulation in high-temperature environments.
Expansion of 5G Infrastructure and Advanced Electronics:
The global rollout of 5G networks has increased the demand for advanced semiconductor devices, driving growth in the Semiconductor Advanced Ceramics Market. It supports critical infrastructure for high-frequency applications where thermal stability and electrical insulation are essential. Ceramics enable high-speed performance and efficient signal transmission in compact devices. As telecom equipment becomes more complex, manufacturers rely on advanced ceramics for durability and heat resistance. This trend accelerates the adoption of ceramic components in RF and power electronics.
- For instance, Qualcomm’s Snapdragon 5G mobile platform integrates advanced ceramic-based packaging to enable high-speed data transmission and efficient heat dissipation in smartphones and IoT devices.
Increasing Electric Vehicle Production and Automotive Electronics:
The rapid growth of electric vehicles (EVs) is contributing significantly to the expansion of the Semiconductor Advanced Ceramics Market. EVs require advanced power semiconductors that operate under high temperatures and voltages. It ensures stable performance and longer service life in powertrain and battery systems. Ceramics offer electrical insulation and thermal management benefits, making them essential in EV component manufacturing. The integration of driver-assistance systems and sensors further elevates ceramic demand in automotive electronics.
Rising Focus on Energy Efficiency and Environmental Compliance:
Stringent regulations on energy efficiency and environmental impact are encouraging the use of advanced ceramics in semiconductor applications. The Semiconductor Advanced Ceramics Market benefits from these policies by supplying eco-friendly materials with long operational life. It helps reduce waste and enhance system reliability. Ceramics support low-energy consumption in devices while maintaining high functional performance. Manufacturers are investing in recyclable and sustainable ceramic technologies to meet evolving global standards. This shift fosters innovation and market growth.
Market Trends:
Integration of Advanced Ceramics in Wafer Processing Equipment:
Manufacturers are increasingly incorporating advanced ceramics into wafer processing tools to improve precision and durability. The Semiconductor Advanced Ceramics Market benefits from this trend by providing materials that resist high temperatures, plasma environments, and corrosive chemicals. It supports critical semiconductor processes such as etching, ion implantation, and deposition. The use of ceramics ensures minimal contamination and prolonged equipment lifespan. This integration enhances yield and production efficiency in semiconductor fabrication.
- For instance, Kyocera supplies fine ceramics for semiconductor processing equipment, such as lightweight, high-rigidity ceramics for lithography tools and plasma-resistant ceramics for etching and deposition equipment, as well as sapphire windows and wafer carrier plates for optical transparency and chemical resistance.
Adoption of Ceramic Substrates in Power Electronics:
Ceramic substrates are gaining traction in power electronics due to their high thermal conductivity and electrical insulation properties. The Semiconductor Advanced Ceramics Market sees growing demand from sectors like electric vehicles, industrial automation, and renewable energy. It enables improved heat dissipation and electrical performance in high-power applications. The shift to wide-bandgap semiconductors like SiC and GaN further drives ceramic substrate adoption. Manufacturers are developing advanced ceramic composites to meet higher performance standards.
- For instance, Remtec has developed metallized ceramic circuits utilized in high-power automotive braking systems and power converters for mobile radar, leveraging ceramic substrates’ ability to handle high voltages and dissipate significant heat in compact, high-density layouts.
Increased Investment in Smart Manufacturing and Automation:
The rise of Industry 4.0 and smart manufacturing practices is reshaping material requirements in the semiconductor industry. The Semiconductor Advanced Ceramics Market is aligning with this trend by offering precision-engineered components that support automated, high-throughput environments. It contributes to process stability and real-time quality control. Ceramics with tight tolerances and minimal thermal expansion are essential in robotic systems and precision tools. Market players are investing in digital technologies to streamline production and ensure consistent material performance.
Growing Emphasis on Sustainability and Eco-Friendly Materials:
Environmental concerns are influencing the development of sustainable ceramic solutions in the semiconductor industry. The Semiconductor Advanced Ceramics Market is responding with recyclable, lead-free, and energy-efficient materials. It supports cleaner manufacturing processes and reduces the ecological footprint of semiconductor production. Regulatory pressures and corporate sustainability goals are driving this transition. Companies are adopting lifecycle analysis and green certification to validate their products. This shift is shaping product innovation and long-term industry competitiveness.
Market Challenges Analysis:
High Production Costs and Complex Manufacturing Processes:
The Semiconductor Advanced Ceramics Market faces significant challenges due to the high cost and complexity of ceramic manufacturing. Producing high-purity, precision-engineered ceramics requires advanced processing techniques and expensive raw materials. It demands strict quality control, which adds to operational costs and lengthens production timelines. Small manufacturing errors can lead to product rejection, increasing waste and reducing efficiency. These challenges limit market entry for new players and constrain economies of scale for existing manufacturers. The reliance on specialized equipment and skilled labor further complicates scalability.
- For instance, CoorsTek manufactures semiconductor ceramic components that demand ultra-fine grinding and polishing after sintering to achieve tolerances within microns, adding substantial labor and equipment costs to each production batch.
Limited Availability of Raw Materials and Supply Chain Constraints:
Raw material scarcity poses another hurdle for the Semiconductor Advanced Ceramics Market. High-purity alumina, silicon carbide, and other ceramic materials depend on limited global sources. It exposes the industry to supply chain disruptions and price volatility. Geopolitical tensions and export restrictions can further impact material availability and production continuity. Manufacturers face difficulties maintaining consistent supply while ensuring quality standards. These constraints hinder timely product delivery and affect the competitiveness of ceramic component suppliers.
Market Opportunities:
The growing demand for AI, IoT, and high-performance computing is creating new growth avenues for the Semiconductor Advanced Ceramics Market. These technologies require advanced chips with greater heat resistance, miniaturization, and operational stability. It drives the need for ceramic materials that maintain performance under extreme thermal and electrical loads. Manufacturers are exploring innovative ceramic designs to support next-generation chip architectures. The rising use of smart sensors and edge computing devices expands the application scope for ceramic substrates and packaging materials. These trends offer strong prospects for market players targeting emerging digital technologies.
The push for renewable energy and advanced aerospace systems opens new opportunities for the Semiconductor Advanced Ceramics Market. Power electronics in solar inverters, wind turbines, and electric propulsion systems require high-durability, thermally stable ceramic components. It supports reliability in harsh and fluctuating environments. The aerospace industry, focused on lightweight and high-efficiency systems, values ceramic materials for insulation and structural applications. Government investments in clean energy and defense modernization enhance the need for high-performance semiconductor ceramics. These developments expand the market’s footprint beyond traditional consumer electronics.
Market Segmentation Analysis:
By Material Type
The Semiconductor Advanced Ceramics Market includes key materials such as Aluminum Nitride (AlN), Silicon Nitride (Si₃N₄), Aluminum Oxide (Al₂O₃), Silicon Carbide (SiC), and Zirconia (ZrO₂). Aluminum Nitride and Silicon Carbide lead demand due to their superior thermal conductivity and mechanical strength. It enables high-performance applications in power electronics and wafer processing. Aluminum Oxide remains widely used for its cost-efficiency and electrical insulation properties. Emerging materials under the "Others" category are gaining traction in specialized applications requiring enhanced resistance and durability.
By Application
Substrates and wafer processing equipment components represent the largest application segments in the Semiconductor Advanced Ceramics Market. Ceramics used in substrates enhance device reliability by providing thermal and electrical stability. It also plays a key role in thermal management, where materials like AlN and SiC support efficient heat dissipation. Packaging materials are seeing increased demand due to the need for miniaturized, high-performance devices. Other applications include structural supports and high-voltage insulation components.
By End-Use
Integrated circuit manufacturing remains the dominant end-use segment in the Semiconductor Advanced Ceramics Market, driven by consistent demand for high-density and low-defect chip production. Power electronics is a fast-growing area, supported by rising adoption of EVs and renewable energy systems. It also finds strong application in optoelectronics for lasers and photonic devices requiring precision and durability. MEMS and sensors are expanding due to increased demand in automotive and consumer electronics sectors. Other end-uses include aerospace and industrial automation.
Segments:
Based on Material Type:
- Aluminum Nitride (AlN)
- Silicon Nitride (Si3N4)
- Aluminum Oxide (Al2O3)
- Silicon Carbide (SiC)
- Zirconia (ZrO2)
- Others
Based on Application:
- Substrates
- Packaging Materials
- Thermal Management
- Wafer Processing Equipment Components
- Others
Based on End-Use:
- Integrated Circuit Manufacturing
- Power Electronics
- Optoelectronics
- MEMS and Sensors
- Others
Based on Manufacturing Process:
- Pressing and Sintering
- Chemical Vapor Deposition (CVD)
- Hot Isostatic Pressing (HIP)
- Others
Based on Property:
- Thermal Conductivity
- Electrical Insulation
- Mechanical Strength
- Chemical Resistance
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia Pacific
Asia Pacific dominates the Semiconductor Advanced Ceramics Market with a market share of 45%. The region benefits from a strong presence of semiconductor manufacturing hubs in China, Japan, South Korea, and Taiwan. It supports demand for high-performance ceramics in wafer processing and IC packaging. Government support, rising investments in electronics manufacturing, and growing electric vehicle production fuel the market. Local suppliers continue to expand capacity to meet domestic and export demand. Rapid industrialization and expanding consumer electronics sectors reinforce the region’s leadership.
North America
North America holds a 25% share in the Semiconductor Advanced Ceramics Market, driven by advanced R&D and high-value semiconductor production. The U.S. leads the region, supported by strong investments in AI, aerospace, and defense-related chip technologies. It sees rising use of ceramics in power electronics and optoelectronics applications. Companies are adopting advanced materials to enhance chip performance and meet stringent quality standards. Strategic collaborations between semiconductor firms and ceramic suppliers support market expansion. Resilient demand in automotive and energy sectors also contributes to growth.
Europe
Europe accounts for 18% of the Semiconductor Advanced Ceramics Market, supported by developments in automotive electronics, renewable energy, and industrial automation. Germany, France, and the Netherlands lead in manufacturing and technology adoption. It relies on high-quality ceramic components to enhance energy efficiency and environmental compliance. Regional suppliers invest in sustainable ceramic materials to align with EU regulations. The market benefits from the region’s focus on decarbonization and digital transformation. Technological innovation and strong export activity sustain long-term growth potential.
Key Player Analysis:
- Maruwa
- GBC Advanced Materials
- NGK Spark Plug (NTK Ceratec)
- ASUZAC Fine Ceramics
- 3M Ceramics
- Coorstek
- MiCo Ceramics Co., Ltd.
- NGK Insulators
- TOTO Advanced Ceramics
- Kyocera
- Japan Fine Ceramics Co., Ltd. (JFC)
- Ferrotec
Competitive Analysis:
The Semiconductor Advanced Ceramics Market features a competitive landscape marked by strong global and regional players focused on technological innovation, product customization, and strategic collaborations. Key companies such as Coorstek, Kyocera, NGK Insulators, and Ferrotec lead the market through continuous investment in material science and precision manufacturing. It reflects a high degree of specialization, where firms differentiate based on thermal stability, electrical insulation, and purity of ceramic components. Players like 3M Ceramics and TOTO Advanced Ceramics leverage diversified portfolios to serve multiple semiconductor applications. Regional players such as MiCo Ceramics and ASUZAC Fine Ceramics strengthen their positions through localized supply and tailored product offerings. Mergers, capacity expansions, and long-term contracts with semiconductor manufacturers are common competitive strategies. The market rewards consistent quality, supply reliability, and alignment with next-generation semiconductor technologies, pushing companies to enhance their R&D capabilities and sustain long-term client relationships in a performance-driven environment.
Recent Developments:
- On February 4, 2025, Kyocera unveiled the world's first Camera-LIDAR fusion sensor with perfect optical alignment, marking a significant advancement in detection technologies for semiconductor and electronics applications.
- On April 10, 2025, Kyocera Fineceramics Europe announced the development of a new high-end ceramic, Starceram N3000 P, and launched a new silicon nitride material, specifically targeting functional and semiconductor applications.
- In April 2023, Kyocera secured a 37-acre plot in Isahaya City, Japan, for the development of a new smart factory dedicated to expanding production of fine ceramic components for semiconductor use.
- In February 2023, MO SCI Corp. finalized the acquisition of 3M's advanced materials division, transferring over 350 proprietary equipment units and intellectual property to its Rolla, Missouri facility.
Market Concentration & Characteristics:
The Semiconductor Advanced Ceramics Market exhibits moderate to high market concentration, with a few global players holding significant shares due to their technological expertise and long-standing industry presence. It is characterized by high entry barriers driven by complex manufacturing processes, capital-intensive production, and stringent quality requirements. Companies compete based on product purity, thermal stability, and application-specific performance. The market favors vertically integrated players who can control the entire value chain, from raw material sourcing to component fabrication. It also demands continuous innovation to meet evolving semiconductor performance standards, particularly in miniaturized and high-power applications. Strong R&D capabilities, intellectual property, and strategic collaborations with semiconductor manufacturers define competitive success. The market shows stable long-term demand, supported by the critical role of ceramics in advanced chip manufacturing, packaging, and thermal management. Geographic presence and the ability to meet regional regulatory standards further influence market positioning and customer loyalty across global supply chains.
Report Coverage:
The research report offers an in-depth analysis based on Material Type, Application, Manufacturing Process, Property and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for advanced ceramics will rise with the increasing complexity of semiconductor devices.
- Manufacturers will focus on developing ceramic materials with higher thermal and mechanical performance.
- Integration of ceramics in next-generation 5G and AI chips will expand significantly.
- Electric vehicle growth will drive the use of ceramics in power electronics and battery systems.
- Companies will invest more in sustainable and recyclable ceramic solutions to meet regulatory goals.
- Regional production capacity will increase to reduce dependence on limited global raw material sources.
- Precision engineering and miniaturization will push innovation in ceramic processing technologies.
- Strategic partnerships between ceramic suppliers and chipmakers will strengthen supply chain resilience.
- Adoption of ceramics in optoelectronics, MEMS, and advanced sensors will gain traction.
- Technological advancements will enable broader use of ceramics in high-frequency and high-power semiconductor applications.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Semiconductor Advanced Ceramics Market?
What factors are driving the growth of the Semiconductor Advanced Ceramics Market?
What are some challenges faced by the Semiconductor Advanced Ceramics Market?
Who are the major players in the Semiconductor Advanced Ceramics Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Semiconductor Advanced Ceramics Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Semiconductor Advanced Ceramics Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,550 million → 2032: USD 5,658 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Semiconductor Advanced Ceramics Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Semiconductor Advanced Ceramics Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Semiconductor Advanced Ceramics Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Semiconductor Advanced Ceramics Market Drivers
- 3.3 Semiconductor Advanced Ceramics Market Restraints & Challenges
- 3.4 Semiconductor Advanced Ceramics Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Semiconductor Advanced Ceramics Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Semiconductor Advanced Ceramics Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Semiconductor Advanced Ceramics category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Semiconductor Advanced Ceramics Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Semiconductor Advanced Ceramics Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Semiconductor Advanced Ceramics market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Semiconductor Advanced Ceramics Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Semiconductor Advanced Ceramics Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Semiconductor Advanced Ceramics Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Semiconductor Advanced Ceramics (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Semiconductor Advanced Ceramics Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Semiconductor Advanced Ceramics Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Semiconductor Advanced Ceramics Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Semiconductor Advanced Ceramics Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Semiconductor Advanced Ceramics Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Semiconductor Advanced Ceramics Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Semiconductor Advanced Ceramics Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Semiconductor Advanced Ceramics Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Semiconductor Advanced Ceramics Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
