
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Silicone Foam Market Size 2024 | USD 1435 Million |
| Silicone Foam Market, CAGR | 3.4% |
| Silicone Foam Market Size 2032 | USD 1813.4 Million |
Market Overview:
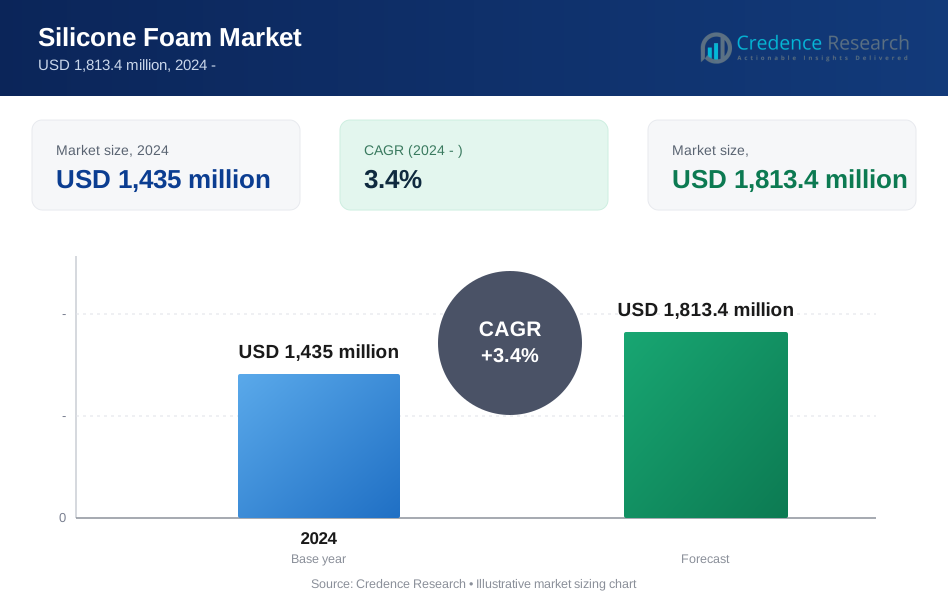
Silicone Foam Market size was valued at USD 1435 million in 2024 and is anticipated to reach USD 1813.4 million by 2032, at a CAGR of 3.4% during the forecast period (2024-2032).
Key drivers propelling the Silicone Foam Market include rising environmental regulations that favor the use of eco-friendly and non-toxic materials, positioning silicone foam as a preferred alternative to traditional foams such as polyurethane. Its excellent resistance to extreme temperatures, UV radiation, and chemical exposure makes it ideal for automotive and electronics applications, where reliability and safety are paramount. The growing focus on energy efficiency and sustainability in construction is further accelerating the adoption of silicone foam as an insulation material. Moreover, expanding research and development activities are driving innovation in silicone foam with improved mechanical properties and multifunctionality, meeting diverse industry demands. Additionally, increased urbanization and infrastructure development, especially in emerging economies, drive the demand for advanced insulation materials in building and construction. Innovation in silicone foam formulations to enhance performance and cost-efficiency is also enabling market players to expand their product portfolios and cater to specialized applications.
Regionally, Asia Pacific dominates the Silicone Foam Market, accounting for over 40% of the global market share in 2024. The region benefits from rapid industrialization, expanding automotive and electronics sectors, and significant infrastructure investments in countries such as China, India, Japan, and South Korea. Government initiatives promoting green building practices and sustainable industrial growth further boost demand for silicone foam products in this region. Additionally, the presence of numerous manufacturing hubs and growing consumer awareness about product durability and safety contribute to the robust market expansion. North America and Europe hold substantial shares as well, driven by stringent environmental standards and strong automotive manufacturing bases. North America is witnessing growth due to rising adoption in healthcare and aerospace industries, while Europe’s market growth is supported by sustainability initiatives and innovation in high-performance silicone foam products. Latin America and the Middle East & Africa are expected to register moderate growth, supported by increasing construction activities and growing awareness of advanced material benefits. Emerging economies in these regions are also investing in infrastructure modernization, which is expected to further fuel demand.
Market Insights:
- The Silicone Foam Market was valued at USD 1,435 million in 2024 and is projected to reach USD 1,813.4 million by 2032, registering a CAGR of 3.4% during the forecast period (2024–2032).
- Rising environmental regulations favoring eco-friendly and non-toxic materials drive demand, positioning silicone foam as a preferred alternative to traditional foams like polyurethane across various industries.
- Its superior resistance to extreme temperatures, UV radiation, and chemicals makes silicone foam ideal for automotive and electronics applications where safety and reliability are critical.
- Rapid urbanization and infrastructure development, particularly in emerging economies, propel demand for advanced insulation materials in construction, supporting energy efficiency and sustainability goals.
- Continuous innovation in silicone foam formulations improves mechanical strength, flame retardancy, and cost-efficiency, expanding its application scope into healthcare, aerospace, and consumer goods.
- The market faces challenges from high production costs and complex manufacturing processes that limit competitiveness, especially in price-sensitive sectors and emerging regions.
- Asia Pacific leads the market with a 42% revenue share in 2024, driven by industrialization and infrastructure growth, while North America (27%) and Europe (21%) show steady growth fueled by strict environmental standards and innovation.
Market Drivers:
Rising Environmental Regulations and Growing Demand for Eco-Friendly Materials Drive Silicone Foam Adoption
The Silicone Foam Market benefits significantly from stringent environmental regulations worldwide that encourage the use of eco-friendly and non-toxic materials. Industries are increasingly shifting away from traditional foams like polyurethane due to their environmental impact. Silicone foam offers superior chemical stability and low toxicity, aligning with regulatory mandates and corporate sustainability goals. It enables manufacturers to meet green building standards and reduce carbon footprints. This regulatory landscape compels various sectors to adopt silicone foam for insulation, gasketing, and sealing applications. Consequently, demand for silicone foam in construction, automotive, and electronics rises steadily.
Exceptional Thermal Stability and Chemical Resistance Boost Usage in Automotive and Electronics Applications
Silicone foam delivers excellent resistance to extreme temperatures, UV radiation, and harsh chemicals, making it an ideal material for automotive and electronic components. It withstands prolonged exposure to heat and weathering without significant degradation, ensuring long-term performance and safety. The material’s flexibility and cushioning properties protect sensitive electronics and vehicle parts from shocks and vibrations. Manufacturers rely on it for engine components, electronic housings, and sealing solutions where reliability is critical. The growth of electric vehicles and smart electronics further fuels demand for high-performance silicone foam materials. It plays a crucial role in enhancing product durability and user safety.
- For instance, Shin-Etsu’s silicone thermal interface materials are used in automotive electronics for their proven long-term reliability under extreme temperatures and vibrations.
Urbanization and Infrastructure Development Propel Demand for Advanced Insulation Materials in Construction Sector
Rapid urbanization and increasing infrastructure projects in emerging economies generate strong demand for advanced building materials. Silicone foam’s superior insulation properties reduce energy consumption and improve building efficiency. It supports sustainable construction by providing thermal and acoustic insulation while maintaining fire resistance. Builders and developers favor silicone foam for roofing, wall panels, and window seals to meet rising energy codes and occupant comfort standards. Expanding commercial and residential construction activities in Asia Pacific, Latin America, and the Middle East stimulate the market’s regional growth. It offers a cost-effective solution to address energy conservation and building safety challenges.
- For instance, Dow’s DOWSIL™ 3-6548 RTV Silicone Foam is used in commercial construction for fire-resistant sealing and insulation, helping buildings meet stringent safety and energy efficiency standards.
Continuous Innovation in Silicone Foam Formulations Enhances Market Penetration and Application Scope
Market players focus on developing new silicone foam formulations that improve mechanical strength, flame retardancy, and processing efficiency. Innovations enable the material to meet specialized application requirements in healthcare, aerospace, and consumer goods sectors. It expands the scope of silicone foam beyond traditional uses to include wearable devices, medical pads, and cushioning products. Improved production techniques reduce costs and increase product availability, making silicone foam more competitive. Collaborative efforts between manufacturers and end-users accelerate adoption by tailoring solutions to specific industry needs. The ongoing innovation supports sustained market growth and diversification.
Market Trends:
Increasing Integration of Smart and Multifunctional Silicone Foam Solutions Expands Application Potential
The Silicone Foam Market experiences a rising trend toward the development of smart and multifunctional silicone foam products that offer enhanced performance characteristics. Manufacturers focus on integrating properties such as self-healing, conductivity, and antimicrobial resistance into foam materials to meet evolving industry demands. It enables use in advanced electronics, healthcare devices, and wearable technology, expanding beyond traditional insulation and cushioning roles. The shift toward lightweight and flexible materials in automotive and aerospace sectors also drives innovation in silicone foam formulations. Companies invest in research to create foams with tailored physical and chemical attributes that support customized applications. This trend promotes broader adoption of silicone foam across high-growth industries and encourages collaboration between material scientists and end-users.
- For instance, in September 2024, Solventum introduced the V.A.C. Peel and Place Dressing—a smart silicone foam dressing designed for rapid application and extended wear, simplifying wound care and enabling remote monitoring in home healthcare settings.
Sustainability and Circular Economy Principles Shape Product Development and Market Expansion
Sustainability continues to influence the Silicone Foam Market significantly, with manufacturers adopting circular economy principles to reduce environmental impact. Efforts to develop recyclable and bio-based silicone foam formulations respond to increasing consumer and regulatory pressure for green products. It supports industries seeking materials that comply with stricter environmental standards without compromising functionality. The growth of green construction and energy-efficient building initiatives further drives demand for sustainable silicone foam products. Market players focus on minimizing waste through improved manufacturing processes and lifecycle management. This trend fosters innovation in eco-friendly materials and encourages wider acceptance of silicone foam in environmentally conscious sectors worldwide.
- For instance, in 2024 Elkem launched a pilot plant in Saint-Fons, France, using depolymerization chemistry to enable circularity for silicone waste, and is advancing projects like RENOV for mechanical recycling, directly supporting the circular economy in silicone foam manufacturing.
Market Challenges Analysis:
High Production Costs and Complex Manufacturing Processes Limit Wider Adoption of Silicone Foam
The Silicone Foam Market faces challenges related to the relatively high production costs compared to conventional foam materials. The complexity of manufacturing processes, including precise temperature and pressure controls, increases operational expenses. It affects pricing competitiveness, especially in price-sensitive end-use industries such as construction and consumer goods. Limited availability of raw materials and dependency on specialized equipment further constrain large-scale production. These factors slow down market penetration in emerging economies where cost efficiency drives purchasing decisions. Manufacturers need to balance quality improvements with cost optimization to overcome this barrier.
- For instance, Dow Inc. has successfully optimized its silicone foam production by integrating advanced automation and precision-controlled curing techniques, reducing operational inefficiencies while maintaining high product quality.
Performance Limitations in Certain Applications and Lack of Industry Standardization Restrict Market Growth
Silicone foam exhibits performance limitations in some high-load or highly abrasive applications, reducing its suitability compared to alternative materials. It may not always provide adequate mechanical strength or abrasion resistance for heavy-duty industrial uses. The lack of universally accepted industry standards and certifications for silicone foam products creates uncertainty among potential users. It complicates product selection and limits adoption across regulated sectors such as aerospace and healthcare. Fragmented regulations across regions also pose compliance challenges for manufacturers aiming at global expansion. Addressing these issues requires focused innovation and collaboration within the supply chain to establish consistent quality benchmarks.
Market Opportunities:
Expanding Applications in Emerging Industries and Technological Advancements Create New Growth Avenues
The Silicone Foam Market presents significant opportunities through expanding applications in emerging sectors such as wearable technology, healthcare devices, and electric vehicles. It offers material properties that meet the specialized requirements of these fast-growing industries, including flexibility, durability, and thermal resistance. Continuous technological advancements enable the development of customized silicone foam formulations tailored to unique application needs. Growth in the electric vehicle sector, in particular, drives demand for lightweight and high-performance insulation materials. Collaborations between silicone foam manufacturers and technology developers foster innovation and accelerate product adoption. This trend opens new revenue streams and enhances market diversification.
Rising Demand for Sustainable and Eco-Friendly Materials Offers Scope for Product Innovation and Market Expansion
Sustainability trends provide the Silicone Foam Market with ample opportunities to develop recyclable and bio-based foam products. It aligns with increasing environmental regulations and consumer preferences for green building materials and eco-conscious manufacturing processes. The focus on circular economy principles encourages manufacturers to design products with reduced environmental impact and enhanced lifecycle performance. Expansion in green construction projects and energy-efficient applications fuels demand for such advanced silicone foam solutions. Market participants that invest in sustainable innovation stand to gain a competitive advantage and access new markets globally. This creates a strategic pathway for long-term growth.
Market Segmentation Analysis:
By Product Type
The Silicone Foam Market divides into open-cell and closed-cell silicone foams. Closed-cell silicone foam leads the market due to its excellent thermal insulation, moisture resistance, and durability. It is widely used in automotive and electronics sectors where sealing and gasketing require high performance. Open-cell silicone foam offers superior cushioning and sound absorption, gaining traction particularly in healthcare and consumer goods. This product type diversity enables manufacturers to address varied industry requirements efficiently.
By Application
The market covers automotive, construction, electronics, healthcare, and other sectors such as aerospace and consumer products. Automotive dominates due to increasing demand for lightweight and heat-resistant materials in electric and traditional vehicles. Construction benefits from silicone foam’s thermal and acoustic insulation, supporting green building and energy efficiency initiatives. Electronics use silicone foam for protective cushioning and thermal management. Healthcare applications expand owing to its biocompatibility and comfort, while other industries adopt it for specialized needs, supporting steady market growth.
By Distribution Channel
Distribution channels consist of direct sales and indirect sales, which include distributors, wholesalers, and online platforms. Direct sales hold a substantial share since manufacturers supply large industrial clients with tailored silicone foam solutions. Indirect sales grow due to rising e-commerce adoption and increased demand from small and medium enterprises. Digital platforms enhance market accessibility and allow manufacturers to broaden their customer reach. These evolving channels support deeper penetration in both developed and emerging markets.
Segmentations:
By Product Type:
- Open-Cell Silicone Foam
- Closed-Cell Silicone Foam
By Application:
- Automotive
- Construction
- Electronics
- Healthcare
- Aerospace
- Consumer Goods
By Distribution Channel:
- Direct Sales
- Distributors
- Wholesalers
- Online Platforms
By End-User:
- Industrial Manufacturers
- Construction Companies
- Healthcare Providers
- Automotive Manufacturers
- Electronics Manufacturers
- Aerospace Companies
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia Pacific Leads Due to Rapid Industrialization and Infrastructure Expansion
Asia Pacific accounts for 42% of the global Silicone Foam Market revenue in 2024, making it the largest regional contributor. The region’s growth stems from rapid industrialization and significant infrastructure development across countries such as China, India, Japan, and South Korea. Strong demand in automotive, electronics, and construction sectors drives adoption of silicone foam products. Government policies encouraging green building and energy-efficient technologies further accelerate market growth. Expanding manufacturing capabilities and increasing consumer awareness about durability and performance support sustained demand. The region also attracts global manufacturers due to its cost-effective production environment and skilled labor force.
North America Holds a Significant Portion Fueled by Healthcare, Aerospace, and Automotive Innovation
North America captures 27% of the global Silicone Foam Market revenue in 2024, supported by established automotive, aerospace, and healthcare industries. Demand in the region focuses on high-performance silicone foam tailored for specialized applications such as electric vehicles and wearable healthcare devices. Strict environmental regulations push the use of eco-friendly and durable silicone foam products. Investments in research and innovation enhance product quality and diversification. The region benefits from a mature market that demands compliance with rigorous quality standards, driving continuous technological advancement.
Europe Demonstrates Consistent Growth Driven by Sustainability and Regulatory Compliance
Europe accounts for 21% of the global Silicone Foam Market revenue in 2024, with steady growth backed by stringent environmental regulations and sustainability initiatives. Automotive and construction sectors lead consumption, focusing on energy-efficient and safe building materials. Rising consumer demand for sustainable and recyclable silicone foam products drives manufacturers to innovate. Strong industrial infrastructure and advanced manufacturing technologies support market expansion. While fluctuating raw material costs pose challenges, the region maintains progress through ongoing compliance efforts and product development.
Key Player Analysis:
- Dow Corning Corporation
- Reiss Manufacturing, Inc.
- Rogers Corporation
- Wacker Chemie AG
- Shin-Etsu Chemical Co., Ltd.
- Armacell International S.A.
- Momentive Performance Materials Inc.
- Elkem ASA
- Auburn Manufacturing, Inc.
- Saint-Gobain Performance Plastics
- Specialty Silicone Products, Inc.
- Stockwell Elastomerics, Inc.
Competitive Analysis:
The Silicone Foam Market features a competitive landscape dominated by several key players focusing on innovation, product quality, and strategic partnerships. Leading companies invest heavily in research and development to enhance foam performance, durability, and sustainability. It experiences ongoing consolidation with mergers and acquisitions aimed at expanding product portfolios and geographic reach. Manufacturers differentiate through customized solutions tailored to automotive, construction, and healthcare sectors. Competitive pricing and efficient supply chain management also play crucial roles in gaining market share. The presence of global and regional players fosters intense competition, driving continuous improvements in technology and customer service. Market leaders prioritize compliance with environmental regulations, enabling them to capitalize on growing demand for eco-friendly silicone foam products. The competitive environment encourages collaboration between suppliers and end-users to meet evolving application requirements, supporting sustained growth and innovation in the market.
Recent Developments:
- In April 2025, Elkem ASA’s Silicones division launched two new 100% recycled silicones-based, solvent-free products—SILCOLEASE® RE POLY 11362 and SILCOLEASE® RE POLY 368—for the label industry.
- In May 2025, Rogers Corporation and Stockwell Elastomerics announced their partnership to provide silicone materials and fabrication expertise for advanced air mobility (AAM) and electric vertical take-off and landing (eVTOL) aircraft applications.
- In April 2025, Saint-Gobain Weber Co., Ltd. (a Saint-Gobain subsidiary), in partnership with Dow and Prepack Thailand, launched an innovative 1-kilogram tile grout package using Dow’s REVOLOOP™ post-consumer recycled resin.
Market Concentration & Characteristics:
The Silicone Foam Market exhibits a moderately concentrated structure with a mix of established global players and emerging regional manufacturers. It is characterized by strong emphasis on innovation, product differentiation, and adherence to environmental regulations. Leading companies maintain competitive advantages through advanced technology, robust R&D capabilities, and strategic collaborations. The market’s growth relies on the ability to deliver customized solutions that meet diverse industry needs, particularly in automotive, construction, and healthcare sectors. It faces challenges related to high production costs and complex manufacturing processes, which create barriers for smaller entrants. However, increasing demand for eco-friendly and high-performance materials encourages investment and expansion. The balance between large corporations’ resources and agility of smaller players drives dynamic competition, fostering continuous improvements in product quality and sustainability within the market.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Application, Distribution Channel, End-User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Expansion in emerging economies will increase demand for silicone foam in construction and automotive sectors due to rapid industrialization and urbanization.
- Advancements in manufacturing technologies will reduce production costs and improve product performance, enhancing market competitiveness.
- Growth in the automotive industry, especially electric vehicles, will drive adoption of silicone foam for insulation, sealing, and vibration damping applications.
- Rising demand in the electronics sector for efficient thermal management will support greater use of silicone foam in consumer and industrial devices.
- Healthcare sector expansion and innovation in medical devices will boost applications of silicone foam in wound care, prosthetics, and cushioning.
- Increased focus on sustainability and stricter environmental regulations will push the development and adoption of eco-friendly silicone foam products.
- Customization of silicone foam products will grow, allowing manufacturers to better meet the specific requirements of diverse industries.
- Integration of smart technologies, such as sensors embedded in silicone foam, will create new functional applications across multiple sectors.
- Strategic partnerships and collaborations among companies will accelerate innovation and enable broader market penetration.
- Continuous investment in research and development will lead to advanced silicone foam materials with enhanced mechanical and chemical properties to satisfy evolving market needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Silicone Foam Market?
What is the expected growth rate of the Silicone Foam Market?
What are the main drivers of Silicone Foam Market growth?
Which region leads the Silicone Foam Market?
What industries are driving demand in North America and Europe?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Silicone Foam Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Silicone Foam Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 1,435 million → forecast year: USD 1,813.4 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Silicone Foam Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Silicone Foam Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Silicone Foam Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Silicone Foam Market Drivers
- 3.3 Silicone Foam Market Restraints & Challenges
- 3.4 Silicone Foam Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Silicone Foam Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Silicone Foam Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Silicone Foam category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Silicone Foam Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Silicone Foam Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Silicone Foam market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Silicone Foam Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Silicone Foam Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Silicone Foam Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Silicone Foam (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Silicone Foam Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Silicone Foam Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Silicone Foam Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Silicone Foam Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Silicone Foam Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Silicone Foam Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Silicone Foam Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Silicone Foam Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Silicone Foam Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
