
Market Overview:
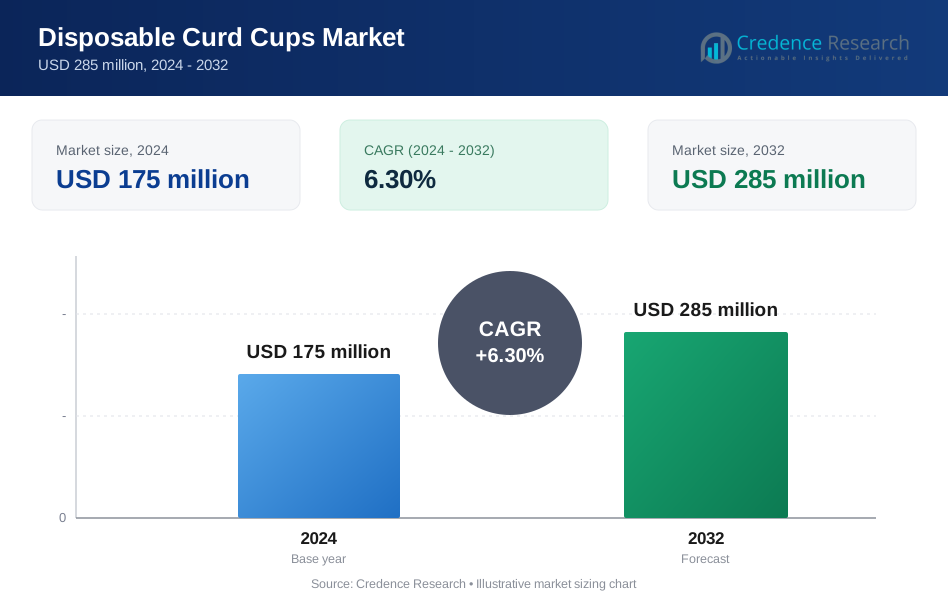
The Disposable curd cups market size was valued at USD 175 million in 2024 and is anticipated to reach USD 285 million by 2032, at a CAGR of 6.3 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Disposable Curd Cups Market Size 2024 | USD 175 million |
| Disposable Curd Cups Market, CAGR | 6.3% |
| Disposable Curd Cups Market Size 2032 | USD 285 million |
Key drivers fueling the disposable curd cups market include growing urbanization, increased demand for hygienic food packaging, and rising awareness around food safety. The surge in consumption of probiotic and fermented dairy products, particularly curd and yogurt, is boosting the demand for single-use, tamper-proof packaging. Changing dietary habits, busy lifestyles, and the rising number of nuclear families contribute to the preference for compact, pre-packed curd units. In parallel, manufacturers are innovating with sustainable and biodegradable cup materials to meet evolving environmental standards. The introduction of recyclable polypropylene (PP), polylactic acid (PLA), and paper-based cups with barrier coatings is creating new growth avenues while addressing regulatory concerns on plastic waste.
Regionally, Asia Pacific dominates the disposable curd cups market, accounting for the highest revenue share due to the high consumption of curd across India, Bangladesh, and Southeast Asia. India represents a key market, driven by a large vegetarian population and strong domestic dairy production, supported by the presence of leading packaging companies such as Huhtamaki Oyj, Graphic Packaging International, Berry Global Inc., WestRock Company, and DUNI AB. North America and Europe are witnessing steady adoption, supported by growing demand for Greek yogurt and dairy snacks. Latin America is emerging as a promising market due to the expanding dairy industry in Brazil and Mexico. The Middle East and Africa show gradual growth, supported by rising dairy processing infrastructure and increasing urban penetration.
Market Insights:
- The Disposable Curd Cups Market was valued at USD 175 million in 2024 and is projected to reach USD 285 million by 2032, growing at a CAGR of 6.3% during 2024–2032.
- Urbanization, food safety awareness, and demand for hygienic, single-serve packaging are key forces driving market adoption.
- Curd and yogurt consumption is rising due to health trends, boosting demand for tamper-evident disposable packaging formats.
- Biodegradable materials such as PLA and coated paperboard are gaining traction amid tightening regulations on single-use plastics.
- Asia Pacific holds 45% market share, led by India and Southeast Asia, supported by high curd consumption and expanding retail access.
- North America and Europe hold 35% share, driven by demand for functional dairy packaging and advancement in sustainable material use.
- Regulatory pressure, raw material price fluctuations, and supply chain constraints remain major challenges for market stability and profitability.
Market Drivers:
Rising Demand for Single-Serve and On-the-Go Dairy Packaging Solutions:
The growing preference for convenience-oriented food packaging is a key driver of the disposable curd cups market. Single-serve dairy products, including curd, appeal to busy urban consumers seeking portion-controlled and hygienic options. These cups support easy portability and minimal handling, making them suitable for school lunches, office meals, and travel consumption. The shift toward compact, ready-to-consume formats has prompted dairy manufacturers to expand their product lines in disposable packaging. It enhances consumer trust by offering tamper-evident seals and extended shelf life. The disposable curd cups market is benefiting from this broader trend in modern food consumption.
- For instance, Dean Foods became the first U.S. company to use Stork aseptic technology to double the shelf life of single-serve flavored milk and coffee beverages, extending it upto 180 days without the need for preservatives.
Expansion of the Organized Dairy Sector and Cold Chain Infrastructure:
The rapid expansion of organized dairy networks and retail cold chain systems is contributing to increased adoption of disposable curd cups. Supermarkets, hypermarkets, and online grocery platforms require standardized and efficient packaging formats to ensure product safety and consistency. These cups support long-distance transportation and cold storage without compromising the integrity of the curd. It enables small and medium-sized dairies to distribute packaged curd across urban and semi-urban markets. The disposable curd cups market is growing in tandem with the modernization of dairy logistics and retail packaging systems.
- For instance, Amul is setting up the world’s largest curd manufacturing facility in Kolkata, with a capacity of 1 million kilograms of curd per day, demonstrating large-scale adoption of standardized curd packaging and distribution.
Consumer Awareness About Food Safety, Hygiene, and Shelf Life:
Rising consumer concern about food safety and hygiene is positively influencing demand for disposable curd cups. Reusable or bulk curd containers are often perceived as less sanitary compared to sealed, single-use options. It protects against contamination and leakage, aligning with the increasing preference for clean-label and tamper-proof dairy packaging. Growing incidences of foodborne illness have heightened awareness around proper packaging standards. The disposable curd cups market is gaining traction among consumers who prioritize safety and convenience in daily food choices.
Sustainability Trends Driving Innovation in Packaging Materials:
The shift toward eco-friendly packaging is reshaping product strategies in the disposable curd cups market. Manufacturers are moving away from traditional plastic toward recyclable and biodegradable materials such as PLA, coated paperboard, and bio-based polymers. It helps align packaging with global regulations on plastic waste reduction and appeals to environmentally conscious consumers. Major dairy brands are incorporating green packaging to differentiate their products and meet retailer sustainability benchmarks. This trend is pushing innovation in material science and driving demand for sustainable curd packaging formats.
Market Trends:
Increased Adoption of Sustainable and Biodegradable Packaging Solutions by Dairy Producers:
A significant trend in the disposable curd cups market is the shift toward environmentally sustainable packaging. Manufacturers are investing in biodegradable and recyclable materials such as paper-based cups with biopolymer linings, polylactic acid (PLA), and molded fiber. These alternatives reduce dependency on conventional plastics and help companies comply with evolving environmental regulations. Dairy brands are highlighting eco-friendly packaging on product labels to attract consumers who value sustainability. It strengthens brand perception and improves market competitiveness. The disposable curd cups market is witnessing growing alignment between environmental goals and packaging innovation.
- For instance, Sidel launched lightweight PET/rPET bottles for liquid dairy products, reducing bottle weight by 5 grams for 150 mL containers and enabling full recyclability within PET systems.
Integration of Advanced Packaging Technologies for Product Differentiation and Shelf Life Extension:
Another emerging trend is the integration of advanced technologies to enhance the performance and appeal of disposable curd cups. Companies are adopting tamper-evident lids, leak-proof sealing, UV protection films, and smart labeling to improve safety and extend shelf life. These features ensure curd remains fresh throughout distribution and consumption cycles. It also enables better product traceability and regulatory compliance. Manufacturers are using thermoformed and injection-molded cups to achieve design precision and printing flexibility for branding. The disposable curd cups market is evolving with enhanced functionality and aesthetics to meet modern retail standards.
- For instance, Greiner Packaging thermoformed T-IML cups achieved a 25% reduction in cup weight-lowering from 15 grams to 11.4 grams-by switching from injection molding to thermoforming, while maintaining high-quality branding and barrier properties for extended shelf life.
Market Challenges Analysis:
Environmental Regulations and Growing Pressure to Eliminate Single-Use Plastics:
One of the primary challenges in the disposable curd cups market is the tightening of global regulations on single-use plastics. Many countries are imposing bans or restrictions on plastic packaging to combat pollution and landfill overflow. It places pressure on manufacturers to shift toward eco-friendly alternatives, which often come with higher production costs. Small and medium-sized dairy producers may struggle to absorb or pass on these costs, affecting profitability. Compliance with multiple regional packaging norms also adds operational complexity. The disposable curd cups market must adapt quickly to avoid disruptions in supply chains and retail distribution.
Fluctuating Raw Material Prices and Supply Chain Constraints:
Volatility in raw material prices presents another major challenge for disposable curd cup manufacturers. Prices of plastic resins, biopolymers, and coated paper fluctuate due to supply chain instability, geopolitical factors, and oil price dynamics. It increases input costs and affects the consistency of production schedules. Supply chain disruptions, especially during global crises, can delay packaging availability and lead to curd wastage. The disposable curd cups market faces the risk of delivery backlogs and reduced inventory turnover, particularly for smaller dairy businesses with limited sourcing options.
Market Opportunities:
Rising Demand for Packaged Curd in Tier 2 and Tier 3 Cities across Emerging Economies:
The expansion of retail infrastructure in smaller cities presents a strong growth opportunity for the disposable curd cups market. Organized dairy brands are targeting semi-urban and rural areas where demand for hygienically packaged curd is increasing. Consumers in these regions are becoming more health-conscious and shifting from loose curd to branded alternatives. It enables dairy producers to extend their market reach and build consumer loyalty through standardized packaging. Growth in cold chain logistics further supports this regional expansion. The disposable curd cups market stands to gain from the untapped potential in these fast-growing consumption zones.
Innovation in Smart and Functional Packaging for Brand Differentiation:
Smart packaging technologies offer new opportunities for brands to differentiate in the competitive dairy space. Features such as QR codes for traceability, tamper-evident lids, and freshness indicators enhance product transparency and consumer trust. It helps brands position themselves as premium and safety-oriented. Functional packaging that combines convenience with sustainability can also attract eco-conscious urban buyers. Innovation in lightweight and space-efficient cup designs can reduce transport costs and improve retail display efficiency. The disposable curd cups market can leverage these advancements to create value-added offerings across diverse retail channels.
Market Segmentation Analysis:
By Material:
The disposable curd cups market features materials such as polypropylene (PP), polystyrene (PS), polyethylene terephthalate (PET), paperboard, and biodegradable plastics. Polypropylene dominates due to its durability, food-grade safety, and cost-effectiveness. Paperboard and PLA-based materials are gaining traction in response to sustainability regulations and consumer demand for eco-friendly options. It supports high compatibility with automated filling lines and maintains product freshness. Material selection significantly influences recyclability, shelf life, and brand positioning across different retail formats.
- For instance, GoodBioPak operates a fully automatic mixing workshop capable of producing 5,200 tons of fully biodegradable, EN-13432 and ASTM D6400 certified PLA material annually, supporting large-scale adoption of compostable cups and food packaging.
By Printing:
The market includes offset, flexographic, and digital printing techniques used for branding and labeling. Flexographic printing leads due to its speed, cost-efficiency, and suitability for large-volume production. Digital printing is growing in small-batch and customized product runs, offering high-resolution graphics and flexibility for seasonal promotions. It allows dairy brands to enhance shelf appeal and maintain regulatory compliance through detailed labeling. Printing quality plays a vital role in consumer perception and product differentiation.
- For instance, modern high-speed flexographic presses, such as those produced by Keshenglong Shinko, can exceed 500 meters per minute, enhancing throughput in industrial applications.
By Capacity:
Disposable curd cups are segmented into small (up to 100 ml), medium (100–200 ml), and large (above 200 ml) capacities. The medium segment holds the highest share due to its alignment with standard single-serve portions. Small cups are popular in institutional catering and meal kits, while large cups cater to families and value-conscious consumers. It helps brands cater to diverse consumer preferences and retail packaging requirements across markets.
Segmentations:
By Material:
- Polypropylene (PP)
- Polystyrene (PS)
- Polyethylene Terephthalate (PET)
- Paperboard
- Polylactic Acid (PLA) and Bioplastics
By Printing:
- Flexographic Printing
- Offset Printing
- Digital Printing
By Capacity:
- Up to 100 ml
- 100–200 ml
- Above 200 ml
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia Pacific :
Asia Pacific holds 45% share of the global disposable curd cups market, driven by high curd consumption in countries such as India, China, and Bangladesh. Rapid urbanization, rising income levels, and increasing adoption of packaged dairy products support sustained market growth across the region. India remains the dominant contributor due to its large vegetarian population and strong reliance on curd as a daily dietary staple. It benefits from a rapidly expanding organized dairy sector and government-backed cold chain infrastructure improvements. Local and regional dairy brands are adopting disposable cups to ensure product hygiene and market penetration in tier 2 and tier 3 cities. Demand is also rising in Southeast Asian markets with growing retail availability and changing food consumption patterns.
North America and Europe:
North America and Europe collectively account for 35% of the global disposable curd cups market, supported by strong demand for ready-to-eat dairy snacks and functional food packaging. In the United States and Canada, consumers value convenience, portion control, and hygienic packaging in products like Greek yogurt and probiotic curd. European countries such as Germany, France, and the UK are advancing sustainable packaging mandates, prompting a shift to biodegradable and recyclable cup formats. It creates opportunities for innovation and premium offerings in the market. Both regions support high penetration of modern retail and strong regulatory compliance, encouraging adoption of advanced packaging formats. Leading brands are investing in eco-friendly material development to align with environmental goals.
Latin America, Middle East, and Africa :
Latin America, the Middle East, and Africa together hold 20% of the disposable curd cups market, with steady gains driven by growing dairy consumption and infrastructure improvements. Brazil and Mexico lead in Latin America, supported by increasing consumer preference for safe and portioned curd packaging. In the Middle East, urbanization and rising demand for refrigerated dairy products support curd cup sales. Africa is witnessing gradual progress as local dairies modernize production and retail distribution systems. It creates future opportunities for multinational brands to expand with cost-effective and sustainable packaging formats. Economic growth and dietary diversification are expected to further support demand across these emerging markets.
Key Player Analysis:
- Huhtamaki Oyj
- Graphic Packaging International etc
- Berry Global Inc.
- WestRock Company
- DUNI AB
- ConverPack Inc.
- Stanpac Inc.
- Dart Container Corporation
- Pactiv LLC
- Georgia-Pacific LLC
Competitive Analysis:
The disposable curd cups market features strong competition among global and regional packaging manufacturers. Key players include Huhtamaki Oyj, Graphic Packaging International, Berry Global Inc., WestRock Company, and DUNI AB. These companies focus on lightweight, recyclable, and food-safe materials to meet hygiene and regulatory standards. It drives innovation in design, barrier protection, and custom printing to support dairy branding needs. Larger firms maintain scale advantages through automated production and global distribution networks, while smaller players serve localized dairy segments with cost-effective offerings. Strategic priorities include expanding biodegradable product lines, securing long-term supply contracts with dairy producers, and investing in sustainable material development. Market competition is shaped by pricing pressure, compliance with environmental policies, and the ability to deliver high-volume, high-quality packaging with minimal lead times.
Recent Developments:
- In November 2024, The company launched next-generation recyclable polypropylene party cups for private-label retail, supporting circular economy goals.
- In June 2025, Duni AB launched the Vista Take-Away Series, offering improved recyclability and functionality with grey plastic bases suitable for modern recycling systems.
- In September 2024, Dart Container Corporation became a PulPac licensee and began installing North America’s first PulPac Scala Dry Molded Fiber line, a technology that supports sustainable food packaging solutions and significantly reduces environmental footprint.
Market Concentration & Characteristics:
The disposable curd cups market is moderately fragmented, with a mix of regional packaging manufacturers and large-scale suppliers catering to dairy producers. It features intense competition based on pricing, material innovation, hygiene standards, and sustainability compliance. Companies focus on lightweight designs, high barrier properties, and custom branding to meet evolving dairy packaging requirements. The market relies heavily on polypropylene, polystyrene, and emerging biodegradable materials. Short product lifecycles and growing regulatory scrutiny are pushing firms to invest in recyclable and compostable solutions. It also exhibits high volume demand, particularly in price-sensitive regions, which influences manufacturing scale and distribution strategies.
Report Coverage:
The research report offers an in-depth analysis based on Material, Printing, Capacity and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- Adoption of biodegradable and compostable materials will accelerate, reducing plastic dependency.
- Manufacturers will integrate smart packaging features like freshness indicators and QR-based traceability.
- Expanded distribution through e‑commerce platforms will enhance market reach in rural and peri‑urban regions.
- Collaborations between packaging suppliers and dairy producers will focus on co-branded eco-friendly solutions.
- Investments in light-weighting techniques will reduce material costs while maintaining structural integrity.
- Modular cup designs with resealable lids will introduce multi-use options without compromising hygiene.
- Investment in packaging automation will improve production efficiency and reduce per-unit costs.
- Regulatory alignment across regions will standardize packaging requirements and streamline cross-border trade.
- Consumer demand for clean-label packaging will push firms toward transparent barrier materials and fewer additives.
- Strategic mergers and acquisitions will consolidate regional players, fostering innovation and cost competitiveness.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Urbanization and Changing Lifestyles
Rapid urbanization and the shift toward nuclear families are increasing the demand for convenient, single-serve curd packaging, as consumers seek hygienic and portable food options for busy routines.
Rising Food Safety and Hygiene Awareness
Growing consumer concern over foodborne illnesses and contamination is driving preference for tamper-evident, disposable curd cups that ensure product safety and extend shelf life.
Growth in Probiotic and Fermented Dairy Consumption
The surge in health-conscious eating and the popularity of probiotic-rich foods like curd and yogurt are boosting demand for single-use, portion-controlled packaging formats.
Sustainability and Regulatory Pressure
Tightening regulations on single-use plastics and increasing consumer demand for eco-friendly packaging are pushing manufacturers to innovate with biodegradable and recyclable materials, expanding market opportunities.
Expansion of Organized Dairy and Cold Chain Infrastructure
The growth of organized dairy sectors and improved cold chain logistics, especially in emerging markets, is enabling wider distribution of packaged curd, fueling demand for standardized disposable cups.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Disposable Curd Cups Market?
What are the key segments within the Disposable Curd Cups Market?
What are some challenges faced by the Disposable Curd Cups Market?
Who are the major players in the Disposable Curd Cups Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Capacity
- 1.2.1 Up to 100 ml
- 1.2.2 100–200 ml
- 1.2.3 Above 200 ml
- 1.3 By Material
- 1.3.1 Polypropylene (PP)
- 1.3.2 Polystyrene (PS)
- 1.3.3 Polyethylene Terephthalate (PET)
- 1.3.4 Paperboard
- 1.3.5 Polylactic Acid (PLA) and Bioplastics
- 1.4 By Printing
- 1.4.1 Flexographic Printing
- 1.4.2 Offset Printing
- 1.4.3 Digital Printing
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 175 million → 2032: USD 285 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Disposable Curd Cups Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Disposable Curd Cups Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Disposable Curd Cups Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Disposable Curd Cups Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Disposable Curd Cups Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Disposable Curd Cups Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Disposable Curd Cups Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Disposable Curd Cups Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 175 million → 2032: USD 285 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Disposable Curd Cups Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Capacity - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Up to 100 ml
- 12.3.7.2 100–200 ml
- 12.3.7.3 Above 200 ml
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Polypropylene (PP)
- 12.4.7.2 Polystyrene (PS)
- 12.4.7.3 Polyethylene Terephthalate (PET)
- 12.4.7.4 Paperboard
- 12.4.7.5 Polylactic Acid (PLA) and Bioplastics
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Printing - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Flexographic Printing
- 12.5.7.2 Offset Printing
- 12.5.7.3 Digital Printing
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Disposable Curd Cups Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Disposable Curd Cups Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Disposable Curd Cups Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Huhtamaki Oyj
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Graphic Packaging International
- 17.4 Berry Global Inc.
- 17.5 WestRock Company
- 17.6 DUNI AB
- 17.7 Dart Container Corporation
- 17.8 Stanpac Inc.
- 17.9 Pactiv LLC
- 17.10 Georgia-Pacific LLC
- 17.11 ConverPack Inc.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

