
Market Overview:
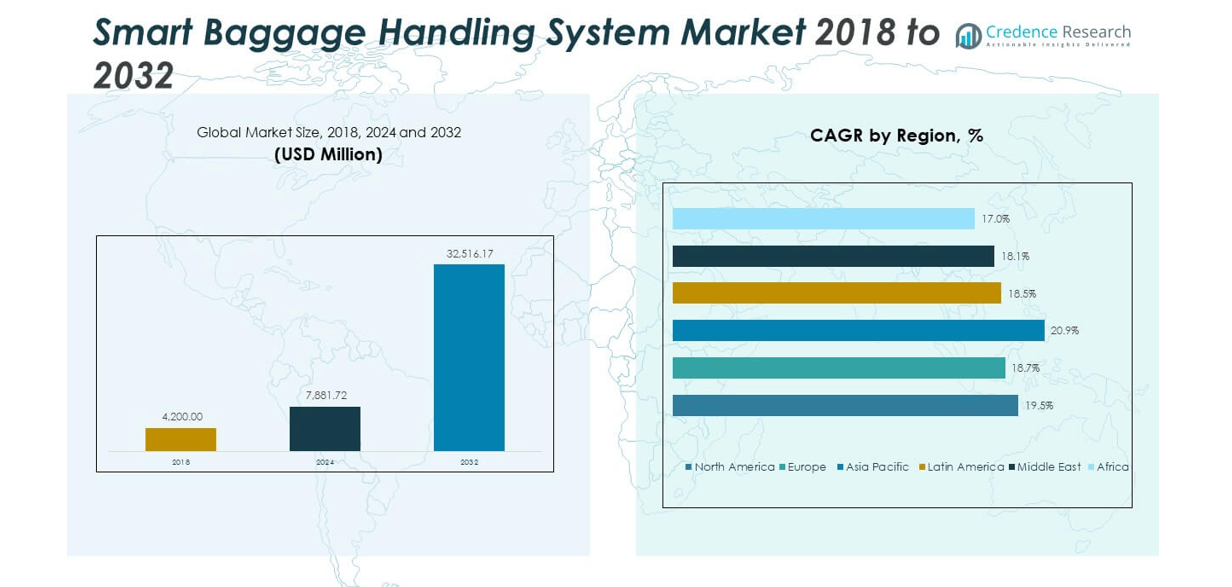
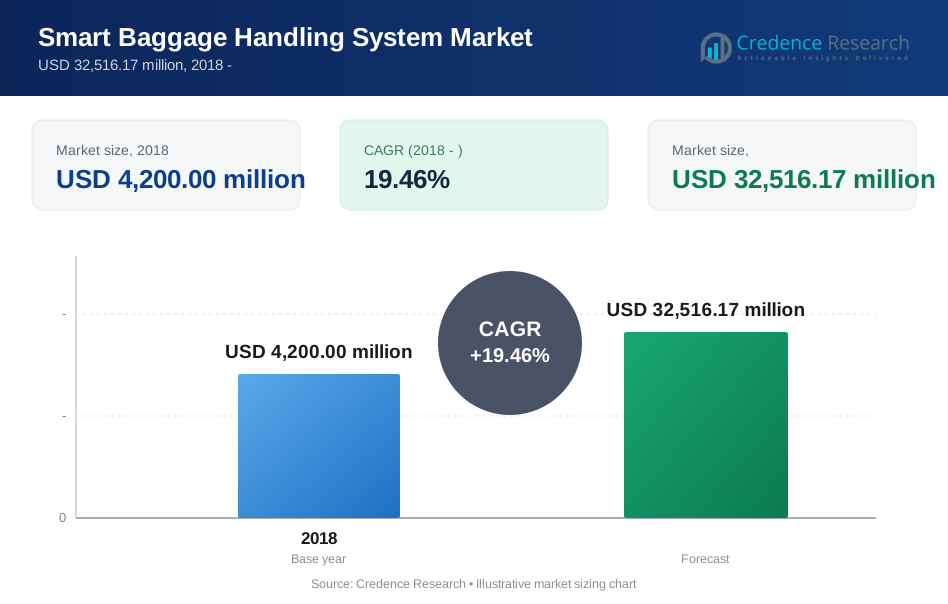
The Global Smart Baggage Handling System Market size was valued at USD 4,200.00 million in 2018 to USD 7,881.72 million in 2024 and is anticipated to reach USD 32,516.17 million by 2032, at a CAGR of 19.46% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Smart Baggage Handling System Market Size 2024 | USD 7,881.72 million |
| Smart Baggage Handling System Market, CAGR | 19.46% |
| Smart Baggage Handling System Market Size 2032 | USD 32,516.17 million |
Market expansion is driven by the aviation industry’s shift toward automation and operational efficiency. Airports are adopting smart baggage handling systems to reduce delays, minimize mishandling, and enhance passenger satisfaction. The integration of IoT, AI, and RFID technologies enables real-time tracking, predictive maintenance, and improved security. Rising air traffic, coupled with investments in airport modernization and smart infrastructure, supports strong demand for these systems globally.
North America and Europe lead the market due to advanced airport infrastructure, early technology adoption, and stringent operational standards. The Asia-Pacific region is emerging rapidly, fueled by expanding aviation networks in China, India, and Southeast Asia. Middle Eastern hubs like Dubai and Doha are also investing heavily in next-generation baggage handling systems to enhance global connectivity. Latin America and Africa are witnessing gradual growth supported by modernization projects and increasing regional air traffic.
Market Insights:
- The Global Smart Baggage Handling System Market size was valued at USD 4,200.00 million in 2018, reached USD 7,881.72 million in 2024, and is projected to attain USD 32,516.17 million by 2032, expanding at a CAGR of 19.46%.
- North America (28%), Asia Pacific (29%), and Europe (24%) hold the top three regional shares due to strong airport automation, digital transformation, and modernization programs.
- Asia Pacific is the fastest-growing region with a 29% share, driven by expanding airport infrastructure, rising passenger traffic, and large-scale smart airport projects in China and India.
- The airport segment dominates with about 55% of the total share, reflecting large-scale adoption of automation and RFID integration in major international hubs.
- The domestic and international segments collectively account for around 45%, supported by increasing regional air connectivity and mid-scale airport upgrades worldwide.
Market Drivers:
Rising Passenger Traffic and Demand for Operational Efficiency:
The Global Smart Baggage Handling System Market is witnessing strong growth due to the rapid rise in global air passenger traffic. Airports face increasing pressure to manage higher baggage volumes while maintaining accuracy and speed. Smart systems powered by automation and digital connectivity improve handling efficiency and minimize delays. Real-time data analytics helps streamline baggage flow and reduce manual errors. Airlines benefit from enhanced turnaround time and better utilization of airport resources. The increasing need for faster processing and seamless travel experiences drives adoption. Major airports are investing in advanced handling infrastructure to maintain competitiveness and passenger trust. This focus on efficiency continues to shape long-term technological investments across the sector.
Adoption of IoT, AI, and RFID Technologies for Real-Time Baggage Tracking:
The integration of Internet of Things (IoT), Artificial Intelligence (AI), and Radio-Frequency Identification (RFID) is transforming baggage management. These technologies enable live monitoring of luggage across every stage of travel. Airlines and airports gain transparency and control over tracking, reducing lost or mishandled baggage incidents. Predictive analytics allows systems to identify bottlenecks and optimize routing. AI enhances sorting accuracy and resource allocation during peak hours. The Global Smart Baggage Handling System Market benefits from these innovations, improving reliability and passenger confidence. Automation reduces dependency on manual labor, ensuring consistency and safety. The growing demand for smart airport ecosystems strengthens the push toward full digital integration.
- For instance, Delta Air Lines deployed RFID baggage tracking at 344 locations, achieving a 99.9% bag tracking success rate. After its global rollout in 2016, this technology contributed to lowering the rate of mishandled baggage, with some reports citing a reduction of approximately 10-13%.
Growing Focus on Passenger Experience and Airport Modernization Programs:
Airports are evolving from transit hubs to experience-driven environments where convenience matters. Passengers expect smoother travel and faster baggage delivery, driving investment in next-generation systems. Modernization programs in major airports emphasize end-to-end automation for check-in, security, and baggage flow. Smart conveyors, scanners, and self-service systems improve operational visibility and reduce waiting times. The Global Smart Baggage Handling System Market supports this transformation through scalable and modular solutions. Governments and airport authorities are allocating budgets to upgrade outdated infrastructure. Improved baggage management directly correlates with passenger satisfaction scores. This growing focus on user experience positions smart systems as critical assets for global airport competitiveness.
Government Investments and Sustainability Goals in Airport Infrastructure:
Governments are funding airport modernization to boost connectivity, tourism, and sustainability. The focus on green airport development encourages adoption of energy-efficient and low-emission handling systems. Automation helps reduce idle time, electricity use, and operational waste. The Global Smart Baggage Handling System Market benefits from such policies supporting smart infrastructure expansion. Public-private partnerships are enabling large-scale upgrades across key aviation hubs. Sustainability certification programs are pushing airports to integrate intelligent systems that optimize energy and resource management. Eco-friendly technologies align with broader national carbon-reduction strategies. The emphasis on long-term operational sustainability drives continued market demand across emerging and developed regions.
Market Trends:
Expansion of Self-Service Technologies and Contactless Airport Operations:
Self-service solutions are becoming standard features in modern airports worldwide. The Global Smart Baggage Handling System Market is benefiting from the shift toward self-check-in kiosks, bag-drop counters, and contactless scanning. Passengers value control over their travel processes, driving adoption across major terminals. Contactless operations gained momentum post-pandemic, focusing on safety and hygiene. Integration of biometric verification and automated baggage tagging enhances operational speed. Airports are redesigning layouts to support seamless passenger flow and reduce congestion. Airlines are collaborating with system providers to ensure compatibility and scalability. These advancements make travel faster, safer, and more efficient for global passengers.
- For instance, Changi Airport's Fast and Seamless Travel (FAST) program was launched with biometric systems in Terminal 4 in 2017 and expanded to passport-free clearance across all terminals in 2024. The newer system has reduced average immigration clearance time for many travelers by 60%, from 25 to 10 seconds. All departing travelers are now eligible for this contactless process, though foreign visitors still present their passport upon arrival.
Integration of Data Analytics and Predictive Maintenance Capabilities:
Data-driven insights are reshaping how airports manage their baggage handling infrastructure. Advanced analytics platforms now track equipment performance and detect maintenance needs before failures occur. Predictive maintenance reduces downtime and improves reliability across complex systems. The Global Smart Baggage Handling System Market is increasingly aligning with this digital trend. Real-time dashboards support decision-making and operational transparency for management teams. Sensors and software integration help identify inefficiencies in baggage routing. Airlines can optimize workforce scheduling and improve service quality. This trend is helping airports move toward smarter, more resilient infrastructure with lower lifecycle costs.
- For instance, Munich Airport and Siemens agreed to a strategic digitalization partnership in March 2018, where Siemens used its Internet of Things (IoT) operating system, MindSphere, to develop applications for the baggage handling system. Siemens had already installed the baggage handling system in Terminal 2, which at the time could sort up to 17,800 pieces of luggage per hour.
Collaborations Between Technology Providers and Airport Operators:
Strategic partnerships are accelerating innovation in baggage handling automation. Airport authorities are working closely with tech firms to design customized systems suited for specific passenger volumes and layouts. The Global Smart Baggage Handling System Market gains momentum from these collaborations, fostering knowledge sharing and rapid implementation. Joint ventures ensure compatibility between legacy equipment and new technologies. Vendors are developing modular platforms that allow phased upgrades without disrupting operations. Airlines benefit from unified solutions that integrate with check-in and security systems. Such partnerships strengthen industry resilience and adaptability in changing operational environments. The collaboration model ensures faster rollout of smart baggage ecosystems globally.
Shift Toward Cloud-Based and AI-Driven System Management:
Cloud computing is transforming how airports manage baggage handling data and performance metrics. The Global Smart Baggage Handling System Market is embracing cloud-based control systems for flexibility and scalability. AI-driven algorithms optimize sorting, loading, and transfer operations in real time. Cloud platforms allow remote monitoring and rapid data sharing between airlines and ground staff. This enables predictive adjustments to manage surges in passenger traffic. The approach lowers hardware dependency and simplifies maintenance. Scalable cloud architectures support multi-airport operations through a centralized management interface. These innovations contribute to cost efficiency and operational excellence across the aviation ecosystem.
Market Challenges Analysis:
High Implementation Costs and Complex Integration with Legacy Infrastructure:
The deployment of smart baggage systems requires large-scale financial commitments from airports. High initial investment and ongoing maintenance costs limit adoption, especially for smaller airports. Integrating modern digital systems with legacy mechanical infrastructure poses technical challenges. The Global Smart Baggage Handling System Market faces delays in implementation due to these constraints. Airports must coordinate multiple vendors, which increases complexity and cost. Compatibility issues between old and new systems often cause downtime and require skilled technical expertise. Limited funding and lengthy procurement cycles slow modernization efforts. Balancing cost efficiency with technology advancement remains a persistent challenge for operators.
Data Security Concerns and Shortage of Skilled Workforce:
The integration of IoT and AI technologies raises cybersecurity and privacy challenges. Large volumes of passenger and operational data create potential vulnerabilities. The Global Smart Baggage Handling System Market faces risk from data breaches and unauthorized access. Maintaining secure communication between interconnected devices demands constant updates and monitoring. Many airports lack trained professionals capable of managing advanced automated systems. The shortage of skilled technicians delays troubleshooting and performance optimization. Frequent system upgrades require continuous training, which adds operational cost. Strengthening cybersecurity and workforce competency is essential for sustainable industry growth.
Market Opportunities:
Rising Airport Modernization Projects Across Emerging Economies:
Developing countries are investing in airport modernization to support growing passenger traffic. Governments in Asia-Pacific, Latin America, and the Middle East are prioritizing automation to enhance service quality. The Global Smart Baggage Handling System Market is positioned to benefit from these upgrades. New airports are being built with smart systems integrated from design to operation. The adoption of advanced technology supports international connectivity and operational resilience. Increasing tourism and economic expansion encourage long-term infrastructure investment. The expansion of aviation networks creates vast opportunities for equipment suppliers and software developers.
Increasing Focus on Seamless Passenger Experience and Real-Time Tracking:
Passenger expectations are shaping the future of baggage management technology. Travelers now demand faster and more transparent baggage tracking through mobile applications. The Global Smart Baggage Handling System Market is capitalizing on this demand by integrating IoT-enabled systems. Real-time tracking improves confidence and reduces passenger anxiety over lost luggage. Enhanced user interfaces and mobile notifications strengthen customer satisfaction. Airlines are adopting digital solutions to align with customer-centric strategies. The opportunity to enhance engagement and brand loyalty through technology remains a key growth driver for global stakeholders.
Market Segmentation Analysis:
By Type of Transportation
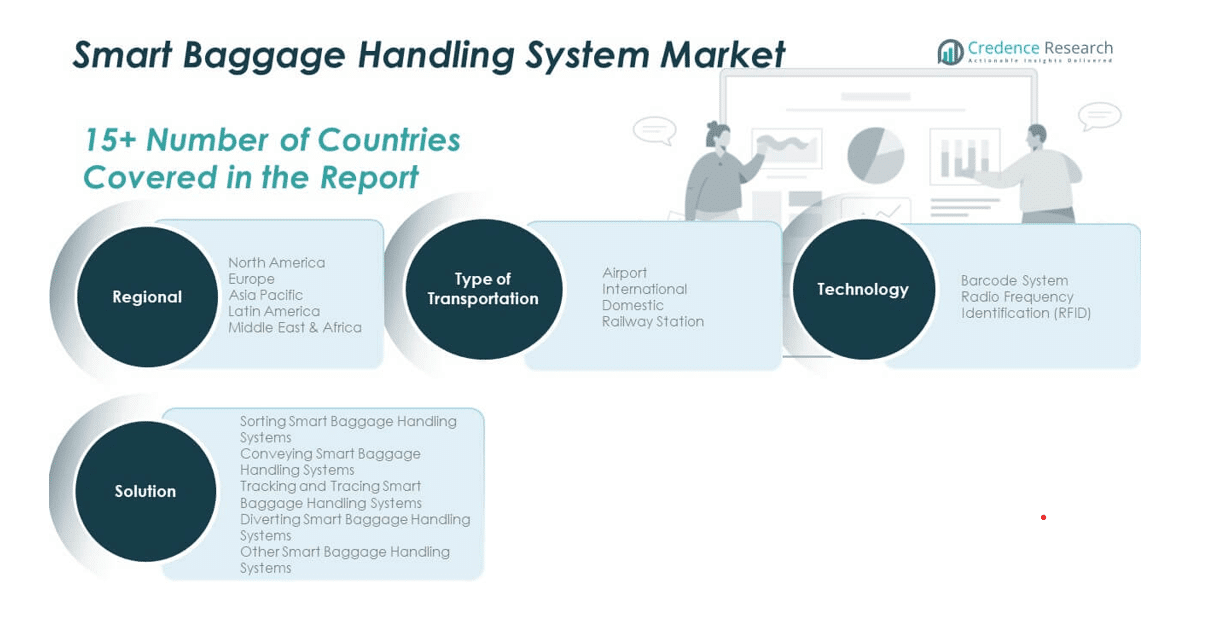
The Global Smart Baggage Handling System Market is segmented into airport, international, domestic, and railway station categories. Airports hold the dominant share due to the growing demand for efficient and automated baggage processing across large hubs. International airports are leading adopters of advanced systems driven by high passenger volumes and global connectivity requirements. Domestic airports are integrating mid-scale automation to reduce turnaround times and improve accuracy. Railway stations are emerging as a new focus area for baggage automation, supported by smart mobility initiatives and increasing intermodal transport integration.
- For instance, Deutsche Bahn's 2024 Integrated Report highlights the completion of the ICE 4 train fleet delivery, making it the largest and most modern fleet in the company's history. The report also details other fleet modernization efforts, such as orders for new ICE 3neo and ICE L trains, the latter featuring step-free entry for enhanced accessibility. The original claim incorrectly mentioned automated baggage handling and mischaracterized the ICE T train modernization, which has been phased out. Efforts to improve accessibility, including tactile orientation aids, are part of ongoing initiatives.
By Technology
The market is classified into barcode systems and radio frequency identification (RFID). Barcode systems remain widely used for their cost efficiency and easy integration into existing airport infrastructure. RFID technology is growing rapidly due to its ability to provide real-time baggage tracking and improve data accuracy. It enhances transparency across baggage movement stages, reducing mishandling and loss incidents. Airports are progressively combining both technologies to achieve redundancy and improve reliability in baggage tracking networks.
- For instance, Hong Kong International Airport (HKIA), a global leader in baggage handling, achieved nearly universal reconciliation compliance (>99%) by upgrading its baggage tagging technology to use Radio Frequency Identification (RFID). This shift significantly improved upon the accuracy of older barcode-only systems and enhanced the resolution of handling issues by providing real-time, highly accurate tracking data.
By End-User
End-user segments include sorting, conveying, tracking and tracing, diverting, and other smart baggage handling systems. Sorting systems dominate due to their role in managing complex routing and minimizing transfer errors. Conveying systems ensure smooth movement between terminals and aircraft zones. Tracking and tracing systems are gaining traction for improving passenger experience through live baggage status updates. Diverting systems and other specialized components support customization for various airport sizes and operational capacities, driving comprehensive system adoption.
Segmentation:
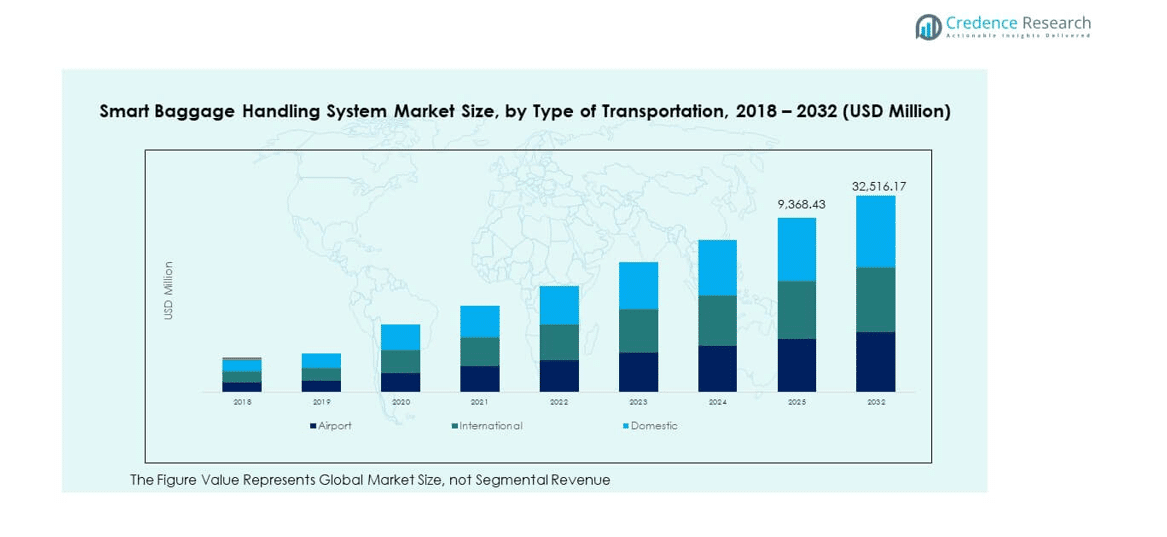
- By Type of Transportation
- Airport
- International
- Domestic
- Railway Station
- By Technology
- Barcode System
- Radio Frequency Identification (RFID)
- By End-User
- Sorting Smart Baggage Handling Systems
- Conveying Smart Baggage Handling Systems
- Tracking and Tracing Smart Baggage Handling Systems
- Diverting Smart Baggage Handling Systems
- Other Smart Baggage Handling Systems
- By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
- North America
Regional Analysis:
North America
The North America Global Smart Baggage Handling System Market size was valued at USD 1,369.20 million in 2018 to USD 2,534.71 million in 2024 and is anticipated to reach USD 10,441.00 million by 2032, at a CAGR of 19.5% during the forecast period. North America accounts for nearly 28% of the global share, driven by strong adoption of airport automation and digital transformation initiatives. The United States dominates with major airports integrating IoT-based tracking and RFID-enabled baggage management. High passenger traffic and regulatory focus on operational safety accelerate investment in smart systems. Canada follows with modernization projects at key airports like Toronto and Vancouver. Airlines are emphasizing seamless travel experiences supported by data-driven baggage tracking. Partnerships between system providers and aviation authorities strengthen regional growth. North America remains a technology hub for innovation, influencing global adoption patterns.
Europe
The Europe Global Smart Baggage Handling System Market size was valued at USD 1,238.16 million in 2018 to USD 2,242.92 million in 2024 and is anticipated to reach USD 8,797.34 million by 2032, at a CAGR of 18.7% during the forecast period. Europe represents about 24% of the market, supported by the presence of advanced airport infrastructure and established system suppliers. The UK, Germany, and France are leading markets implementing fully automated baggage flow solutions. European airports focus on improving passenger convenience and sustainability, aligning with EU digital aviation policies. The integration of RFID and AI-driven predictive systems enhances transparency and reliability. Expanding air connectivity and tourism recovery continue to fuel adoption. Governments support smart airport projects under broader digital transformation goals. This mature regional ecosystem ensures consistent demand for innovative handling technologies.
Asia Pacific
The Asia Pacific Global Smart Baggage Handling System Market size was valued at USD 1,012.20 million in 2018 to USD 1,984.98 million in 2024 and is anticipated to reach USD 9,049.27 million by 2032, at a CAGR of 20.9% during the forecast period. Asia Pacific contributes around 29% of the global share, led by rapid infrastructure growth in China, India, and Japan. Expanding passenger volumes and new airport constructions drive large-scale deployments of smart baggage systems. Governments are investing heavily in digital aviation infrastructure to enhance capacity and efficiency. China’s major hubs like Beijing and Shanghai are setting benchmarks for automation. India is witnessing strong growth under airport privatization and modernization programs. Southeast Asia is emerging as a hotspot with increasing adoption in Singapore, Thailand, and Malaysia. The region’s pace of technological advancement positions it as the fastest-growing global market.
Latin America
The Latin America Global Smart Baggage Handling System Market size was valued at USD 302.40 million in 2018 to USD 562.68 million in 2024 and is anticipated to reach USD 2,174.36 million by 2032, at a CAGR of 18.5% during the forecast period. Latin America holds roughly 9% of the global share, supported by increasing aviation activity and modernization of regional airports. Brazil and Mexico are leading countries investing in smart infrastructure to enhance passenger processing efficiency. Growing tourism and expanding low-cost carriers are improving air connectivity. Airports in Chile and Colombia are integrating automation for baggage tracking and security enhancement. The focus on reducing baggage mishandling and improving turnaround times drives adoption. Government-backed infrastructure upgrades and international collaborations accelerate growth. Latin America’s market outlook remains positive with gradual technology diffusion across emerging hubs.
Middle East
The Middle East Global Smart Baggage Handling System Market size was valued at USD 176.40 million in 2018 to USD 312.06 million in 2024 and is anticipated to reach USD 1,174.01 million by 2032, at a CAGR of 18.1% during the forecast period. The Middle East captures nearly 6% of the global share, dominated by world-class hubs in Dubai, Doha, and Abu Dhabi. These airports prioritize operational excellence and passenger comfort through high-end baggage automation. Smart tracking, AI-powered sorting, and RFID tagging are integral to their systems. Strong investment in aviation under national vision programs sustains growth momentum. The region’s role as a global transit hub supports continuous technology upgrades. Collaboration with leading global suppliers ensures advanced implementation standards. Strategic expansion of airport capacity across the Gulf region continues to fuel the adoption of intelligent baggage systems.
Africa
The Africa Global Smart Baggage Handling System Market size was valued at USD 101.64 million in 2018 to USD 244.37 million in 2024 and is anticipated to reach USD 880.19 million by 2032, at a CAGR of 17.0% during the forecast period. Africa contributes about 4% of the global share, with growing demand for efficient baggage management at major international airports. South Africa leads adoption through modernization of Johannesburg and Cape Town airports. Egypt and Nigeria are investing in automation to handle rising passenger traffic and improve reliability. Regional governments are prioritizing aviation upgrades under infrastructure development programs. The introduction of RFID and barcoding systems enhances baggage tracking capabilities. Partnerships with international technology providers are expanding implementation capacity. Africa’s gradual adoption pace indicates strong long-term growth potential in the global market landscape.
Key Player Analysis:
- Siemens AG
- Vanderlande Industries B.V.
- Daifuku Co., Ltd.
- BEUMER Group
- Honeywell International Inc.
- Alstef Group SAS
- Pteris Global Limited
- Lyngsoe Systems AS
- FIVES Group
- G&S Airport Conveyor
- Logplan LLC
- Smiths Detection Group Ltd.
- ADB Safegate BV
Competitive Analysis:
The Global Smart Baggage Handling System Market is highly competitive, featuring established players with strong technological capabilities and global presence. It is driven by leading companies such as Siemens AG, Vanderlande Industries, Daifuku Co., Ltd., and BEUMER Group, which dominate through innovation and long-term airport partnerships. Firms are focusing on automation, RFID integration, and AI-enabled tracking systems to enhance efficiency and reduce mishandling rates. Strategic collaborations with airports and government authorities are common to expand deployment. New entrants are emphasizing modular and energy-efficient systems to capture emerging markets. The competitive landscape is marked by continuous R&D investments and service expansion across developed and developing regions.
Recent Developments:
- In May 2025, Vanderlande Industries B.V. completed a major acquisition by taking over Siemens Logistics, a prominent provider of baggage and cargo handling solutions for airports. This transaction, valued at €300 million and set for regulatory closure by the end of 2025, will significantly enhance Vanderlande’s technology offering and global presence in automated airport logistics.
- In April 2024, Daifuku Co., Ltd. executed an absorption-type merger of its wholly owned subsidiary Iwasaki Seisakusho Co., Ltd., aiming to centralize management resources and increase operational efficiency, a strategy aligned with strengthening its baggage automation and cleanroom logistics segments.
- In September 2025, BEUMER Group reinforced its push towards digital transformation by integrating the digital companies Codept and Elara fully into its structure. Both companies, initially spun off from the in-house incubator Beam, offer cutting-edge digital products that will enhance BEUMER’s automation, transparency, and maintenance offerings for logistics and airport baggage handling clients.
- In May 2025, Honeywell International Inc. announced the acquisition of Johnson Matthey’s Catalyst Technologies business for £1.8 billion, expanding Honeywell’s footprint in catalyst and process technologies and reinforcing its offerings in sectors including airport infrastructure.
Report Coverage:
The research report offers an in-depth analysis based on transportation type, technology, and end-user segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Integration of AI and IoT will redefine airport operational efficiency.
- RFID and sensor-based technologies will become standard for baggage tracking.
- Emerging economies will witness rapid adoption through new airport projects.
- Automation upgrades in existing airports will fuel recurring revenue.
- Demand for cloud-based monitoring and predictive analytics will rise.
- Sustainability and energy-efficient systems will influence procurement decisions.
- Cross-border partnerships will expand to support global aviation recovery.
- Passenger experience enhancement will remain a key investment focus.
- Modular and scalable designs will dominate future procurement trends.
- Continuous innovation will shape long-term competitiveness across all regions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Passenger Traffic and Demand for Operational Efficiency
The surge in global air travel is increasing baggage volumes, putting pressure on airports to handle luggage more efficiently. Smart baggage handling systems powered by automation and digital connectivity streamline baggage flow, reduce delays, and minimize manual errors, directly supporting operational efficiency.
Adoption of IoT, AI, and RFID Technologies
The integration of IoT, AI, and RFID enables real-time baggage tracking, predictive maintenance, and improved security. These technologies reduce mishandling rates, enhance transparency, and allow airports and airlines to optimize resource allocation, driving widespread adoption of smart baggage systems.
Airport Modernization and Government Investments
Governments and airport authorities are investing heavily in modernization programs to boost connectivity, sustainability, and passenger experience. Funding for smart infrastructure and automation upgrades is accelerating the deployment of advanced baggage handling systems, especially in emerging markets.
Focus on Passenger Experience and Seamless Travel
Airports are prioritizing end-to-end automation and self-service technologies to enhance passenger satisfaction. Smart baggage handling systems reduce waiting times, improve baggage delivery speed, and provide real-time tracking, which directly correlates with higher passenger satisfaction and loyalty.
Expansion of Self-Service and Contactless Technologies
The shift toward self-check-in kiosks, automated bag-drop counters, and contactless scanning is transforming airport operations. These solutions, supported by smart baggage handling systems, improve safety, reduce congestion, and enable faster, more convenient travel experiences.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the size of Smart Baggage Handling System Market?
At what Compound Annual Growth Rate is the Global Smart Baggage Handling System Market projected to grow between 2025 and 2032?
What drives the growth of the Smart Baggage Handling System market?
Which regions lead the market?
What challenges do smart baggage handling systems face?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Sorting Smart Baggage Handling Systems
- 1.2.2 Conveying Smart Baggage Handling Systems
- 1.2.3 Tracking and Tracing Smart Baggage Handling Systems
- 1.2.4 Diverting Smart Baggage Handling Systems
- 1.2.5 Other Smart Baggage Handling Systems
- 1.3 By Technology
- 1.3.1 Barcode System
- 1.3.2 Radio Frequency Identification (RFID)
- 1.4 By Type of Transportation
- 1.4.1 Airport
- 1.4.2 International
- 1.4.3 Domestic
- 1.4.4 Railway Station
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 4,200.00 million → 2032: USD 32,516.17 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Smart Baggage Handling System Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Smart Baggage Handling System Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Smart Baggage Handling System Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Smart Baggage Handling System Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Smart Baggage Handling System Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Smart Baggage Handling System Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Smart Baggage Handling System Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Smart Baggage Handling System Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 4,200.00 million → 2032: USD 32,516.17 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Smart Baggage Handling System Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Sorting Smart Baggage Handling Systems
- 12.3.7.2 Conveying Smart Baggage Handling Systems
- 12.3.7.3 Tracking and Tracing Smart Baggage Handling Systems
- 12.3.7.4 Diverting Smart Baggage Handling Systems
- 12.3.7.5 Other Smart Baggage Handling Systems
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Barcode System
- 12.4.7.2 Radio Frequency Identification (RFID)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Type of Transportation - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Volume Forecast, 2018-2032
- 12.5.5 Base-Year Market Share, 2018
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Airport
- 12.5.7.2 International
- 12.5.7.3 Domestic
- 12.5.7.4 Railway Station
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Smart Baggage Handling System End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Smart Baggage Handling System Geographic Market Outlook, 2018-2032
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Smart Baggage Handling System Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Smart Baggage Handling System Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Siemens AG
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Vanderlande Industries B.V.
- 18.4 Daifuku Co., Ltd.
- 18.5 BEUMER Group
- 18.6 Honeywell International Inc.
- 18.7 Alstef Group SAS
- 18.8 Pteris Global Limited
- 18.9 Lyngsoe Systems AS
- 18.10 FIVES Group
- 18.11 Smiths Detection Group Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

