
Market Overview
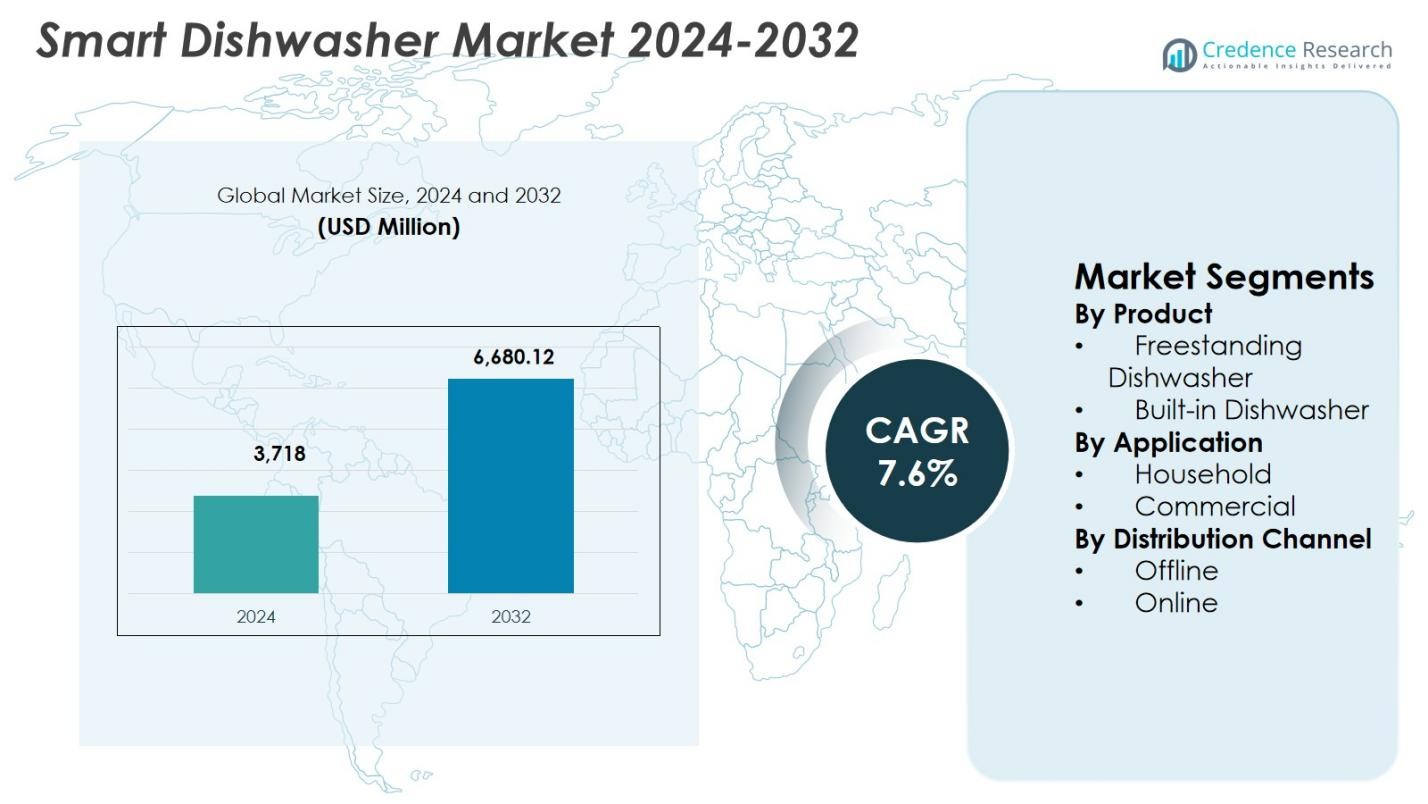
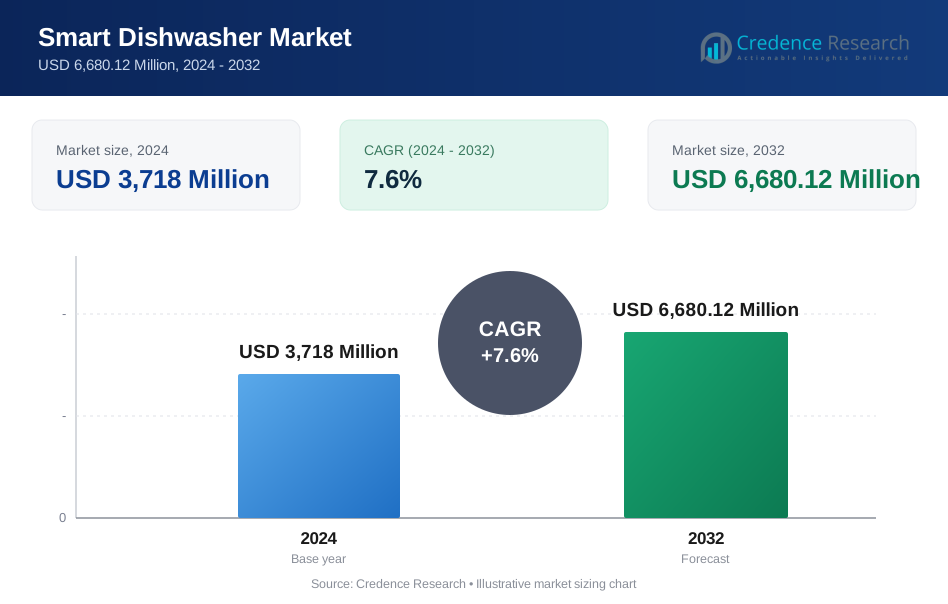
Smart Dishwasher Market size was valued at USD 3,718 Million in 2024 and is anticipated to reach USD 6,680.12 Million by 2032, growing at a CAGR of 7.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Smart Dishwasher Market Size 2024 | USD 3,718 Million |
| Smart Dishwasher Market, CAGR | 7.6% |
| Smart Dishwasher Market Size 2032 | USD 6,680.12 Million |
Smart Dishwasher Market is driven by strong participation from leading appliance manufacturers such as LG Electronics, Samsung Electronics Co., Ltd., Whirlpool Corporation, Robert Bosch GmbH, Siemens AG, Haier Group Corporation, Miele & Cie. KG, Beko, General Electric Company, and Smeg S.p.A. These companies focus on smart connectivity, AI-enabled wash technologies, and energy-efficient designs to strengthen their product portfolios and expand global reach. Continuous investments in innovation, premium built-in models, and smart home integration support brand differentiation and customer retention. Regionally, North America leads the Smart Dishwasher Market with a 34.2% share, supported by high smart home adoption and strong consumer spending on advanced appliances, followed by Europe and Asia-Pacific, which benefit from sustainability regulations and rapid urbanization, respectively.
Market Insights
- Smart Dishwasher Market was valued at USD 3,718 Million in 2024 and is projected to reach USD 6,680.12 Million by 2032, growing at a CAGR of 7.6% during the forecast period, driven by smart appliance adoption and premium kitchen upgrades.
- Market growth is driven by rising smart home penetration, increasing focus on water and energy efficiency, and growing demand from urban dual-income households seeking automated and time-saving appliances.
- Key market trends include integration of AI and IoT technologies, expansion of online distribution channels, and increasing preference for built-in smart dishwashers, which held 6% segment share in 2024 due to modular kitchen adoption.
- Major players focus on product innovation, smart ecosystem compatibility, premium feature expansion, and omnichannel presence to strengthen brand positioning and customer engagement across regions.
- Regionally, North America led with 34.2% share in 2024, followed by Europe at 29.6% and Asia-Pacific at 24.1%, while household applications dominated with 4% share, reflecting strong residential demand.
Market Segmentation Analysis:
By Product
By product, the Smart Dishwasher Market is led by Built-in Dishwashers, which accounted for 58.6% market share in 2024. Built-in models gain strong adoption due to their seamless integration with modular kitchens, premium aesthetics, and compatibility with smart home ecosystems. Rising urbanization, increasing penetration of smart kitchens, and higher spending on premium home appliances drive demand for built-in variants. These products also offer advanced features such as Wi-Fi connectivity, AI-based wash cycles, and energy optimization, strengthening consumer preference. Freestanding dishwashers maintain steady demand, supported by flexibility and lower installation requirements.
- For instance, Siemens built-in dishwashers incorporate the Intelligent Programme, which learns from user feedback via the Home Connect app to adjust wash settings for optimal cleaning and drying.
By Application
By application, the Household segment dominated with a 71.4% share in 2024, reflecting rising adoption of smart appliances in residential settings. Growth is driven by increasing dual-income households, time-saving preferences, and rising awareness of water and energy efficiency. Smart dishwashers offer remote monitoring, automated detergent dosing, and customized wash programs, enhancing user convenience. Expanding smart home adoption and higher disposable incomes further support household demand. The commercial segment shows consistent growth, supported by restaurants and hotels focusing on hygiene standards, operational efficiency, and reduced manual labor dependency.
- For instance, GE Profile Smart Dishwashers integrate with the SmartHQ app for remote cycle control and automatic detergent reordering based on usage tracking.
By Distribution Channel
By distribution channel, Offline retail held a 62.8% market share in 2024, driven by consumer preference for physical product inspection, in-store demonstrations, and after-sales support. Specialty appliance stores and brand-owned outlets play a key role in influencing purchase decisions for high-value smart dishwashers. Offline channels also benefit from professional installation services and bundled warranty offerings. The online segment continues to expand due to competitive pricing, wider product availability, and digital promotions, supported by increasing consumer trust in e-commerce platforms and doorstep installation services.
Key Growth Driver
Rising Adoption of Smart Home Ecosystems
The expansion of smart home ecosystems is a major growth driver for the Smart Dishwasher Market. Increasing integration of appliances with IoT platforms, voice assistants, and centralized home management systems enhances user convenience and control. Smart dishwashers offer remote operation, cycle optimization, and real-time performance monitoring, aligning with connected living trends. Growing consumer preference for automation, combined with rising penetration of smart kitchens in urban households, supports sustained demand. Manufacturers continue to enhance compatibility with major smart home platforms, strengthening product value and accelerating adoption across residential environments.
- For instance, LG's 2018 dishwashers, equipped with ThinQ technology, allow Wi-Fi control via the ThinQ app or voice commands through Alexa and Google Assistant. Owners start, stop cycles, check remaining time, and get completion alerts remotely.
Increasing Focus on Water and Energy Efficiency
Rising awareness of water conservation and energy efficiency strongly drives the Smart Dishwasher Market. Smart dishwashers optimize water usage, adjust cycle duration, and reduce electricity consumption through sensor-based load detection and AI-driven wash programs. Regulatory emphasis on energy-efficient appliances and consumer demand for lower utility costs further reinforce adoption. These systems appeal to environmentally conscious buyers seeking sustainable household solutions. Continuous improvements in energy ratings and efficiency-focused product innovation enhance long-term market growth and support replacement demand for conventional dishwashers.
- For instance, Bosch dishwashers utilize only 7 liters of water per wash cycle through efficient rinsing technology. Their ActiveWater system enhances water circulation and quick heating to minimize overall consumption while ensuring clean results.
Urbanization and Changing Lifestyles
Rapid urbanization and evolving consumer lifestyles significantly support growth in the Smart Dishwasher Market. Increasing numbers of dual-income households and busy urban professionals prioritize time-saving and automated appliances. Smart dishwashers reduce manual effort while maintaining high hygiene standards, aligning with modern living requirements. Growth in modular kitchens and premium residential developments further accelerates adoption. Rising disposable incomes in urban regions also encourage spending on smart appliances, positioning smart dishwashers as essential components of contemporary households.
Key Trend & Opportunity
Integration of AI and Advanced Sensors
The integration of artificial intelligence and advanced sensors represents a key trend and opportunity in the Smart Dishwasher Market. AI-driven algorithms enable adaptive wash cycles, load recognition, and predictive maintenance, improving performance and durability. Sensor-based technologies enhance water efficiency and cleaning accuracy, delivering consistent results across varying load types. These innovations create differentiation opportunities for manufacturers and support premium product positioning. As AI capabilities improve, smart dishwashers can offer enhanced personalization, strengthening consumer engagement and long-term value creation.
- For instance, Hobart's SMART VISION CONTROL uses AI to identify each item loaded onto the conveyor, adjusting wash parameters instantly based on more than 80,000 training images for optimal results and reduced water and chemical consumption.
Expansion of Online Sales Channels
The rapid expansion of online sales channels creates strong growth opportunities for the Smart Dishwasher Market. E-commerce platforms provide consumers with broader product choices, transparent pricing, and detailed feature comparisons. Digital marketing, virtual demonstrations, and easy financing options enhance purchase confidence for high-value appliances. Online channels also enable manufacturers to reach emerging urban and semi-urban consumers efficiently. Continued improvements in logistics, installation support, and after-sales service further strengthen online adoption and accelerate market penetration.
- For instance, LG offers Wi-Fi-enabled smart dishwashers with SmartThinQ technology, allowing remote monitoring and control via the LG ThinQ app on smartphones, even when users are away from home.
Key Challenge
High Initial Cost and Price Sensitivity
High initial costs remain a significant challenge for the Smart Dishwasher Market. Advanced connectivity features, AI integration, and premium components increase product pricing, limiting affordability for price-sensitive consumers. In developing regions, high upfront investment discourages adoption despite long-term efficiency benefits. Consumers often compare smart dishwashers with conventional alternatives, slowing conversion rates. Addressing this challenge requires cost optimization, flexible financing options, and stronger communication of long-term savings to improve market accessibility.
Limited Consumer Awareness and Adoption Barriers
Limited consumer awareness poses a key challenge to the Smart Dishwasher Market, particularly in emerging economies. Many potential buyers lack familiarity with smart features, usage benefits, and maintenance requirements. Concerns related to installation complexity, connectivity reliability, and data security further hinder adoption. In some regions, cultural preferences for manual dishwashing persist. Overcoming these barriers requires focused consumer education, in-store demonstrations, and improved after-sales support to build trust and accelerate acceptance of smart dishwasher solutions.
Regional Analysis
North America
North America accounted for 34.2% market share in 2024 in the Smart Dishwasher Market, supported by high smart home adoption and strong consumer spending on premium appliances. The region benefits from widespread penetration of connected home ecosystems, advanced digital infrastructure, and high awareness of energy-efficient appliances. Consumers increasingly prefer smart dishwashers with AI-based wash cycles, remote monitoring, and voice assistant compatibility. Replacement demand for conventional dishwashers remains strong, driven by lifestyle upgrades. The presence of leading appliance manufacturers and well-established distribution networks further strengthens regional market performance.
Europe
Europe held a 29.6% market share in 2024, driven by stringent energy-efficiency regulations and strong sustainability awareness. Consumers across Germany, the UK, France, and Italy prioritize water-saving and low-energy appliances, accelerating adoption of smart dishwashers. Built-in smart dishwashers are widely integrated into modular kitchens, supporting premium segment growth. Government-backed energy labeling programs and eco-design standards encourage replacement of older models. High urbanization levels, growing smart kitchen installations, and strong demand for technologically advanced home appliances continue to support steady regional expansion.
Asia-Pacific
Asia-Pacific captured 24.1% market share in 2024 and represents the fastest-growing regional market. Rapid urbanization, rising disposable incomes, and expanding middle-class populations drive adoption across China, Japan, South Korea, and India. Growth in smart home ecosystems and increasing penetration of modular kitchens support demand for smart dishwashers. Consumers increasingly seek time-saving appliances aligned with busy urban lifestyles. Expanding e-commerce penetration and competitive pricing strategies further enhance accessibility. Local manufacturing capabilities and strong innovation pipelines position Asia-Pacific as a key growth engine for the market.
Latin America
Latin America accounted for 7.1% market share in 2024, supported by gradual adoption of smart home appliances in Brazil, Mexico, and Chile. Rising urban housing development and increasing consumer exposure to connected appliances drive market growth. Demand is concentrated in premium urban households seeking convenience and improved hygiene standards. Expanding retail infrastructure and improving availability of smart appliances through online channels support adoption. However, price sensitivity remains a key factor influencing purchasing decisions, encouraging manufacturers to focus on mid-range smart dishwasher offerings.
Middle East & Africa
The Middle East & Africa region held 5.0% market share in 2024, driven by growth in premium residential construction and rising smart home adoption in the UAE, Saudi Arabia, and South Africa. High disposable incomes in Gulf countries support demand for advanced, built-in smart dishwashers integrated into luxury kitchens. Commercial adoption in hotels and hospitality facilities also contributes to growth. Increasing awareness of water efficiency is particularly relevant in water-scarce regions. Gradual improvement in retail penetration and smart infrastructure continues to support long-term market development.
Market Segmentations:
By Product
- Freestanding Dishwasher
- Built-in Dishwasher
By Application
- Household
- Commercial
By Distribution Channel
- Offline
- Online
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape in the Smart Dishwasher Market is shaped by leading players including LG Electronics, Samsung Electronics Co., Ltd., Whirlpool Corporation, Bosch (Robert Bosch GmbH), Siemens AG, Haier Group Corporation, Miele & Cie. KG, Beko, General Electric Company, and Smeg S.p.A. These companies focus on technological differentiation through IoT integration, AI-driven wash optimization, and energy-efficient designs to strengthen their market positions. Product innovation, premium feature expansion, and seamless smart home compatibility remain central strategies. Players actively invest in R&D to enhance connectivity, water efficiency, and noise reduction. Strategic partnerships with smart home platform providers and expansion of omnichannel distribution networks further support competitiveness. Strong brand recognition and after-sales service capabilities provide an advantage in high-value appliance segments. Regional customization, pricing strategies, and continuous product upgrades remain critical for sustaining market presence and capturing emerging demand.
Key Player Analysis
- Haier Group Corporation
- Smeg S.p.A.
- General Electric Company
- Beko
- Siemens AG
- Whirlpool Corporation
- Miele & Cie. KG
- LG Electronics
- SAMSUNG ELECTRONICS CO., LTD.
- Robert Bosch GmbH
Recent Developments
- In August 2025, Bosch Home Appliances unveiled its all-new 500 Series dishwasher line, featuring Zone Wash Spray Arm technology, AutoAir® open-door drying, and smart Home Connect® connectivity to enhance cleaning performance and user convenience in mainstream smart dishwasher offerings.
- In January 2025, LG unveiled its second-generation LG SIGNATURE Dishwasher at CES with a pop-out handle, QuadWash Pro, and ThinQ app integration for seamless smart kitchen connectivity.
- In April 2023, Xiaomi Corporation launched the Mijia N1 Smart Dishwasher, featuring advanced drying systems, a large capacity design, and flexible installation options for medium- to large-sized households.
Report Coverage
The research report offers an in-depth analysis based on Product, Application, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Smart dishwasher adoption will increase steadily as smart home ecosystems expand across urban and semi-urban households.
- Manufacturers will integrate advanced AI algorithms to enable adaptive wash cycles, predictive maintenance, and personalized usage settings.
- Energy and water efficiency improvements will remain a core focus, supporting regulatory compliance and sustainability goals.
- Built-in smart dishwashers will gain stronger preference due to rising modular kitchen installations and premium housing projects.
- Online sales channels will play a larger role, supported by virtual product demonstrations and improved installation services.
- Demand from commercial applications such as hotels and restaurants will grow with higher hygiene and automation requirements.
- Product differentiation will increasingly rely on connectivity reliability, cybersecurity features, and seamless platform compatibility.
- Emerging markets will contribute higher growth as disposable incomes rise and consumer awareness improves.
- Manufacturers will focus on mid-priced smart models to address cost sensitivity and broaden customer reach.
- Continuous innovation in sensors, noise reduction, and smart diagnostics will strengthen long-term market competitiveness.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Smart Dishwasher Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Smart Dishwasher Market projected to grow between 2024 and 2032?
Which Smart Dishwasher Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Smart Dishwasher Market?
Who are the leading companies in the Smart Dishwasher Market?
Which region commanded the largest share of the Smart Dishwasher Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Smart Dishwasher Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Smart Dishwasher Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,718 Million → 2032: USD 6,680.12 Million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Smart Dishwasher Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Smart Dishwasher Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Smart Dishwasher Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Smart Dishwasher Market Drivers
- 3.3 Smart Dishwasher Market Restraints & Challenges
- 3.4 Smart Dishwasher Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Smart Dishwasher Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Smart Dishwasher Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Smart Dishwasher category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Smart Dishwasher Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Smart Dishwasher Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Smart Dishwasher market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Smart Dishwasher Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Smart Dishwasher Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Smart Dishwasher Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Smart Dishwasher (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Smart Dishwasher Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Smart Dishwasher Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Smart Dishwasher Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Smart Dishwasher Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Smart Dishwasher Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Smart Dishwasher Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Smart Dishwasher Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Smart Dishwasher Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Smart Dishwasher Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
