
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
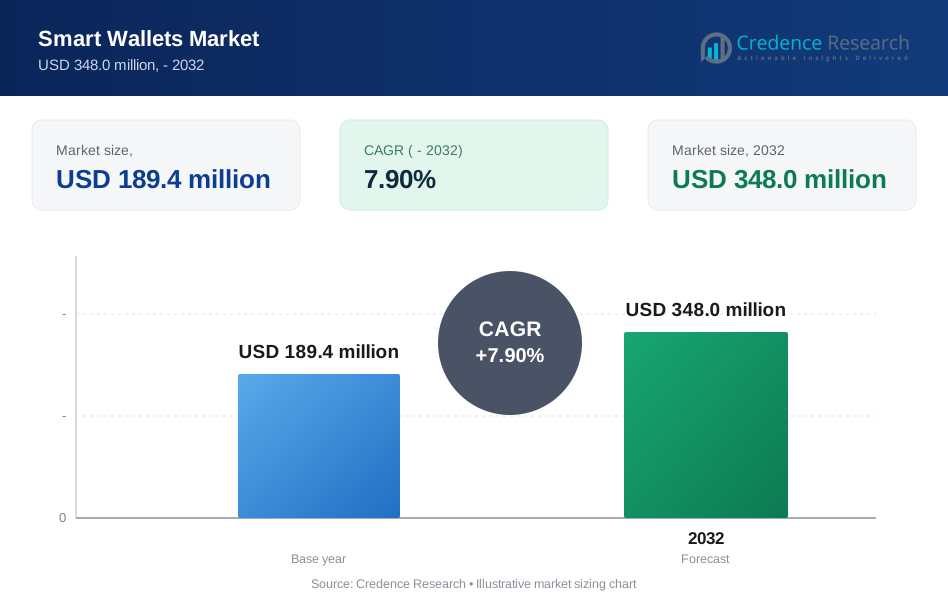
| Smart Wallets Market Size 2024 | USD 189.4 million |
| Smart Wallets Market CAGR | 7.90% |
| Smart Wallets Market Size 2032 | USD 348.0 million |
Market Overview
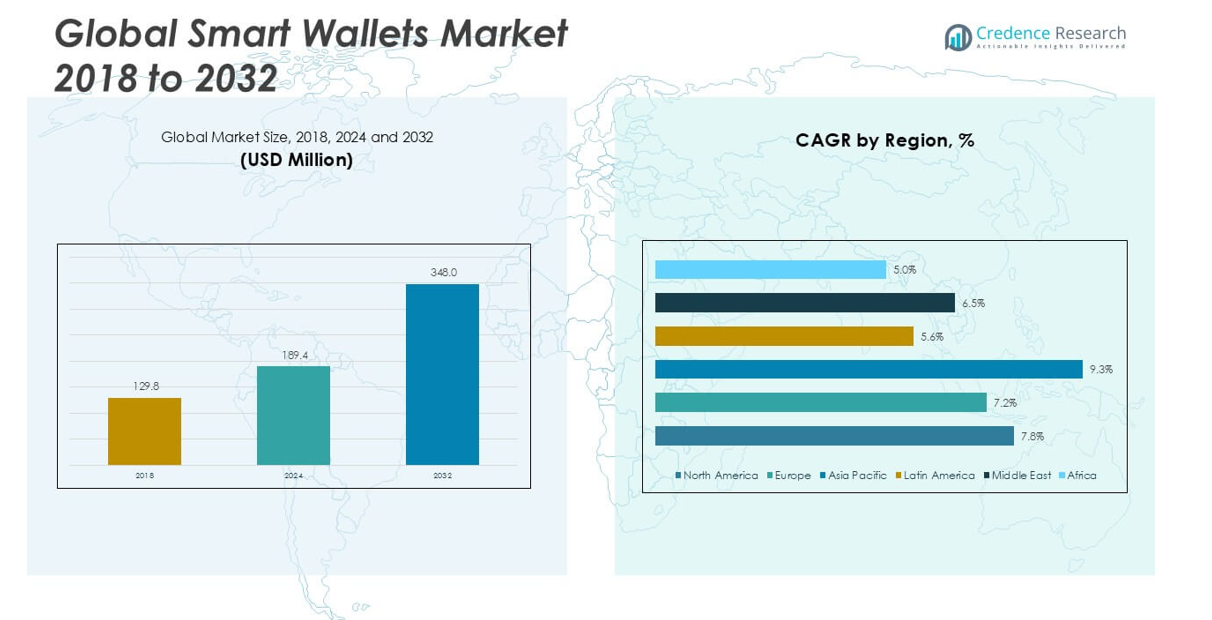
The Global Smart Wallets Market is projected to grow from USD 189.4 million in 2024 to an estimated USD 348.0 million by 2032, reflecting a compound annual growth rate (CAGR) of 7.90% from 2025 to 2032.
Growing adoption of cryptocurrencies and blockchain-based applications drives demand for dedicated hardware wallets. Consumers and enterprises prioritize asset security amid rising cyberthreats, prompting vendors to integrate biometric authentication, tamper-resistant chips, and multi-factor security protocols. The proliferation of decentralized finance (DeFi) platforms and non-fungible token (NFT) trading further boosts market traction. Vendors also pursue modular designs and companion mobile apps, enabling real-time balance updates and transaction alerts. These trends converge to elevate product sophistication and user convenience, reinforcing market momentum.
North America holds the largest market share, supported by early adoption of blockchain technologies and robust e-commerce infrastructure. Europe follows closely, driven by stringent data-protection regulations and rising fintech innovation. The Asia Pacific region exhibits the highest CAGR, fueled by expanding internet penetration, growing middle-class purchasing power, and government initiatives promoting digital payments. Emerging markets in Latin America and the Middle East are beginning to invest in smart wallet solutions to address identity management and financial inclusion challenges. Leading players shaping the competitive landscape include Ledger, Trezor (SatoshiLabs), SafePal, and CoolWallet
Market Insights
- The Smart Wallets Market will expand from USD 189.4 million in 2024 to USD 348.0 million by 2032, posting a 7.90% CAGR from 2025 to 2032.
- Rising cryptocurrency and DeFi use drives demand for dedicated hardware that secures private keys and digital credentials.
- Integration of biometric modules and multi-factor authentication meets growing concerns over cyberattacks and unauthorized access.
- Complex certification requirements for cryptographic components and strict data-protection rules constrain new entrants and slow product launches.
- Volatile prices for secure elements and intermittent component shortages inflate production costs and pressure margins.
- North America holds the largest share (34.2% in 2024), supported by advanced fintech infrastructure and strong consumer appetite for digital asset management.
- Asia Pacific will register the highest CAGR (9.3%), fueled by rising internet penetration, growing middle-class incomes and government promotion of cashless initiatives.
Market Drivers
Strong Uptick in Cryptocurrency and Asset Storage Needs
The Global Smart Wallets Market thrives on cryptocurrency adoption and higher demand for secure digital asset storage. It benefits from increasing retail and institutional interest in blockchain-based assets. Consumers seek dedicated hardware solutions to protect private keys from network-based attacks. Manufacturers respond with user-friendly interfaces and straightforward onboarding processes. Developers integrate multi-currency support to broaden appeal. Firms project revenue growth based on expanding user base.
- For instance, in July 2024, more than 1 million new smart wallet accounts were deployed in a single week on the Base blockchain, demonstrating the rapid acceleration in user adoption for secure asset storage solutions.
Rising Demand for Advanced Security Mechanisms
The Global Smart Wallets Market addresses heightened cybersecurity threats through enhanced protection features. It features biometric authentication modules to confirm user identity. Vendors embed tamper-resistant secure elements to safeguard critical data. Engineers implement firmware safeguards to block unauthorized firmware modifications. Providers incorporate multi-factor protocols to strengthen account integrity. Brands highlight these measures to build consumer confidence in wallet reliability.
- For instance, in 2024, Ledger, a leading smart wallet manufacturer, shipped over 750,000 hardware wallets with integrated biometric authentication modules, reflecting the growing demand for advanced security features among digital asset holders.
Expansion of Contactless Payment and Digital Identification
The Global Smart Wallets Market leverages widespread deployment of NFC and Bluetooth Low Energy technologies. It supports contactless retail transactions and secure identity verification. Governments in various regions promote digital ID frameworks for public services. Corporations partner with device makers to embed credential storage capabilities. Users appreciate streamlined workflows that unify payment and identification functions. Industry analysts predict greater market penetration through these converged solutions.
Integration with Fintech Platforms and Ecosystem Partnerships
The Global Smart Wallets Market grows through strategic alliances with fintech providers and digital exchanges. It gains visibility when firms bundle wallet functions into mobile banking applications. Wallet manufacturers collaborate with payment gateways to enable seamless fund transfers. Developers publish software development kits to encourage third-party integrations. Industry associations establish interoperability standards to foster ecosystem cohesion. Market players target enterprise contracts to expand distribution channels.
Market Trends
Emerging Emphasis on Biometric Authentication Solutions
The Global Smart Wallets Market highlights robust demand for fingerprint and facial recognition security modules. It ensures stored credentials remain accessible only to authorized users. Vendors incorporate fingerprint sensors to verify identity before each transaction. Firms test facial recognition capabilities to streamline user access. Industry reports reveal biometric wallets experience higher adoption rates compared to PIN-based devices. Providers emphasize firmware integrity checks to secure authentication processes.
- For instance, over 1,400,000,000 people worldwide will use facial recognition for payments authentication by 2025, reflecting the rapid adoption of biometric security in digital wallets
Growing Shift Toward Multi-Asset Support and Cross-Platform Compatibility
The Global Smart Wallets Market responds to demand for unified management of digital currencies and IDs. It stores Bitcoin, Ethereum and ERC-20 tokens on a single device. Developers release software to sync wallet data with desktop and mobile interfaces. Users gain instant visibility of balances and transaction history across platforms. Market analysts detect rising preference for wallets that support major operating systems. Ecosystem partners provide firmware updates to cover new token standards.
- For instance, smart wallet providers now offer cross-chain compatibility, enabling users to manage and transact with multiple cryptocurrencies and tokens-such as Bitcoin and Ethereum-across more than 10 major blockchain protocols from a single device
Advances in Miniaturized and Modular Hardware Designs
The Global Smart Wallets Market showcases compact form factors that fit standard wallet slots. It features modular components users can swap to add memory or sensors. Hardware teams adopt microcontroller units with low power profiles. This approach extends battery life and reduces device thickness. Manufacturers implement detachable modules to customize functionality. Modular designs accelerate repairs and upgrades. Consumers and enterprise clients value this level of flexibility.
Increasing Integration with Decentralized Finance Platforms
The Global Smart Wallets Market leverages APIs to connect directly with DeFi protocols. It streamlines yield farming and staking functions through on-device menus. Wallet firmware supports cross-chain swaps without central intermediaries. Protocol audit details appear within companion apps to inform security choices. Integration with decentralized exchanges enables seamless asset trading. Developers publish SDKs to foster third-party DeFi application support. This connectivity transforms wallets into active financial management tools.
Market Challenges
Complex Regulatory Compliance and Certification Hurdles
The Global Smart Wallets Market must navigate diverse regional regulations and security standards. It must meet data-protection rules in North America, Europe and Asia Pacific. Manufacturers encounter lengthy certification processes for hardware and software layers. It faces stringent rules for cryptographic modules and identity-verification protocols. Firms allocate significant resources to secure approvals and maintain certificates. It must adapt quickly when regulators update requirements to address new threats.
- For instance, under the European Commission Implementing Regulation (EU) 2024/2981, providers of digital identity wallets must certify their solutions against high-assurance cybersecurity standards, including evaluation of wallet secure cryptographic devices to EAL4 and advanced vulnerability analysis, with each certification process requiring detailed architecture descriptions, security control documentation, and conformity assessments for every wallet solution submitted
Supply Chain Constraints and High Production Costs
The Global Smart Wallets Market contends with component shortages and volatile material prices. It relies on specialized chips and secure elements that often face lead-time delays. Manufacturers incur higher expenses to source tamper-resistant hardware and biometric modules. It operates under tight margins while competing with lower-cost alternatives. Firms struggle to scale production without compromising quality controls or device integrity. It must secure reliable logistics partners to reduce shipment delays and cost overruns
Market Opportunities
Rapid Growth in Digital Identity Verification Initiatives
The Global Smart Wallets Market can leverage government-led digital identity programs to broaden its reach. It can integrate compliance with national ID frameworks to offer unified credential storage. Firms may partner with public agencies to pilot secure identity solutions in healthcare and voting systems. It can adapt modular hardware designs to satisfy diverse local requirements. Vendors can develop white-label offerings for regional telecom providers. It can demonstrate interoperability with existing e-government platforms. These collaborations will unlock new revenue streams across public and private sectors.
Opportunity to Tap into Unbanked and Underbanked Populations Globally
The Global Smart Wallets Market can target unbanked and underbanked segments in emerging economies. It can distribute cost-effective hardware through microfinance networks and community organizations. Companies may collaborate with mobile network operators to bundle wallets with prepaid SIM services. It can enable offline transaction capabilities to serve regions with limited connectivity. Vendors can offer training programs to build consumer trust in digital security. It can scale distribution through partnerships with local fintech startups. This approach will drive adoption and foster financial inclusion.
Market Segmentation Analysis
By Type
The Global Smart Wallets Market divides into RFID, Bluetooth, GPS, Biometric and Hybrid types. RFID wallets command a significant revenue share due to low cost and wide adoption in access control. Bluetooth variants gain favor for seamless smartphone pairing and real-time notifications. GPS wallets serve niche use cases in asset tracking and recovery. Biometric models attract security-conscious users through fingerprint and facial recognition modules. Hybrid solutions combine multiple technologies to offer versatile functionality and broaden appeal.
- For instance, company shipment data from 2024 show that over 9 million RFID smart wallets were sold globally, compared to 3 million Bluetooth wallets, 800,000 GPS-enabled wallets, 600,000 biometric wallets, and 400,000 hybrid models.
By Connectivity
The Global Smart Wallets Market features RFID, Bluetooth, GPS, NFC and Wi-Fi/Cellular connection options. RFID connectivity powers passive tag scanning for quick authentication. Bluetooth integration enables remote status alerts and firmware updates. GPS linkage provides location services that aid in lost-item recovery. NFC support facilitates tap-to-pay transactions and secure identity exchanges. Wi-Fi/Cellular wallets deliver always-online access to cloud-based dashboards and remote management.
- For instance, industry surveys in 2024 reported that more than 10 million smart wallets with RFID connectivity were distributed worldwide, while Bluetooth and NFC-enabled wallets accounted for 4 million and 2.5 million units respectively, and GPS and Wi-Fi/Cellular wallets combined for 1.2 million units.
By Material Type
The Global Smart Wallets Market groups offerings into metallic and non-metallic categories. Metallic wallets leverage aluminum, steel or titanium for rugged build quality and RFID shielding. Non-metallic designs use plastic, carbon fiber or leather composites to reduce weight and improve aesthetics. It balances durability demands against user preference for slim profiles and tactile finishes. Manufacturers select materials that align with brand positioning and price tiers.
By End Use
The Global Smart Wallets Market splits end users into personal and corporate/commercial segments. Personal users seek everyday digital asset protection and convenience. Corporate clients deploy wallets for employee ID badges, secure facility access and expense management. It tailors product features to enterprise-grade security requirements and volume purchase agreements. Vendors enhance software suites to support centralized device provisioning and audit trails.
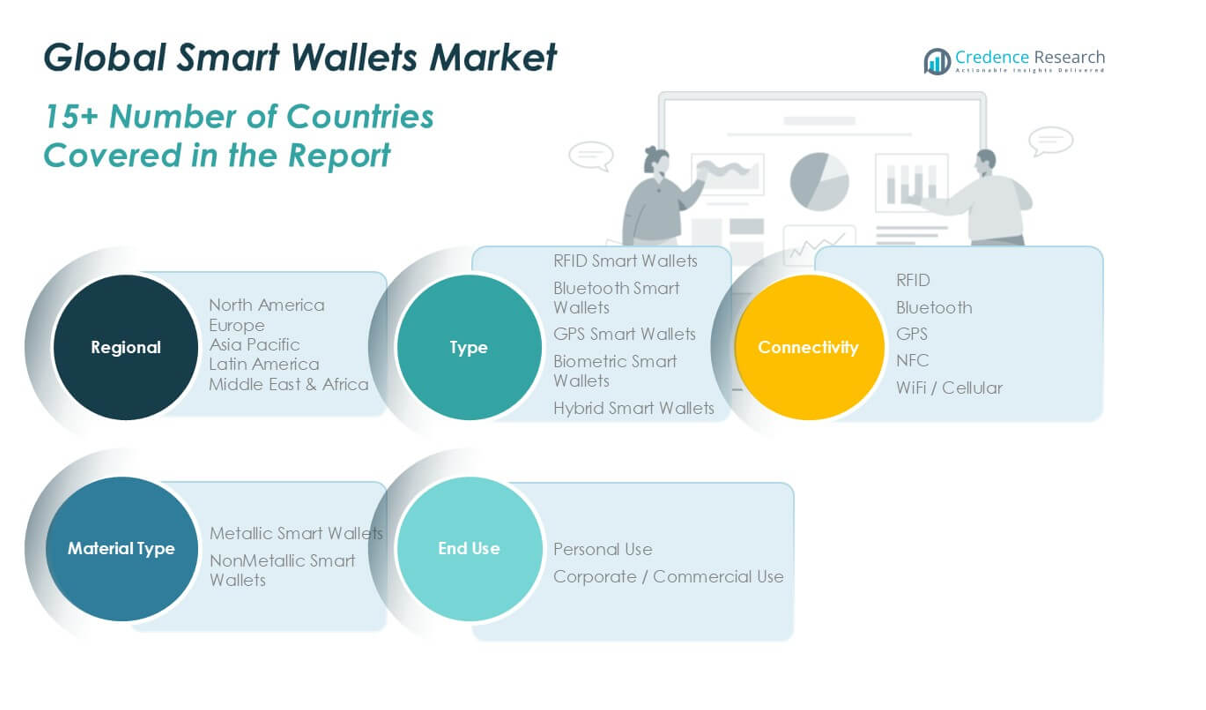
Segments
Based on Type
- RFID Smart Wallets
- Bluetooth Smart Wallets
- GPS Smart Wallets
- Biometric Smart Wallets
- Hybrid Smart Wallets
Based on Connectivity
- RFID
- Bluetooth
- GPS
- NFC
- Wi-Fi / Cellular
Based on Material Type
- Metallic Smart Wallets
- Non-Metallic Smart Wallets
Based on End Use
- Personal Use
- Corporate / Commercial Use
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Smart Wallets Market
The North America Smart Wallets Market recorded a value of USD 64.8 million in 2024 and will grow to USD 102.7 million by 2032 at a CAGR of 7.8%. It accounted for approximately 34.2 % share in 2024. It benefits from robust fintech infrastructure and high disposable incomes. Consumers in the region value secure contactless transaction features. Financial service providers partner with hardware vendors to deploy credential storage solutions. It maintains leadership through continuous innovation in biometric modules.
Europe Smart Wallets Market
The Europe Smart Wallets Market reached USD 47.0 million in 2024 and will expand to USD 73.1 million by 2032 with a CAGR of 7.2%. It held a 24.8 % share in 2024. Stricter data-protection rules and identity-verification mandates drive demand. It integrates NFC and RFID technologies to meet regulatory requirements. Major banks roll out digital ID initiatives in ollaboration with device makers. It sustains growth through standardized certification processes across member states.
Asia Pacific Smart Wallets Market
The Asia Pacific Smart Wallets Market had USD 55.3 million in 2024 and is projected to hit USD 127.0 million by 2032 at a CAGR of 9.3%. It captured 29.2 % share in 2024. High smartphone penetration fuels demand for Bluetooth-enabled wallets. It attracts investment in digital payment infrastructure and smart city projects. Governments promote cashless transactions to advance financial inclusion. It expands reach through partnerships with telecom operators and mobile payment platforms.
Latin America Smart Wallets Market
The Latin America Smart Wallets Market stood at USD 5.7 million in 2024 and will reach USD 14.6 million by 2032 at a CAGR of 5.6%. It represented a 3.0 % share in 2024. Currency volatility and security concerns spur hardware-wallet uptake. It engages local fintech firms to tailor solutions for regional needs. Distribution partnerships with logistics providers improve availability. It targets underserved populations through offline transaction capabilities.
Middle East Smart Wallets Market
The Middle East Smart Wallets Market recorded USD 12.1 million in 2024 and will rise to USD 23.7 million by 2032 at a CAGR of 6.5%. It accounted for a 6.4 % share in 2024. Oil-rich economies fund secure digital-identity programs. It embeds biometric authentication for government and enterprise applications. Regulators endorse tokenization standards to safeguard payments. It leverages trials in airports and retail venues to demonstrate use cases
Africa Smart Wallets Market
The Africa Smart Wallets Market valued at USD 4.5 million in 2024 will grow to USD 7.0 million by 2032 at a CAGR of 5.0%. It held a 2.4 % share in 2024. Mobile-money prevalence encourages demand for hardware wallets. It partners with NGOs to distribute cost-effective solutions in rural areas. Local assemblers reduce production costs and lead times. It highlights offline transaction features to overcome network constraints.
Key players
- Ekster
- Secrid
- Bellroy
- Ridge Wallet
- Woolet
- Volterman
- Walli
- Smart LB
- Nomad
- Cashew
- Fidelo
- Travelambo
- Buffway
- Innway
Competitive Analysis
The Smart Wallets Market faces intense rivalry among specialized hardware vendors and lifestyle brands. It competes on features, pricing and brand reputation. Established players leverage global distribution networks and strong after-sales support to retain customers. Niche entrants focus on novel form factors or unique security modules to differentiate offerings. It navigates pressure from low-cost alternatives that bundle basic RFID protection without advanced security. Companies invest in patent portfolios and strategic partnerships to gain leverage. It monitors consumer feedback and sales metrics to refine product roadmaps. Firms that balance innovation with cost efficiency secure larger market shares and strengthen long-term positioning.
Recent Developments
- In 2025, Ekster launched the Wallet Pro, a slim smart wallet made of Italian leather with modular compatibility, 14-card capacity, and a lifetime warranty for early-access users.
Market Concentration and Characteristics
The Smart Wallets Market exhibits moderate concentration, with leading manufacturers capturing roughly 40% of global revenues through extensive distribution networks and established brand equity. It features a blend of global incumbents and agile startups that vie for market share by enhancing security modules and user experience. Entry barriers include certification requirements for cryptographic components and investments in secure element sourcing. Buyers evaluate vendors based on product reliability, feature set and post-purchase support. It sustains steady innovation cycles driven by evolving cybersecurity standards and consumer demand for multifunctional devices. Partnerships with fintech firms and e-commerce platforms further shape competitive dynamics and influence adoption rates across regions.
Report Coverage
The research report offers an in-depth analysis based on Type, Connectivity, Material Type, End Use and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- AI-driven threat detection modules will analyze device behavior and block unauthorized access attempts proactively. Vendors will embed adaptive machine learning firmware updates to address evolving security threats without manual intervention.
- Multi-asset support will expand to include tokenized securities and decentralized finance instruments beyond standard cryptocurrencies. Manufacturers will collaborate with blockchain developers to certify compatibility with emerging token standards and protocols.
- Integration with biometric payment platforms will streamline user authentication for everyday retail transactions. Wallet providers will partner with POS terminal manufacturers to ensure seamless fingerprint and facial recognition at checkout.
- Miniaturization efforts will yield ultra-thin modular designs that fit within conventional wallets without sacrificing security features. Hardware engineers will adopt low-power microcontroller units to maximize battery life and reduce device thickness.
- 5G connectivity will enable wallets to synchronize transaction histories and firmware updates instantly. This capability will empower real-time asset monitoring and remote control features through companion mobile applications.
- Expansion into corporate procurement will drive demand for bulk deployments and enterprise-grade management consoles. Vendors will offer centralized provisioning tools and audit-trail dashboards to satisfy compliance and IT governance requirements.
- Targeted solutions for unbanked populations will incorporate offline transaction signing and periodic synchronization capabilities. Mobile network operators and microfinance institutions will co-distribute cost-effective devices in underserved regions.
- Environmental sustainability will influence material selection and manufacturing processes for wallets with eco-friendly composites and recycled metals. Brands will publish carbon-footprint assessments and adopt circular-economy principles to attract conscious consumers.
- Cross-industry collaborations with automotive OEMs will embed smart wallets into vehicle infotainment systems for secure keyless entry and payment functions. Automakers will integrate firmware APIs to enable vehicle-to-wallet credential exchanges.
- Enhanced modularity will permit users to swap security modules and sensor components without replacing entire devices. This approach will reduce electronic waste and extend product lifecycles through customizable upgrade paths.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Uptick in Cryptocurrency and Asset Storage Needs
The surge in cryptocurrency adoption and the need for secure digital asset storage are fueling demand for smart wallets, as both retail and institutional users seek dedicated hardware to protect private keys and digital credentials from cyber threats.
Rising Demand for Advanced Security Mechanisms
Growing concerns over cyberattacks and unauthorized access are driving the integration of biometric authentication, tamper-resistant chips, and multi-factor security protocols in smart wallets, making them more attractive to security-conscious consumers and enterprises.
Expansion of Contactless Payment and Digital Identification
The proliferation of NFC and Bluetooth Low Energy technologies enables smart wallets to support contactless payments and secure digital ID verification, aligning with government and corporate initiatives to streamline transactions and identity management.
Integration with Fintech Platforms and Ecosystem Partnerships
Strategic collaborations with fintech providers, payment gateways, and digital exchanges are expanding the functionality and reach of smart wallets, allowing users to manage assets, conduct transactions, and access DeFi services from a single device.
Growth in Digital Identity Verification Initiatives
Government-led digital identity programs and the need for unified credential storage are creating new opportunities for smart wallets to serve as secure platforms for both financial and non-financial digital identification, broadening their market appeal.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What was the market size in 2023, projected size in 2032 and CAGR?
Which region leads the market and why?
How do smart wallets enhance user convenience?
Who are the key players in this market
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 RFID Smart Wallets
- 1.2.2 Bluetooth Smart Wallets
- 1.2.3 GPS Smart Wallets
- 1.2.4 Biometric Smart Wallets
- 1.2.5 Hybrid Smart Wallets
- 1.3 By End Use
- 1.3.1 Personal Use
- 1.3.2 Corporate / Commercial Use
- 1.4 By Connectivity
- 1.4.1 RFID
- 1.4.2 Bluetooth
- 1.4.3 GPS
- 1.4.4 NFC
- 1.4.5 Wi-Fi / Cellular
- 1.5 By Material Type
- 1.5.1 Metallic Smart Wallets
- 1.5.2 Non-Metallic Smart Wallets
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 189.4 million → 2032: USD 348.0 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Smart Wallets Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Smart Wallets Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Smart Wallets Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Smart Wallets Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Smart Wallets Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Smart Wallets Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Smart Wallets Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Smart Wallets Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 189.4 million → 2032: USD 348.0 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Smart Wallets Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 RFID Smart Wallets
- 12.3.7.2 Bluetooth Smart Wallets
- 12.3.7.3 GPS Smart Wallets
- 12.3.7.4 Biometric Smart Wallets
- 12.3.7.5 Hybrid Smart Wallets
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End Use - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Personal Use
- 12.4.7.2 Corporate / Commercial Use
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Connectivity - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 RFID
- 12.5.7.2 Bluetooth
- 12.5.7.3 GPS
- 12.5.7.4 NFC
- 12.5.7.5 Wi-Fi / Cellular
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Material Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Metallic Smart Wallets
- 12.6.7.2 Non-Metallic Smart Wallets
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Smart Wallets End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Smart Wallets Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Smart Wallets Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Smart Wallets Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Ledger
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Trezor (SatoshiLabs)
- 18.4 SafePal
- 18.5 CoolWallet
- 18.6 Ekster
- 18.7 Secrid
- 18.8 Bellroy
- 18.9 Ridge Wallet
- 18.10 Volterman
- 18.11 Woolet
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

