
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
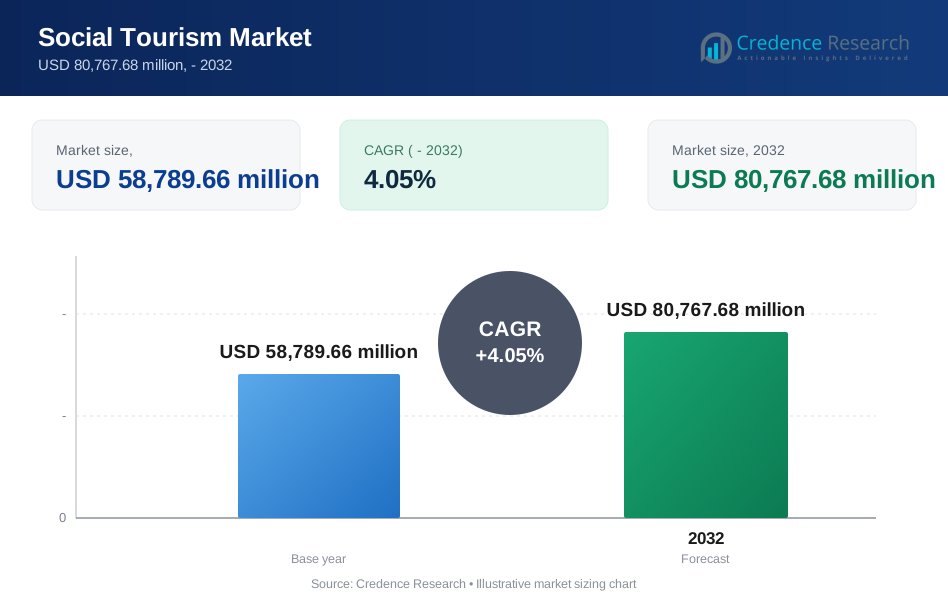
| Social Tourism Market Size 2024 | USD 58,789.66 Million |
| Social Tourism Market, CAGR | 4.05% |
| Social Tourism Market Size 2032 | USD 80,767.68 Million |
Market Overview
The Social Tourism market is projected to grow from USD 58,789.66 million in 2024 to USD 80,767.68 million by 2032, reflecting a compound annual growth rate (CAGR) of 4.05%.
The Social Tourism market is primarily driven by increasing government initiatives promoting affordable travel for low-income families, seniors, and disabled individuals. Additionally, the rise of social awareness and corporate social responsibility (CSR) programs that encourage inclusive tourism significantly contribute to market growth. There is also a noticeable trend towards partnerships between governments, non-profit organizations, and travel agencies to expand access to tourism. These collaborations are enhancing travel experiences and boosting local economies, further fueling the growth of the social tourism sector.
The Social Tourism market exhibits significant geographical diversity, with key regions including Europe, North America, Asia-Pacific, and Latin America. Europe leads in social tourism initiatives, driven by strong support from organizations like Eurostar and SNCF, which promote inclusive travel. North America is rapidly catching up, supported by innovative community-focused tours from companies like Intrepid and G. Adventures. In Asia-Pacific, companies like Maharashtra Tourism are pivotal in developing regional social tourism. Key players in the market such as Trenitalia and Renfe emphasize sustainable and accessible tourism, catering to a broad demographic spectrum across these regions.
Market Drivers
Rising disposable income and demographic shifts
The expansion of the global middle class provides more people with the financial means to travel, thus fueling the growth of the social tourism market. For instance, the U.S. Bureau of Economic Analysis reported a real change in disposable personal income in June 2024 by +0.1%. Simultaneously, an aging population, consisting of retirees with time and resources for leisure activities, forms a crucial segment of this market. These demographic trends support a more inclusive approach to travel, addressing the needs of diverse groups and promoting tourism experiences for marginalized communities.
Increased awareness and government support
There is a rising consciousness about social inequalities, driving demand for more inclusive tourism options. Government initiatives play a pivotal role in this context, with policies aimed at fostering social tourism to ensure it benefits broader societal groups. For instance, the U.S. Department of Commerce released the 2022 National Travel and Tourism Strategy, focusing on promoting the United States as a premier destination grounded in the breadth and diversity of our communities. These efforts not only enhance market growth but also ensure that tourism development contributes positively to social cohesion and equity.
Digital transformation in tourism
The integration of digital tools, such as online platforms and mobile applications, is revolutionizing the way social tourism operates. These technologies make it easier for travelers to access information, book trips, and manage travel logistics, thus enhancing the accessibility of travel experiences for all social groups. Social media platforms further amplify this effect by promoting social tourism destinations and experiences through user-generated content and influencer campaigns.
Emphasizing sustainable and accessible travel
The increasing emphasis on sustainability reflects a shift towards environmentally friendly and socially responsible tourism practices, aligning perfectly with the principles of social tourism. Additionally, there is a growing focus on making tourism more accessible to people with disabilities, which not only broadens the market but also aligns with global movements towards inclusivity and equal opportunities in travel. This trend not only attracts a wider audience but also promotes a more caring and equitable tourism industry.
Market Trends
Emerging Trends in Wellness and Micro-Tourism
Wellness and health tourism are gaining traction, incorporating mindful travel activities like yoga and meditation alongside traditional leisure travel. For instance, the Global Wellness Institute reports that wellness tourism is experiencing a 36% annual spending growth, significantly outpacing general tourism growth. This segment also extends to medical tourism, where healthcare treatments are combined with travel experiences, and includes disability-inclusive wellness programs. Another noteworthy trend is micro-tourism and slow travel, which promote local exploration and encourage travelers to engage deeply with smaller areas for shorter periods, thereby reducing environmental impact and enhancing the authenticity of the travel experience.
Collaboration for Sustainable and Authentic Experiences
The sector is witnessing increased collaboration and partnerships among various stakeholders, including public-private partnerships with governments and NGOs to ensure sustainable development. There are also growing collaborations within the industry, such as those between travel agencies, airlines, and accommodations, which streamline the travel process and enhance the overall tourist experience. Importantly, these collaborations often involve local communities, ensuring that travel experiences are genuine and mutually beneficial, thereby enriching the social tourism ecosystem.
Market Challenges Analysis
Standardization and Inclusive Access
The Social Tourism sector faces significant challenges related to standardization and quality control. With varying standards across destinations, it becomes difficult for consumers to evaluate and trust the options available, which impacts the reliability and ethical perception of social tourism offerings. For instance, the International Organization for Standardization (ISO) has published the world’s first standard on accessible tourism, ISO 21902 Tourism and related services – Accessible tourism for all – Requirements and recommendations. However, accessibility and inclusivity present considerable hurdles. Many destinations and accommodations are not fully accessible to people with disabilities, and economic barriers further limit the ability for all potential tourists to participate in social tourism. For example, globally the WHO estimates that 15% of the population has some kind of need for accessibility assistance. These challenges require robust solutions to ensure that social tourism can be a viable option for a diverse range of travelers, not just those who can physically and financially afford to engage.
Sustainability and Competitive Pressures Measuring the impact and ensuring the sustainability of social tourism initiatives pose complex challenges. Quantifying the actual social benefits and ensuring that these initiatives have a lasting positive impact on communities is intricate and often lacks clear methodologies. For instance, the paper “How crucial is the social responsibility for tourism sustainability?” discusses the importance of social responsibility for tourism sustainability and provides a critical analysis of examples of the social responsibility practice in the key tourism subsectors. Furthermore, competition with traditional tourism sectors places additional stress on social tourism providers. These entities often operate with lower profit margins and struggle to attract a significant market share without compromising their ethical standards. This competition is exacerbated by the need for effective destination management to prevent overtourism and ensure the sustainable use of local resources, such as water and energy, which are vital for the long-term health of tourist destinations. For example, the paper “Social Sustainability on Competitiveness in the Tourism Industry: Toward New Approach?” reflects on the importance of considering social sustainability as part of the concept of tourism competitiveness.
Market Segmentation Analysis:
By Tour Type:
The Social Tourism market offers a diverse range of tour types, catering to varying interests and social goals. Socio-educational tours are increasingly popular, focusing on learning and enrichment, appealing to schools, universities, and groups interested in educational development. Socio-cultural tours allow tourists to immerse themselves in local cultures, supporting cultural preservation and appreciation. Socio-recreational tours cater to those seeking leisure activities that also foster social interaction and community engagement. Socio-adventure tours appeal to a more dynamic crowd, offering activities that combine physical challenges with social experiences. The "others" category encompasses specialized tours that may blend elements of all the above categories or focus on niche interests. Each tour type addresses different aspects of social tourism, from educational and cultural exchange to adventure and recreation, making the sector versatile and inclusive.
By Booking Channel:
The booking channels for the Social Tourism market reflect the modern traveler’s preferences and technological advancements. Online booking is the dominant channel, favored for its convenience, accessibility, and the ability to compare options easily. This method aligns with global trends towards digital solutions and is crucial for reaching a broader audience. Phone booking remains relevant for a segment of tourists who prefer personal interaction or require additional assistance when planning their travels. In-person booking, though less common, is crucial for last-minute travel arrangements or for tourists who are already at their destination. Each channel plays a strategic role in the accessibility and efficiency of booking social tourism experiences, ensuring that the services are accessible to all potential tourists, regardless of their access to technology or personal booking preferences.
Segments:
Based on Tour Type:
- Socio-educational tours
- Socio-cultural tours
- Socio-recreational tours
- Socio-adventure tours
- Others
Based on Booking Channel:
- Phone booking
- Online booking
- In-person booking
Based on Tourist Type:
- Domestic tourist
- International tourist
Based on Age Group:
- 15-25 Years
- 26-35 Years
- 36-45 Years
- 46-55 Years
- 56-65 Years
- 66-75 Years
- Above 75 Years
Based on the Geography:
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis
Europe
Europe is leading the global landscape and holding approximately 45% of the market share. This dominance is primarily attributed to well-established social tourism programs and policies across many European countries, particularly in France, Spain, and Belgium. For instance, since the beginning of the 21st century, the European Union tourism policy has been increasingly focused on initiatives in the field of social tourism, which are one of the ways of achieving sustainable development in the European tourism economy. These nations have long-standing traditions of promoting accessible tourism for all social classes, including low-income groups, seniors, and people with disabilities. The European Union’s support through initiatives like the Calypso program has further bolstered social tourism, encouraging cross-border travel and cultural exchange. The region’s extensive network of social tourism accommodations, ranging from holiday villages to youth hostels, contributes to its market leadership. Additionally, strong labor unions and social organizations play a crucial role in advocating for and organizing social tourism initiatives, ensuring sustained growth in this sector.
Asia-Pacific
Asia-Pacific emerges as the fastest-growing region in the social tourism market, currently accounting for about 25% of the global share. This growth is driven by increasing government recognition of tourism’s social and economic benefits, particularly in countries like China, Japan, and South Korea. These nations are implementing policies to promote domestic tourism among various demographic groups, including the elderly and low-income families. For instance, an Economist Impact survey of more than 4,500 travellers in the region—across Australia, Japan, India, Malaysia, the Philippines, Singapore, South Korea, Taiwan and Thailand—shows that more than 7 in 10 (71.8%) respondents agree that covid-19 has changed the way they think about sustainable tourism by making it more important to them. China’s “Red Tourism” initiative, focusing on historical and patriotic sites, exemplifies the region’s unique approach to social tourism. The rapid expansion of budget travel options and the growing middle class in countries like India and Indonesia are also contributing to the market’s growth. As awareness of social tourism’s benefits spreads, many Asia-Pacific countries are developing infrastructure and programs to support inclusive travel experiences, potentially positioning the region to challenge Europe’s market dominance in the coming years.
Key Player Analysis
- Intrepid
- Adventures
- Trenitalia
- SNCF
- Eurostar
- Renfe
- Explore Tours
- Maharashtra Tourism
- Exodus Travels
- Deutsch Bahn
- FlixTrain
- On-the-go Tours
Competitive Analysis
The competitive landscape of the Social Tourism market is robust, with leading players employing diverse strategies to capture market share and enhance their offerings. Eurostar and SNCF are at the forefront in Europe, leveraging extensive rail networks to promote accessible travel packages. In North America, companies like Intrepid and G. Adventures differentiate themselves through unique, community-oriented travel experiences that emphasize sustainability and ethical tourism. Trenitalia and Renfe focus on integrating eco-friendly practices within their rail services, appealing to environmentally conscious travelers. Furthermore, Exodus Travels and Explore Tours are recognized for their wide range of socio-adventure and cultural tours that cater to varying tourist preferences. Each competitor's strategy not only strengthens their market position but also contributes to the growth and diversification of the social tourism sector, enhancing overall market competitiveness.
Recent Developments
- In September 2023, Intrepid Travel introduced over 100 new itineraries for 2024, emphasizing low-carbon travel, family connections, shoulder season travel, and active adventures. Notable trips include a 10-day low-carbon tour in Borneo, a 14-day family holiday in Costa Rica, a 5-day Northern Lights tour in Iceland, and a 7-day multi-active adventure in Southern Greece.
- In July 2024, G Adventures added a series of new ‘Classic’ trips to its 2025 portfolio. These trips focus on value-for-money safaris in Africa and other unique travel experiences designed to offer rich cultural insights and adventure.
- In July 2024, SNCF Voyageurs announced the launch of high-speed rail services in Italy, based on a framework agreement allowing the operation of TGVs in Italy for 15 years. This marks a significant expansion of SNCF’s international high-speed rail network.
- In April 2024, FlixTrain announced their largest expansion till date. With immediate effect, the long distance train company is expanding their services, with the goal of reaching around 40% greater capacity than in 2023 by summer. The business is also expanding frequencies, on the Berlin-Cologne line, green FlixTrain trains will now operate up to six times a day, and on the Berlin-Frankfurt route, up to eight times.
- In April 2024, Eurostar announced flexible rates across all travel classes are now 'the standard' between Europe's most popular cities. Customers can now enjoy an even easier, more seamless, and distinctive experience owing to the October 2023 launch of Eurostar's new website, app, and rewards programme. For European travel, all clients will now benefit from a premium proposition in terms of refunds and exchanges across all ticket classes. From November, travel classes will be called consistently across Eurostar's extended five country network, which covers the United Kingdom, France, Belgium, the Netherlands, and Germany, as Eurostar Standard, Eurostar Plus, and Eurostar Premier.
Market Concentration & Characteristics
The Social Tourism market is characterized by a moderate level of concentration, with a mix of large and small players that cater to various niches within the sector. Major companies like Eurostar and SNCF hold significant market shares due to their extensive networks and established brand reputations, which allow them to offer diverse and accessible tourism options across Europe. Meanwhile, specialized firms such as Intrepid and G. Adventures capitalize on niche markets by providing unique, immersive experiences that focus on cultural and environmental sustainability. This segmentation enables smaller players to thrive alongside industry giants by targeting specific traveler needs and preferences. Overall, the market's structure fosters competition and innovation, driving the development of more inclusive, responsible, and varied tourism offerings that appeal to a broad spectrum of tourists globally. This dynamic contributes to a vibrant and competitive environment within the social tourism industry.
Report Coverage
The research report offers an in-depth analysis based on Tour Type, Booking Channel, Tourist Type, Age Group and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Increased adoption of sustainable practices will continue to shape the future of social tourism, with a focus on minimizing environmental impacts.
- Technological advancements will further streamline booking processes and enhance accessibility, particularly through digital platforms and mobile apps.
- There will be a growing emphasis on inclusive travel options that cater to diverse demographic groups, including seniors, people with disabilities, and LGBTQ+ communities.
- Partnerships between governments, NGOs, and private sectors are expected to increase, promoting social tourism through collaborative initiatives.
- The expansion of social media influence will play a crucial role in marketing and promoting social tourism destinations and packages.
- Community-based tourism will see further development, focusing on empowering local communities and preserving cultural heritage.
- Virtual reality and augmented reality technologies will become more integrated, offering potential tourists immersive previews of destinations.
- Wellness and health tourism will expand within the social tourism sector, blending travel with wellness activities and medical treatments.
- There will be a significant rise in micro-tourism and slow travel, emphasizing local exploration and sustainable travel habits.
- Economic barriers will be addressed more rigorously, with initiatives aimed at making social tourism more affordable and accessible to a broader audience.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Social Tourism Market?
What factors are driving the growth of the Social Tourism Market?
What are the key segments within the Social Tourism Market?
What are some challenges faced by the Social Tourism Market?
Who are the major players in the Social Tourism Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Social Tourism Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Social Tourism Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (2032) (base year: USD 58,789.66 million → 2032: USD 80,767.68 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Social Tourism Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Social Tourism Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Social Tourism Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Social Tourism Market Drivers
- 3.3 Social Tourism Market Restraints & Challenges
- 3.4 Social Tourism Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Social Tourism Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Social Tourism Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Social Tourism category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Social Tourism Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Social Tourism Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Social Tourism market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Social Tourism Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Social Tourism Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Social Tourism Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Social Tourism (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Social Tourism Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Social Tourism Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & 2032)
- 7.1.2 Channel Mix Evolution (2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Social Tourism Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Social Tourism Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Social Tourism Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Social Tourism Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Social Tourism Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Social Tourism Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Social Tourism Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
