
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
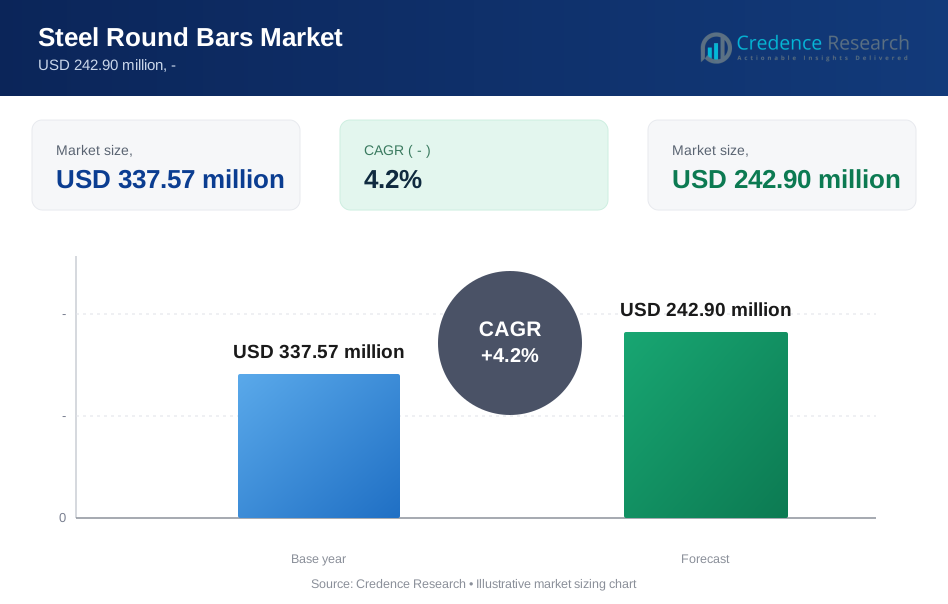
| Steel Round Bars Market Size 2024 | USD 242.90 million |
| Steel Round Bars Market, CAGR | 4.2% |
| Steel Round Bars Market Size 2032 | USD 337.57 million |
Market Overview
The Steel Round Bars Market is experiencing notable growth, with a market valuation of approximately USD 337.57 million as of 2024. It is projected to grow at a compound annual growth rate (CAGR) of 4.2% over the forecast period, reaching around USD 242.90 million by 2032. This growth trajectory is largely attributed to the increasing demand for steel round bars in various sectors, including construction, automotive, and manufacturing.
Several key factors are driving this market expansion. The surge in infrastructure development and urbanization is a significant contributor, as steel round bars are essential in construction applications for reinforcement purposes. Additionally, the automotive industry’s ongoing shift towards lightweight and high-strength materials is further boosting demand. The rise in industrial activities and manufacturing output is also creating a favorable environment for the growth of the steel round bars market.
Regionally, Asia-Pacific dominates the Steel Round Bars Market, primarily due to rapid industrialization and infrastructural projects in countries like China and India. North America follows, supported by a robust manufacturing sector and ongoing investments in infrastructure. Europe is also expected to see steady growth, driven by a focus on sustainability and the adoption of advanced manufacturing technologies. As emerging economies continue to invest in infrastructure and industrial development, significant growth opportunities are anticipated in the global Steel Round Bars Market.
Market Drivers:
Increasing Infrastructure Development:
The demand for steel round bars is significantly driven by the surge in infrastructure development worldwide. Governments across the globe are investing heavily in infrastructure projects, including roads, bridges, and residential buildings. According to the World Bank, global infrastructure investment is expected to increase by 3% annually, reaching approximately 4% of global GDP by 2030. This investment creates a robust demand for steel round bars, which are essential for reinforcing structures and ensuring their stability and durability. For instance, the Indian government has announced plans to invest over 1 trillion in infrastructure development by 2025, focusing on projects such as the development of smart cities and transportation networks, which will further fuel the demand for construction materials, including steel round bars.
Growth in the Automotive Sector:
The automotive industry is another significant driver of the steel round bars market. The shift towards lightweight and high-strength materials in vehicle manufacturing has led to increased consumption of steel products. According to the International Monetary Fund (IMF), global vehicle production is projected to grow by 2.5% annually through 2025. Steel round bars play a crucial role in automotive applications, such as suspension systems and chassis components, where strength and weight reduction are critical. For instance, major automotive manufacturers, including Ford and Toyota, are increasingly integrating high-strength steel in their designs to enhance performance and fuel efficiency. Additionally, the U.S. Department of Transportation has emphasized the importance of investing in innovative materials for vehicle safety, further propelling the demand for steel round bars.
Rising Industrial Production:
The growth in industrial production is a key driver of the steel round bars market. As economies recover from recent downturns, industrial output is expected to rise, leading to increased demand for steel products. According to the World Economic Forum, global manufacturing output is anticipated to increase by approximately 3.7% annually between 2024 and 2030. This growth is primarily attributed to advancements in manufacturing technologies and increased automation. Steel round bars are vital in various industrial applications, including machinery, tools, and equipment. For instance, sectors such as construction equipment and machinery manufacturing are projected to grow by over 5% annually. The U.S. Bureau of Economic Analysis has reported that manufacturing jobs have increased by 1.5 million since 2020, indicating robust demand for industrial materials like steel round bars.
Expanding Construction Activities in Emerging Economies:
Emerging economies are witnessing a construction boom, driven by urbanization and population growth. According to a report by the International Labour Organization (ILO), urban populations in developing countries are expected to increase by 1.5 billion by 2030, leading to a heightened demand for housing and infrastructure. This trend is significantly impacting the demand for steel round bars, as they are extensively used in residential and commercial construction projects. For instance, countries like China and India are ramping up their construction activities, with China investing approximately 2 trillion in urban infrastructure over the next decade, focusing on railways, highways, and smart city initiatives. The Asian Development Bank has also highlighted the need for significant investments in infrastructure to accommodate growing urban populations, creating substantial opportunities for steel round bar manufacturers to meet the rising demand.
Market Trends:
Adoption of Sustainable Practices:
One of the most prominent trends in the steel round bars market is the increasing emphasis on sustainability and eco-friendly manufacturing practices. With rising global awareness regarding climate change, steel manufacturers are adopting greener technologies to reduce their carbon footprint. According to the International Energy Agency (IEA), the steel industry accounts for approximately 7% of global CO2 emissions, prompting calls for more sustainable practices. As a result, many companies are investing in electric arc furnace (EAF) technology, which uses recycled scrap steel and significantly reduces emissions compared to traditional blast furnaces. For instance, a report from the World Steel Association highlights that the use of EAF technology could potentially decrease CO2 emissions by up to 75%. Major players in the steel industry, such as ArcelorMittal, are also committing to carbon neutrality by 2050, which aligns with global sustainability goals. Additionally, the European Commission's Green Deal aims to make Europe the first climate-neutral continent by 2050, driving steel manufacturers to adopt more sustainable practices. This shift not only reflects growing regulatory pressures but also responds to consumer demand for sustainable products, as businesses increasingly seek suppliers that prioritize environmentally friendly practices.
Technological Advancements and Automation:
The integration of advanced technologies and automation is another key trend shaping the steel round bars market. Manufacturers are increasingly leveraging Industry 4.0 technologies, such as the Internet of Things (IoT), artificial intelligence (AI), and big data analytics, to enhance production efficiency and product quality. According to a report by the World Economic Forum, digital technologies can increase productivity in the manufacturing sector by up to 30% while simultaneously reducing operational costs. For instance, the U.S. Department of Commerce has emphasized the importance of adopting smart manufacturing technologies to remain competitive in the global market. According to a survey conducted by the National Institute of Standards and Technology (NIST), over 70% of manufacturers reported improved efficiency after integrating automation technologies. automation in production lines is leading to safer working environments, as robots handle hazardous tasks and minimize human intervention in risky areas. According to the International Labour Organization (ILO), automation could lead to a more skilled workforce and higher-paying jobs in the long term, countering fears of job losses due to technological advancements. In fact, a report from the World Bank indicates that countries that invest in automation can expect up to a 20% increase in job quality and wages over the next decade.
Market Challenges Analysis:
Fluctuating Raw Material Prices:
One of the most significant challenges facing the steel round bars market is the volatility of raw material prices, particularly iron ore and scrap steel. These fluctuations can severely impact production costs, forcing manufacturers to adjust pricing strategies, which can lead to reduced profitability. According to the World Bank, the prices of iron ore have seen dramatic changes over the past few years, influenced by global demand, geopolitical tensions, and changes in trade policies. For instance, in 2021, iron ore prices surged to record highs, but they have since experienced significant declines due to regulatory changes in China and a slowdown in construction activities. This unpredictability can create financial strain on steel manufacturers, as they may find it challenging to manage their budgets and forecasts effectively. Moreover, these fluctuations can also affect smaller players in the market, who may lack the financial resilience to absorb such shocks, leading to potential market consolidation as weaker companies exit the industry.
Environmental Regulations and Compliance Costs:
Another considerable challenge in the steel round bars market is the increasing regulatory scrutiny surrounding environmental impacts and sustainability practices. Governments worldwide are tightening regulations on emissions and waste management to combat climate change, leading to higher compliance costs for manufacturers. For example, the European Union’s Green Deal imposes stricter emission targets, compelling steel producers to invest in cleaner technologies and processes. While these regulations aim to foster a sustainable industry, they can also impose significant financial burdens. According to the International Monetary Fund (IMF), compliance with environmental regulations can increase operational costs by up to 20% for steel manufacturers. This situation is particularly challenging for companies that have not yet transitioned to greener technologies, as they may face hefty fines and additional operational costs. Furthermore, the pressure to innovate and adopt sustainable practices can strain resources, diverting funds from other critical areas such as research and development or workforce training. As a result, companies must navigate the delicate balance between regulatory compliance, sustainability initiatives, and maintaining profitability in a competitive market.
Market Segmentation Analysis:
By Type
The steel round bars market can be segmented by type into various categories, including mild steel, high-strength steel, and stainless steel. Mild steel round bars are widely used due to their excellent weldability and cost-effectiveness, making them a preferred choice in construction and general engineering applications. High-strength steel round bars, known for their superior tensile strength and durability, are increasingly favored in industries such as automotive and aerospace, where performance and safety are paramount. Stainless steel round bars are gaining traction due to their corrosion resistance and aesthetic appeal, often utilized in architectural applications, automotive components, and medical equipment. This diverse range of types allows manufacturers to cater to specific industry needs, thereby enhancing their market reach.
By Technology
The market can also be segmented by technology into traditional manufacturing processes and advanced manufacturing techniques. Traditional manufacturing processes include methods such as hot rolling and cold drawing, which have been utilized for decades and are well-established in the industry. However, the shift towards advanced manufacturing techniques, such as electric arc furnace (EAF) technology and automated production lines, is gaining momentum. EAF technology, which allows for the recycling of scrap steel, not only reduces production costs but also aligns with global sustainability goals. Additionally, automation and digitalization in manufacturing processes are improving efficiency, reducing waste, and enhancing product quality. Companies that adopt these advanced technologies are better positioned to meet the evolving demands of the market while adhering to stricter environmental regulations.
By End-User
The steel round bars market can be segmented by end-user into several key sectors, including construction, automotive, manufacturing, and energy. The construction sector remains the largest end-user, driven by ongoing infrastructure projects and urbanization trends worldwide. Steel round bars are essential in reinforcement applications, contributing to the strength and stability of structures. The automotive industry is another significant end-user, as manufacturers increasingly utilize high-strength steel for components that require enhanced performance and safety. In the manufacturing sector, steel round bars are integral in producing machinery, tools, and various equipment. Lastly, the energy sector, particularly in renewable energy projects, is also driving demand for steel round bars, as they are used in the construction of wind turbines and other infrastructure. This diverse range of end-users illustrates the versatility and essential nature of steel round bars across multiple industries.
Segmentations:
Based on Product Type
- Mild Steel Round Bars
- High-Strength Steel Round Bars
- Stainless Steel Round Bars
- Other Specialty Steel Round Bars
Based on Technology:
- Traditional Manufacturing Processes
- Electric Arc Furnace (EAF) Technology
- Automated Production Techniques
- Advanced Digital Manufacturing
Based on End-User:
- Construction
- Automotive
- Manufacturing
- Energy
- Other Industries
Based on Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a significant share of the steel round bars market, accounting for approximately 25% of the global market. The region benefits from a well-established manufacturing sector and robust infrastructure development, which drive the demand for steel round bars. The United States is the largest contributor in this region, with substantial investments in construction and automotive industries. According to the American Iron and Steel Institute (AISI), steel consumption in the U.S. is expected to increase by around 2% annually, reflecting ongoing projects in infrastructure and residential construction. Additionally, the push for sustainability has led many companies to adopt advanced manufacturing technologies, such as electric arc furnaces, further enhancing production efficiency. The presence of major steel producers, such as Nucor and U.S. Steel, ensures a competitive market landscape, facilitating innovation and growth.
Europe
Europe also plays a crucial role in the steel round bars market, capturing approximately 30% of the global market share. The region is characterized by stringent environmental regulations and a strong emphasis on sustainability, which is driving steel manufacturers to adopt cleaner production technologies. Countries like Germany, France, and Italy are leading the charge, investing heavily in advanced manufacturing processes and green technologies. The European Steel Association reports that the region's steel industry is transitioning towards carbon neutrality by 2050, spurring innovation in production methods. The automotive sector in Europe, known for its focus on high-strength steel applications, significantly influences the demand for steel round bars. With major automotive manufacturers like Volkswagen and BMW increasingly incorporating advanced materials, the market is poised for steady growth. Furthermore, the European Union’s Green Deal promotes investments in infrastructure, further enhancing the demand for construction-related steel products.
Asia-Pacific
The Asia-Pacific region is the largest market for steel round bars, accounting for approximately 40% of the global market share. This dominance can be attributed to rapid industrialization, urbanization, and increasing infrastructure investments across countries such as China, India, and Japan. China, as the world’s largest steel producer, significantly impacts the steel round bars market, driven by its vast construction and manufacturing sectors. The Chinese government’s initiatives to enhance infrastructure, such as the Belt and Road Initiative, are expected to sustain high demand for steel products. Similarly, India is witnessing a construction boom, fueled by urbanization and government investments in infrastructure projects, aiming to build smart cities and improve transportation networks. The Indian Steel Association projects a growth rate of 7-8% annually for the steel sector, indicating a strong upward trajectory for steel round bars. Moreover, Japan’s focus on advanced manufacturing and technology-driven solutions in various industries supports the demand for high-strength and specialty steel products, further contributing to the region's market growth.
Key Players:
- ArcelorMittal
- Nucor Corporation
- Tata Steel Limited
- United States Steel Corporation
- Steel Authority of India Limited (SAIL)
- POSCO
- JFE Steel Corporation
- Shagang Group
- China Baowu Steel Group
- Evraz Group
Competitive Analysis:
The competitive landscape of the steel round bars market is characterized by a mix of established players and emerging companies, each vying for market share through strategic investments and innovations. Major players such as ArcelorMittal, Nucor Corporation, and Tata Steel Limited dominate the market, leveraging their extensive production capacities, established supply chains, and strong brand recognition to maintain competitive advantages. These companies invest heavily in technology and sustainability initiatives, adopting advanced manufacturing processes like electric arc furnace technology to improve efficiency and reduce environmental impact. Additionally, they are focusing on product diversification to meet the varying needs of industries, including construction, automotive, and manufacturing. Emerging players are also gaining traction, particularly in the Asia-Pacific region, where rapid industrialization and infrastructure development create opportunities for growth. However, competition is intensified by fluctuating raw material prices and stringent regulatory requirements, pushing companies to innovate continually and optimize their operations. Collaborative efforts, such as strategic alliances and joint ventures, are becoming increasingly common as companies seek to expand their market presence and enhance their technological capabilities. Overall, the steel round bars market is dynamic, with companies needing to adapt to changing market conditions and consumer demands to remain competitive.
Recent Developments:
- In 2022, ArcelorMittal, a Luxembourg-based multinational steel manufacturing corporation headquartered in Luxembourg City, launched a new range of round steel bars distinguished by their exceptional strength. This product line caters to industries such as construction and automotive, which require robust and durable materials.
- Tata Steel introduced a new line of stainless-steel round bars in 2022, specifically designed for applications requiring corrosion resistance, such as the food and beverage industry. Tata Steel Limited, an Indian multinational steel-making company based in Jamshedpur, Jharkhand, and headquartered in Mumbai, Maharashtra, is part of the Tata Group.
- Shri Bhagavati Bright Bars launched a new line of cold-drawn steel round bars in 2022, aimed at applications demanding high precision and surface finish, particularly in the aerospace industry. Established in the 1980s, Shri Bhagavati Bright Bars Ltd (SBBBL) specializes in producing Cold Drawn Bright Bars and hand pump shafts.
- In 2022, Tata Steel Limited partnered with Nippon Steel Corporation, a Japan-based steel producer formed in 2012 through the merger of Nippon Steel and Sumitomo Metal. As of 2019, Nippon Steel ranks as the third-largest steel producer globally by volume. This partnership enables Tata Steel and Nippon Steel to combine their expertise in steel round bar production and marketing.
- Shri Bhagavati Bright Bars also partnered with ThyssenKrupp AG in 2022, a Germany-based steel producer specializing in industrial engineering and steel production. This collaboration will facilitate the development of new steel round bar products.
Market Concentration & Characteristics:
The steel round bars market exhibits a moderate level of market concentration, characterized by a few dominant players alongside numerous smaller companies. Major corporations like ArcelorMittal, Nucor Corporation, and Tata Steel Limited control a significant portion of the market share, leveraging their economies of scale, advanced manufacturing technologies, and extensive distribution networks to maintain competitive advantages. This concentration allows them to influence pricing and drive industry standards, particularly in terms of quality and sustainability practices. Despite the presence of these key players, the market also features a diverse array of smaller manufacturers, particularly in emerging economies, which cater to niche markets and regional demands. These smaller companies often focus on localized production and specialized products, allowing them to compete effectively against larger firms. The market is also characterized by a growing emphasis on sustainability and technological innovation, with many companies investing in eco-friendly production methods and advanced manufacturing techniques to meet regulatory requirements and consumer expectations. As a result, the landscape is continuously evolving, with firms seeking to enhance their competitive positioning through strategic partnerships, technological advancements, and sustainability initiatives. Overall, while a few players dominate the market, the presence of smaller firms and the push for innovation contribute to a dynamic and competitive environment.
Report Coverage:
This report provides a comprehensive analysis of the global steel round bars market, encompassing various dimensions such as market dynamics, segmentation, competitive landscape, and regional insights. It examines key market drivers, including infrastructure development, automotive growth, and rising industrial production, alongside challenges like fluctuating raw material prices and stringent environmental regulations. The segmentation analysis categorizes the market by product type, technology, end-user, and region, offering a nuanced understanding of market trends and consumer preferences. Additionally, the report highlights the competitive landscape, profiling major players such as ArcelorMittal, Nucor Corporation, and Tata Steel Limited, while also considering the impact of emerging companies in the Asia-Pacific region. Regional analysis covers North America, Europe, and Asia-Pacific, detailing specific market shares and growth opportunities within these areas. The report aims to equip stakeholders with actionable insights and strategic recommendations, fostering informed decision-making in an increasingly competitive environment. It serves as a valuable resource for industry participants, investors, and policymakers seeking to navigate the complexities of the steel round bars market and capitalize on emerging trends and opportunities. By synthesizing data from credible sources and providing a forward-looking perspective, this report offers a holistic view of the market landscape, enabling stakeholders to adapt to evolving market conditions and drive sustainable growth.
Future Outlook:
- Continued investment in infrastructure projects will drive sustained demand for steel round bars globally.
- Increased adoption of electric arc furnace technology will enhance sustainability in steel production.
- Emerging economies, particularly in Asia-Pacific, will witness significant growth in construction activities, boosting market potential.
- The automotive sector will increasingly utilize high-strength steel round bars to improve vehicle performance and safety.
- Growing emphasis on renewable energy projects will create new opportunities for steel round bars in energy infrastructure.
- Technological advancements in manufacturing processes will improve efficiency and reduce production costs.
- Regulatory pressures for sustainability will compel manufacturers to invest in eco-friendly practices and innovations.
- Strategic partnerships and collaborations will become more common as companies seek to enhance their market position.
- Rising consumer awareness of sustainable materials will influence purchasing decisions, driving demand for greener options.
- The market will evolve with an increasing focus on product diversification to meet specific industry needs and preferences.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current valuation of the steel round bars market?
What factors are contributing to the growth of the steel round bars market?
What is the projected compound annual growth rate (CAGR) for the steel round bars market?
Which regions are expected to dominate the steel round bars market?
How are manufacturers responding to environmental regulations in the steel round bars market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Steel Round Bars Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Steel Round Bars Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 337.57 million → forecast year: USD 242.90 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Steel Round Bars Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Steel Round Bars Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Steel Round Bars Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Steel Round Bars Market Drivers
- 3.3 Steel Round Bars Market Restraints & Challenges
- 3.4 Steel Round Bars Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Steel Round Bars Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Steel Round Bars Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Steel Round Bars category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Steel Round Bars Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Steel Round Bars Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Steel Round Bars market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Steel Round Bars Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Steel Round Bars Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Steel Round Bars Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Steel Round Bars (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Steel Round Bars Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Steel Round Bars Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Steel Round Bars Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Steel Round Bars Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Steel Round Bars Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Steel Round Bars Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Steel Round Bars Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Steel Round Bars Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Steel Round Bars Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
