
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Tempera Paint Market Size 2024 | USD 675.3 million |
| Tempera Paint Market, CAGR | 5.5% |
| Tempera Paint Market Size 2032 | USD 1,165.3 million |
Market Overview
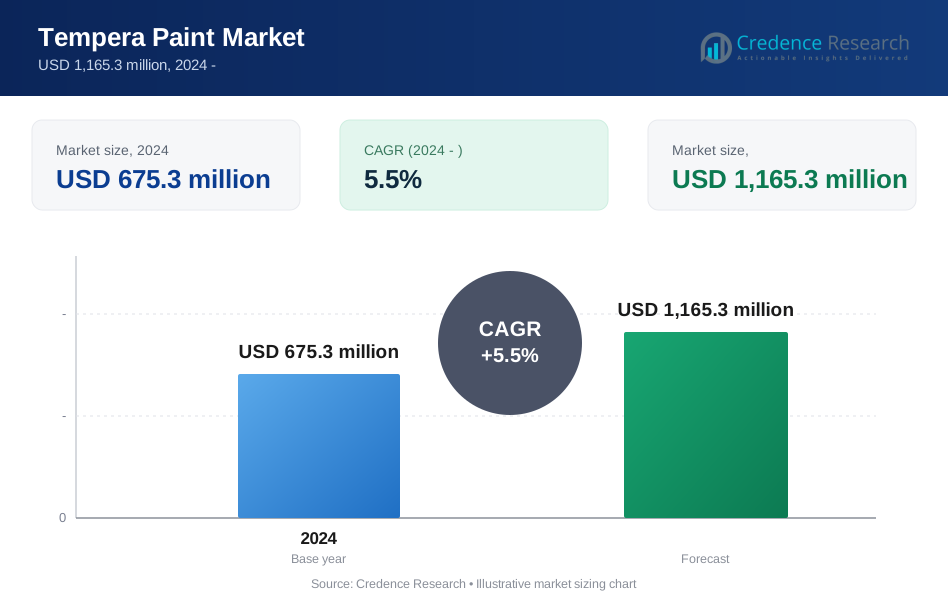
The Tempera Paint Market is experiencing notable growth, driven by increasing demand for artistic supplies and educational materials. As of 2024, the global Tempera Paint Market is valued at approximately USD 675.3 million and is projected to grow at a compound annual growth rate (CAGR) of 5.5% over the forecast period, reaching around USD 1,165.3 million by 2032. This robust growth is indicative of a rising interest in art and craft activities among various demographics, including children, hobbyists, and professional artists.
Several key factors are propelling the market's expansion. The growing popularity of art education in schools and institutions is a significant driver, as tempera paints are favored for their versatility and ease of use in educational settings. Additionally, the increasing trend of DIY projects and home decor is leading to higher consumption of tempera paints among consumers seeking creative outlets. The introduction of innovative product formulations, such as non-toxic and eco-friendly options, is also enhancing market appeal and attracting environmentally conscious buyers.
Regionally, North America holds the largest share of the Tempera Paint Market, primarily due to a well-established art supplies industry and a strong culture of artistic expression. Europe follows closely, supported by similar trends in art education and craft activities. The Asia-Pacific region is anticipated to witness significant growth during the forecast period, driven by rising disposable incomes, increasing participation in creative activities, and growing awareness of the benefits of art for personal development. Emerging economies in this region are expected to offer substantial growth opportunities as urbanization and educational initiatives expand.
Market Drivers:
Growing Demand for Art Education:
The rising emphasis on art education in schools and educational institutions is a significant driver of the Tempera Paint Market. According to a report by the International Monetary Fund (IMF), investments in educational sectors, particularly in arts programs, have seen an upward trend, with countries allocating approximately 6% of their GDP to education by 2025. This growing focus on creativity and artistic skills is leading to increased consumption of art supplies, including tempera paints. For instance, a survey by the National Art Education Association found that 75% of teachers believe that art education fosters creativity and critical thinking in students, further supporting the integration of arts into the curriculum.
Increasing Popularity of DIY and Craft Activities:
The trend toward DIY projects and crafts has gained momentum in recent years, further fueling the demand for tempera paints. The World Bank reports that the DIY market has expanded by 30% since 2020, as individuals seek creative outlets and cost-effective solutions for home decor. Tempera paints, known for their versatility and ease of use, are becoming a preferred choice among hobbyists and crafters. This growth in DIY culture is also reflected in social media trends, where platforms such as Instagram and Pinterest are filled with craft ideas that prominently feature tempera paints. For instance, a study by the Craft and Hobby Association indicated that 65% of consumers engaged in DIY projects during the past year, reinforcing the sustained interest in creative activities.
Emphasis on Eco-Friendly Products:
With increasing awareness about environmental sustainability, there is a growing demand for eco-friendly art supplies, including tempera paints. According to a study by the World Resources Institute, over 70% of consumers are now actively seeking products that are environmentally friendly. Manufacturers are responding to this trend by developing non-toxic and biodegradable formulations of tempera paints, catering to environmentally conscious consumers. For instance, research by the Environmental Protection Agency (EPA) shows that the eco-friendly product segment is projected to grow by 25% from 2023 to 2028, reflecting a significant shift in consumer preferences. Government regulations supporting the use of sustainable materials in consumer products are also contributing to this trend, providing a conducive environment for eco-friendly tempera paint production.
Expansion of Retail Channels:
The expansion of retail channels, including online platforms and brick-and-mortar stores, is enhancing the accessibility of tempera paints to consumers. According to a report by the United Nations Conference on Trade and Development (UNCTAD), e-commerce in the arts and crafts sector has grown by over 40% in the last few years, driven by the increasing preference for online shopping. This trend has allowed consumers to access a wide range of tempera paint options from the comfort of their homes. Moreover, traditional retail outlets are also adapting to changing consumer behaviors by offering exclusive deals and promotions on art supplies, thereby encouraging purchases. For instance, a survey conducted by the National Retail Federation estimates that online sales of art supplies will contribute to approximately 20% of total market growth over the next five years.
Market Trends:
Rise of Digital Art and Online Learning:
The emergence of digital art and online learning platforms is reshaping the landscape of the Tempera Paint Market. As technology advances, more artists and hobbyists are exploring digital mediums, which has created a complementary demand for traditional art supplies like tempera paints. According to a report by the International Monetary Fund (IMF), online art courses have surged in popularity, with a 50% increase in enrollment in virtual art classes since 2020. This trend is encouraging a younger generation to experiment with various artistic techniques, including traditional painting, while enhancing their digital skills. For instance, the National Endowment for the Arts has observed that participation in art-related online courses has increased by 40% among students aged 18 to 24, broadening access to art education and prompting students to engage with physical materials such as tempera paints. Additionally, surveys from the College Art Association indicate that 70% of art educators are incorporating traditional methods alongside digital techniques in their curricula, driving demand for tempera products as individuals transition from digital to physical art practices.
Customization and Personalization in Art Supplies:
Another significant trend in the tempera paint market is the growing consumer preference for customization and personalization in art supplies. As artists seek unique and tailored products, manufacturers are responding by offering customizable options for tempera paints. This trend aligns with broader consumer behavior towards personalized products across various sectors, reflecting a desire for individual expression in artistic endeavors. A study by the World Bank highlights that nearly 60% of consumers are willing to pay a premium for personalized products, including art supplies. This willingness is encouraging companies to explore innovative formulations and packaging that allow for customization, such as personalized color sets or eco-friendly options that align with individual values. For instance, Crayola has launched initiatives allowing customers to create their own crayon colors, which has received positive feedback and is expected to inspire similar offerings in the tempera paint sector. government initiatives supporting local artisans and craftsmen are boosting this trend. Many countries are implementing programs to promote local art and craftsmanship, further enhancing the appeal of personalized art supplies. The U.S. Small Business Administration has reported a 30% increase in funding for small businesses focusing on custom art supplies in the last year, signaling a strong market potential for tempera paint manufacturers to tap into this growing niche.
Market Challenges Analysis:
Competition from Digital Art Solutions:
One of the primary challenges facing the Tempera Paint Market is the increasing competition from digital art solutions. As technology advances, digital painting tools and software have become more accessible and affordable, particularly for younger generations who are often more tech-savvy. The availability of sophisticated digital platforms allows artists to create intricate designs without the need for traditional materials, leading to a decline in the consumption of physical art supplies like tempera paints. According to the National Endowment for the Arts, nearly 50% of artists reported integrating digital tools into their creative processes, reflecting a significant shift in how art is created and consumed. This trend poses a substantial challenge for manufacturers of traditional art supplies, as they must compete not only with other physical products but also with a growing array of digital options that offer convenience and flexibility. To address this challenge, companies need to innovate and find ways to merge traditional and digital art practices, potentially developing hybrid products or marketing strategies that highlight the unique benefits of tempera paints.
Environmental Concerns and Regulatory Compliance:
Another significant challenge for the tempera paint market is the increasing scrutiny surrounding environmental concerns and regulatory compliance. As consumers become more environmentally conscious, there is a rising demand for eco-friendly and non-toxic art supplies. This shift in consumer preference compels manufacturers to adapt their formulations and practices to meet stringent environmental standards. For instance, the Environmental Protection Agency (EPA) has implemented stricter regulations regarding the use of harmful chemicals in consumer products, which includes art supplies. Companies face the challenge of reformulating their products to eliminate hazardous materials, which can be costly and time-consuming. Additionally, businesses must invest in sustainability initiatives, such as eco-friendly packaging and sourcing of materials, to align with consumer expectations. Failure to adapt to these regulatory pressures not only risks potential fines but can also lead to a loss of market share as environmentally conscious consumers turn to competitors that prioritize sustainability. Thus, companies in the tempera paint market must navigate these challenges while ensuring they remain compliant and appealing to an increasingly eco-aware consumer base.
Market Segmentation Analysis:
By Type
The tempera paint market can be segmented based on the type of paint, which includes liquid tempera, dry tempera, and powdered tempera. Liquid tempera is the most popular type, favored for its ease of use and versatility in various artistic applications, including painting, crafting, and educational activities. Dry tempera is often used in classroom settings for convenience, allowing for easier storage and longer shelf life. Powdered tempera, while less common, appeals to artists looking for custom color mixing and specific texture effects. Each type serves distinct purposes and caters to different segments of the market, from educational institutions to professional artists and hobbyists.
By Technology
The segmentation by technology focuses on the manufacturing processes and formulations used in producing tempera paints. This includes traditional formulations, which use standard pigments and binders, and innovative eco-friendly formulations that prioritize non-toxic and biodegradable ingredients. As environmental awareness grows, manufacturers are increasingly developing sustainable options that meet consumer demands for safe and eco-friendly products. This segment is crucial for brands looking to differentiate themselves in a competitive market. Companies that invest in research and development to create advanced, environmentally safe formulations may capture a significant share of the market.
By End-User
The tempera paint market can also be segmented by end-user, which includes educational institutions, professional artists, and hobbyists. Educational institutions represent a major segment, as tempera paints are widely used in schools for art classes and projects. The professional artist segment, while smaller, is crucial for premium product lines that emphasize quality and unique color formulations. Hobbyists constitute a growing segment, driven by the rising interest in DIY projects and home crafting. Each end-user group has specific needs and preferences, influencing purchasing decisions and shaping product development strategies in the tempera paint market. Understanding these segments enables manufacturers to tailor their offerings effectively and address the unique demands of each group.
Segmentations:
Based on Product Type:
- Liquid Tempera
- Dry Tempera
- Powdered Tempera
Based on Technology:
- Traditional Formulations
- Eco-Friendly Formulations
- Specialty Formulations
Based on End-User:
- Educational Institutions
- Professional Artists
- Hobbyists
Based on Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest share of the tempera paint market, accounting for approximately 35% of the total market share. This dominance is primarily driven by the high demand from educational institutions, where tempera paints are widely used in art classes and creative activities. The region's well-established art supplies industry and strong focus on art education further enhance market growth. In the United States, initiatives promoting arts education have led to increased funding for school art programs, resulting in higher consumption of tempera paints. Additionally, the presence of major manufacturers and distributors facilitates easy access to a wide range of products, catering to both educational and professional markets. The growing trend of DIY projects among consumers has also contributed to the market's expansion, as hobbyists increasingly turn to tempera paints for their versatility and ease of use.
Europe
Europe is the second-largest region in the tempera paint market, holding approximately 30% of the market share. The growth in this region is driven by a combination of factors, including a rich artistic heritage and a strong emphasis on creative education. Countries like Germany, France, and the United Kingdom are significant contributors to the market, with robust art programs in schools and a vibrant arts and crafts community. Furthermore, the increasing popularity of eco-friendly and sustainable art supplies aligns with consumer preferences in Europe, leading manufacturers to innovate and develop environmentally safe formulations. Government regulations supporting the use of non-toxic materials in consumer products have also prompted a shift towards eco-friendly tempera paints, catering to the growing demand among environmentally conscious consumers. Collaborative initiatives between educational institutions and art supply manufacturers have further boosted market penetration, enhancing the availability of tempera paints in schools and retail outlets.
Asia-Pacific
The Asia-Pacific region is witnessing rapid growth in the tempera paint market, currently accounting for about 25% of the market share. The expansion of this market segment is largely driven by increasing disposable incomes and a rising interest in art and creative activities among the younger population. Countries such as China, India, and Japan are at the forefront of this growth, with a surge in art education programs and extracurricular activities promoting artistic expression. The growing middle class in these countries is fueling demand for quality art supplies, including tempera paints, as parents seek to provide their children with creative opportunities. Additionally, the rise of online retail platforms has made it easier for consumers to access a variety of tempera products, further driving market growth. Local manufacturers are also emerging, focusing on affordable options to cater to a broader audience, thereby increasing competition and product availability.
Key Players:
- Crayola LLC
- Faber-Castell AG
- Sargent Art
- Reeves (Colart Group)
- Liquitex (Colart Group)
- Sax Arts & Crafts
- Prang (Dixon Ticonderoga Company)
- RASCHER GmbH
- Richeson Art Material
- Jovi S.L.
- Handy Art
- Prang
- Pelikan
Competitive Analysis:
The tempera paint market is characterized by a diverse competitive landscape, featuring both established manufacturers and emerging brands. Key players such as Crayola, Liquitex, and Sargent Art dominate the market, leveraging strong brand recognition and extensive distribution networks to maintain their positions. These companies invest significantly in research and development to innovate product offerings, particularly in eco-friendly formulations that meet growing consumer demand for sustainable art supplies. Additionally, the rise of online retail has intensified competition, enabling smaller brands to enter the market with niche products targeting specific consumer segments, such as hobbyists and educators. Regional players in Asia-Pacific are also making strides by offering affordable options tailored to local preferences, further increasing competition. To gain a competitive edge, companies are focusing on marketing strategies that emphasize product quality, versatility, and safety, particularly in the context of children's art supplies. Partnerships with educational institutions and participation in art fairs and community events are also common strategies to enhance visibility and brand loyalty. Overall, the tempera paint market is dynamic, with companies needing to continually adapt to consumer preferences and trends to thrive amidst increasing competition.
Recent Developments:
- In September 2023, Crayola announced a new licensing agreement with BrightColors, LLC, aimed at expanding its Crayola Experience venues in the U.S. over the next five years. This partnership plans to open a minimum of five new Crayola Experience venues, effectively doubling the brand's presence in the country. BrightColors, an operating subsidiary of Good Vibrations Holding Co., brings extensive experience in the leisure, attraction, and retail industries.
- In October 2023, Crayola announced its first international expansion deal for its family attraction business in collaboration with Max-Matching Entertainment. This strategic move aims to enhance Crayola's global footprint and provide more families with engaging experiences.
- In November 2023, Faber-Castell acquired Robert E. Huber GmbH, a well-known manufacturer of precision mechanical products and components specializing in high-quality writing instruments and accessories. This acquisition represents a strategic effort by Faber-Castell to strengthen its position in the premium writing instruments market and expand its range of high-quality products.
Market Concentration & Characteristics:
The tempera paint market exhibits moderate concentration, with a few major players holding significant market shares while a multitude of smaller brands and niche manufacturers also operate within the space. Leading companies like Crayola, Liquitex, and Sargent Art command substantial portions of the market due to their established reputations, extensive product lines, and widespread distribution networks. However, the market is characterized by a high degree of fragmentation, with numerous smaller companies focusing on specialized products, such as eco-friendly formulations or unique color palettes, catering to specific consumer needs. This diversity allows for a variety of choices for consumers, ranging from high-quality professional-grade paints to budget-friendly options for educational purposes. The competitive landscape is further influenced by increasing consumer awareness regarding sustainability, prompting many manufacturers to invest in environmentally friendly practices and non-toxic ingredients. Additionally, the rise of e-commerce has transformed distribution channels, allowing smaller brands to reach a broader audience and challenge larger players. Overall, the tempera paint market is dynamic, balancing established market leaders with innovative newcomers, creating a rich tapestry of products and brands that cater to diverse consumer preferences and trends.
Report Coverage:
This report provides a comprehensive analysis of the global tempera paint market, encompassing various critical aspects such as market dynamics, trends, segmentation, and competitive landscape. It offers detailed insights into market drivers, challenges, and opportunities, highlighting factors influencing growth across different regions, including North America, Europe, and Asia-Pacific. The report categorizes the market based on product type, technology, and end-user, facilitating a nuanced understanding of consumer preferences and emerging trends. In addition to quantitative data, qualitative insights are included to assess market characteristics and competitive dynamics. Key players in the market are analyzed in terms of their market share, product offerings, and strategic initiatives, providing a clear picture of the competitive landscape. Furthermore, the report examines regulatory impacts and sustainability trends shaping the industry, reflecting the growing consumer demand for eco-friendly art supplies. This in-depth coverage serves as a valuable resource for stakeholders, including manufacturers, distributors, and investors, looking to make informed decisions in the tempera paint market. By offering a holistic view of the market landscape, the report aims to equip readers with the knowledge necessary to navigate the complexities of this evolving industry effectively.
Future Outlook:
- Increasing adoption of eco-friendly formulations will drive product innovation in the tempera paint market.
- Rising interest in art education will enhance demand for tempera paints in schools and educational institutions.
- The growth of online retail platforms will improve accessibility and expand market reach for manufacturers.
- Consumer preferences for personalized art supplies will lead to the development of customizable tempera paint options.
- Collaborative initiatives between manufacturers and educational entities will promote the use of tempera paints in creative programs.
- The popularity of DIY and crafting activities will continue to boost the consumption of tempera paints among hobbyists.
- Investments in marketing strategies highlighting product safety and sustainability will strengthen brand loyalty.
- Emerging economies in Asia-Pacific will present significant growth opportunities due to rising disposable incomes and interest in arts.
- Enhanced distribution networks will facilitate the entry of niche players, fostering a more competitive market landscape.
- Ongoing research into innovative pigment technologies will improve the quality and performance of tempera paints, appealing to professional artists and educators alike.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is driving the growth of the tempera paint market?
What is the projected market value of tempera paints by 2032?
Which regions are leading in the tempera paint market?
What consumer segments are contributing to the demand for tempera paints?
How are eco-friendly formulations impacting the tempera paint market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Tempera Paint Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Tempera Paint Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 675.3 million → forecast year: USD 1,165.3 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Tempera Paint Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Tempera Paint Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Tempera Paint Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Tempera Paint Market Drivers
- 3.3 Tempera Paint Market Restraints & Challenges
- 3.4 Tempera Paint Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Tempera Paint Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Tempera Paint Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Tempera Paint category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Tempera Paint Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Tempera Paint Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Tempera Paint market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Tempera Paint Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Tempera Paint Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Tempera Paint Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Tempera Paint (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Tempera Paint Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Tempera Paint Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Tempera Paint Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Tempera Paint Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Tempera Paint Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Tempera Paint Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Tempera Paint Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Tempera Paint Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Tempera Paint Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
